
 Pediatrics Medicine Market | 2026-2036
Pediatrics Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatrics Medicine Market Analysis
FDA's Pediatric Research Equity Act is consolidating the cost-of-entry calculus for developers seeking pediatric indications, forcing smaller firms toward partnership models. Pfizer sustains one of the industry's broadest pediatric vaccine portfolios across multiple infectious disease categories. GlaxoSmithKline dominates seasonal pediatric immunization contracts with national procurement agencies in Europe and emerging markets. Novartis specializes in oncology pipelines targeting hematologic malignancies in adolescent populations.
Pediatrics medicine encompasses pharmaceutical formulations, biologics, and delivery systems specifically designed for neonatal, infant, child, and adolescent patients, with dosing algorithms adjusted for developmental pharmacokinetics and organ maturation trajectories. These therapeutics address a physiological spectrum where hepatic enzyme expression, renal clearance rates, and blood-brain barrier permeability shift substantially across age brackets, requiring distinct efficacy and safety profiling from adult counterparts. Vaccines command the largest value pool within product type segmentation due to national immunization program procurement scale and recurring birth-cohort demand. The chronic conditions application segment attracts premium pricing for biologics treating juvenile idiopathic arthritis and cystic fibrosis, while preventive care generates volume through public health infrastructure. Oral delivery mode retains dominant share in outpatient settings, though injectable formulations capture hospital-based acute care.
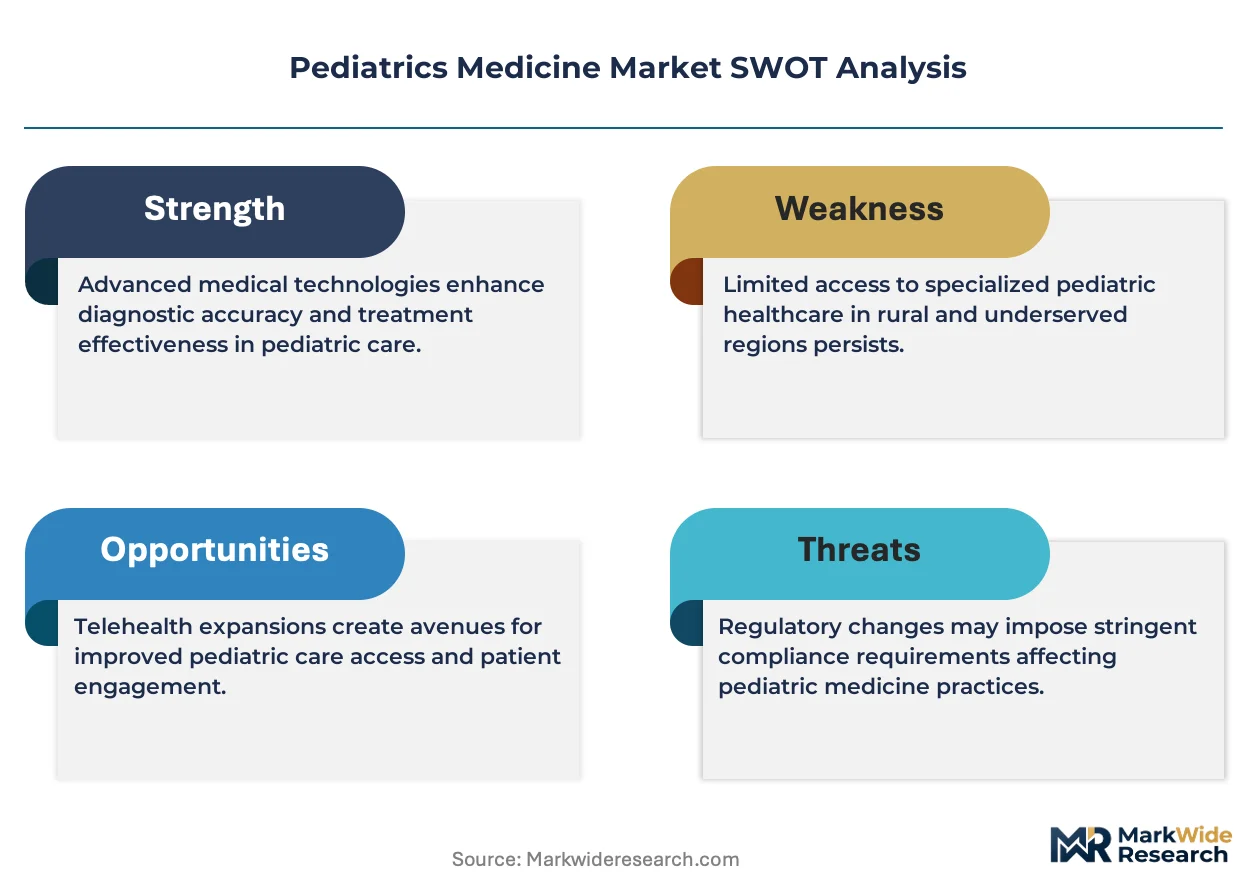
The European Medicines Agency's pediatric investigation plans and FDA's Pediatric Research Equity Act create parallel compliance obligations that extend development timelines but expand market exclusivity incentives for compliant sponsors. Health Canada's pediatric drug submission requirements and Japan's PMDA pediatric action plans add further regulatory layers for multinational portfolio planning. Stakeholders must monitor how real-world evidence frameworks evolve for post-approval pediatric safety commitments, as regulators weigh accelerated pathways against long-term developmental risk profiles.
Market Dynamics
The FDA's Pediatric Research Equity Act and EMA's pediatric investigation plans are compressing development timelines while expanding compliance costs, forcing developers toward specialized contract research organizations with neonatal pharmacology expertise.
Growth Catalysts
- Orphan drug exclusivity incentives:The FDA awards seven-year market exclusivity for pediatric rare disease indications, attracting venture capital into juvenile idiopathic arthritis and cystic fibrosis pipelines.
- Neonatal intensive care unit expansion:Children's hospital networks in Texas, California, and Ohio are adding level IV NICU capacity, creating concentrated demand for intravenous immunoglobulin and surfactant therapies.
- Real-world evidence frameworks:Health Canada and Japan's PMDA are accepting registry data for post-approval safety commitments, accelerating label expansions for adolescent oncology indications.
Market Restraints
- Active pharmaceutical ingredient concentration:Ninety percent of pediatric antibiotic precursors originate from Zhejiang and Shandong provinces, exposing formulators to supply disruption risk.
- Ethical enrollment barriers:Institutional review boards impose stricter assent requirements for neonatal trials than adult equivalents, extending recruitment phases by twelve to eighteen months.
- Formulation complexity premiums:Palatable liquid and dispersible tablet development requires taste-masking technologies that add thirty to fifty percent to manufacturing costs versus standard oral solids.
Strategic Opportunities
- Adolescent mental health therapeutics:The FDA's breakthrough therapy designation pathway for pediatric depression and anxiety indications offers expedited review timelines for sponsors with biomarker-stratified trials.
- Home infusion service integration:Hospital-at-home programs in Pennsylvania and Massachusetts are creating demand for portable infusion pumps with pediatric-specific dosing algorithms.
- Biosimilar penetration in growth hormone:Patent cliffs for reference biologics are opening substitution opportunities in Medicaid and national health service formularies across Germany and the United Kingdom.
Industry Challenges
- Pediatric pharmacokinetic modeling expertise:The scarcity of clinical pharmacologists trained in physiologically-based pharmacokinetic modeling for developmental organ maturation is constraining trial design capacity.
- Multi-regulatory dossier harmonization:Divergent age-group definitions between FDA pediatric subcategories and EMA's pediatric investigation plan age brackets force redundant clinical program designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatrics Medicine Market |
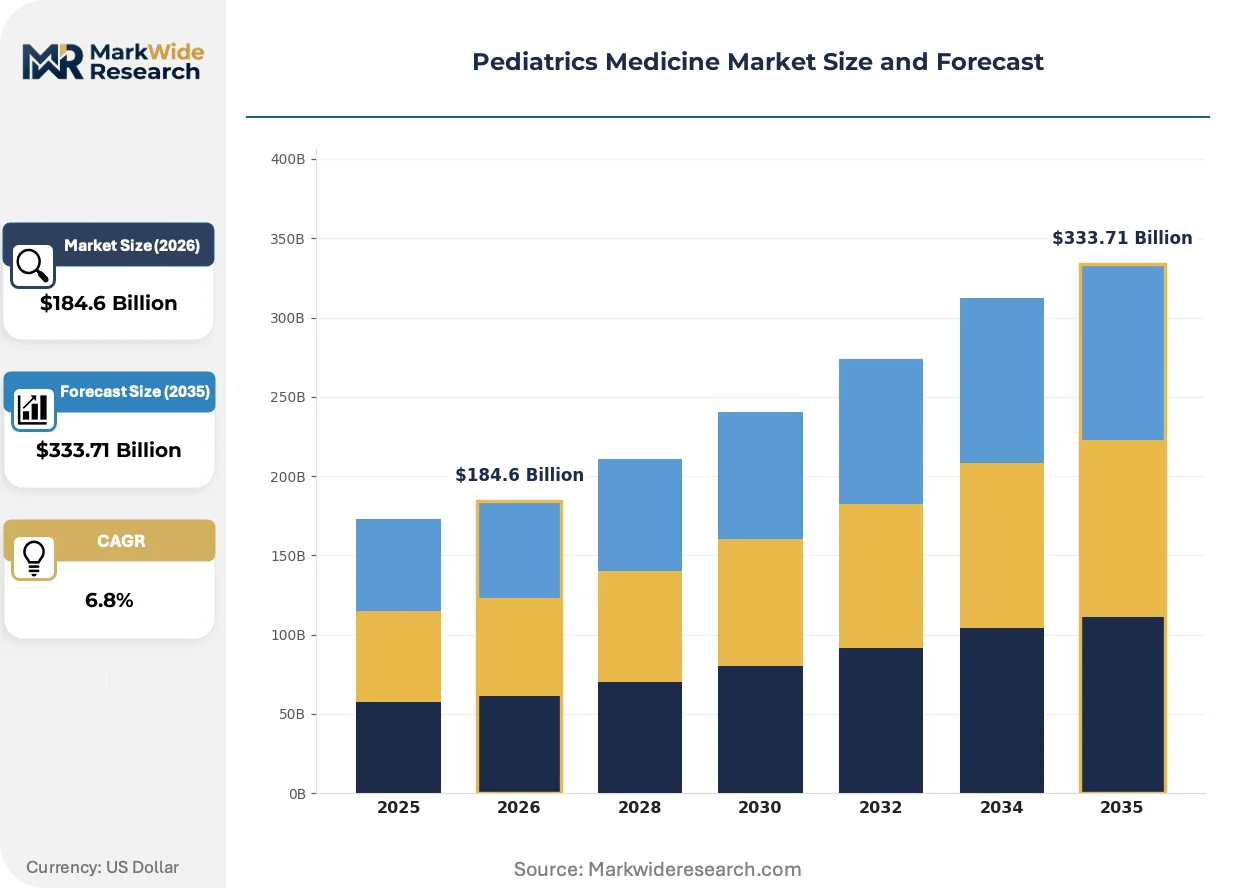
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Vaccines, Devices, Diagnostic Tools Application: Chronic Conditions, Acute Illnesses, Preventive Care, Nutritional Support End User: Pediatric Clinics, Hospitals, Home Care, Research Institutions Delivery Mode: Oral, Injectable, Inhalation, Transdermal |
| Companies Covered | Pfizer, GlaxoSmithKline, Johnson & Johnson, Sanofi, Abbott Laboratories, Novartis, Merck & Co., Bayer, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatrics Medicine Market Emerging Trajectories
Developmental pharmacology modeling is compressing traditional dose-finding paradigms, while regulatory convergence around real-world evidence is reshaping post-market surveillance obligations for pediatric sponsors.
Microphysiological systems incorporating pediatric liver and kidney organoids are electrifying preclinical toxicity screening, enabling age-specific metabolic pathway validation before human dosing. Large pharmaceutical sponsors and specialized biotechs are adopting these platforms at pilot scale for immunology and infectious disease programs. This technology is electrifying the replacement of adult-derived safety assumptions with developmental-stage-specific data, reducing Phase I exposure risk in neonatal populations.
EMA's revised guideline on clinical investigation of medicinal products in the pediatric population is mandating pediatric study plan submissions earlier in development, compressing adult-first trial sequences. Sponsors must now justify waiver requests with disease prevalence data stratified by age bracket. Oncology and hematology programs face the steepest compliance burden, with adolescent inclusion requirements now triggering parallel enrollment in adult solid tumor trials.
Specialized pharmacy benefit managers are consolidating procurement for rare disease biologics, replacing hospital-based purchasing with centralized distribution and patient hub services. This channel concentration is most visible in hemophilia and enzyme replacement therapies, where manufacturers now contract directly with CVS Specialty and Accredo for home delivery logistics. Germany's statutory health insurance funds are piloting similar consolidated tendering for growth hormone and immunoglobulin products.
Pediatrics Medicine Market Segmentation
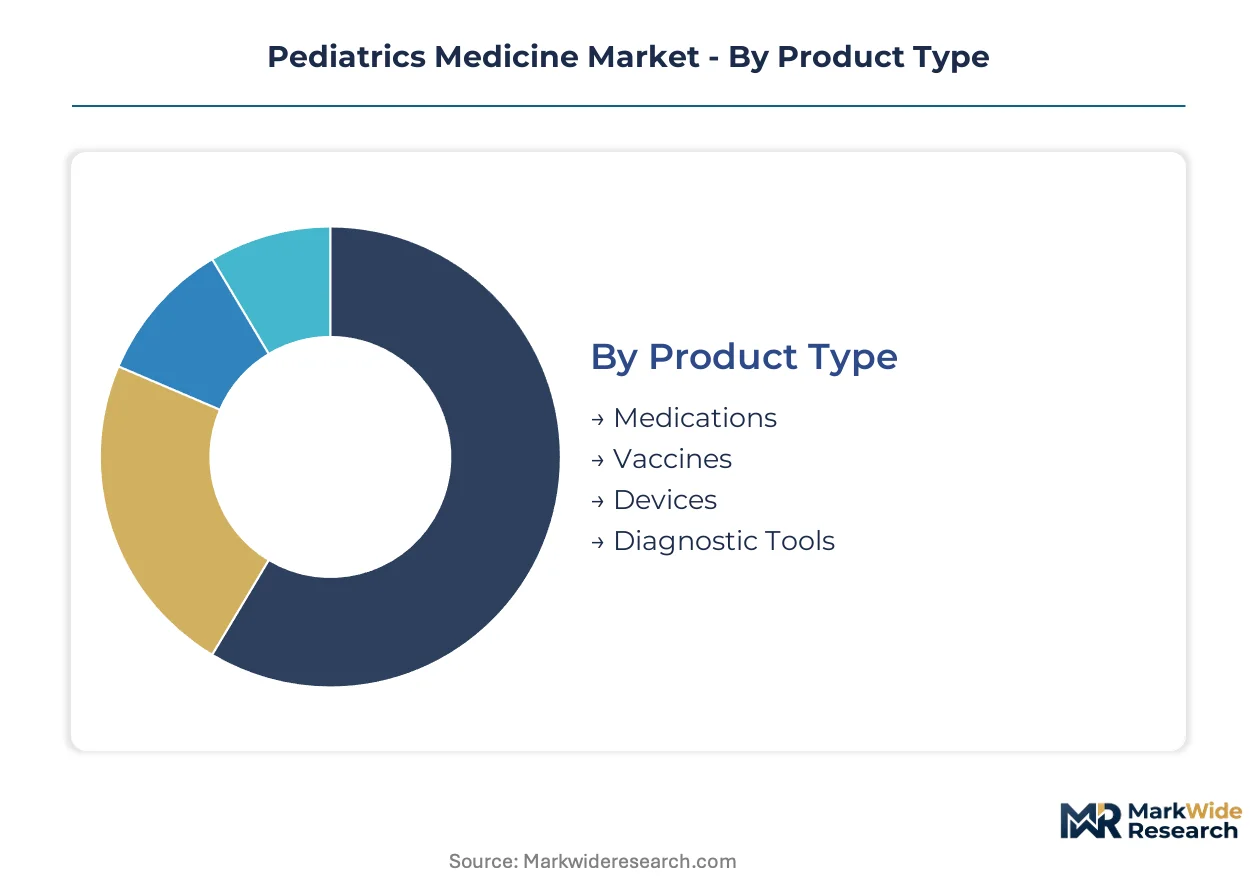
Pediatric therapeutics demand precise segmentation due to developmental pharmacokinetic variability across neonatal, infant, and adolescent populations. Each category reflects distinct regulatory pathways, reimbursement structures, and formulation requirements that shape commercial strategy.
Product Type:
Vaccines require WHO prequalification or national regulatory approval for immunization program inclusion, while medications face FDA Pediatric Research Equity Act and EMA pediatric investigation plan mandates. Devices and diagnostic tools trigger separate conformity assessment routes under MDR and FDA device regulations.
- Vaccines:Multivalent formulations targeting infectious diseases command procurement scale through national immunization schedules. Demand concentrates in Gavi-eligible countries and Medicaid-funded US birth cohorts, driven by WHO Expanded Programme on Immunization procurement cycles and federal Vaccines for Children program mandates.
- Medications:Small-molecule and biologic formulations adjusted for weight-based dosing and organ maturation trajectories. Oncology and rare disease pipelines attract orphan drug exclusivity incentives in the United States, where pediatric subpopulations trigger seven-year market exclusivity extensions.
- Devices:Neonatal respiratory support, infusion pumps with pediatric dosing algorithms, and portable monitoring equipment. FDA breakthrough device designation accelerates review for technologies addressing unmet needs in congenital heart disease and prematurity complications.
- Diagnostic Tools:Age-appropriate imaging protocols, biomarker assays, and genetic screening platforms. Adoption accelerates in children's hospital networks with embedded precision medicine programs.
Leading the category by volume: Vaccines. Growing fastest: Medications targeting rare pediatric indications.
Application:
Cost tier stratification separates chronic condition biologics with premium pricing from high-volume preventive interventions funded through public health infrastructure.
- Chronic Conditions:Juvenile idiopathic arthritis, cystic fibrosis, and hemophilia therapeutics require lifelong administration with dose escalation protocols. Medicaid and national health service formularies in Germany and the United Kingdom negotiate outcomes-based contracts for enzyme replacement therapies.
- Acute Illnesses:Antibiotics, antivirals, and supportive care for respiratory and gastrointestinal infections. Hospital-based procurement dominates, with concentrated demand in level IV NICU expansions across Texas, California, and Ohio.
- Preventive Care:Immunization and prophylactic interventions delivered through school-based programs and pediatric well visits. Volume scales with birth cohort replacement and catch-up campaign cycles.
- Nutritional Support:Specialized formulas and parenteral nutrition for metabolic disorders and prematurity. Home infusion service integration in Pennsylvania and Massachusetts creates channel shift opportunities.
Highest margin concentration: Chronic Conditions. Steepest expansion trajectory: Nutritional Support via home care channels.
End User:
Customer type determines procurement authority, with hospitals retaining formulary control for acute therapies while home care shifts purchasing to specialty pharmacy benefit managers.
- Pediatric Clinics:Outpatient settings managing routine immunization, developmental screening, and stable chronic disease monitoring. Volume correlates with Medicaid managed care network density.
- Hospitals:Tertiary children's hospitals and NICUs concentrate demand for intravenous immunoglobulin, surfactant therapies, and oncology biologics. Federal 340B drug pricing program eligibility shapes purchasing economics.
- Home Care:Hospital-at-home programs and family-administered therapies for hemophilia, growth hormone deficiency, and enzyme replacement. CVS Specialty and Accredo consolidate distribution logistics.
- Research Institutions:Academic medical centers conducting investigator-initiated trials and real-world evidence generation for post-approval safety commitments.
Dominant procurement authority: Hospitals. Fastest channel shift: Home Care.
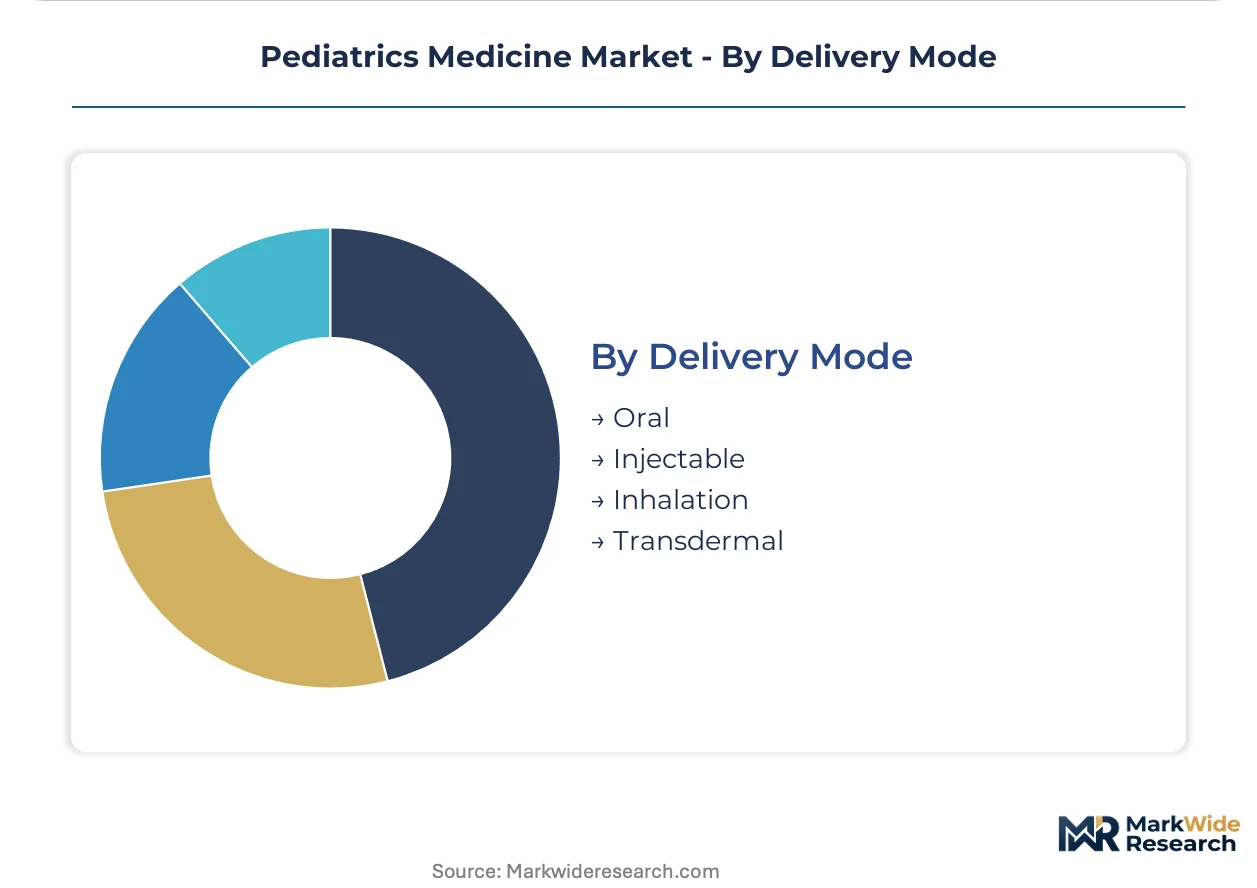
Delivery Mode:
Supply concentration in active pharmaceutical ingredients shapes formulation availability, with Zhejiang and Shandong provinces originating ninety percent of pediatric antibiotic precursors.
- Oral:Liquid suspensions, dispersible tablets, and taste-masked formulations dominate outpatient compliance. Palatability engineering adds manufacturing cost premiums versus standard oral solids.
- Injectable:Intravenous and subcutaneous routes for hospital-based acute care and biologic administration. Prefilled syringes with needle safety features reduce medication errors in pediatric populations.
- Inhalation:Metered-dose and dry powder devices adapted for age-appropriate coordination. Spacer chamber requirements complicate home administration for asthma management.
- Transdermal:Patches and topical formulations for pain management and hormone delivery. Limited by skin permeability variation across developmental stages.
Widest utilization: Oral. Gaining share fastest: Injectable biologics via home infusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pediatric therapeutics concentrates in markets with specialized children's hospital networks and strong orphan drug incentive frameworks. Regulatory mandates from the FDA and EMA reshape investment flows across developed economies. Procurement patterns diverge between public immunization programs and premium-priced rare disease biologics.
United States
Texas, California, and Ohio children's hospitals are expanding level IV NICU capacity, driving concentrated demand for intravenous immunoglobulin and surfactant therapies. The FDA's Pediatric Research Equity Act mandates pediatric study plans for new molecular entities, extending development timelines but expanding market exclusivity incentives. The 340B drug pricing program eligibility shapes purchasing economics across tertiary pediatric centers.
Germany
Statutory health insurance funds are piloting consolidated tendering for growth hormone and immunoglobulin products, shifting procurement toward centralized distribution. The country's national pharmaceutical regulator enforces pediatric investigation plan compliance for EMA marketing authorization applications. Bavaria and North Rhine-Westphalia host the densest clusters of pediatric specialty clinics and academic medical centers conducting real-world evidence generation.
United Kingdom
National Health Service formularies negotiate outcomes-based contracts for enzyme replacement therapies in cystic fibrosis and hemophilia. The MHRA pediatric investigation plan requirements align with EMA frameworks post-Brexit transitional arrangements. London and the Southeast concentrate demand through embedded precision medicine programs at major children's hospital networks.
Japan
PMDA pediatric action plans add regulatory layers for multinational sponsors seeking market access. The country's national health insurance system reimburses premium-priced biologics for juvenile idiopathic arthritis under specific cost-effectiveness thresholds. Kanto and Kansai regions anchor demand through university-affiliated children's hospitals with investigator-initiated trial capacity.
India
CDSCO pediatric drug submission requirements are tightening for multinational portfolio planning, though enforcement capacity varies across states. Maharashtra and Gujarat concentrate manufacturing of active pharmaceutical ingredients for pediatric antibiotic formulations. Gavi-eligible procurement cycles drive vaccine volume through national immunization program expansion.
Pediatrics Medicine Market Vendor Landscape
United States-based pharmaceutical conglomerates anchor one tier of vaccine and rare disease biologics development; European specialists hold positions in seasonal immunization contracts and adolescent oncology pipelines. The vendor base separates into three archetypes: diversified multinationals with broad pediatric portfolios, regional immunization-focused suppliers, and rare disease biotechs pursuing orphan exclusivity. Competitive moves center on strategic partnerships for pediatric pharmacokinetic expertise and portfolio diversification into adolescent mental health indications.
Within the diversified multinational tier, Pfizer and GlaxoSmithKline represent archetypal positions across infectious disease and immunization categories. Novartis occupies a position exemplifying oncology pipeline specialization for hematologic malignancies in adolescent populations. These three anchors demonstrate how geographic origin and portfolio breadth stratify competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Pfizer |
| GlaxoSmithKline |
| Johnson & Johnson |
| Sanofi |
| Abbott Laboratories |
| Novartis |
| Merck & Co. |
| Bayer |
| F. Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
EMA's pediatric investigation plan mandates gate qualified supply access for sponsors seeking premium-tier orphan drug pricing in European markets. Manufacturers without compliant clinical programs face exclusion from statutory health insurance reimbursement at premium rates.
Pricing Analysis
Short lead-time contracts for intravenous immunoglobulin and surfactant therapies command premium pricing from children's hospital networks expanding level IV NICU capacity. Three-tier pricing structure across originator biologics, authorized generics, and biosimilars reflects FDA orphan exclusivity status and manufacturing complexity. Cost compression in antibiotic formulations intensifies because concentrated active pharmaceutical ingredient sourcing from Zhejiang and Shandong provinces limits negotiating leverage. Medicaid managed care networks exhibit highest price sensitivity; rare disease patient hubs show lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Regional distribution centers in Pennsylvania and Massachusetts anchor hospital-at-home program logistics for portable infusion pumps with pediatric dosing algorithms. Active pharmaceutical ingredient production concentrates in India and China, with Maharashtra and Gujarat hosting pediatric antibiotic precursor manufacturing. Formulation development rests on taste-masking technologies, excipient sourcing, and sterile fill-finish capacity. Single-source vulnerability in neonatal pharmacology expertise constrains contract research organization selection. Distribution runs through CVS Specialty and Accredo for rare disease biologics, replacing hospital-based purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric pharmacokinetic modeling expertise scarcity props pricing for qualified contract research organization partnerships. Capacity bottlenecks in neonatal trial design constrain sponsor pipeline velocity.
For Market Incumbents: Hedge against biosimilar substitution in growth hormone by deepening prescriber relationships through patient hub services. Secure backward integration into active pharmaceutical ingredient sourcing for antibiotic portfolios to mitigate Zhejiang and Shandong supply disruption exposure. FDA Pediatric Research Equity Act compliance investments create exclusivity extension opportunities that emerging entrants cannot replicate.
For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting adolescent mental health therapeutics in Pennsylvania and Massachusetts hospital-at-home corridors. White-space concentration in portable infusion pump pediatric dosing algorithms offers lowest competitive density. Real-world evidence generation partnerships with academic medical centers provide differentiated regulatory submission pathways.
For Investors and Strategic Acquirers: Consolidated tendering announcements by Germany's statutory health insurance funds are the leading indicator that biosimilar penetration in immunoglobulin and growth hormone is accelerating. Five-to-ten-year viability favors rare disease biotechs with FDA breakthrough therapy designations and adolescent oncology pipelines. Watch for pediatric investigation plan waiver justifications with disease prevalence stratification as inflection signal for regulatory strategy shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Submission | EMA compliance secures marketing authorization access across Bavaria and North Rhine-Westphalia clusters. |
| Real-World Evidence Partnership | Health Canada registry data acceptance accelerates label expansion for adolescent oncology indications. |
| Patient Hub Service Integration | CVS Specialty and Accredo consolidation captures hemophilia and enzyme replacement therapy distribution. |
| Neonatal Pharmacology CRO Alliance | Specialized contract research organization access compresses trial design timelines for developmental pharmacokinetic modeling. |
| Biosimilar Portfolio Entry | Patent cliff exploitation in Medicaid and NHS formularies opens substitution opportunities in Germany and United Kingdom. |
Methodological Framework
Document review covered FDA Pediatric Research Equity Act filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov records, and hospital procurement databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare data, GPO contracts, and WHO prequalification records. Bottom-up demand modeling triangulated against top-down market sizing across the projection horizon.
Cross-reference between historical immunization program procurement cycles and expert panel input shaped the analytical framework. Segmentation dimensions included product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from growth rate reconciliation across independent modeling approaches. Forecast inputs incorporated neonatal intensive care unit expansion trajectories and orphan drug exclusivity incentive utilization rates.
Regulatory guideline revisions, supply disruption events, and reimbursement policy shifts are the dominant revision risks for pediatric medicine demand projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Growth Hormone Deficiency Market