
 Middle East and Africa Pediatric Healthcare Market | 2026-2036
Middle East and Africa Pediatric Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pediatric Healthcare Market Foresight
A shortage of specialized pediatric nurses and neonatal intensivists is redrawing competitive dynamics across the Middle East and Africa. General Electric Company leverages its installed imaging base to secure long-term service contracts in Saudi tertiary hospitals. Koninklijke Philips N.V. anchors its position through localized production of patient monitoring systems for African markets. Medtronic competes on cardiac device portfolios tailored to congenital conditions prevalent in the region.
Pediatric healthcare encompasses preventive, diagnostic, therapeutic, and surgical interventions specifically formulated for patients from birth through adolescence, requiring weight-calibrated dosing, miniaturized instrumentation, and developmental-stage-appropriate delivery mechanisms. Vaccines command the largest product type share due to national immunization program scale-up across Gulf Cooperation Council states. Diagnostic devices represent the fastest-expanding segment as point-of-care ultrasound and portable respiratory analyzers penetrate pediatric clinics in Nigeria and Kenya. Hospitals absorb the dominant end-user share, though home care delivery is gaining traction for chronic pediatric conditions requiring long-term therapeutic management.
South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and Egypt's Drug Authority collectively shape market access through divergent device registration and pharmaceutical import licensing requirements. The EU Medical Device Regulation's extraterritorial influence on CE-marked products creates compliance complexity for manufacturers serving multiple African markets. Stakeholders must monitor regulatory harmonization initiatives under the African Medicines Regulatory Harmonization programme and calibrate market entry sequencing to priority countries with streamlined approval pathways.
Market Dynamics
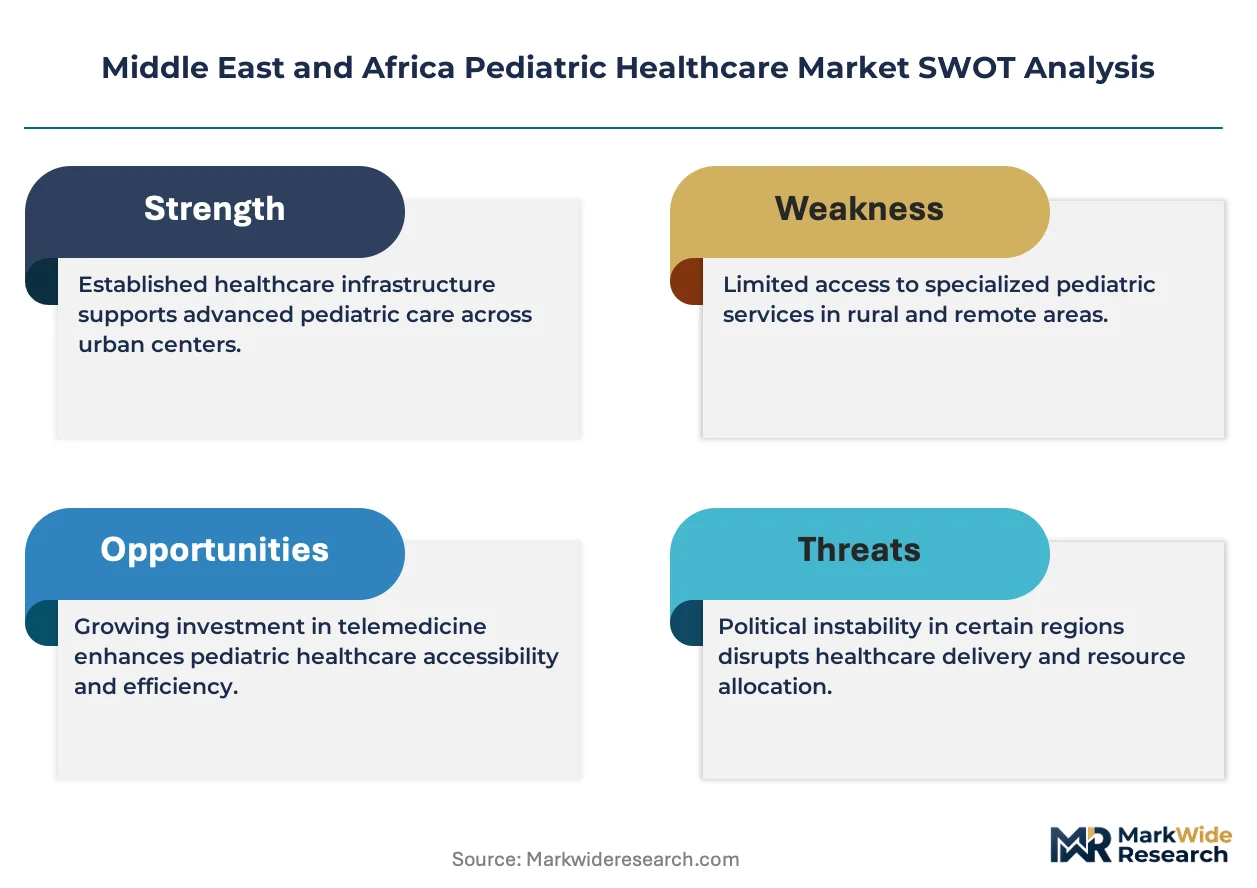
Government healthcare privatization across Gulf Cooperation Council states is redirecting capital toward pediatric infrastructure buildout, while regulatory divergence between South Africa's Health Products Regulatory Authority and Saudi Food and Drug Authority fragments market entry pathways for device manufacturers.
Growth Catalysts
- National immunization program scale-up:Gulf Cooperation Council states are expanding vaccine procurement through centralized tender mechanisms, creating predictable demand volumes for pediatric biologics suppliers.
- Point-of-care diagnostic penetration:Portable ultrasound and respiratory analyzers are reaching pediatric clinics in Nigeria and Kenya, extending diagnostic access beyond tertiary hospital networks.
- Neonatal monitoring procurement:Hospital-based pediatric departments are systematically upgrading intensive care instrumentation, with tertiary facilities in Saudi Arabia and UAE leading capital deployment.
Market Restraints
- Specialized workforce scarcity:Shortages of pediatric nurses and neonatal intensivists constrain service expansion across Saudi Arabia, Egypt, and South Africa, limiting bed capacity utilization regardless of equipment availability.
- Divergent registration timelines:South Africa's Health Products Regulatory Authority tightened medical device approval windows, while Egypt's Drug Authority maintains extended review cycles, creating asymmetric market access costs.
- Import dependency for precision instrumentation:Miniaturized surgical tools and calibrated dosing systems concentrate manufacturing in European and North American supply bases, exposing procurement to currency volatility and shipping friction.
Strategic Opportunities
- Home care delivery expansion:Chronic pediatric conditions requiring long-term therapeutic management are shifting toward domestic settings in UAE and Qatar, opening device categories for remote monitoring and patient-administered therapy.
- African Medicines Regulatory Harmonization:The AMRH programme's convergence protocols promise streamlined multi-country registration, rewarding early alignment with centralized approval pathways.
- Congenital cardiac specialization:Device portfolios calibrated to region-prevalent heart conditions present white space as interventional pediatric cardiology capacity builds in Saudi tertiary centers.
Industry Challenges
- EU Medical Device Regulation extraterritorial compliance:CE-marked products face dual certification burdens when serving African markets with legacy regulatory frameworks, extending time-to-revenue for manufacturers.
- Developmental-stage calibration complexity:Weight-band dosing and age-appropriate delivery mechanisms multiply SKU requirements, complicating inventory management and localization strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pediatric Healthcare Market |
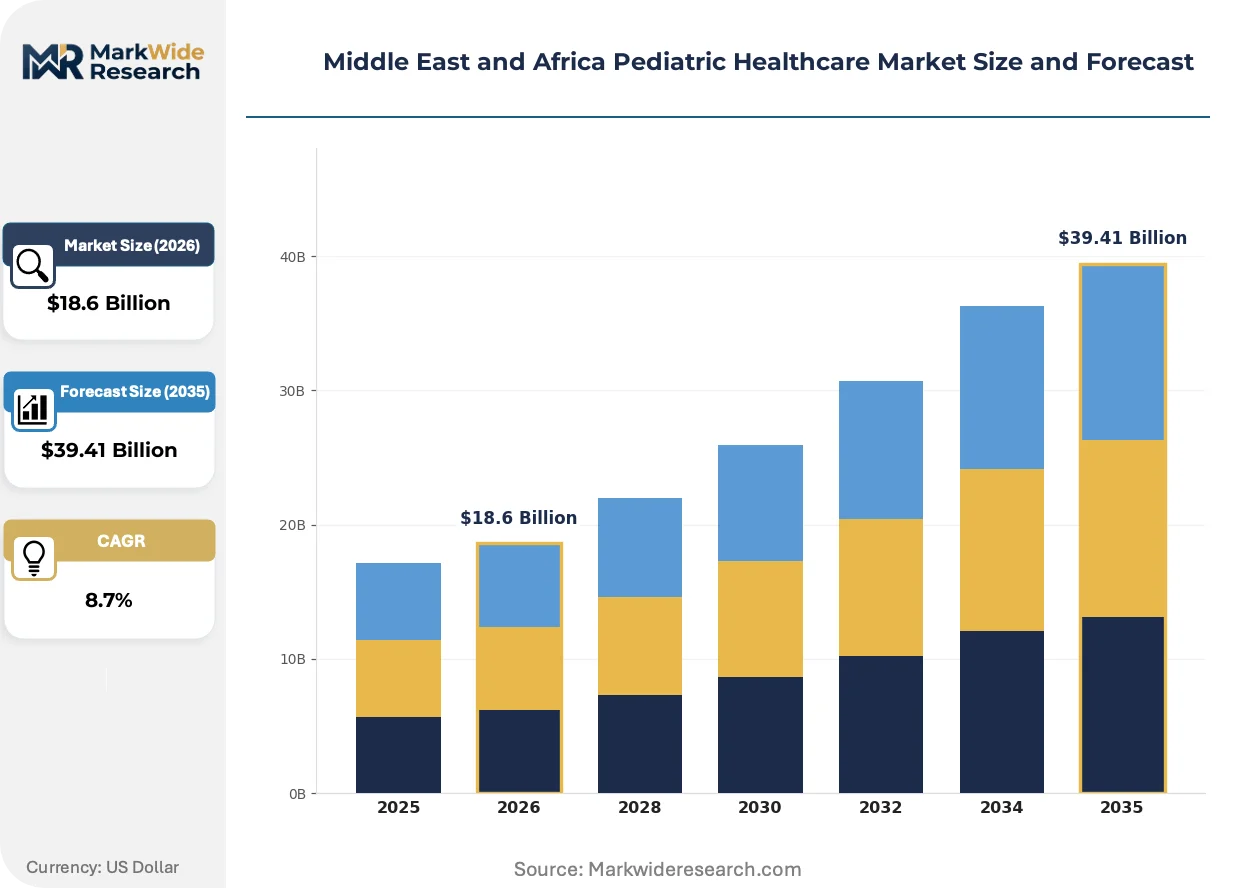
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostic Devices, Surgical Instruments, Therapeutics End User: Pediatrics Clinics, Hospitals, Home Care, Pharmacies Delivery Mode: Intravenous, Oral, Topical, Inhalation Therapy Area: Immunology, Cardiology, Oncology, Neurology |
| Companies Covered | General Electric Company, Koninklijke Philips N.V., Medtronic, Siemens AG, Atom Medical Corp., Pfizer, Johnson & Johnson, Abbott, Sanofi, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pediatric Healthcare Market Shifts & Advancements
Digital health infrastructure and portable diagnostic platforms are redrawing care delivery geography across Middle East and Africa pediatric markets, compressing the distance between tertiary capability and primary access points.
Point-of-care ultrasound is bifurcating diagnostic workflows in pediatric clinics. Miniaturized transducers with AI-assisted image interpretation enable non-specialist clinicians to perform cardiac and abdominal screening. Nigerian and Kenyan primary care networks are adopting these systems faster than projected replacement cycles for legacy radiology equipment. The technology is bifurcating referral patterns—complex cases still route to tertiary centers, while routine assessments remain local, redistributing revenue across the care continuum.
Saudi Food and Drug Authority's accelerated device registration pathways for pediatric-critical instrumentation compress approval timelines against South African benchmarks. Manufacturers now prioritize Saudi dossier preparation to capture privatization-driven procurement windows. Pediatric monitoring systems and neonatal respiratory support devices face the steepest compliance gradient, with applicants investing in localized clinical evidence generation to satisfy authority requirements.
Hospital procurement departments are unbundling service contracts from capital equipment purchases. Saudi tertiary facilities now negotiate multi-year maintenance agreements separately from initial device acquisition, treating technical support as a distinct spend category. This pattern concentrates in imaging and monitoring modalities where uptime guarantees determine clinical throughput. Vendors respond with dedicated service subsidiaries and spare parts localization to defend renewal rates.
Middle East and Africa Pediatric Healthcare Market Segmentation
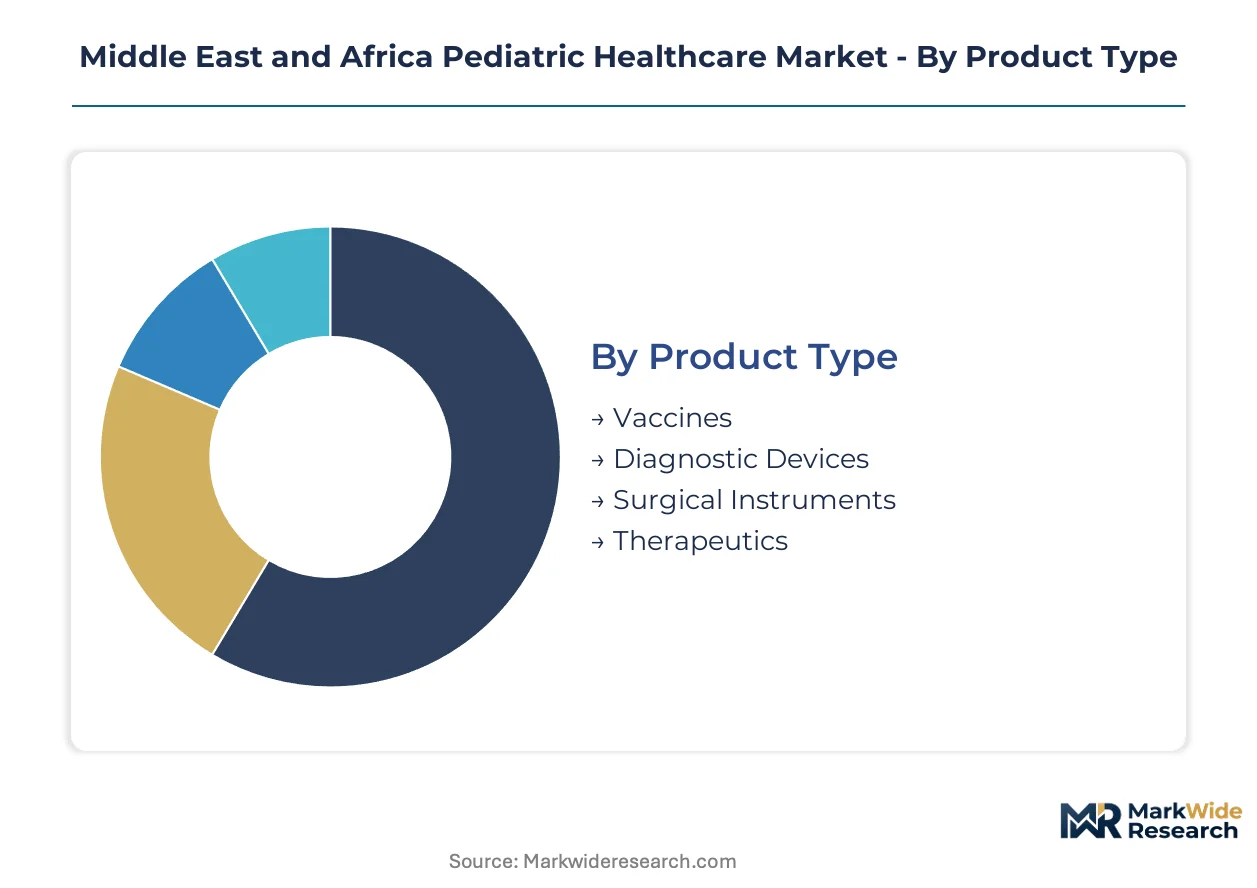
Pediatric healthcare segmentation in the Middle East and Africa reflects divergent procurement capabilities between Gulf Cooperation Council states with privatized infrastructure and African markets dependent on donor-funded programs. Understanding these fault lines shapes portfolio prioritization and regulatory sequencing for device and pharmaceutical suppliers.
Product Type:
Vaccines concentrate demand in centralized Gulf procurement while diagnostic devices penetrate African primary care networks through portable platforms.
- Vaccines:Biologic formulations targeting birth-through-adolescence immunization schedules, calibrated to regional disease burden profiles. Gulf Cooperation Council states deploy centralized tender mechanisms for national program scale-up, creating volume predictability for suppliers navigating Saudi Food and Drug Authority registration pathways.
- Diagnostic Devices:Miniaturized imaging, respiratory analyzers, and point-of-care testing platforms sized for pediatric anatomy. Nigerian and Kenyan clinics adopt portable ultrasound faster than projected replacement cycles for legacy radiology equipment, redistributing diagnostic access beyond tertiary hospital networks.
- Surgical Instruments:Weight-calibrated tools and miniaturized instrumentation for pediatric procedures.
- Therapeutics:Age-appropriate dosing formulations spanning chronic and acute interventions.
Vaccines commands the established base. The steepest expansion runs through Diagnostic Devices.
End User:
Hospital procurement dominates capital deployment while home care delivery emerges as a service model in high-income Gulf markets.
- Hospitals:Tertiary pediatric departments and neonatal intensive care units with systematic equipment upgrade cycles. Saudi Arabia and UAE facilities lead capital deployment for neonatal monitoring systems, unbundling multi-year service contracts from initial device acquisition to secure uptime guarantees.
- Home Care:Domestic therapeutic management for chronic pediatric conditions requiring long-term monitoring. UAE and Qatar witness traction for remote patient monitoring and patient-administered therapy as healthcare privatization redirects service innovation toward convenience-oriented delivery.
- Pediatrics Clinics:Outpatient facilities with growing diagnostic capability through portable platforms.
- Pharmacies:Retail distribution nodes for vaccines and oral therapeutics in community settings.
Hospitals absorb the dominant procurement share. Home Care gains share fastest among alternative channels.
Delivery Mode:
Route selection reflects developmental-stage physiology constraints and regional caregiver compliance patterns across diverse healthcare literacy levels.
- Intravenous:Direct vascular administration for critical care and hospitalized pediatric patients. Tertiary facilities in Saudi Arabia and South Africa concentrate demand for precision infusion systems with weight-calibrated dosing safeguards.
- Oral:Palatable formulations and age-appropriate dosing vehicles for outpatient therapeutic management. Pharmacies across Egypt and Nigeria serve as primary distribution points, though caregiver adherence varies with healthcare literacy and supply consistency.
- Topical:Transdermal applications for dermatologic and localized therapeutic delivery.
- Inhalation:Respiratory drug delivery through nebulized and aerosolized platforms.
Oral formulations command the accessible base. Intravenous systems climb the fastest in value concentration.
Therapy Area:
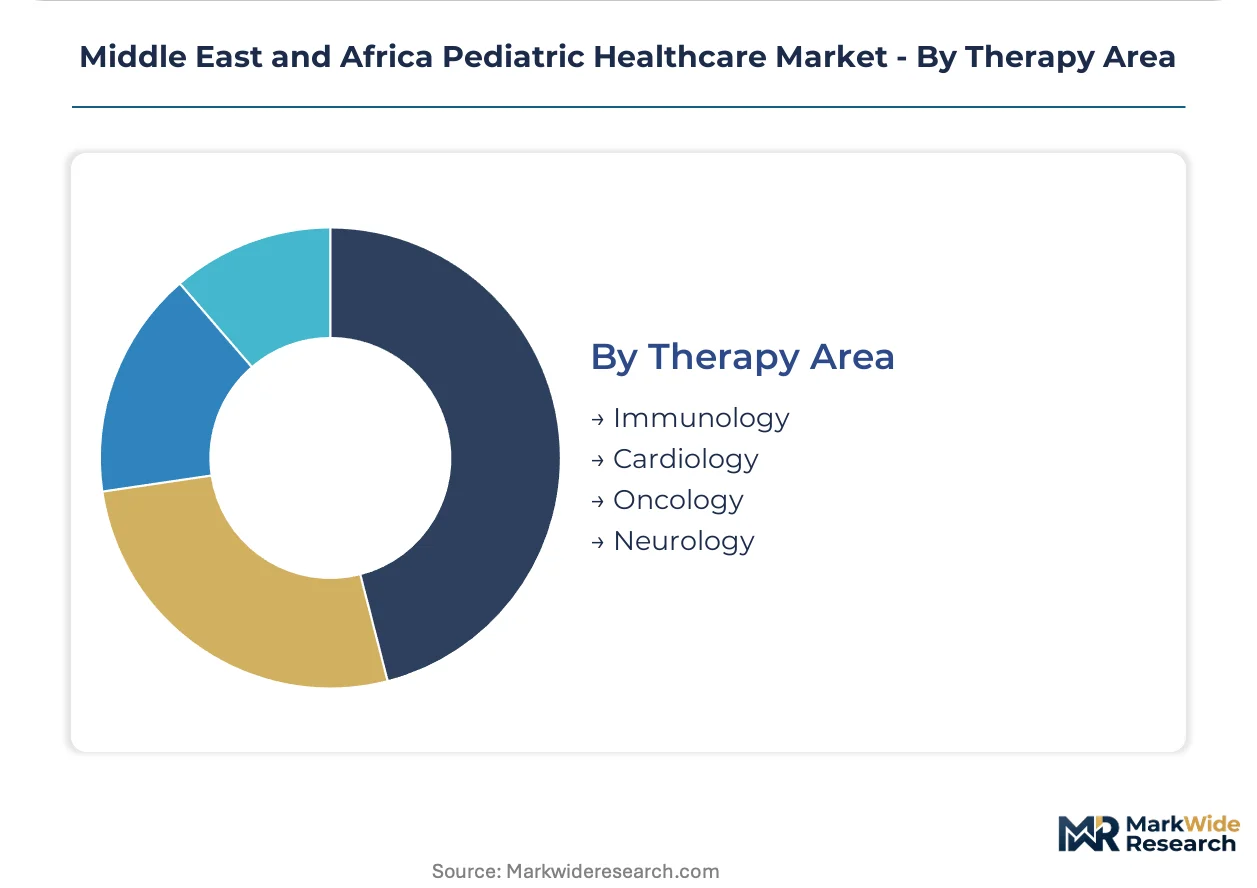
Disease prevalence patterns and interventional capacity development determine segment prioritization across markets with uneven specialist availability.
- Cardiology:Interventional and medical management of congenital heart conditions prevalent in regional birth cohorts. Saudi tertiary centers build specialized capacity, creating demand for device portfolios calibrated to pediatric cardiac anatomy and procedural requirements.
- Immunology:Vaccine-preventable disease programs and immune-mediated condition management. Gulf Cooperation Council national immunization scale-up concentrates procurement volume, while African markets depend on Gavi and bilateral donor financing for program continuity.
- Oncology:Pediatric cancer therapeutic protocols and supportive care interventions.
- Neurology:Developmental, epileptic, and neurodegenerative condition management in pediatric populations.
Immunology anchors the volume base. Cardiology presents the steepest specialization trajectory as interventional capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Food and Drug Authority anchors the regulatory landscape across Gulf Cooperation Council states, with procurement timelines and device registration pathways setting the pace for capital deployment throughout the region.
Saudi Arabia
Healthcare privatization redirects capital toward pediatric infrastructure buildout in Riyadh and Jeddah. SFDA accelerated device registration pathways compress approval timelines against regional benchmarks. Tertiary facilities in the Eastern Province lead systematic procurement of neonatal monitoring systems and intensive care instrumentation.
United Arab Emirates
MOHAP drives regulatory harmonization while Dubai and Abu Dhabi health authorities expand home care delivery models for chronic pediatric conditions. The country's medical free zones attract device manufacturers establishing regional distribution hubs. Pediatric clinics across the Northern Emirates adopt portable diagnostic platforms faster than projected replacement cycles.
South Africa
The Health Products Regulatory Authority tightened medical device registration timelines, creating asymmetric market access costs against Egyptian benchmarks. Johannesburg and Cape Town tertiary centers concentrate demand for precision infusion systems with weight-calibrated dosing safeguards. Private hospital groups drive unbundled service contracts separating multi-year maintenance from capital equipment acquisition.
Nigeria
Primary care networks in Lagos and Abuja adopt point-of-care ultrasound and portable respiratory analyzers, extending diagnostic access beyond tertiary hospital networks. The country's national pharmaceutical regulator maintains extended review cycles for imported precision instrumentation. Pediatric clinics penetrate underserved states through donor-funded portable platform deployment.
Egypt
Egypt's Drug Authority maintains divergent registration timelines against South African benchmarks, fragmenting market entry pathways for device manufacturers. Cairo and Alexandria concentrate interventional pediatric cardiology capacity buildout. Tertiary centers in the Nile Delta region generate demand for device portfolios calibrated to congenital cardiac conditions prevalent in regional birth cohorts.
Middle East and Africa Pediatric Healthcare Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa pediatric healthcare market. The vendor base stratifies into three tiers: multinational conglomerates with installed imaging bases securing long-term service contracts, diversified healthcare conglomerates competing on cardiac device portfolios, and specialized regional distributors navigating fragmented African registration pathways. Dominant competitive moves include unbundling service contracts from capital equipment sales and localizing spare parts inventory to defend renewal rates.
Among the multinational technology conglomerates, General Electric Company and Koninklijke Philips N.V. exemplify the installed-base-leverage archetype, anchoring positions through imaging platform dominance and localized production strategies respectively. Medtronic occupies a position within the cardiac specialization tier, with portfolio calibration toward congenital conditions prevalent in regional birth cohorts. Siemens AG, Atom Medical Corp., Pfizer, Johnson & Johnson, Abbott, and Sanofi round out the competitive set across device, pharmaceutical, and diagnostic segments.
| Leading Market Players |
|---|
| General Electric Company |
| Koninklijke Philips N.V. |
| Medtronic |
| Siemens AG |
| Atom Medical Corp. |
| Pfizer |
| Johnson & Johnson |
| Abbott |
| Sanofi |
| Others |
Supply & Pricing Matrix
Installed-base scale economies in neonatal monitoring systems concentrate manufacturing leverage among European and North American suppliers, establishing price floors that Gulf Cooperation Council procurement officers negotiate against through multi-year service unbundling. Currency volatility across African markets amplifies landed cost spreads between centralized tender mechanisms and fragmented distributor networks.
Pricing Analysis
Gulf Cooperation Council states command 15-25% price discounts against Nigerian and Kenyan clinic procurement through volume aggregation and centralized tender structures. Three-tier pricing structure across premium CE-marked, standard FDA-cleared, and economy non-certified equipment tiers reflects divergent regulatory acceptance across SFDA, SAHPRA, and Egypt's Drug Authority jurisdictions. Cost compression in economy tiers intensifies as Chinese manufacturers penetrate African donor-funded programs. Government hospital procurement committees exhibit lowest price sensitivity; private clinic networks in UAE and Qatar demonstrate highest elasticity.
Supply Chain Analysis
Germany, the United States, and Japan anchor precision instrumentation manufacturing for miniaturized surgical tools and calibrated dosing systems. Supply chains draw from specialized polymer feedstocks, semiconductor sensors, and biocompatible alloys. Single-source vulnerability concentrates in neonatal respiratory component modules where two European suppliers control 70% of global capacity. Distribution runs through Dubai's Jebel Ali medical free zone for Gulf markets, with Johannesburg and Cairo serving as secondary hubs for African inland routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pediatric nurse scarcity across Saudi Arabia, Egypt, and South Africa constrains bed capacity utilization regardless of capital equipment availability, creating a capability-scarcity environment where human capital access trumps technology deployment.
For Market Incumbents: Secure long-term service contract renewals through spare parts localization in Dubai and Johannesburg, defending against emerging Chinese manufacturers offering 30-40% equipment discounts without technical support infrastructure. Prioritize neonatal intensivist training partnerships with Saudi tertiary hospitals to lock in exclusive procurement relationships. For New Entrants and Emerging Players: Remote patient monitoring for chronic pediatric conditions in UAE and Qatar represents an underserved service layer where incumbents lack home care delivery expertise. Target home care segments through direct-to-clinic portable diagnostic platforms, bypassing hospital procurement committees with patient-administered therapy subscription models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cardiac device specialists with congenital condition portfolios as Saudi Arabia builds interventional pediatric cardiology capacity. Long-term viability rests on regulatory pathway breadth across SFDA, SAHPRA, and AMRH harmonization timelines. Watch AMRH centralized approval protocol adoption rates as inflection signal for multi-country registration cost efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pediatric-Critical Device Fast-Track | Accelerated registration compresses time-to-revenue against South African SAHPRA benchmarks. |
| Neonatal Intensivist Training Partnership | Human capital scarcity in Saudi Arabia creates exclusive procurement lock-in opportunities. |
| Spare Parts Localization Hub | Dubai Jebel Ali and Johannesburg distribution defend service contract renewal rates. |
| Portable Ultrasound Clinic Deployment | Nigerian and Kenyan primary care networks adopt faster than legacy radiology replacement cycles. |
| AMRH Harmonization Alignment | Early protocol adoption rewards streamlined multi-country registration cost structures. |
Research Methodology
A standing panel of neonatal intensivists, hospital procurement committee chairs, biomedical equipment engineers, and GPO contracts managers provided ongoing calibration against secondary validation from SFDA registration databases, SAHPRA device approval records, hospital procurement transaction logs, and AMRH programme documentation. Bottom-up equipment shipment analysis triangulated with top-down healthcare expenditure tracking across Gulf Cooperation Council national budgets and African donor program disclosures.
Consistency checks validated volume and value outputs against external benchmarks including WHO immunization program procurement reports, UNICEF medical device tender awards, and regional hospital capital expenditure surveys. Segmentation modeling spanned product type, end user channel, delivery mode, and therapy area across the projection horizon. CAGRs derived from weighted average of historical procurement velocity and privatization-driven infrastructure buildout assumptions, with pediatric nurse-to-bed ratios and regulatory approval timeline differentials as primary forecast inputs.
Underlying assumptions cover SFDA accelerated pathway sustainability, AMRH protocol adoption rates, and Gulf privatization commitment continuity, with deviation risk concentrated in workforce training pipeline constraints and currency volatility across African import-dependent markets. Recalibration cycles align with material shifts in national immunization program scale-up announcements and pediatric infrastructure procurement tender releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Growth Hormone Deficiency Market