
 Global Pediatric Radiology Market | 2026-2036
Global Pediatric Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Radiology Market Foresight
EU MDR is shifting the cost-of-entry calculus for pediatric imaging equipment across European markets. Siemens Healthineers AG leverages its installed base of MRI systems to sustain service revenue in children's hospitals. GE Healthcare anchors its competitive position through R&D intensity in low-dose CT protocols. Koninklijke Philips N.V. differentiates via integrated diagnostic platforms that combine ultrasound with AI-assisted interpretation workflows.
Pediatric radiology encompasses diagnostic imaging techniques adapted for anatomical and physiological differences in neonates, infants, and adolescents, requiring specialized equipment with reduced radiation exposure parameters, smaller detector arrays, and child-appropriate sedation protocols. Its primary purpose is detecting congenital anomalies, trauma, and oncological conditions while minimizing long-term biological risk from ionizing radiation. Ultrasound imaging leads among product types due to its zero-radiation profile and real-time vascular assessment capabilities, while magnetic resonance imaging captures expanding share in neurological assessment applications where soft-tissue contrast resolution proves critical. Children's hospitals represent the dominant end-user segment, though teleradiology services are growing fastest as rural and underserved regions seek remote access to pediatric subspecialty interpretation.
FDA pediatric device consortia, EU MDR Article 10 clinical evidence requirements, and WHO diagnostic imaging guidelines collectively shape product standards and market access for pediatric-specific equipment. The FDA mandates child-inclusive trial data for new imaging modalities, while WHO guidelines establish minimum technical specifications for radiation dose management in low-resource settings. Stakeholders must monitor evolving AI validation frameworks and reimbursement parity between adult and pediatric imaging codes to anticipate where capital deployment yields sustainable returns.
Market Dynamics
EU MDR Article 10 clinical evidence requirements are compressing time-to-market for pediatric imaging equipment while simultaneously elevating safety validation standards across all major jurisdictions. This regulatory compression is forcing manufacturers to front-load clinical trial investments and restructure quality management systems before commercial deployment.
Growth Catalysts
- FDA Pediatric Device Consortia:The FDA's specialized pathway accelerates regulatory review for child-safe imaging protocols, reducing approval timelines for modified adult systems adapted to neonatal anatomical specifications.
- Congenital disorder detection protocols:Children's hospitals in Germany and the United States are expanding dedicated pediatric imaging infrastructure to support early-intervention surgical planning for cardiac and neurological anomalies.
- Low-dose CT reconstruction algorithms:Iterative reconstruction software is enabling diagnostic-quality imaging at radiation exposure levels previously considered subtherapeutic, expanding eligible patient populations.
Market Restraints
- Helium supply concentration:Superconducting magnet production for MRI systems depends on helium extraction concentrated in Qatar and the United States, creating input cost volatility and supply interruption risk.
- Pediatric-specific coil manufacturing:Smaller detector arrays require specialized production lines with limited economies of scale, elevating unit costs relative to adult-equivalent hardware.
- Sedation protocol complexity:Child-appropriate anesthesia requirements for lengthy MRI examinations add procedural overhead and specialist staffing constraints that limit throughput in outpatient settings.
Strategic Opportunities
- Rural teleradiology penetration:Underserved regions in India and Brazil present white-space demand for remote pediatric subspecialty interpretation services delivered via cloud-based PACS integration.
- AI-assisted ultrasound interpretation:Machine learning algorithms combined with portable probe hardware are enabling point-of-care cardiac and abdominal screening by non-radiologist clinicians in emergency departments.
- WHO diagnostic imaging guidelines:Minimum technical specifications for radiation dose management in low-resource settings are creating procurement mandates that favor vendors with established pediatric protocol libraries.
Industry Challenges
- Pediatric radiologist workforce scarcity:Fellowship-trained specialists remain concentrated in academic medical centers, creating interpretation bottlenecks for community hospitals attempting to expand pediatric service lines.
- Legacy PACS integration friction:New AI-enabled workstations require costly middleware development to communicate with decade-old archival systems prevalent in mid-tier children's hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Radiology Market |
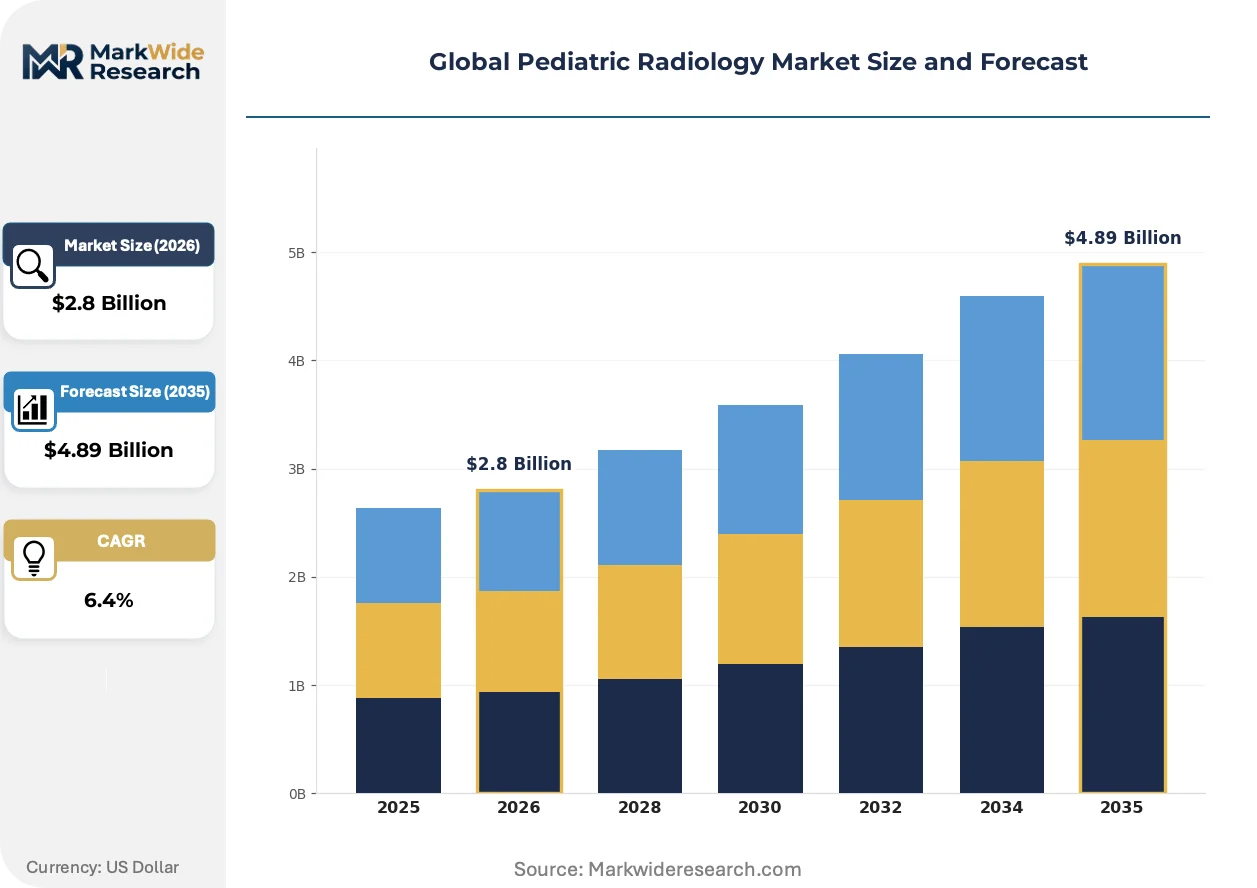
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Radiography, Computed Tomography, Ultrasound Imaging, Magnetic Resonance Imaging, Fluoroscopy Application: Bone Fracture Diagnosis, Abdominal Imaging, Thoracic Examination, Neurological Assessment, Congenital Disorder Detection End User: Children's Hospitals, Specialty Clinics, Diagnostic Centers, Academic Medical Centers, Rehabilitation Facilities Deployment Mode: On-Premise Solutions, Cloud-Based Systems, Hybrid Platforms, Mobile Imaging Units, Teleradiology Services |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, Hitachi Ltd, Esaote SpA, Samsung Electronics Co., Ltd., Fujifilm Holdings Corporation, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Radiology Market Shifts & Advancements
Deep learning reconstruction and portable hardware form factors are rewriting how pediatric imaging capabilities deploy across clinical environments. These shifts are compressing the traditional capital equipment cycle and enabling diagnostic services at points of care previously dependent on centralized radiology departments.
Photon-counting CT detector technology is rewriting dose-efficiency benchmarks for pediatric chest and abdominal protocols. Children's hospitals in Switzerland and South Korea are adopting these systems at replacement cycle acceleration, compressing the obsolescence timeline for energy-integrating detector platforms that dominated the prior decade.
EU MDR clinical evidence requirements are mandating child-inclusive trial data for all new imaging modalities seeking CE marking. Manufacturers are responding by establishing dedicated pediatric investigation plans earlier in development pipelines, with neurological and cardiac applications facing the most stringent evidence thresholds.
Subscription-based equipment access models are displacing outright capital purchases in mid-tier pediatric facilities. Children's hospitals in Spain and Australia are piloting managed service arrangements that bundle hardware, maintenance, and software updates into per-scan pricing, transferring technology obsolescence risk to vendors.
Global Pediatric Radiology Market Segmentation
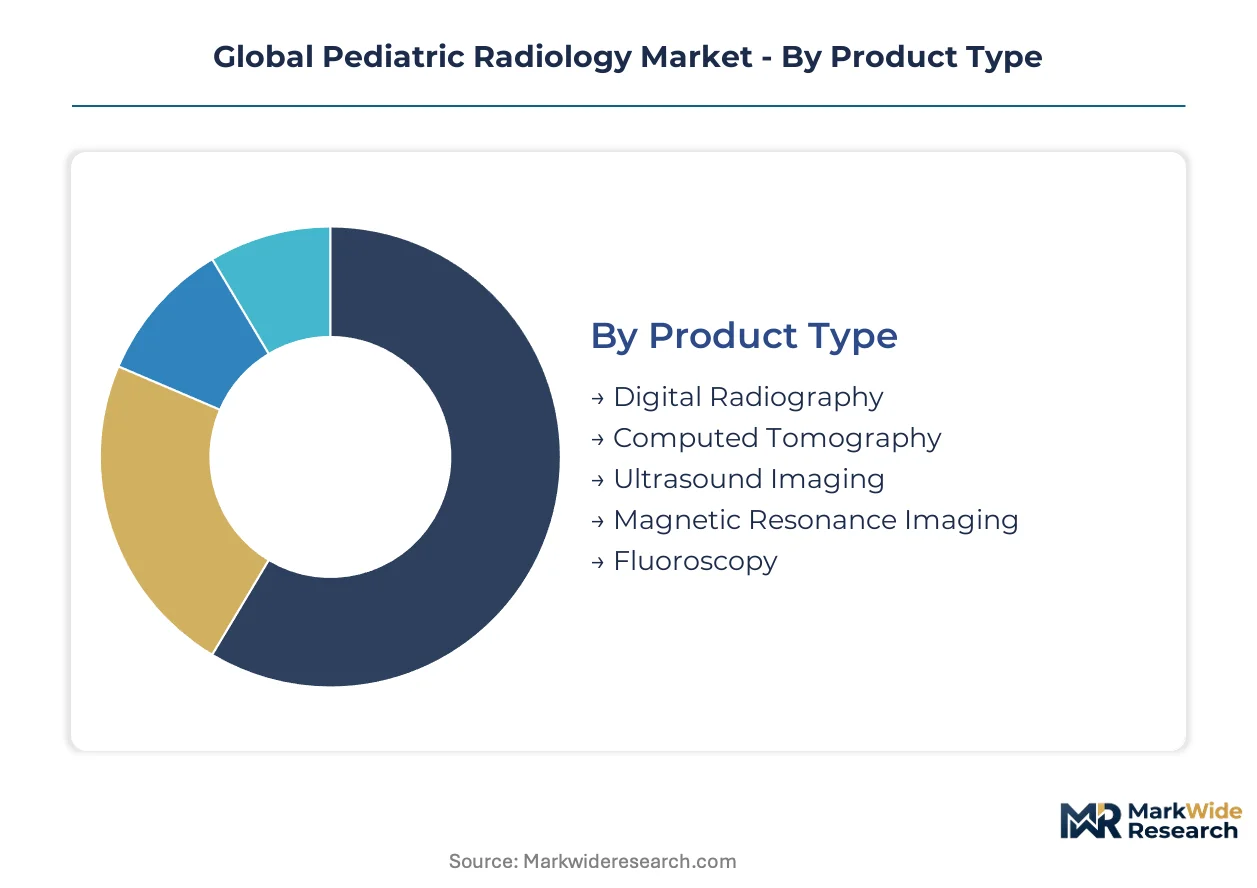
Pediatric radiology segmentation reflects distinct clinical workflows, capital intensity gradients, and regulatory compliance requirements across imaging modalities. Equipment specifications, patient age stratification, and facility reimbursement tiers drive divergent procurement patterns and vendor pricing architectures.
Product Type:
Capital allocation decisions pivot on radiation exposure profiles, magnetic field requirements, and installation footprint constraints.
- Digital Radiography:Flat-panel detector systems with pediatric-specific exposure protocols deliver chest and skeletal imaging at dose levels 40-60% below adult-equivalent settings. Demand clusters in German university hospitals and US children's hospitals upgrading from analog cassette-based systems to meet Joint Commission dose-tracking mandates.
- Ultrasound Imaging:Zero-ionizing-radiation modality employing high-frequency linear and curvilinear probes optimized for neonatal cranial, cardiac, and abdominal applications. Volume concentrates in India and Brazil where portable systems enable point-of-care screening in resource-limited settings without specialist radiologist availability.
- Computed Tomography:Iterative reconstruction algorithms and organ-dose modulation software reduce effective dose in pediatric chest and abdominal protocols.
- Magnetic Resonance Imaging:Superconducting 1.5T and 3T systems with specialized neonatal head and cardiac coils require helium-cooled magnets and child-appropriate sedation infrastructure.
- Fluoroscopy:Pulsed fluoroscopy with last-image-hold functionality minimizes cumulative dose during interventional procedures and contrast studies.
Volume sits with Digital Radiography; growth tilts toward Ultrasound Imaging.
Application:
Clinical indication severity and surgical intervention timelines shape equipment utilization rates and reimbursement coding density.
- Congenital Disorder Detection:Prenatal and postnatal imaging protocols for cardiac, neurological, and renal anomalies demand highest-resolution modalities with submillimeter spatial resolution. Swiss and South Korean children's hospitals are accelerating replacement cycles for photon-counting CT systems specifically to advance early-intervention surgical planning capabilities.
- Neurological Assessment:MRI dominates for posterior fossa malformations, white-matter disorders, and epilepsy surgical planning where soft-tissue contrast resolution proves critical. Academic medical centers in Boston and Heidelberg anchor demand for functional MRI and diffusion tensor imaging protocols adapted to sedated pediatric populations.
- Bone Fracture Diagnosis:Digital radiography and low-dose CT handle growth plate injuries, non-accidental trauma evaluation, and sports-related fractures.
- Abdominal Imaging:Ultrasound-first protocols for appendicitis, intussusception, and hepatobiliary disorders reduce CT utilization in emergency departments.
- Thoracic Examination:Chest radiography and CT address pneumonia complications, congenital lung lesions, and pre-transplant evaluation.
Procedure volume concentrates in Bone Fracture Diagnosis; steepest expansion trajectory belongs to Congenital Disorder Detection.
End User:
Reimbursement tier and subspecialist density determine capital budget scale and technology refresh cadence.
- Children's Hospitals:Dedicated pediatric institutions in Cincinnati, Paris, and Singapore command highest imaging volumes with comprehensive modality portfolios and fellowship-trained radiologist staffing. These facilities drive adoption of AI-assisted reconstruction and dose-tracking analytics as competitive differentiators for referring physician networks.
- Academic Medical Centers:Research-intensive institutions combine clinical service with pediatric imaging trial enrollment for FDA and EMA submission pathways. Clinical evidence generation requirements under EU MDR Article 10 mandate these sites as obligatory partners for manufacturer premarket validation studies.
- Specialty Clinics:Orthopedic, cardiac, and oncology-focused outpatient facilities require narrow-purpose imaging configurations.
- Diagnostic Centers:Independent imaging facilities face reimbursement compression and radiologist recruitment challenges in pediatric service line expansion.
- Rehabilitation Facilities:Long-term care and developmental disorder centers utilize imaging for complication monitoring and treatment response assessment.
Revenue concentrates in Children's Hospitals; patient volume expansion tilts toward Specialty Clinics.
Deployment Mode:
IT infrastructure maturity and network latency tolerances govern architecture selection across facility tiers.
- Teleradiology Services:Cloud-based PACS integration enables pediatric subspecialist interpretation for rural and underserved regions lacking on-site fellowship-trained radiologists. Indian and Brazilian health systems are expanding teleradiology procurement to address workforce maldistribution without capital-intensive equipment duplication.
- Cloud-Based Systems:Vendor-hosted infrastructure reduces hospital IT staffing burdens and enables automatic software updates for AI reconstruction algorithms. Australian and Spanish children's hospitals are piloting managed service arrangements transferring technology obsolescence risk to equipment vendors.
- On-Premise Solutions:Legacy PACS architectures persist in mid-tier US children's hospitals with decade-old archival systems requiring costly middleware for AI workstation integration.
- Hybrid Platforms:Mixed cloud-edge configurations balance data sovereignty requirements with computational scalability.
- Mobile Imaging Units:Truck-mounted MRI and CT systems extend diagnostic access to remote populations and disaster response scenarios.
Installed base sits with On-Premise Solutions; procurement momentum tilts toward Teleradiology Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Karnataka are concentrating pediatric imaging equipment manufacturing through tax-advantaged export processing. These zones attract multinational assembly operations seeking proximity to Asia-Pacific demand clusters while maintaining tariff-efficient supply chains into European and North American markets.
United States
Children's hospitals in Cincinnati and Boston drive MRI replacement cycles for neurological assessment protocols. The FDA pediatric device consortia pathway accelerates 510(k) clearances for modified adult systems adapted to neonatal anatomical specifications. Research-intensive medical centers in Greater Boston anchor clinical trial enrollment for photon-counting CT validation studies.
Germany
University hospitals in Heidelberg and Munich scale imaging infrastructure for congenital cardiac anomaly detection. EU MDR Article 10 mandates child-inclusive trial data for CE marking of new modalities, elevating evidence requirements for manufacturers. The Baden-Württemberg medical technology cluster concentrates superconducting magnet engineering and specialized pediatric coil production.
China
Provincial maternal and child health hospitals in Guangdong and Sichuan expand CT and MRI procurement under national healthcare infrastructure programs. NMPA regulatory harmonization with IMDRF standards streamlines approval pathways for imported imaging equipment. The Yangtze River Delta manufacturing corridor supplies detector arrays and gradient coil subassemblies to global OEMs.
India
Public sector hospitals in Maharashtra and Karnataka deploy portable ultrasound systems for point-of-care neonatal screening. CDSCO import licensing requirements for radiation-emitting devices create compliance bottlenecks for CT and fluoroscopy equipment. The Bengaluru medical device SEZ concentrates assembly operations for Southeast Asian and African export markets.
Switzerland
Children's hospitals in Zurich and Geneva accelerate replacement cycles for photon-counting CT systems. Swissmedic maintains stringent pediatric-specific safety surveillance for imaging equipment post-market performance. The Basel pharmaceutical-medical technology corridor supports contrast agent and imaging software co-development partnerships.
Global Pediatric Radiology Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across modality-specific segments. The vendor base organizes into three tiers: full-platform conglomerates with installed base leverage, mid-scale regional specialists with service density advantages, and emerging Asian manufacturers competing on hardware cost. Consolidation pressure intensifies as AI-enabled reconstruction software becomes the primary differentiation vector. Strategic moves concentrate on teleradiology platform acquisitions and managed service contract structures that transfer obsolescence risk.
Among diversified imaging conglomerates, Siemens Healthineers AG and GE Healthcare occupy positions defined by superconducting MRI magnet installed bases and service revenue capture. Koninklijke Philips N.V. represents the integrated diagnostic platform archetype combining ultrasound hardware with AI-assisted interpretation workflows. These three entities exemplify distinct competitive positioning strategies: Siemens Healthineers AG through magnetic resonance technology depth, GE Healthcare through low-dose CT protocol R&D intensity, and Koninklijke Philips N.V. through point-of-care ultrasound portability and cloud-based PACS integration.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Hitachi Ltd |
| Esaote SpA |
| Samsung Electronics Co., Ltd. |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert Group |
| Others |
Supply & Pricing Matrix
EU MDR Article 10 clinical evidence requirements for pediatric imaging equipment gate both qualified supply and premium-tier pricing access, as manufacturers must front-load validation investments before commercial deployment. This regulatory threshold bifurcates vendor tiers, with compliant suppliers commanding service-contract premiums while non-compliant competitors face exclusion from German and Swiss procurement channels.
Pricing Analysis
Short lead-time premiums for helium-cooled MRI magnet systems run 15-25% above standard contract pricing, while spot inventory of pediatric-specific detector arrays trades at discounts in oversupplied quarters. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled reconstruction platforms from legacy hardware and refurbished systems. Cost compression in mid-tier digital radiography is intensifying because Indian and Brazilian buyers prioritize per-scan economics over upfront capital outlays. Community hospitals in rural North America exhibit highest price sensitivity, whereas academic medical centers in Boston and Heidelberg demonstrate lowest sensitivity due to grant-funded procurement.
Supply Chain Analysis
Single-source vulnerability sits with Qatar and the United States for helium extraction, creating input cost volatility that ripples through superconducting magnet production. Manufacturing draws from China for detector array subassemblies, Germany for gradient coil engineering, and South Korea for photon-counting CT detector modules. Tariff exposure on rare-earth magnet materials feeds from escalating trade restrictions between major economies. Distribution runs through OEM direct sales for large hospital systems, specialized medical device distributors for mid-tier facilities, and managed service providers piloting subscription-based equipment access in Spain and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with control over helium supply and AI reconstruction software emerging as the decisive upstream and downstream levers determining sustainable margin capture.
For Market Incumbents: Lock in helium supply through long-term offtake agreements with Qatari and US extraction facilities, insulating production from commodity volatility. Deepen backward integration into pediatric-specific coil manufacturing to capture economies of scale currently lost to specialized subassembly vendors. Defend against emerging Asian manufacturers competing on hardware cost by embedding AI-assisted interpretation into service contracts that raise switching costs for children's hospitals.
For New Entrants and Emerging Players: Begin with portable ultrasound hardware paired with cloud-based PACS integration, targeting teleradiology white space in Indian and Brazilian rural health systems where specialist radiologist scarcity creates immediate demand. Prioritize point-of-care cardiac and abdominal screening applications that bypass capital-intensive MRI and CT infrastructure requirements. Establish go-to-market partnerships with regional distributors possessing existing relationships with public sector maternal and child health hospitals.
For Investors and Strategic Acquirers: FDA pediatric device consortia pathway acceleration is the leading indicator that regulatory compression will favor vendors with pre-validated clinical evidence packages, making acquisition of mid-scale specialists with established pediatric trial portfolios attractive. Frame long-term viability around AI-enabled reconstruction software becoming the primary differentiation vector, displacing hardware-centric competition. Target acquisition candidates with managed service contract expertise and installed base leverage in children's hospitals.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Security Program | Long-term offtake agreements with Qatar and US extraction facilities stabilize superconducting magnet production costs. |
| Pediatric Coil Manufacturing Integration | In-house production of specialized detector arrays captures margin currently paid to German and Japanese subassembly vendors. |
| AI Reconstruction Platform Development | Machine learning algorithms for iterative CT reconstruction and accelerated MRI sequences differentiate premium-tier offerings. |
| Teleradiology Infrastructure Partnership | Cloud-based PACS integration with Indian and Brazilian health systems addresses workforce maldistribution without capital duplication. |
| Managed Service Contract Expansion | Subscription-based equipment access in Spanish and Australian children's hospitals transfers technology obsolescence risk to vendors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with pediatric radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EU MDR Article 10 submissions, NMPA registration databases, and hospital procurement records provided validation benchmarks. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis enabled triangulation across methodology approaches.
Data-stream reconciliation across product type, application, end user, and deployment mode dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating replacement cycle timing, regulatory approval velocity, and reimbursement code parity evolution. Industry-specific forecast inputs included helium price volatility indices and pediatric radiologist workforce density metrics by metropolitan statistical area.
Underlying measurement precision varies by segment; digital radiography and ultrasound imaging carry tighter precision than photon-counting CT where adoption remains nascent. Forecasts reflect assumptions around EU MDR enforcement consistency, helium supply chain stability, and AI validation framework maturation. Deviation in FDA pediatric device consortia pathway throughput or NMPA regulatory harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Autism Service Platform Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Pediatric Tube Feeding Market