
 Global Pediatric Vaccines Market | 2026-2036
Global Pediatric Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Vaccines Market Intelligence
EU MDR is realigning the cost-of-entry calculus for pediatric vaccine developers, forcing upgrades to clinical documentation and post-market surveillance systems. Merck & Co., Inc. leverages its manufacturing scale across multiple antigen platforms to sustain supply commitments to UNICEF and Gavi. Sanofi anchors its position through recombinant protein expertise, while Serum Institute of India Pvt. Ltd. competes aggressively on volume pricing for WHO-prequalified combination vaccines.
Pediatric vaccines comprise antigenic preparations administered to infants and children to induce active immunity against infectious diseases, typically formulated with aluminum-based adjuvants or lipid nanoparticle delivery systems and stabilized within strict cold-chain parameters. Their primary purpose is to prevent morbidity and mortality from pathogens such as Streptococcus pneumoniae, Haemophilus influenzae type b, and rotavirus in populations under five years of age. Conjugate vaccines command premium positioning due to complex polysaccharide-protein coupling chemistry and superior immunogenicity in neonatal immune systems. mRNA technology is gaining fastest traction among pipeline candidates, though recombinant DNA platforms still dominate current commercial supply.
FDA's pediatric study requirements under the Pediatric Research Equity Act, EMA's extrapolation guidelines for pediatric immunogenicity, and WHO prequalification standards collectively shape trial design, labeling, and distribution eligibility across jurisdictions. These frameworks determine which formulations reach national immunization schedules and which manufacturers qualify for multilateral procurement tenders. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on pediatric extrapolation protocols, as alignment or divergence will reshape development timelines and portfolio prioritization decisions.
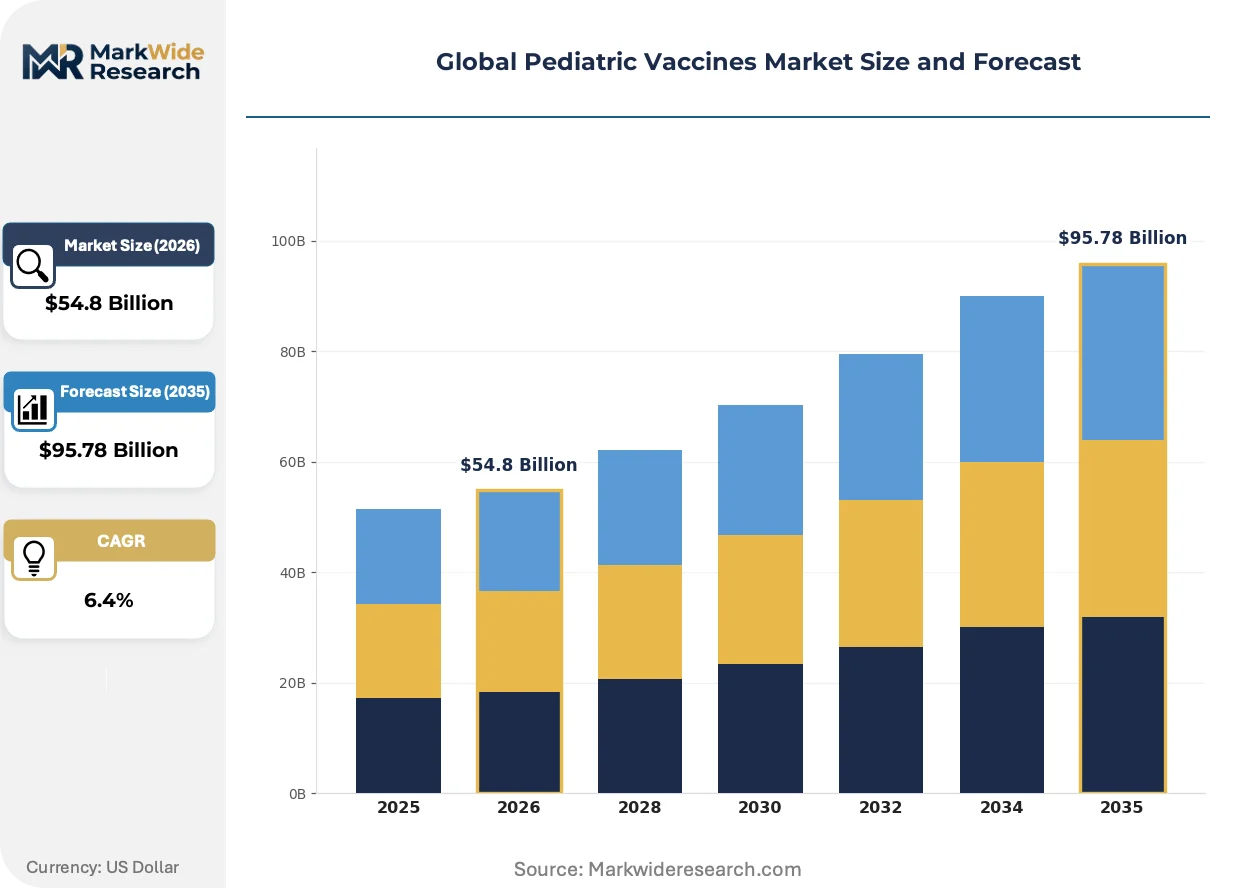
Market Dynamics
Supply consolidation among a handful of antigen manufacturers is concentrating procurement leverage in multilateral agencies, while mRNA platform investments are compressing development timelines and reshaping portfolio economics across the industry.
Growth Catalysts
- WHO Prequalification Pathway:The streamlined assessment protocol accelerates market access for combination vaccines in Gavi-eligible countries, expanding addressable volumes for qualified suppliers.
- India's Public Procurement Networks:Domestic manufacturers leverage centralized tendering mechanisms to achieve scale economies in pentavalent and rotavirus formulations, driving unit cost reductions across South Asian supply.
- Conjugate Chemistry Advances:Improved polysaccharide-protein coupling methods enhance immunogenicity in neonatal populations, enabling earlier dosing schedules and expanded schedule coverage.
Market Restraints
- Cold-Chain Infrastructure Gaps:Last-mile distribution in sub-Saharan Africa and parts of South Asia requires maintained 2-8°C integrity, limiting reach where passive cooling fails.
- Aluminum Adjuvant Supply Concentration:Three specialty chemical suppliers control bulk aluminum phosphate production, creating input vulnerability for legacy formulation manufacturers.
- EMA Pediatric Extrapolation Friction:Divergent immunogenicity bridging requirements between European and WHO standards force duplicate clinical investments for dual-label products.
Strategic Opportunities
- Indonesia's National Immunization Scale-Up:The country's expanding birth cohort and local production incentives under the Health Law create demand for pentavalent and PCV formulations.
- Thermostable Formulation Platforms:Vaccines stable at 25°C for 30+ days eliminate cold-chain dependency, opening last-mile access in tropical climates without active refrigeration.
- Digital Immunization Registries:Integration of biometric patient tracking with supply chain systems reduces wastage and enables demand-forecast precision at district level.
Industry Challenges
- Fill-Finish Capacity Bottlenecks:Aseptic manufacturing suites for multi-dose vials require 18-24 month validation timelines, constraining surge response to outbreak demand.
- Regulatory Convergence Uncertainty:Misalignment between FDA's Pediatric Research Equity Act and EMA's extrapolation guidelines forces parallel development tracks, duplicating clinical investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Vaccines Market |
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $95.78 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Conjugate, Toxoid Technology: Recombinant DNA, mRNA, Viral Vector, Protein Subunit, Adjuvant-Enhanced Application Area: Immunization Programs, Disease Prevention, Outbreak Control, Travel Prophylaxis, Routine Vaccination End User: Pediatric Clinics, Community Health Centers, School-Based Programs, Mobile Vaccination Units |
| Companies Covered | Merck & Co., Inc., Sanofi, Pfizer Inc., GlaxoSmithKline plc, CSL Limited, Johnson & Johnson, AstraZeneca plc, Serum Institute of India Pvt. Ltd., Novavax, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Vaccines Market Strategic Shifts & Innovations
mRNA technology is compressing antigen design cycles from years to months, while regulatory agencies race to adapt pediatric safety frameworks to novel platform risks. These shifts are redrawing competitive boundaries between established recombinant suppliers and emerging biotech developers.
Lipid nanoparticle delivery systems are rewriting the economics of pediatric vaccine development by enabling rapid response to emerging pathogens without cell-culture manufacturing constraints. UNICEF and Gavi procurement officers are piloting mRNA candidates for respiratory syncytial virus in 2024-2025 tenders. The technology is compressing the traditional 10-15 year development horizon into 3-5 year cycles, forcing legacy manufacturers to accelerate platform diversification or cede pipeline leadership.
EMA's Medical Device Regulation extension into combination product oversight is tightening post-market surveillance requirements for needle-free delivery systems and auto-injectors. Manufacturers must now maintain clinical data registries for device-vaccine combinations across the product lifecycle. Pediatric formulation developers in Germany and the Netherlands are consolidating quality management systems to meet the new vigilance standards, raising compliance costs for mid-tier suppliers.
Direct national contracting is displacing traditional distributor networks in middle-income markets, with Brazil's Ministry of Health and Nigeria's National Primary Health Care Development Agency building in-house procurement capabilities. These agencies now negotiate volume commitments directly with WHO-prequalified manufacturers, bypassing regional intermediaries. The shift is most visible in Latin America, where PAHO's Revolving Fund faces competition from bilateral supply agreements struck at price points 8-12% below pooled procurement rates.
Global Pediatric Vaccines Market Segmentation
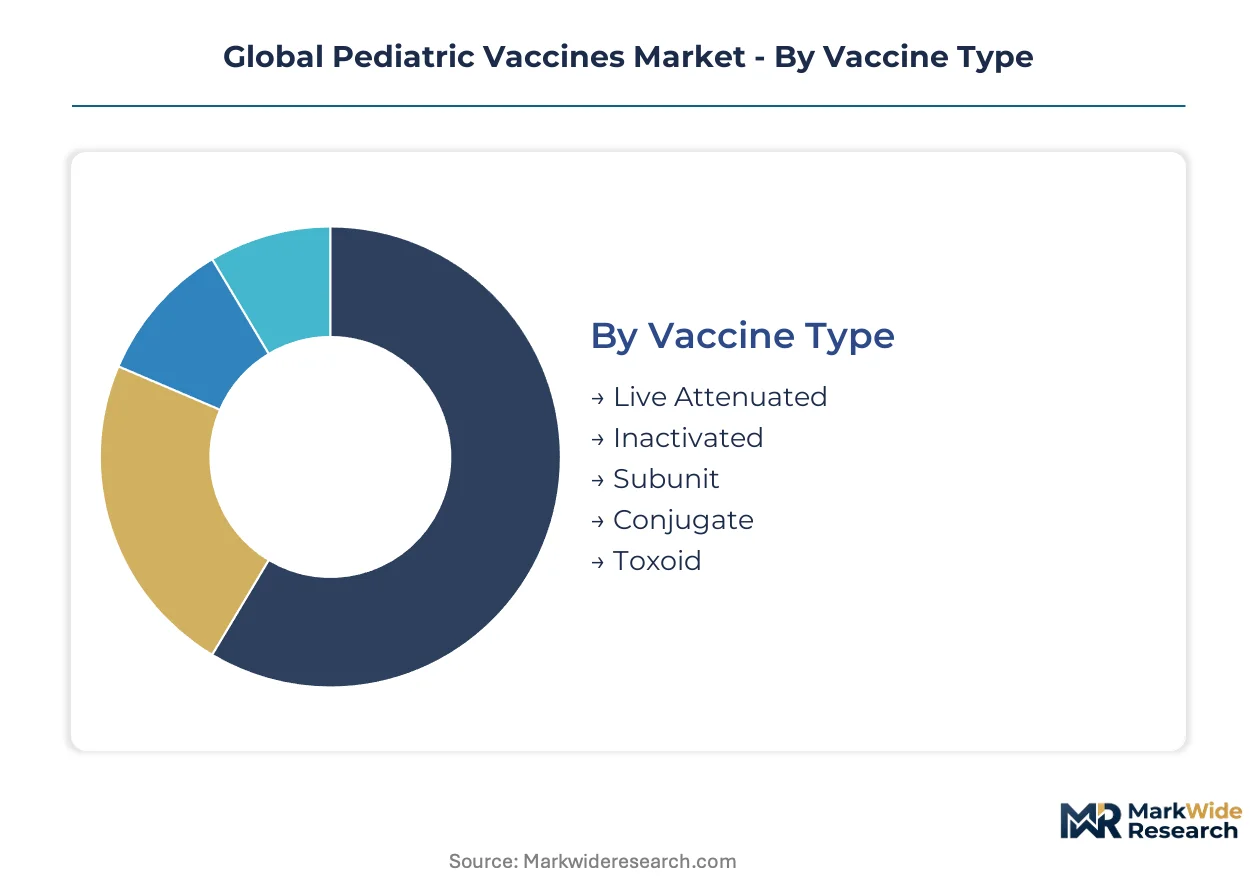
Pediatric vaccine segmentation reveals how formulation chemistry, delivery platforms, and distribution infrastructure intersect to determine access patterns and procurement economics. Manufacturers align R&D portfolios and manufacturing investments across these axes to match WHO prequalification pathways with national immunization schedule requirements.
Vaccine Type:
Formulation chemistry determines cold-chain requirements, dosing schedules, and immunogenicity profiles across neonatal and infant populations.
- Conjugate:Polysaccharide-protein coupling chemistry enables robust T-cell dependent responses in immature immune systems. UNICEF tenders for pneumococcal and meningococcal formulations concentrate procurement volumes for suppliers with validated coupling platforms.
- Live Attenuated:Weakened pathogen strains replicate briefly to elicit durable cellular and humoral immunity. India's Universal Immunization Program drives concentrated demand for measles-rubella and rotavirus oral formulations through centralized state-level procurement.
- Inactivated:Heat-killed or chemically treated pathogens eliminate replication risk while preserving immunogenic epitopes. Demand clusters in injectable polio and hepatitis A schedules requiring strict aseptic administration protocols.
- Subunit:Purified antigen components reduce reactogenicity compared to whole-cell approaches. Acellular pertussis formulations dominate national schedules in Japan and Western European markets with stringent safety surveillance.
- Toxoid:Formalin-inactivated exotoxins induce protective antitoxin antibodies without infection risk. Tetanus-diphtheria combinations anchor routine infant schedules across Gavi-eligible countries with established birth-dose protocols.
Conjugate formulations lead on scale through multilateral procurement concentration; mRNA-enabled subunit approaches lead on momentum in pipeline development.
Technology:
Platform economics determine development timelines, manufacturing flexibility, and regulatory validation burdens for pediatric indications.
- Recombinant DNA:Microbial or mammalian expression systems produce purified antigens without pathogen cultivation. Serum Institute of India and Sanofi anchor commercial supply for hepatitis B and HPV formulations through scaled fermentation infrastructure.
- mRNA:Synthetic nucleic acid sequences enable rapid antigen design without cell-culture constraints. Pfizer-BioNTech and Moderna are advancing respiratory syncytial virus candidates through FDA pediatric trial pathways with compressed development horizons.
- Viral Vector:Engineered adenovirus or vaccinia backbones deliver transgenes for intracellular antigen presentation. Ebola and emerging pathogen platforms are adapting dose-escalation protocols for pediatric safety evaluation.
- Protein Subunit:Recombinant or purified native proteins formulated with aluminum adjuvants dominate current commercial supply. Novavax and GSK maintain validated manufacturing for pertussis and hepatitis B pediatric indications.
- Adjuvant-Enhanced:Novel immunostimulants including AS01 and MF59 amplify responses in populations with reduced immune competence. GSK's malaria RTS,S formulation with AS01 demonstrates efficacy expansion in sub-Saharan African infant cohorts.
Recombinant DNA platforms command current procurement volumes; mRNA systems are climbing the fastest as Gavi and UNICEF pilot novel tender structures.
Application Area:
Deployment context shapes formulation requirements, presentation formats, and supply chain specifications for pediatric delivery.
- Immunization Programs:Government-funded routine schedules require multi-dose vial presentations and centralized cold-chain distribution. India's Mission Indradhanush and Nigeria's National Primary Health Care Development Agency negotiate volume commitments directly with WHO-prequalified manufacturers.
- Disease Prevention:Prophylactic administration targets pathogen-specific protection in defined risk populations. Brazil's Ministry of Health integrates yellow fever and Japanese encephalitis formulations into regional schedules based on epidemiological mapping.
- Outbreak Control:Surge deployment demands rapid scale-up of single-antigen or combination formulations. Cholera and meningococcal stockpiles maintained by WHO and MSF require thermostable presentations for emergency field use.
- Travel Prophylaxis:Private-market administration serves mobile populations visiting endemic regions. Japanese encephalitis and typhoid formulations concentrate in urban pediatric clinics serving expatriate communities in Singapore and Dubai.
- Routine Vaccination:Scheduled primary series and booster doses anchor national health system infrastructure. Indonesia's expanding birth cohort under Health Law provisions is scaling pentavalent and PCV procurement through domestic production incentives.
Immunization programs capture procurement volume concentration; outbreak control applications are gaining share fastest through pandemic preparedness investments.
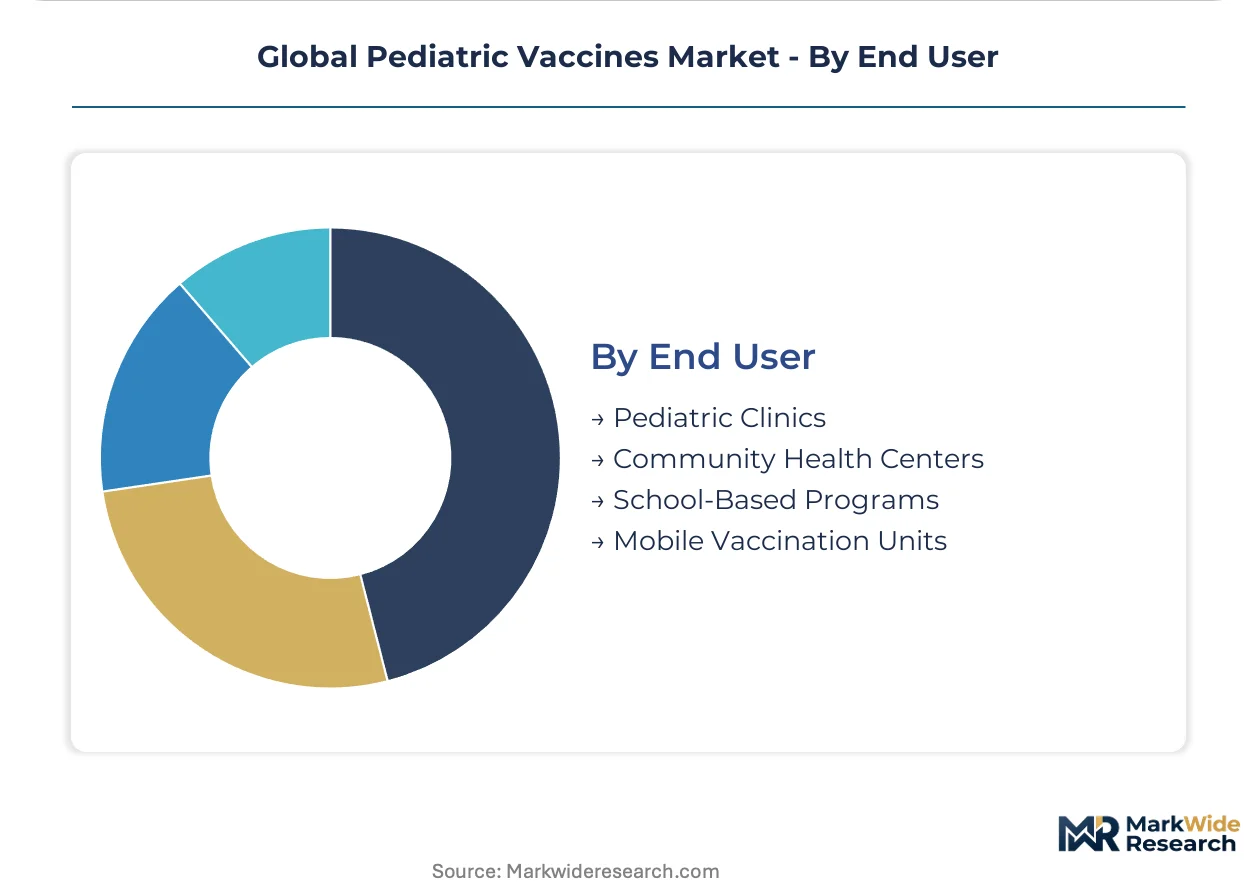
End User:
Delivery site determines cold-chain integrity requirements, waste management protocols, and demand forecasting precision.
- Pediatric Clinics:Dedicated facilities maintain continuous cold-chain infrastructure with trained immunization staff. Urban private clinics in São Paulo and Mumbai administer combination formulations with electronic registry documentation.
- Community Health Centers:Primary care integration extends reach to rural and underserved populations. Ethiopia's Health Extension Program leverages solar-powered refrigeration for last-mile pentavalent and rotavirus delivery.
- School-Based Programs:Mass administration achieves cohort coverage for adolescent boosters and catch-up campaigns. HPV and Tdap formulations in Rwanda and Australia demonstrate efficiency through centralized educational institution access.
- Mobile Vaccination Units:Vehicle-mounted or temporary outreach extends coverage to nomadic and conflict-affected populations. Nigeria's polio eradication infrastructure adapts for measles and COVID-19 pediatric outreach in Lake Chad basin regions.
Community health centers lead on reach expansion; mobile units are expanding most quickly through digital tracking and passive cooling innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioprocessing talent clusters in Basel, Boston, and Bangalore anchor vaccine development capacity across three continents. Manufacturing scale concentrates where regulatory science expertise intersects with cold-chain logistics infrastructure.
United States
FDA's Pediatric Research Equity Act mandates pediatric-specific trial data for new molecular entities, compressing development timelines for mRNA platform candidates. The agency's accelerated approval pathways for breakthrough therapies attract venture funding to the Greater Boston corridor. Maryland's I-270 biotech corridor hosts concentrated fill-finish capacity serving UNICEF tender requirements.
India
CDSCO's streamlined manufacturing license renewals enable rapid scale-up of WHO-prequalified combination vaccines. The government's PLI scheme for pharmaceuticals incentivizes domestic pentavalent and rotavirus production. Hyderabad's Genome Valley cluster houses concentrated bulk antigen fermentation capacity serving Gavi procurement volumes.
Germany
EMA's Medical Device Regulation extension into combination products tightens post-market surveillance for needle-free delivery systems. The regulator's pediatric extrapolation guidelines diverge from FDA standards, forcing parallel clinical investments. Marburg's bioprocessing hub maintains validated viral vector manufacturing for emerging pathogen platforms.
Brazil
ANVISA's alignment with WHO prequalification standards accelerates registration timelines for imported pediatric formulations. The Ministry of Health's direct national contracting displaces traditional distributor networks in favor of bilateral manufacturer agreements. São Paulo's Butantan Institute anchors regional fill-finish capacity for PAHO Revolving Fund supply.
China
NMPA's pediatric vaccine approval pathways require domestic clinical trial data, limiting parallel registration with Western regulators. The national immunization program's expansion to non-EPI vaccines creates demand for private-market PCV and rotavirus formulations. Beijing's Zhongguancun biotech corridor concentrates mRNA platform R&D investment.
Global Pediatric Vaccines Market Key Industry Players
The competitive structure tilts toward diversified pharmaceutical conglomerates with validated multi-antigen manufacturing platforms. Supply consolidation among a handful of bulk antigen producers concentrates procurement leverage in multilateral agencies. Three strategic archetypes dominate: integrated multinationals with UNICEF supply commitments, emerging market scale specialists, and platform-technology biotech developers. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping manufacturing geography.
Within the integrated multinational tier, Merck & Co., Inc. and Sanofi exemplify archetypes built on recombinant protein expertise and manufacturing scale across multiple antigen platforms. Serum Institute of India Pvt. Ltd. occupies a distinct position as an emerging market scale specialist, leveraging centralized tendering mechanisms and volume pricing for WHO-prequalified combination vaccines. These three entities collectively represent the spectrum of competitive positioning from premium conjugate chemistry to high-volume pentavalent supply.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Sanofi |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| CSL Limited |
| Johnson & Johnson |
| AstraZeneca plc |
| Serum Institute of India Pvt. Ltd. |
| Novavax, Inc. |
| Others |
Cost & Logistics Intelligence
mRNA platform investments are compressing development timelines while simultaneously fragmenting manufacturing economics between legacy recombinant suppliers and novel nucleic acid producers. This technological bifurcation concentrates pricing power among WHO-prequalified bulk antigen manufacturers while forcing mid-tier developers toward volume-based procurement participation.
Pricing Analysis
Bundled combination vaccines versus single-antigen formulations create divergent pricing architectures across procurement channels. UNICEF and Gavi tenders for pentavalent and pneumococcal conjugate vaccines anchor the premium tier through complex polysaccharide-protein coupling chemistry, while India's centralized state procurement drives aggressive unit cost compression for measles-rubella and rotavirus oral doses. Pricing pressure stems from aluminum adjuvant supply concentration among three specialty chemical suppliers, tightening margins for legacy formulation manufacturers. Multilateral agencies exhibit highest price sensitivity due to volume commitments across Gavi-eligible countries, whereas private-market travel prophylaxis segments in Singapore and Dubai sustain modest premiums for Japanese encephalitis and typhoid formulations.
Supply Chain Analysis
Bulk aluminum phosphate production rests on specialty chemical suppliers concentrated in Germany, the United States, and India, creating input vulnerability for adjuvant-dependent legacy vaccines. Lipid nanoparticle delivery systems draw from precision lipid manufacturers in South Korea and Japan, while mRNA synthesis capacity clusters in the Greater Boston corridor and Basel biotech hub. Single-source vulnerability runs through fill-finish aseptic manufacturing suites requiring 18-24 month validation timelines, constraining surge response to outbreak demand. Distribution runs through UNICEF's Copenhagen supply division and PAHO's Revolving Fund for pooled procurement, with direct national contracting in Brazil and Nigeria increasingly displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric vaccines market functions as a regulatory compounder where EMA's Medical Device Regulation extension into combination product oversight intensifies post-market surveillance requirements and reshapes competitive access conditions.
For Market Incumbents: To counter mRNA platform compression of traditional 10-15 year development cycles, Merck and Sanofi should accelerate recombinant protein manufacturing diversification into lipid nanoparticle delivery systems. Backward integration into captive lipid production capacity in Basel or Boston clusters reduces dependency on South Korean and Japanese specialty chemical suppliers. Certification investment in WHO prequalification pathway alignment secures multilateral procurement leverage against emerging biotech entrants. For New Entrants and Emerging Players: Begin with thermostable formulation platforms eliminating 2-8°C cold-chain dependency, targeting last-mile access gaps in sub-Saharan Africa and tropical South Asian districts where passive cooling fails. Indonesia's expanding birth cohort under Health Law provisions offers the most penetrable geography for pentavalent and PCV volume entry. A go-to-market angle anchored in digital immunization registry integration enables demand-forecast precision at district level, differentiating from legacy suppliers lacking biometric patient tracking capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier conjugate chemistry specialists with validated polysaccharide-protein coupling platforms but limited WHO prequalification progress. Long-term viability over the next decade hinges on regulatory convergence between FDA Pediatric Research Equity Act and EMA extrapolation guidelines, which would eliminate parallel clinical investment burdens. The signal to watch is Gavi and UNICEF pilot tender structures for mRNA respiratory syncytial virus candidates, indicating platform shift velocity and procurement officer risk appetite for novel delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | UNICEF tender eligibility unlocks multilateral procurement volumes in Gavi-eligible countries. |
| Thermostable Formulation Development | Elimination of 2-8°C cold-chain dependency opens last-mile access in tropical climates without active refrigeration. |
| Digital Immunization Registry Integration | Biometric patient tracking with supply chain systems reduces wastage and enables demand-forecast precision. |
| Fill-Finish Capacity Expansion | Aseptic manufacturing suite validation in Maryland's I-270 corridor serves UNICEF tender surge requirements. |
| mRNA Platform Diversification | Lipid nanoparticle delivery system investment compresses antigen design cycles from years to months. |
Research Approach
Bottom-up immunization program modeling reconciled against top-down bulk antigen manufacturing tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at CDSCO and ANVISA, formulary directors at Brazil's Ministry of Health, and procurement officers at UNICEF Supply Division combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov pediatric trial records, and WHO prequalification databases. Triangulation across these sources ensures demand-side schedule adoption patterns align with supply-side manufacturing capacity expansion announcements.
Historical trendline analysis of national immunization schedule expansion rates and multilateral procurement tender volumes established baseline growth parameters across the projection horizon. The forecast framework segments by vaccine type (conjugate, live attenuated, inactivated, subunit, toxoid), technology platform (recombinant DNA, mRNA, viral vector, protein subunit, adjuvant-enhanced), application area, and end-user delivery site, with CAGRs derived from regression analysis of birth cohort expansion and vaccine penetration elasticity. Industry-specific inputs include CDSCO manufacturing license renewal timelines and Gavi disbursement commitment trajectories.
Several conditions sit outside the modeled scope, including sudden regulatory divergence between FDA and EMA pediatric extrapolation protocols, catastrophic cold-chain infrastructure failure in sub-Saharan Africa, and novel adjuvant safety signals triggering platform abandonment. Forecasts reflect assumptions about continued WHO prequalification pathway stability and aluminum adjuvant supply continuity. A small set of named triggers warrants ongoing watch: mRNA platform pediatric safety data readouts, EMA-CDSCO regulatory convergence announcements, and Gavi pilot tender structure publication for respiratory syncytial virus candidates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Finasteride Market