
 Pediatric Craniosynostosis Treatment Market | 2026-2036
Pediatric Craniosynostosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Craniosynostosis Treatment Market Outlook
Hospital procurement for pediatric neurosurgical devices is rewriting competitive access rules across developed markets. Johnson & Johnson leverages its broad orthopedic portfolio to sustain institutional contracts in academic medical centers. Medtronic anchors its position through deep integration with minimally invasive navigation platforms. KLS Martin Group specializes in cranio-maxillofacial instrumentation that competes on surgical precision.
Pediatric craniosynostosis treatment encompasses surgical and non-surgical interventions to correct premature fusion of cranial sutures in developing children, typically involving calvarial vault remodeling with biocompatible plating systems or endoscopic strip craniectomy with postoperative helmet therapy. Endoscopic surgery leads procedural volume growth due to reduced operative time and blood loss in infants under six months. Open surgery occupies the largest revenue share given complex reconstructive cases requiring cranial vault expansion. Cranial helmet therapy extends post-surgical correction demand through outpatient channels with recurring replacement cycles.
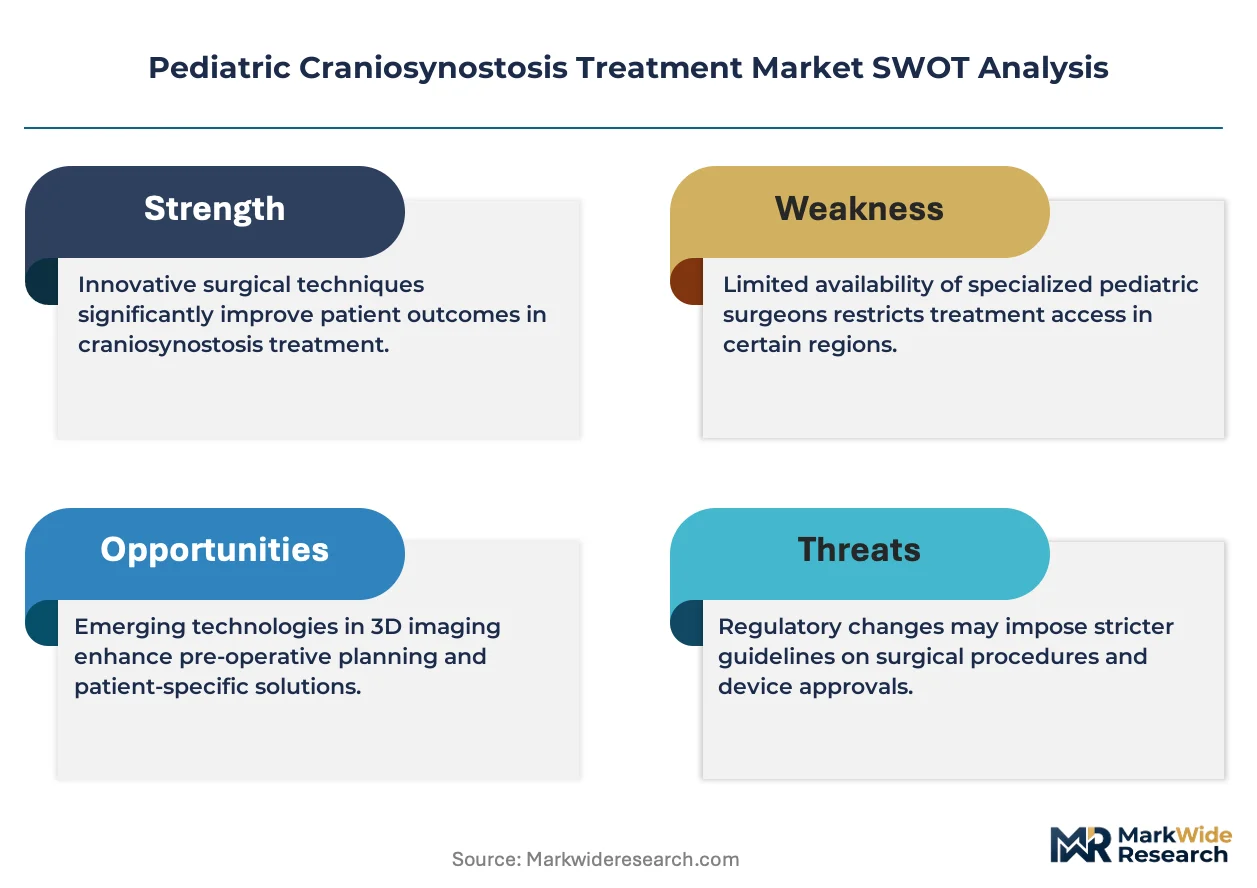
FDA 510(k) premarket notification requirements govern cranial remodeling device approvals in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for pediatric implantable devices under CE marking obligations. Health Canada and Japan's PMDA maintain parallel review frameworks that shape multinational launch sequencing for device manufacturers. Stakeholders must monitor evolving reimbursement thresholds for minimally invasive procedures against open surgery benchmarks as payers recalibrate coverage policies.
Market Dynamics
Minimally invasive endoscopic strip craniectomy is compressing the surgical protocol landscape as pediatric neurosurgical centers abandon open vault remodeling for infants under six months, triggering cascading demand for postoperative cranial helmet therapy and reshaping procurement patterns for biocompatible plating systems.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for cranial remodeling devices reduces time-to-market for manufacturers targeting United States pediatric hospitals.
- Helmet Therapy Protocol Standardization:Post-surgical cranial orthotic programs extend treatment revenue cycles through outpatient channels with scheduled replacement intervals.
- Japan PMDA Parallel Review:Synchronized regulatory frameworks with Health Canada enable coordinated multinational product launches for device manufacturers.
Market Restraints
- Titanium Alloy Input Volatility:Biocompatible plating system costs fluctuate with aerospace sector demand for surgical-grade titanium feedstock.
- EU MDR Clinical Evidence Burden:Stricter pediatric implantable device standards under CE marking obligations extend development timelines and inflate trial expenditures.
- Neurosurgeon Concentration Risk:Craniofacial surgical expertise clusters in academic medical centers across Germany, the United States, and Japan, limiting procedural access elsewhere.
Strategic Opportunities
- Brazil ANVISA Expansion:Underdeveloped referral networks for craniofacial centers present first-mover advantage for helmet therapy distributors establishing local partnerships.
- Digital Surgical Planning Convergence:Integration of patient-specific 3D modeling with intraoperative navigation platforms enables precision customization of calvarial reconstruction.
- India CDSCO Pediatric Device Incentives:Domestic manufacturing incentives for medical devices reduce import dependency and accelerate regional supply chain localization.
Industry Challenges
- Pediatric Neurosurgical Fellowship Scarcity:Extended training requirements for craniofacial specialization constrain hospital expansion of minimally invasive surgical programs.
- Multi-Site Helmet Fitting Coordination:Postoperative orthotic management requires alignment between surgical centers, orthotist networks, and insurance authorization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Craniosynostosis Treatment Market |
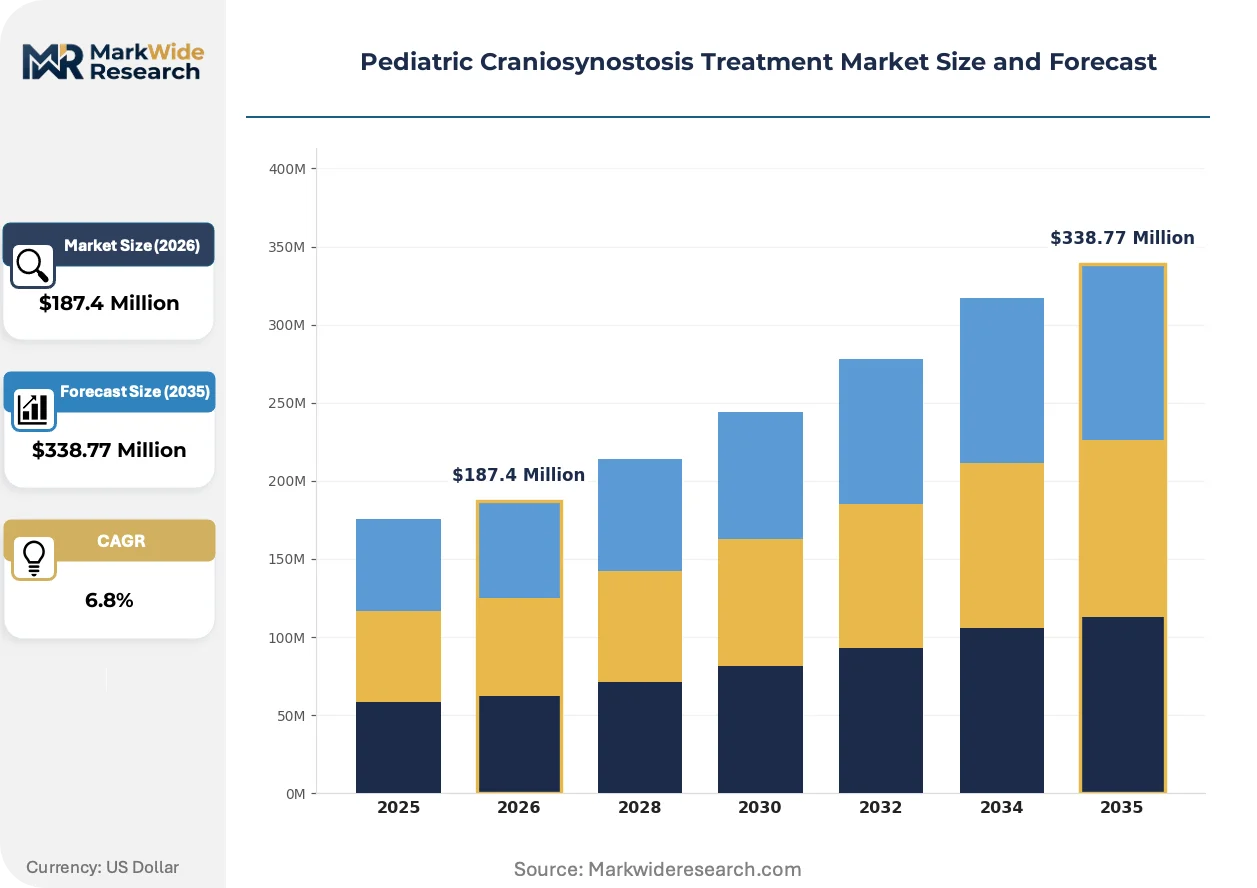
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Endoscopic Surgery, Open Surgery, Non-Surgical Treatment, Cranial Helmet Therapy Age Group: Infants, Toddlers, Children, Adolescents Procedure Type: Reconstructive Surgery, Minimally Invasive Surgery, Corrective Surgery, Diagnostic Procedures Healthcare Setting: Pediatric Hospitals, Specialty Clinics, Outpatient Facilities, Academic Medical Centers |
| Companies Covered | B. Braun Melsungen AG, Integra LifeSciences, Johnson & Johnson, Arthrex, NuVasive, Medtronic, KLS Martin Group, Cogentix Medical, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Craniosynostosis Treatment Market Strategic Shifts
Computational modeling and patient-specific instrumentation are compressing the traditional boundary between preoperative planning and intraoperative execution, forcing device manufacturers to embed software capabilities alongside hardware portfolios.
Virtual surgical planning platforms using three-dimensional cranial reconstruction algorithms are virtualizing the preoperative design phase for complex calvarial vault remodeling. Academic medical centers in Germany and the United States are adopting these systems at accelerating rates for cases involving multiple suture synostosis. This capability is virtualizing the traditional reliance on intraoperative improvisation, reducing operative time variability and standardizing outcomes across less experienced surgical teams.
The EU Medical Device Regulation's pediatric implantable device requirements are tightening clinical evidence standards for bioresorbable plating systems under CE marking obligations. Manufacturers must now submit extended follow-up data on cranial growth accommodation and long-term biocompatibility. Cranial remodeling device categories targeting syndromic synostosis cases face the steepest compliance burden, prompting some firms to sequence launches toward simpler single-suture indications first.
Hospital procurement departments are consolidating vendor contracts for cranio-maxillofacial instrumentation into multi-year enterprise agreements. Academic medical centers in the United States are displacing transactional purchasing with integrated supply partnerships that bundle devices, navigation platforms, and postoperative helmet therapy logistics. This pattern is most visible in craniofacial centers of excellence where surgical volume justifies dedicated supply chain personnel.
Pediatric Craniosynostosis Treatment Market Segmentation
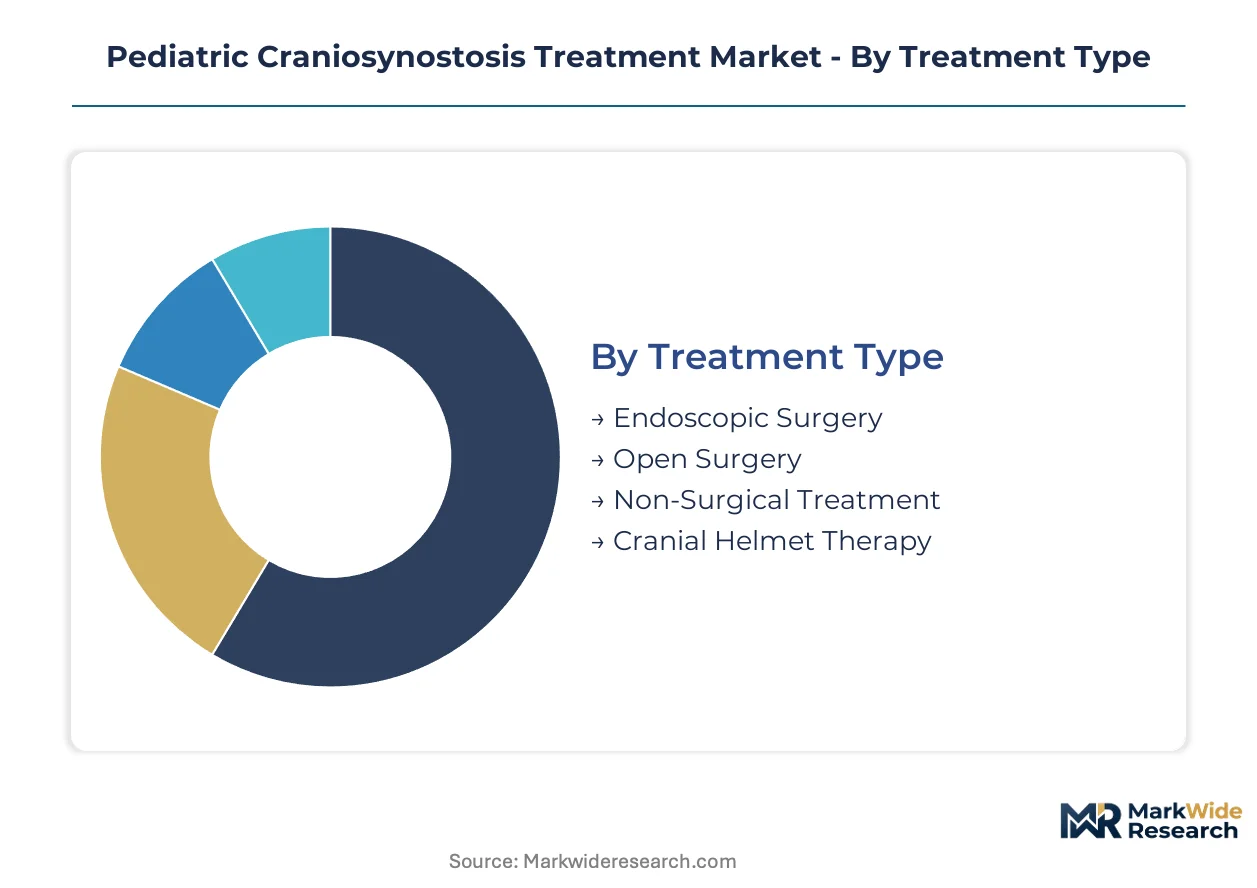
Pediatric craniosynostosis treatment segments diverge sharply in capital intensity and replacement velocity. Surgical modalities demand heavy fixed investment in navigation platforms and plating inventory. Postoperative orthotic services operate on compressed refresh cycles that reshape working capital requirements.
Treatment Type:
Cycle times range from single-episode surgical interventions to multi-year helmet replacement programs, creating divergent revenue recognition patterns across the care continuum.
- Open Surgery:Calvarial vault remodeling with titanium or bioresorbable plating systems addresses complex multi-suture synostosis. Demand clusters in academic medical centers across the United States and Germany where craniofacial surgical volume justifies dedicated operating room allocation and specialized anesthesia teams.
- Cranial Helmet Therapy:Postoperative cranial orthotic management follows endoscopic strip craniectomy with scheduled replacement intervals every 2-3 months during active growth phases. Outpatient orthotist networks in Japan and the United States capture recurring revenue through insurance-authorized fitting protocols.
- Endoscopic Surgery:Minimally invasive strip craniectomy for infants under six months reduces operative time and transfusion requirements.
- Non-Surgical Treatment:Positional molding protocols and observation for mild deformational plagiocephaly.
Open surgery dominates installed base. Cranial helmet therapy is where expansion concentrates.
Age Group:
Clinical presentation timing dictates both procedural eligibility and reimbursement pathway complexity across developmental stages.
- Infants:Patients under six months represent the optimal window for endoscopic intervention before cranial rigidity progresses. United States pediatric hospitals prioritize early detection through neonatal screening protocols to capture candidates for minimally invasive protocols.
- Toddlers:Children aged 1-3 years typically present with established cranial deformity requiring open vault remodeling. German craniofacial centers manage high procedural volume for this cohort through centralized referral networks from primary pediatricians.
- Children:Patients aged 3-12 years require complex revision surgery for recurrent synostosis or syndromic cases.
- Adolescents:Teenage patients present with late-diagnosed single-suture synostosis or psychological distress from residual cranial asymmetry.
Infants dominate installed base. Toddlers is where expansion concentrates.
Procedure Type:
Reimbursement calibration varies sharply between definitive reconstruction and diagnostic workup, shaping hospital margin profiles.
- Reconstructive Surgery:Definitive calvarial vault expansion with osteotomy and rigid fixation addresses severe cranial deformity. Academic medical centers in the United States bundle these procedures with intensive care unit stays and blood conservation protocols.
- Minimally Invasive Surgery:Endoscopic strip craniectomy with postoperative helmet management compresses total episode cost. Japanese pediatric neurosurgical units are expanding capacity for these procedures to reduce length of stay.
- Corrective Surgery:Revision procedures address residual deformity or complications from prior intervention.
- Diagnostic Procedures:CT imaging and cranial index measurement confirm suture fusion status.
Reconstructive surgery dominates installed base. Minimally invasive surgery is climbing the fastest.
Healthcare Setting:
Capital requirements and regulatory burden stratify sharply between high-acuity inpatient facilities and ambulatory service lines.
- Pediatric Hospitals:Dedicated children's hospitals maintain comprehensive craniofacial programs with embedded neurosurgery, plastic surgery, and orthotics. United States freestanding pediatric hospitals capture the highest procedural volume through bundled care contracts.
- Academic Medical Centers:University-affiliated hospitals combine clinical service with fellowship training and research protocols. German academic centers anchor regional referral networks through integrated virtual surgical planning capabilities.
- Specialty Clinics:Craniofacial-focused outpatient facilities concentrate on preoperative evaluation and postoperative helmet fitting.
- Outpatient Facilities:Ambulatory surgery centers perform select endoscopic procedures with same-day discharge protocols.
Pediatric hospitals dominate installed base. Academic medical centers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in pediatric craniosynostosis treatment concentrates in the United States and Germany, where bundled reimbursement contracts command premium rates, while Japanese hospitals negotiate tighter margins despite comparable procedural volumes.
United States
FDA 510(k) premarket notification pathways accelerate cranial remodeling device commercialization for manufacturers targeting pediatric hospitals. Academic medical centers in Boston and Philadelphia anchor regional referral networks for complex craniofacial reconstruction. Freestanding children's hospitals in Texas and California capture the highest endoscopic surgery volumes through early neonatal screening protocols.
Germany
EU MDR clinical evidence requirements under CE marking obligations extend development timelines for bioresorbable plating systems targeting syndromic synostosis cases. Craniofacial centers of excellence in Munich and Hamburg integrate virtual surgical planning platforms with intraoperative navigation. North Rhine-Westphalia hosts the densest concentration of pediatric neurosurgical fellowship training programs in Europe.
Japan
PMDA parallel review frameworks with Health Canada enable synchronized multinational launches for helmet therapy device manufacturers. Tokyo and Osaka pediatric hospitals are expanding minimally invasive surgical capacity to reduce length of stay metrics. METI incentives for digital health adoption accelerate patient-specific 3D modeling integration in academic centers.
Brazil
ANVISA regulatory pathways for imported medical devices create first-mover advantages for helmet therapy distributors establishing local orthotist partnerships. São Paulo and Rio de Janeiro craniofacial centers remain underdeveloped relative to patient prevalence, constraining procedural access. Domestic manufacturing incentives under industrial policy frameworks remain nascent for pediatric implantable devices.
India
CDSCO pediatric device incentives and PLI scheme benefits reduce import dependency for biocompatible plating feedstock. Maharashtra and Karnataka host emerging craniofacial surgical programs in Mumbai and Bangalore private hospital networks. Referral fragmentation across state-level health systems delays diagnosis for infants eligible for endoscopic intervention windows.
Pediatric Craniosynostosis Treatment Market Competitive Environment
Diversified medical technology conglomerates and specialized cranio-maxillofacial instrument manufacturers split the market along capital intensity vectors. Johnson & Johnson leverages broad orthopedic portfolios to sustain multi-year enterprise contracts in academic medical centers. Medtronic anchors positioning through navigation platform integration with minimally invasive surgical workflows. KLS Martin Group competes on surgical precision in complex reconstructive cases. Dominant competitive moves include strategic partnerships bundling devices with postoperative helmet therapy logistics, and portfolio diversification into patient-specific 3D modeling software capabilities.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic occupy positions exemplifying scale-driven supply chain integration with hospital procurement departments. Stryker Corporation represents the archetype of navigation platform anchoring for minimally invasive procedural expansion. Within the specialized instrumentation tier, KLS Martin Group and Integra LifeSciences exemplify precision-focused competitive positioning against commoditized plating alternatives. B. Braun Melsungen AG sits within the European manufacturing anchor archetype, leveraging regional regulatory familiarity for CE marking compliance acceleration.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Integra LifeSciences |
| Johnson & Johnson |
| Arthrex |
| NuVasive |
| Medtronic |
| KLS Martin Group |
| Cogentix Medical |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's surgical instrumentation cluster feeds German academic medical centers with patient-specific plating systems, translating localized manufacturing scale into premium pricing power for complex craniofacial reconstruction cases. Titanium alloy feedstock volatility from aerospace sector competition compresses margins on standard bioresorbable implants while configured-to-order patient-matched devices sustain markup resilience.
Pricing Analysis
Configured-to-order patient-matched plating systems command 40-60% premiums over standard catalog configurations in syndromic synostosis cases. Three-tier pricing structure across premium patient-specific, standard modular, and economy off-the-shelf levels stratifies by surgical complexity and reimbursement pathway. Pricing pressure stems from hospital procurement consolidation into multi-year enterprise agreements bundling devices with navigation platforms. Academic medical centers exhibit lowest price sensitivity due to bundled care contracts, while outpatient orthotist networks face highest sensitivity from insurance authorization friction.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for titanium alloy feedstock procurement in the United States and Germany. Surgical-grade titanium concentrates in United States, German, and Japanese specialty alloy foundries. Bioresorbable polymer resins and patient-specific 3D printing hardware constitute critical input dependencies. Single-source vulnerability persists for electron beam melting equipment servicing patient-matched device production. Distribution runs through hospital procurement departments and GPO contracts in developed markets, with direct manufacturer-to-clinic relationships emerging in helmet therapy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway acceleration and EU MDR clinical evidence tightening create divergent regulatory arbitrage opportunities, positioning nimble manufacturers to capture share by sequencing launches across jurisdiction maturity curves.
For Market Incumbents: Harden enterprise contract renewals through embedded navigation platform integration and virtual surgical planning software bundling. Deepen backward integration into titanium alloy feedstock to offset aerospace sector demand spikes. Prioritize CE marking compliance investment ahead of EU MDR pediatric implantable device enforcement waves.
For New Entrants and Emerging Players: Build out helmet therapy distribution partnerships in São Paulo and Rio de Janeiro ahead of ANVISA regulatory maturation. Target Brazil's underdeveloped craniofacial referral networks through local orthotist training programs. Pursue software companion development for patient-specific 3D modeling as differentiated entry vector.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors patient-specific instrumentation specialists with FDA 510(k) clearance portfolios and Health Canada parallel review capabilities. Five-to-ten year viability hinges on reimbursement strategy execution for minimally invasive procedures. Monitor PMDA digital health adoption incentives as signal for Japanese market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification efficiency captures early-mover advantage in United States pediatric hospital procurement cycles. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation defends market access against stricter pediatric implantable device standards. |
| Hospital System Partnership | Bundled care contracts with academic medical centers lock in multi-year device and navigation platform revenue streams. |
| Software Companion Development | Patient-specific 3D modeling integration differentiates hardware portfolios in virtual surgical planning adoption. |
| Reimbursement Strategy | Minimally invasive procedure coverage expansion determines endoscopic surgery volume growth trajectory. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with pediatric neurosurgeons, craniofacial surgeons, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated with top-down market sizing across treatment type, age group, and healthcare setting segmentation.
Forecast inputs incorporated surgical protocol adoption curves, regulatory pathway timelines, and reimbursement policy trajectories across the projection horizon. Modeled dimensions span treatment modality, patient age cohort, procedure complexity tier, and regional regulatory cluster. CAGRs derived from volume-price elasticity modeling and installed base replacement velocity analysis. Helmet therapy replacement cycle frequency and minimally invasive surgical capacity expansion rates served as industry-specific forecast anchors.
Practitioners should monitor FDA guidance document revisions, EU MDR notified body capacity constraints, and titanium alloy spot price movements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatrics Medicine Market