
 Pediatric Catheter Market | 2026-2036
Pediatric Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Catheter Market Analytics
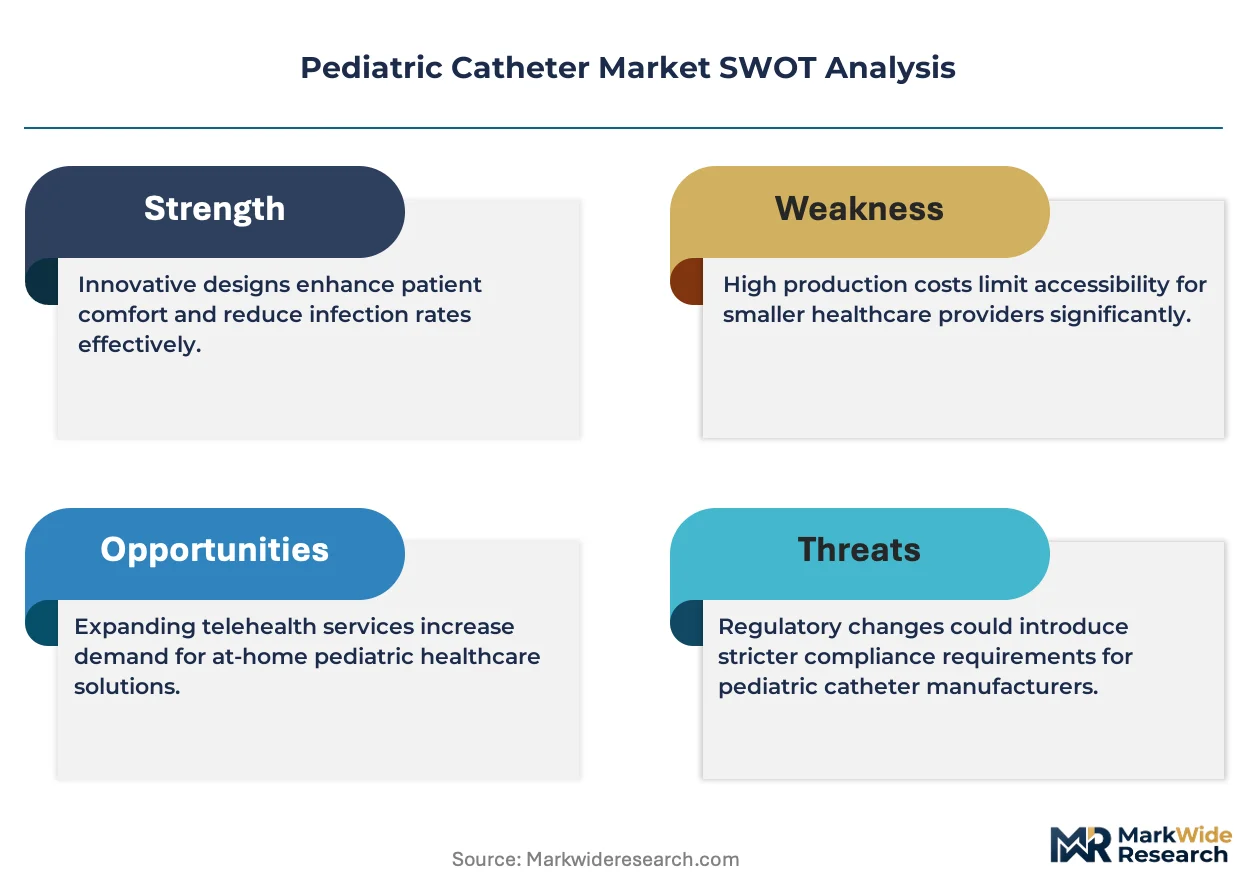
ISO 13485 certification is rotating the competitive set by filtering out suppliers lacking quality management systems for medical device production. Boston Scientific leverages its vertically integrated silicone supply chain to sustain pediatric-specific catheter portfolios. Medtronic anchors its position through R&D intensity in minimally invasive delivery systems for neonatal applications. BD competes on manufacturing scale across multiple material platforms including hydrogel-coated and pure silicone constructions.
Pediatric catheters are slender, flexible tubes manufactured from biocompatible materials such as medical-grade silicone or hydrogel-coated latex, designed for fluid drainage or medication delivery in patients from neonates through adolescents. These devices must meet strict French size specifications and kink-resistance parameters to accommodate anatomical constraints in developing patients. Foley catheters dominate current revenue pools due to indwelling requirements in post-surgical and critical care settings, while intermittent catheters represent the fastest-expanding segment as homecare protocols shift toward clean intermittent catheterization. Hydrogel-coated materials command premium positioning by reducing urethral trauma and infection risk compared to standard PVC alternatives.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments shape product development timelines and market access for pediatric catheter manufacturers. The EPA's oversight of phthalate content in PVC medical devices further constrains material selection, pushing suppliers toward silicone and thermoplastic elastomer alternatives. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement policy shifts in major pediatric procedure markets to align portfolio investments with regulatory and payment trajectories.
Market Dynamics
Neonatal intensive care units in tertiary pediatric hospitals are expanding catheter utilization for minimally invasive procedures, while FDA and EMA biocompatibility requirements for silicone-based devices tighten material specifications across manufacturing pipelines.
Growth Catalysts
- Neonatal ICU expansion:Tertiary pediatric hospitals in the United States, Germany, and Japan are scaling minimally invasive catheter procedures for premature infants, driving volume concentration in markets with established reimbursement frameworks.
- EMA MDR conformity pathways:The Medical Device Regulation's pediatric-specific classification requirements are accelerating manufacturer investment in dedicated silicone catheter portfolios rather than adult device adaptations.
- Hydrogel coating adoption:Medical-grade hydrogel surface treatments are displacing standard PVC constructions in post-surgical settings by reducing urethral trauma and infection risk in developing patients.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone feedstock production clusters in Germany and Japan, exposing catheter manufacturers to input cost volatility and single-source dependency risks.
- EPA phthalate restrictions:The Environmental Protection Agency's oversight of phthalate content in PVC medical devices constrains material selection flexibility and forces costly formulation pivots.
- French size standardization limits:Anatomical constraints in neonates through adolescents require narrow diameter specifications that compress manufacturing tolerances and yield rates.
Strategic Opportunities
- Clean intermittent catheterization protocols:Homecare reimbursement expansion in Japan is creating white space for single-use hydrophilic-coated intermittent catheter systems outside institutional settings.
- ISO 13485 certification gaps:Suppliers lacking quality management systems for medical device production are rotating out of competitive sets, opening share capture potential for certified manufacturers.
- Thermoplastic elastomer convergence:Advanced TPE formulations combined with antimicrobial surface technologies are enabling next-generation kink-resistant constructions for adolescent applications.
Industry Challenges
- FDA 510(k) clearance timelines:Pediatric-specific biocompatibility testing requirements extend regulatory review periods and compress product launch windows against adult device portfolios.
- Specialized molding capability scarcity:Thin-wall silicone extrusion expertise for French size 6-12 specifications concentrates among a limited supplier base, constraining manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Catheter Market |
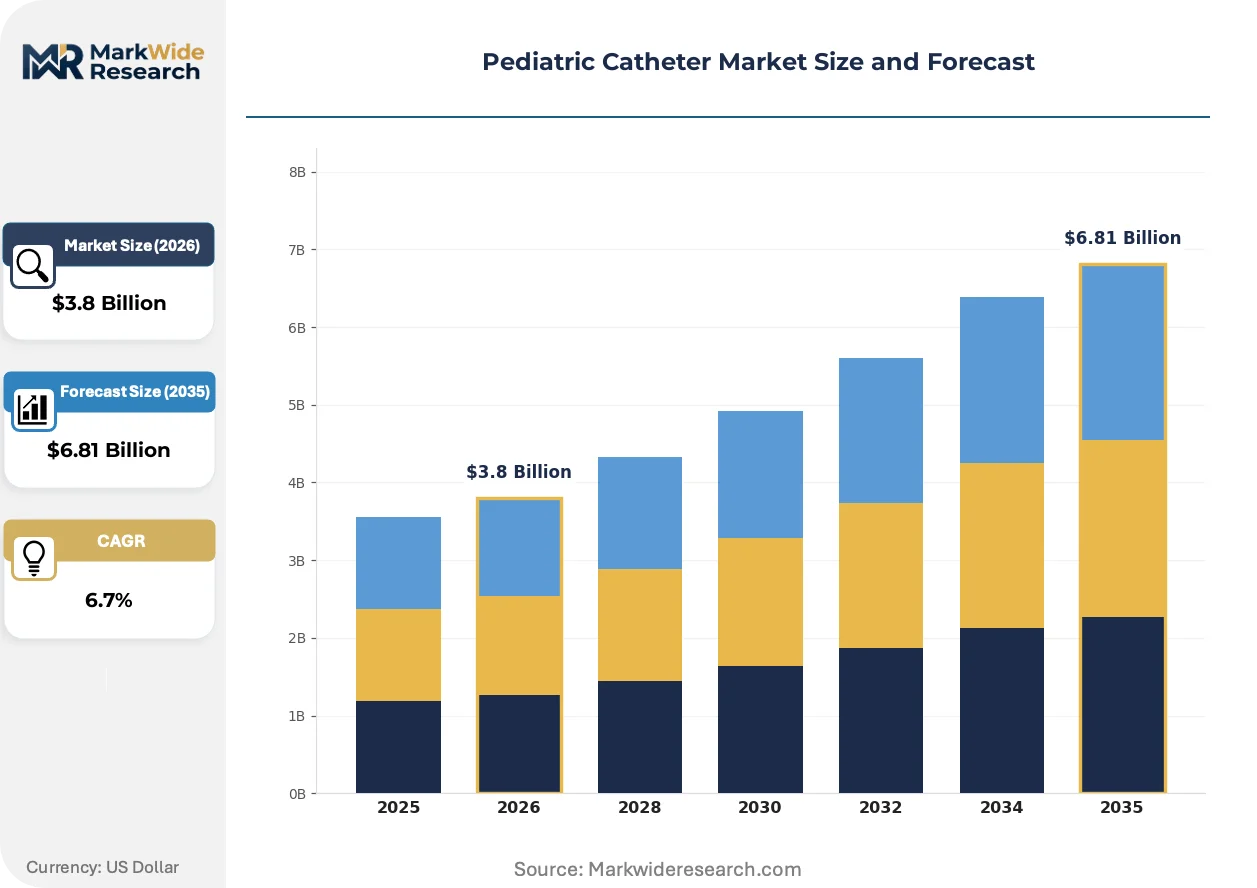
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foley Catheters, Intermittent Catheters, Suprapubic Catheters, Condom Catheters End User: Pediatrics Hospitals, Outpatient Clinics, Homecare Settings, Specialty Clinics Material: Latex, Silicone, PVC, Hydrogel Application: Urinary Incontinence, Urinary Retention, Surgical Procedures, Diagnostic Procedures |
| Companies Covered | Boston Scientific Corporation, Medtronic, BD, Johnson & Johnson Private Limited, Cook, Edwards Lifesciences Corporation, Cardinal Health, B. Braun Melsungen AG, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Catheter Market Evolving Landscape
Catheter design is converging on anatomical precision for developing patients, with material science and regulatory science advancing in parallel to enable safer indwelling and intermittent applications across neonatal through adolescent age bands.
Micro-lumen silicone extrusion technology is miniaturizing. This construction enables multi-channel fluid management within sub-3mm outer diameters for premature neonates. Level III NICUs in the United States and Germany are adopting these configurations for parenteral nutrition and medication delivery simultaneously. The technology is compressing the viable diameter threshold for multi-functional catheters while maintaining kink-resistance parameters.
REACH substance restrictions are reshaping European material pipelines. The European Chemicals Agency's candidate list updates are pressuring manufacturers to eliminate certain plasticizers and stabilizers from pediatric device constructions. German and Swiss catheter suppliers are accelerating silicone and TPE transitions ahead of sunset dates. Hydrogel-coated intermittent catheter segments face reformulation timelines to maintain CE marking validity.
Hospital procurement committees are consolidating supplier relationships around ISO 13485-certified manufacturers with dedicated pediatric quality systems. Group purchasing organizations in the United States are narrowing approved vendor lists to those with vertical silicone supply chain control. Pediatric specialist hospitals in Japan are following similar concentration patterns, privileging suppliers with in-house polymer compounding capabilities and documented biocompatibility traceability.
Pediatric Catheter Market Segmentation
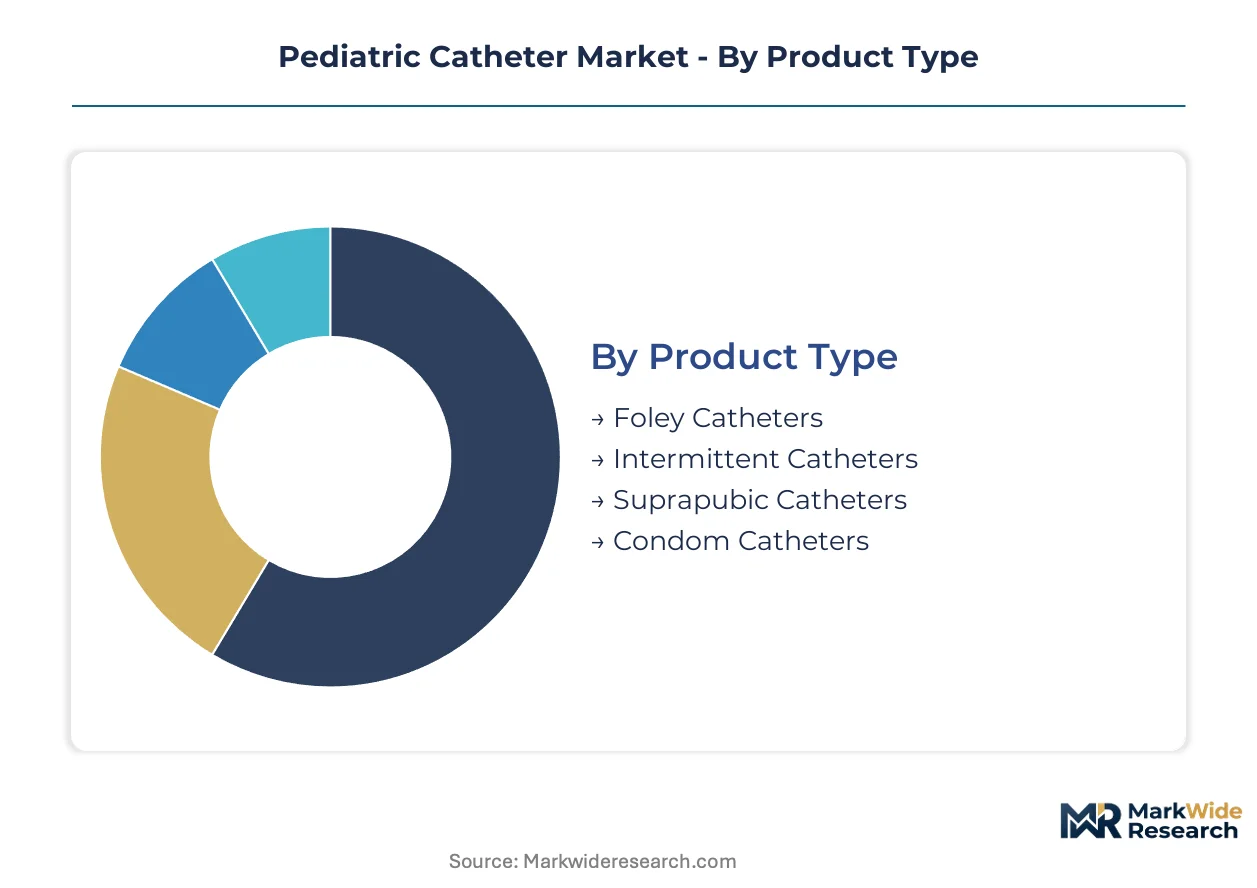
Pediatric catheter purchasing splits sharply between institutional procurement committees and homecare reimbursement pathways. Material specifications and French size constraints further fragment supplier positioning across neonatal through adolescent age bands.
Product Type:
Foley catheters face substitution pressure from intermittent alternatives as clean catheterization protocols expand reimbursement coverage.
- Foley Catheters:Indwelling silicone constructions with balloon retention mechanisms dominate post-surgical and critical care volumes. Tertiary pediatric hospitals in the United States and Germany concentrate demand for multi-lumen configurations supporting simultaneous drainage and irrigation.
- Intermittent Catheters:Single-use hydrophilic-coated systems enable patient-directed catheterization outside institutional settings. Japan's homecare reimbursement expansion is accelerating volume shift toward disposable intermittent formats.
- Suprapubic Catheters:Percutaneous insertion systems for patients with urethral trauma or congenital anomalies.
- Condom Catheters:External collection devices for adolescent males with functional incontinence.
Foley catheters anchor the volume base while intermittent catheters gain share at the steepest rate.
End User:
Procurement authority concentrates differently across settings, with hospital committees prioritizing supply security and homecare channels prioritizing unit economics.
- Pediatrics Hospitals:Level III NICUs and tertiary pediatric centers drive specification intensity for French size 6-12 micro-lumen constructions. FDA 510(k) clearance documentation and biocompatibility traceability determine vendor qualification.
- Outpatient Clinics:Intermittent catheter dispensing for clean catheterization training and urology follow-up.
- Homecare Settings:Patient-directed purchasing through durable medical equipment suppliers. Japanese reimbursement codes for clean intermittent catheterization are expanding eligible patient populations.
- Specialty Clinics:Pediatric urology and nephrology practices prescribing condition-specific catheter formats.
Pediatrics hospitals concentrate the highest-specification demand while homecare settings expand the addressable patient base most rapidly.
Material:
Regulatory pressure on plasticizer chemistry is compressing PVC viability and accelerating silicone and hydrogel transitions.
- Silicone:Medical-grade platinum-cured formulations deliver kink resistance and biocompatibility for indwelling applications. German and Japanese feedstock concentration exposes manufacturers to input cost volatility.
- Hydrogel:Surface-coated constructions reduce urethral trauma and infection risk in developing patients. EMA MDR substance restrictions are forcing reformulation timelines for CE marking maintenance.
- Latex:Declining share due to allergy risk and alternative material performance improvements.
- PVC:Phthalate-dependent constructions facing EPA oversight constraints and hospital procurement exclusion.
Silicone anchors the premium tier while hydrogel coatings climb the fastest as infection prevention protocols tighten.
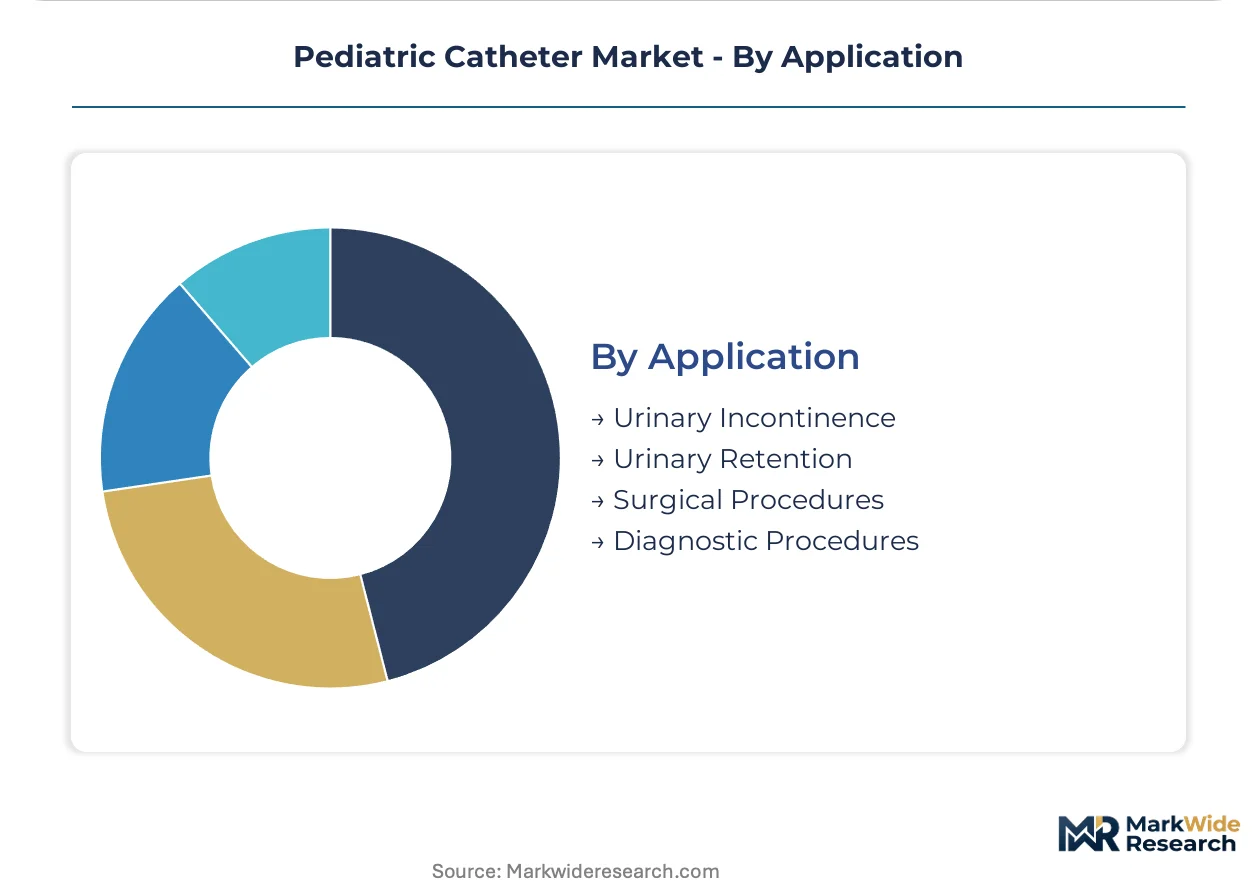
Application:
Procedure reimbursement codes and clinical pathway standardization determine volume allocation across diagnostic and therapeutic indications.
- Urinary Retention:Post-surgical and neurogenic bladder management drives Foley catheter utilization. Tertiary pediatric hospitals in Germany and the United States concentrate volume for congenital anomaly correction procedures.
- Surgical Procedures:Perioperative drainage requirements specify French size compatibility and multi-lumen functionality. Minimally invasive surgery expansion in Level III NICUs is multiplying catheter touchpoints per admission.
- Urinary Incontinence:Functional and structural incontinence management across outpatient and homecare channels.
- Diagnostic Procedures:Urodynamic studies and imaging requiring temporary catheterization.
Urinary retention anchors the procedure volume base while surgical applications expand most quickly through NICU minimally invasive adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for high-specification pediatric catheters, while reimbursement frameworks in these markets determine volume allocation across institutional and homecare channels.
United States
Level III NICUs in tertiary pediatric hospitals drive demand for French size 6-12 micro-lumen configurations supporting minimally invasive procedures. FDA 510(k) clearance pathways and biocompatibility documentation requirements determine vendor qualification for silicone-based indwelling devices. Boston and Minneapolis anchor medical device clusters where catheter manufacturers maintain R&D facilities and regulatory affairs operations.
Germany
Specialty silicone feedstock production concentrates in industrial zones around Munich and Leverkusen, exposing catheter manufacturers to input cost volatility and single-source dependency risks. EMA MDR conformity assessments and REACH substance restrictions accelerate material transitions away from phthalate-dependent PVC constructions. Tübingen and Heidelberg pediatric university hospitals set specification standards for multi-lumen Foley configurations across European procurement networks.
Japan
Homecare reimbursement expansion for clean intermittent catheterization protocols is shifting volume toward disposable hydrophilic-coated systems outside institutional settings. METI industrial standards and PMDA medical device approvals shape product development timelines for neonatal applications. Osaka and Tokyo medical device districts host manufacturers with in-house polymer compounding capabilities and documented biocompatibility traceability.
United Kingdom
NHS procurement frameworks concentrate purchasing authority for pediatric urology and nephrology catheter formats through specialized hospital trusts. MHRA post-Brexit regulatory alignment with EMA MDR requirements extends conformity assessment timelines for silicone-based device portfolios. Cambridge and Oxford medical research clusters influence clinical pathway standardization for intermittent catheterization training programs.
Switzerland
Swissmedic medical device regulations and ISO 13485 certification requirements filter supplier participation in pediatric catheter procurement for university hospitals in Zurich and Geneva. Precision molding expertise for thin-wall silicone extrusion concentrates among specialized manufacturers serving French size specifications for neonatal applications. Basel's pharmaceutical-industrial complex provides adjacent polymer science capabilities supporting material innovation.
Pediatric Catheter Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with vertically integrated silicone supply chains and specialized catheter manufacturers with ISO 13485-certified quality systems. Market structure concentrates around three strategic archetypes: integrated multinationals with captive polymer production, mid-scale specialists with dedicated pediatric portfolios, and regional fabricators competing on manufacturing scale. Dominant competitive moves include backward integration into medical-grade silicone feedstock and geographic expansion through distributor partnerships in Japanese homecare channels.
Within the integrated multinational tier, Boston Scientific Corporation and Medtronic exemplify archetypes with upstream control over polymer supply chains and regulatory affairs infrastructure spanning FDA and EMA jurisdictions. BD occupies a position representing manufacturing scale across multiple material platforms. These three entities anchor the competitive set that hospital procurement committees and group purchasing organizations privilege for supply security and biocompatibility traceability.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| BD |
| Johnson & Johnson Private Limited |
| Cook |
| Edwards Lifesciences Corporation |
| Cardinal Health |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Thin-wall silicone extrusion capacity utilization above 80% in German and Japanese feedstock clusters compresses manufacturing yield rates and elevates price floors for French size 6-12 specifications. Hospital procurement committees in the United States leverage volume concentration to extract cost concessions from suppliers lacking backward integration into medical-grade polymer production.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement between catheter manufacturers and tertiary pediatric hospitals. Three-tier pricing structure across platinum-cured silicone, hydrogel-coated, and standard PVC constructions differentiates by biocompatibility certification tier and kink-resistance performance. Cost compression in PVC tiers is intensifying because EPA phthalate restrictions force formulation pivots toward TPE alternatives. Homecare reimbursement channels in Japan exhibit highest price sensitivity due to patient-directed purchasing, while Level III NICUs in the United States demonstrate lowest sensitivity given supply security priorities.
Supply Chain Analysis
Six-month inventory buffers for specialty silicone feedstock reflect lead-time volatility from German and Japanese production clusters. Geographic supply concentration centers on Germany, Japan, and the United States for medical-grade polymer compounding and precision molding capabilities. Raw material dependencies rest on platinum-cured silicone, hydrogel surface coatings, and antimicrobial TPE formulations. Single-source vulnerability in Munich and Leverkusen feedstock exposes manufacturers to input cost spikes. Distribution runs through group purchasing organizations in the United States, specialized hospital trusts in Germany, and durable medical equipment suppliers in Japanese homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric catheter procurement authority is consolidating around ISO 13485-certified manufacturers with documented biocompatibility traceability, squeezing regional fabricators from approved vendor lists. Group purchasing organizations in the United States and specialized hospital trusts in Germany are narrowing supplier relationships to three or fewer qualified vendors per product category.
For Market Incumbents: Fortify supply security through captive silicone feedstock production or long-term offtake agreements with German and Japanese polymer suppliers. Hospital procurement committees are disqualifying vendors lacking vertical integration or documented REACH compliance, while EMA MDR conformity timelines compress competitive response windows. Priority investment in thin-wall extrusion capacity for French size 6-12 specifications defends share against mid-scale specialists. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for breakthrough device designation accelerate market access timelines against standard clearance routes. White-space concentration in Japanese homecare reimbursement expansion for clean intermittent catheterization protocols offers the most penetrable entry point. Target single-use hydrophilic-coated systems through distributor partnerships with durable medical equipment suppliers rather than direct hospital contracting. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with in-house polymer compounding capabilities and ISO 13485-certified quality systems over assembly-only operations. Long-term viability over a 5-10 year window hinges on regulatory science expertise spanning FDA and EMA jurisdictions. Acquisition target archetype: mid-scale specialists with dedicated pediatric portfolios and established silicone supply relationships. Signal to watch: REACH substance restriction sunset dates forcing material reformulation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | Captive polymer supply secures margin stability against German and Japanese input volatility. |
| FDA 510(k) Fast-Track Submission | Breakthrough device designation compresses regulatory review periods for neonatal micro-lumen configurations. |
| Hospital System Partnership | Preferred supplier status with Level III NICUs locks in multi-year volume commitments. |
| CE Marking Pathway Acceleration | EMA MDR conformity ahead of sunset dates maintains European market access. |
| Reimbursement Strategy Development | Japanese homecare code expansion for clean intermittent catheterization opens patient-directed channels. |
Research Methodology
A spread of perspectives from catheter manufacturing executives, hospital procurement managers, biomedical engineers, and GPO contracts specialists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type, end user setting, material composition, and application indication across the projection horizon. CAGRs were derived from procedure volume trajectories and unit price evolution assumptions. Industry-specific forecast inputs incorporated NICU admission trends, homecare reimbursement expansion timelines, and biocompatibility testing standard updates.
The analysis sits within stated boundaries; outcomes outside FDA clearance pathway stability or REACH substance restriction timelines would require recalibration. Forecasts reflect documented assumptions about silicone feedstock availability and pediatric specialist hospital infrastructure expansion. Specific risk factors including single-source polymer dependency and EMA MDR conformity delays could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Dental Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Asthma Treatment Market