
 IVD Infectious Disease Market | 2026-2036
IVD Infectious Disease Market Size, Share, and Industry Trends Forecast 2026-2036
IVD Infectious Disease Market Outlook
Multi-sourced reagent procurement is recalibrating how IVD infectious disease manufacturers manage supply security and cost predictability. Roche Diagnostics leverages captive enzyme production to insulate assay margins from raw material volatility. Abbott Laboratories anchors its competitive stance through vertically integrated immunoassay manufacturing across North American and European production nodes. bioMérieux SA specializes in culture-based microbiology consumables, occupying a defensible niche as molecular methods expand.
In vitro diagnostic infectious disease testing encompasses reagent-based analytical systems designed to detect pathogenic microorganisms or host immune responses in human clinical specimens, typically employing nucleic acid amplification, antigen-antibody binding, or microbial cultivation with turnaround times ranging from fifteen minutes to several days. Its primary commercial purpose is to enable therapeutic decision-making, infection control protocols, and public health surveillance through laboratory-accurate pathogen identification. Molecular diagnostics commands the fastest expansion trajectory among technology segments, driven by PCR and next-generation sequencing adoption for syndromic panels. Immunoassays sustain the largest installed base and recurring revenue pool, particularly in high-throughput hospital laboratories managing hepatitis and HIV screening volumes.
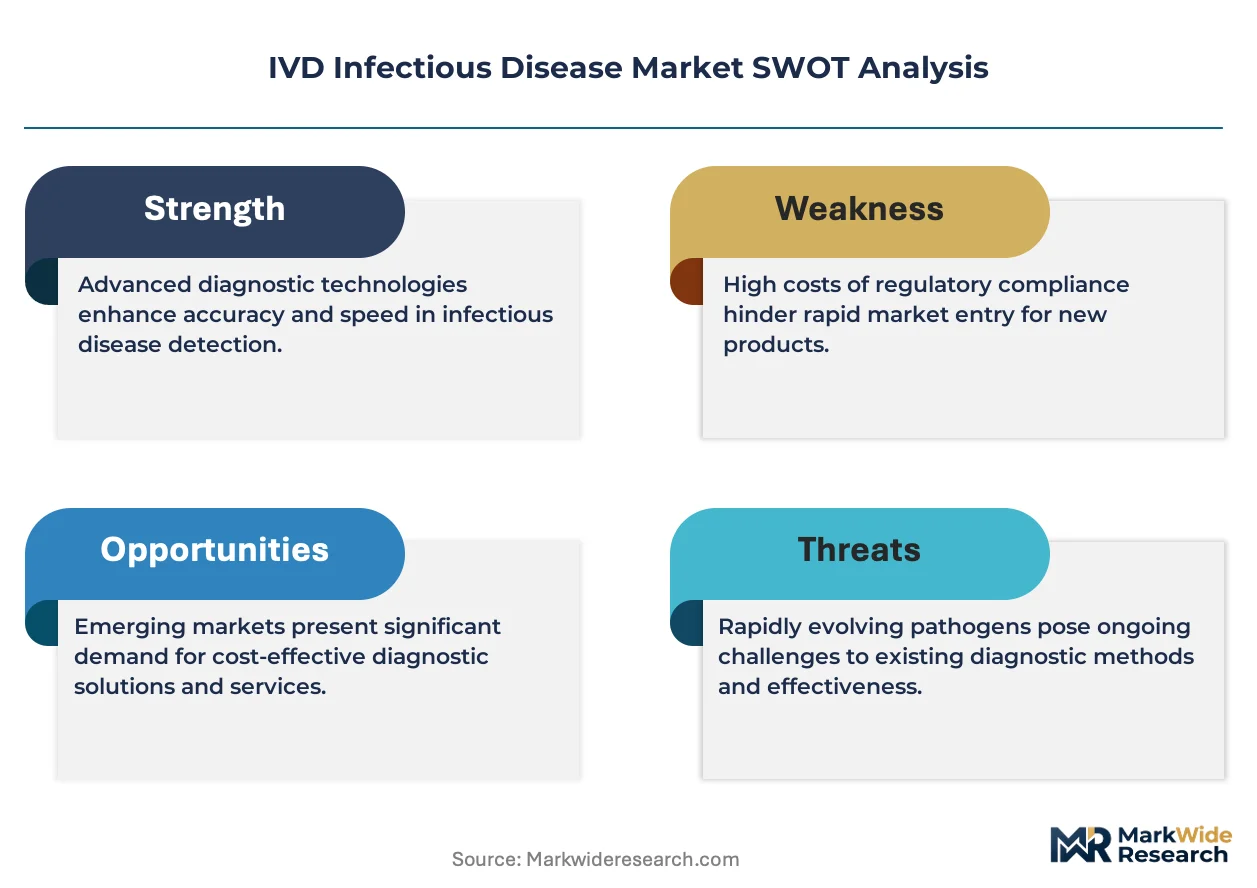
FDA premarket notification pathways under 510(k) and CLIA complexity categorization shape how assay developers design product claims and distribution channels for U.S. market entry. The EMA's In Vitro Diagnostic Medical Devices Regulation imposes new clinical evidence and post-market surveillance obligations across European Economic Area member states, elevating compliance costs for established and emerging manufacturers alike. Stakeholders must monitor how decentralized testing authorization and reimbursement parity between laboratory-developed tests and commercial kits reshape competitive boundaries across care settings.
Market Dynamics
Hospital laboratory consolidation is compressing vendor negotiation leverage while simultaneously elevating demand for syndromic multiplex panels that reduce time-to-diagnosis in emergency departments. This structural concentration reshapes how assay developers configure distribution channels and pricing architectures.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's evolving guidance on multiplex molecular diagnostic panels accelerates assay complexity expansion, enabling broader pathogen detection per test cycle.
- Emergency department throughput pressure:Hospital emergency departments demand pathogen identification within fifteen minutes to sixty minutes, pulling point-of-care molecular platforms into acute care settings.
- Next-generation sequencing adoption:Academic medical centers integrate NGS-based metagenomic surveillance for outbreak investigation and antimicrobial resistance monitoring.
Market Restraints
- Reagent supply concentration:Captive enzyme production capabilities concentrate among three multinational manufacturers, exposing mid-tier assay developers to raw material allocation risk.
- EMA MDR compliance burden:The In Vitro Diagnostic Medical Devices Regulation imposes new clinical evidence and post-market surveillance obligations, elevating fixed compliance costs disproportionately for smaller manufacturers.
- Culture-based method displacement limits:Antimicrobial susceptibility testing still requires viable organism isolation, preserving microbiology consumable demand despite molecular expansion.
Strategic Opportunities
- Decentralized testing authorization:CLIA-waived molecular platforms open pharmacy and urgent care channels previously inaccessible to laboratory-complex assays.
- Antimicrobial stewardship mandates:Hospital reimbursement penalties for healthcare-associated infections drive rapid diagnostic adoption to shorten empiric antibiotic duration.
- Home-based respiratory panel demand:Consumer-accessible influenza and SARS-CoV-2 combination tests expand addressable volume beyond traditional clinical settings.
Industry Challenges
- Bioinformatics talent scarcity:NGS panel interpretation requires computational biology expertise that outpaces current clinical laboratory training pipeline output.
- Legacy LIS integration friction:Hospital information systems built for discrete result reporting struggle with syndromic panel data structures, delaying implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVD Infectious Disease Market |
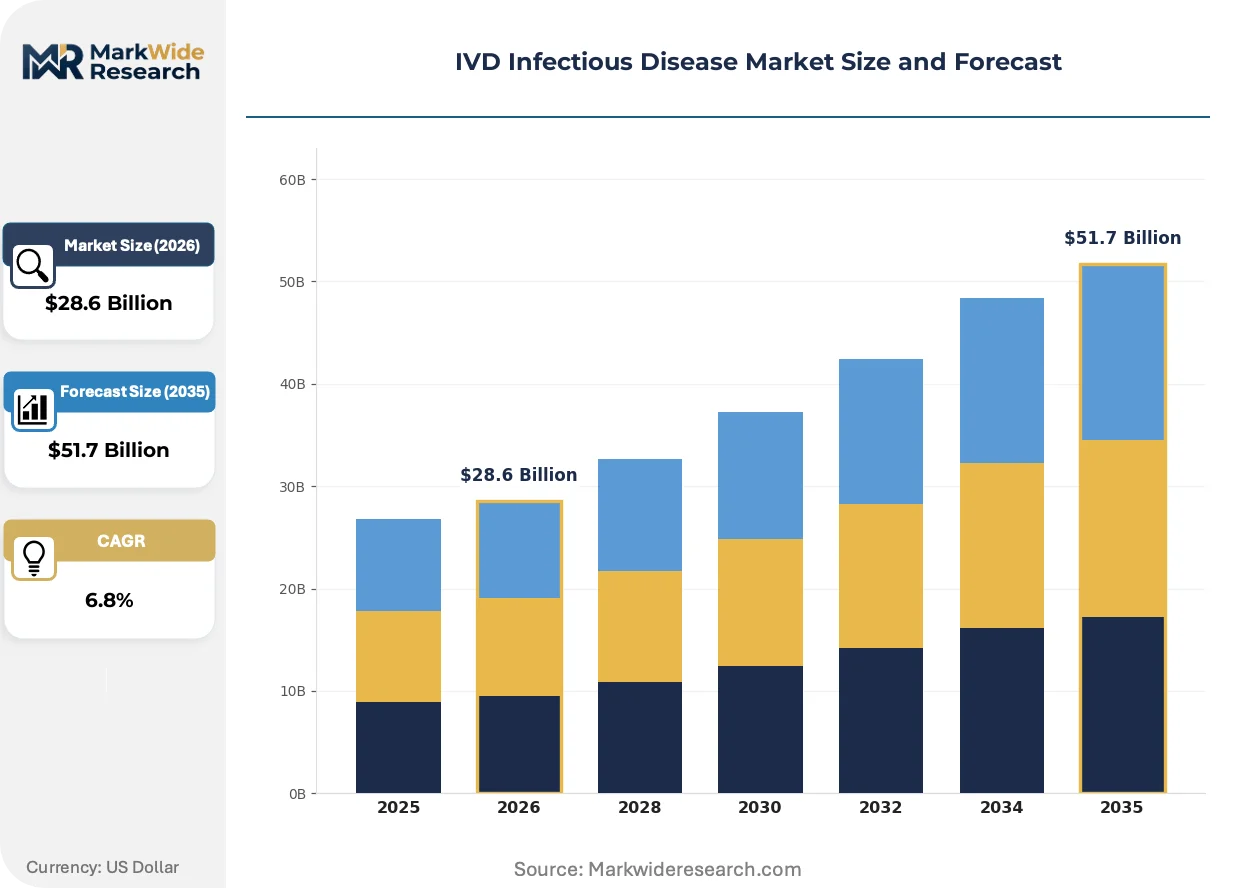
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Software End User: Hospitals, Laboratories, Clinics, Research Institutes Technology: Molecular Diagnostics, Immunoassays, Microbiology, Serology Application: HIV Testing, Hepatitis Screening, COVID-19 Detection, Tuberculosis Diagnosis |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers AG, bioMérieux SA, Becton Dickinson and Company, Danaher Corporation, QIAGEN, Bio-Rad Laboratories, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVD Infectious Disease Market Strategic Shifts
Multiplex molecular diagnostics is actively compressing the traditional sequential testing workflow, replacing culture-based and single-target methods with parallel pathogen detection. This technology convergence reshapes laboratory staffing models and capital allocation priorities.
Random-access molecular platforms is consolidating previously fragmented infectious disease testing into unified instrument footprints. Hospital laboratories adopt these systems to reduce specialized equipment count and consolidate maintenance contracts. The technology is consolidating vendor relationships by enabling hepatitis, HIV, and respiratory panels on identical hardware.
The EMA's In Vitro Diagnostic Medical Devices Regulation imposes stringent clinical performance documentation and post-market surveillance requirements. Manufacturers must generate prospective clinical evidence for novel biomarker claims, extending development timelines. European Economic Area member states apply divergent notified body interpretations, creating compliance fragmentation.
Buyers increasingly unbundle instrument placement from reagent supply commitments, compressing historical lock-in structures. Group purchasing organizations leverage consolidated hospital network volume to negotiate spot pricing on high-throughput hepatitis and HIV screening consumables. This pattern concentrates in the United States, where health system mergers have concentrated purchasing authority among fewer decision-makers.
IVD Infectious Disease Market Segmentation
IVD infectious disease testing fragments across four distinct dimensions that govern procurement patterns and margin architecture. Product type determines capital intensity and recurring revenue stability. Technology choice dictates regulatory pathway complexity and laboratory staffing requirements.
Product Type:
Supply concentration in critical raw materials reshapes how manufacturers configure their product portfolios and defend margin structures across consumable and hardware categories.
- Reagents:Enzyme and nucleotide formulations constitute the highest-margin recurring revenue stream, with captive production capabilities concentrated among three multinational suppliers. Hospital laboratories in the United States absorb the majority of high-throughput hepatitis and HIV screening volumes, driving multi-year supply contracts.
- Assays:Pre-configured test kits for specific pathogen targets require FDA 510(k) clearance or EMA MDR conformity assessment, elevating fixed development costs. Multiplex respiratory panels for emergency department syndromic testing are pulling assay demand toward broader pathogen detection per test cycle.
- Instruments:Random-access molecular platforms consolidate previously fragmented testing workflows into unified footprints.
- Software:Laboratory information system modules and bioinformatics pipelines for NGS interpretation face integration friction with legacy hospital IT infrastructure.
Reagents absorb the bulk of installed capacity; assays are expanding most quickly.
End User:
Customer type segmentation reveals divergent purchasing authority structures and decision-making timelines that reshape vendor sales force deployment.
- Hospitals:Consolidated health system networks in the United States leverage group purchasing organization contracts to compress reagent pricing on high-volume screening menus. Emergency departments demand fifteen-minute to sixty-minute turnaround times, pulling point-of-care molecular platforms into acute care settings.
- Laboratories:Independent and hospital-affiliated reference laboratories sustain the largest installed base of automated immunoassay analyzers for hepatitis and HIV serology.
- Clinics:CLIA-waived molecular authorization opens pharmacy and urgent care channels previously inaccessible to laboratory-complex assays.
- Research Institutes:Academic medical centers integrate NGS-based metagenomic surveillance for outbreak investigation and antimicrobial resistance monitoring.
Hospitals command the largest procurement volumes; clinics are climbing the fastest as decentralized testing authorization expands.
Technology:
Technology maturity and regulatory pathway differentiation segment the competitive landscape into distinct capability clusters with diverging investment requirements.
- Molecular Diagnostics:PCR and next-generation sequencing platforms command the steepest expansion trajectory, driven by syndromic panel adoption and antimicrobial stewardship mandates. The FDA's evolving guidance on multiplex molecular diagnostic panels accelerates assay complexity expansion.
- Immunoassays:Enzyme-linked and chemiluminescent methods sustain the largest installed base and recurring revenue pool in high-throughput hospital laboratories.
- Microbiology:Culture-based methods preserve defensible demand for antimicrobial susceptibility testing requiring viable organism isolation.
- Serology:Antibody detection formats face displacement pressure from nucleic acid amplification methods in acute infection diagnosis.
Immunoassays retain the dominant installed base; molecular diagnostics is gaining share fastest.
Application:
Disease-specific testing volumes concentrate in screening programs and outbreak response protocols that reshape demand seasonality and procurement timing.
- HIV Testing:Fourth-generation antigen-antibody combination assays dominate high-throughput screening workflows in United States hospital laboratories and public health reference centers.
- Hepatitis Screening:Automated immunoassay platforms process routine serology panels for HBV and HCV markers in consolidated laboratory networks.
- COVID-19 Detection:Molecular and rapid antigen platforms established distributed manufacturing capacity and CLIA-waived distribution channels now repurposing for respiratory panel expansion.
- Tuberculosis Diagnosis:Nucleic acid amplification tests for Mycobacterium tuberculosis complex are displacing sputum microscopy in high-burden settings.
Hepatitis screening absorbs the bulk of routine testing volume; COVID-19 detection infrastructure is repurposing most rapidly for broader respiratory applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme and nucleotide manufacturing clusters in Basel, Switzerland and Indianapolis, United States anchor the IVD infectious disease supply base. These raw material localities concentrate captive production capabilities that shape regional market formation. Demand patterns diverge sharply across national healthcare procurement structures.
United States
Hospital consolidation into mega-systems like HCA Healthcare and Kaiser Permanente compresses vendor pricing power through group purchasing organization contracts. FDA 510(k) pathway streamlining accelerates multiplex molecular panel approvals. The Research Triangle Park cluster in North Carolina concentrates diagnostic assay development operations for several multinational manufacturers.
Germany
Automotive supplier regions in Baden-Württemberg pivot engineering talent toward precision diagnostics instrumentation. EMA MDR implementation creates compliance bottlenecks at notified bodies in Berlin and Munich. The Mannheim-Ludwigshafen chemical corridor sustains reagent precursor manufacturing for European assay producers.
China
NMPA regulatory harmonization with international standards accelerates domestic molecular diagnostic platform approvals. Provincial centralized procurement in Guangdong and Jiangsu provinces drives price compression on hepatitis and HIV screening reagents. The Suzhou BioBAY cluster incubates local assay developers targeting respiratory panel markets.
Japan
PMDA's sakigake designation pathway fast-tracks novel infectious disease biomarkers into clinical validation. Aging demographics expand screening program volumes for tuberculosis and hepatitis C in urban prefectures. The Kobe biomedical innovation cluster houses automated immunoassay manufacturing operations serving Asia-Pacific distribution.
India
CDSCO's phased implementation of medical device rules elevates quality standards for imported assay kits. National viral hepatitis control program procurement concentrates demand in Maharashtra and Karnataka state reference laboratories. The Genome Valley cluster in Telangana attracts contract research organizations supporting antimicrobial resistance surveillance.
IVD Infectious Disease Market Competitive Environment
Global majors compete with regional champions across regulatory pathway expertise and raw material captive supply. The market structures around three tiers: vertically integrated multinational conglomerates, specialized microbiology consumable producers, and emerging molecular platform developers. Strategic differentiation clusters on syndromic panel breadth, turnaround time compression, and CLIA complexity tier access. Dominant competitive moves include backward integration into enzyme production and random-access platform consolidation.
Among Swiss-based diagnostics conglomerates, Roche Diagnostics anchors the vertically integrated archetype through captive reagent manufacturing. Abbott Laboratories exemplifies North American scale-driven positioning across immunoassay and molecular platforms. bioMérieux SA occupies the specialized microbiology niche as molecular methods expand.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers AG |
| bioMérieux SA |
| Becton Dickinson and Company |
| Danaher Corporation |
| QIAGEN |
| Bio-Rad Laboratories |
| Hologic |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) pathway streamlining gates qualified supply access for multiplex molecular diagnostic panels, with only manufacturers meeting CLIA-waived authorization standards commanding premium-tier pricing in hospital emergency departments. This regulatory filter compresses margins for mid-tier assay developers while elevating reagent pricing power among vertically integrated multinationals with captive enzyme production.
Pricing Analysis
Service bundling separates instrument placement contracts from standalone reagent supply agreements, with maintenance-inclusive packages commanding 15-20% premiums over unbundled consumable pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by CLIA complexity tier and turnaround time performance, with CLIA-waived molecular platforms capturing the premium band. Pricing pressure stems from group purchasing organization consolidation in United States health systems, compressing hepatitis and HIV screening reagent margins. Reference laboratories exhibit highest price sensitivity due to volume concentration and multi-vendor sourcing strategies, while academic medical centers demonstrate lowest sensitivity for NGS-based metagenomic surveillance capabilities.
Supply Chain Analysis
Reverse-logistics flows for random-access molecular platforms concentrate refurbishment and remanufacturing operations in Indianapolis, United States and Basel, Switzerland, extending instrument lifecycle value through certified pre-owned channel programs. Enzyme and nucleotide formulation capacity anchors in Switzerland, United States, and Germany, with nucleic acid amplification reagents drawing from these concentrated manufacturing nodes. Single-source vulnerability concentrates in Taq polymerase supply chains controlled by three multinational suppliers, exposing mid-tier developers to allocation risk during demand surges. Distribution runs through regional distribution centers serving consolidated hospital networks in the United States, with direct-to-laboratory fulfillment gaining share in European Economic Area markets facing EMA MDR compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVD infectious disease testing is consolidating around vertically integrated multinationals with captive raw material supply, as EMA MDR compliance costs and FDA 510(k) pathway complexity force smaller assay developers toward acquisition or exit.
For Market Incumbents: To counter CLIA-waived molecular platform entrants from emerging Asian manufacturers, Roche Diagnostics and Abbott Laboratories should deepen backward integration into nucleotide formulation capacity while locking multi-year exclusive supply contracts with consolidated United States health systems. Captive enzyme production and random-access platform consolidation represent the critical defensive levers for preserving margin architecture against modular, software-defined competitors. For New Entrants and Emerging Players: Direct-to-consumer respiratory panel distribution through pharmacy retail chains offers the most penetrable white-space channel, bypassing hospital laboratory procurement committees entirely. CLIA-waived molecular authorization for urgent care settings in United States metropolitan markets provides secondary entry point, with antimicrobial stewardship mandate alignment as the differentiated go-to-market angle against established hospital-focused incumbents. For Investors and Strategic Acquirers: FDA 510(k) clearance receipt for multiplex syndromic panels is the leading indicator that mid-tier molecular platform developers have achieved regulatory scalability for acquisition value. The five-to-ten year viability window favors targets with demonstrated CLIA-waived pathway execution and installed base conversion potential, with EMA MDR notified body designation acquisition as the critical inflection signal for European market access capability.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Molecular Authorization | Opens pharmacy and urgent care channels previously inaccessible to laboratory-complex assays. |
| Multiplex Panel FDA 510(k) Submission | Accelerates assay complexity expansion for broader pathogen detection per test cycle. |
| Captive Enzyme Production Expansion | Insulates assay margins from raw material allocation risk among concentrated suppliers. |
| Hospital System GPO Contract Lock-in | Secures multi-year reagent supply commitments against spot pricing pressure. |
| NGS Bioinformatics Pipeline Development | Addresses computational biology talent scarcity constraining metagenomic surveillance adoption. |
Study Parameters
Independent corroboration across hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at molecular diagnostic manufacturers underwrites the qualitative findings. Primary interviews with emergency department clinicians and reference laboratory operations heads combined with secondary validation from FDA 510(k) filings, EMA MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data establish demand-side parameters. Bottom-up instrument placement and reagent volume estimates triangulate against top-down market sizing from consolidated health system capital expenditure disclosures.
Comparable-period anchoring to pre-pandemic baseline utilization patterns and post-acute care normalization trajectories shaped the forecast window construction. Segmentation modeling across product type, technology platform, end-user setting, and disease application dimensions generates volume and value outputs across the projection horizon. CAGRs derive from instrument installed base conversion rates, reagent pull-through coefficients, and CLIA-waived authorization expansion curves, with antimicrobial stewardship mandate penetration and syndromic panel adoption velocity as primary infectious disease-specific forecast inputs.
The model holds under stable FDA 510(k) review timelines and EMA MDR notified body capacity; deviation in regulatory pathway delays or raw material allocation crises would shift reagent pricing and competitive positioning assumptions. Practitioners should monitor CLIA complexity categorization changes and group purchasing organization contract renewal cycles for early signals of procurement authority concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Virology Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market