
 Paediatric Wheelchairs Market | 2026-2036
Paediatric Wheelchairs Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Wheelchairs Market Analytics
Aftermarket service revenue is tilting toward seating assessment and pressure-mapping calibration as margin pools migrate from hardware sales to ongoing clinical support. Permobil sustains R&D intensity in powered mobility with programmable drive controls for paediatric users. Ottobock anchors European distribution through its rehabilitation technology network. Sunrise Medical differentiates via modular frame systems that accommodate growth adjustments without full chair replacement.
Paediatric wheelchairs are mobility devices engineered for users under 18 years, incorporating seat widths from 20 to 35 centimetres, adjustable back angles, and crash-tested transit tie-downs for vehicle safety compliance. Their primary purpose is to support postural development, prevent secondary complications, and enable age-appropriate participation in education and social activities. Electric wheelchairs command premium positioning due to joystick programming and tilt-in-space actuation for complex neurological conditions. Lightweight wheelchairs built from aluminium or carbon fibre compete on caregiver portability and vehicle load limits. Smart wheelchairs with obstacle detection and connectivity modules represent the fastest-expanding technology segment as funding bodies recognise functional independence outcomes.
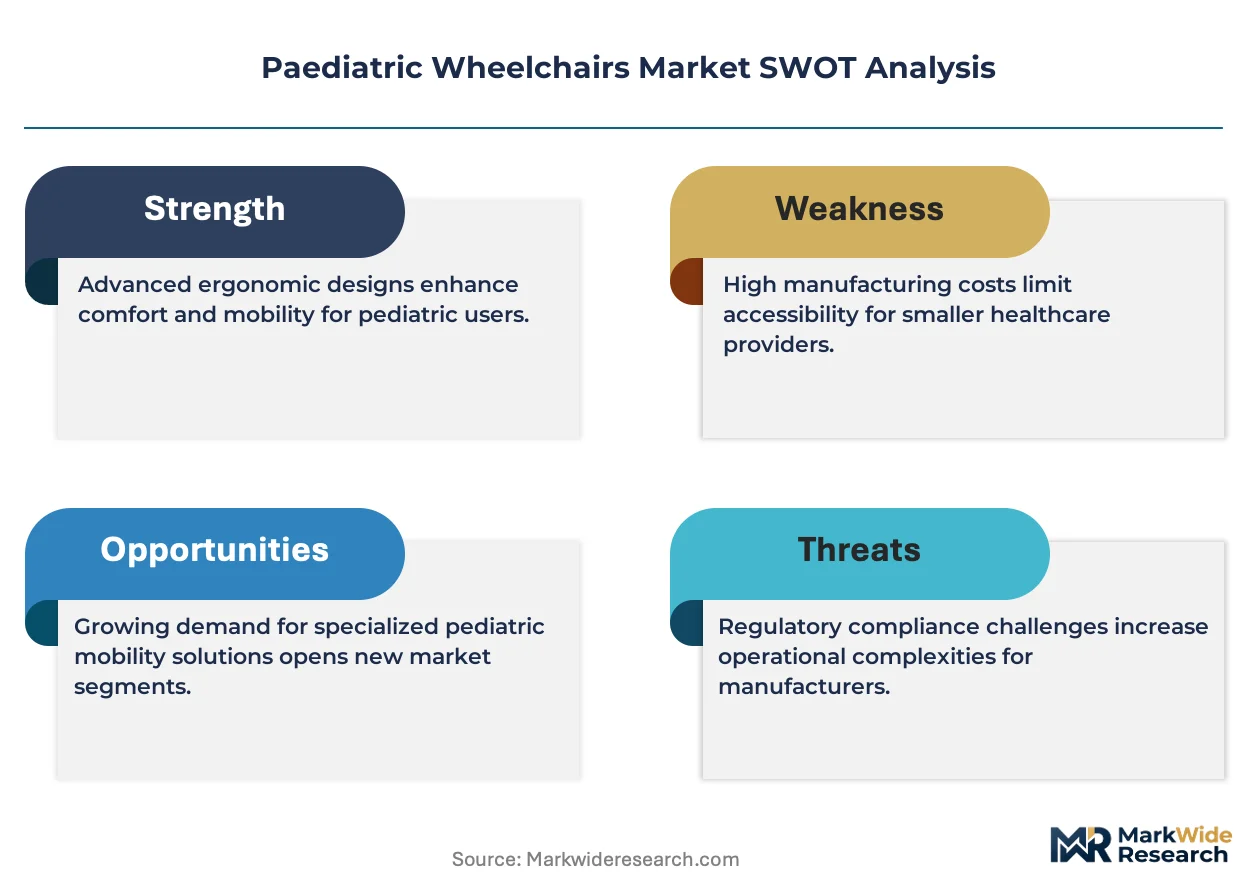
The EU Medical Device Regulation and FDA paediatric device guidance shape design documentation, clinical evidence requirements, and market access timelines for manufacturers serving multiple jurisdictions. ISO 7176 technical standards define durability testing, dimensional stability, and user-safety protocols that products must satisfy before reimbursement approval. Stakeholders must monitor how health technology assessment bodies weigh quality-of-life metrics against acquisition costs when updating paediatric mobility coverage policies.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure their conformity assessment strategies and documentation workflows for paediatric mobility products.
Growth Catalysts
- Statutory reimbursement frameworks:Germany's statutory health insurance mandates coverage for custom-fitted paediatric wheelchairs, creating predictable demand pull from rehabilitation centers and specialized clinics.
- Configurable seating systems:Rehabilitation centers are expanding procurement of growth-adjustable frames that accommodate postural changes in cerebral palsy patients without full chair replacement.
- Smart wheelchair connectivity:Funding bodies in Scandinavia and the Netherlands are recognizing functional independence outcomes from obstacle-detection modules, accelerating technology adoption curves.
Market Restraints
- Aluminium and carbon fibre input volatility:Lightweight frame manufacturers face margin pressure from aerospace and automotive sectors competing for the same composite material supply pools.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints are extending technical documentation review periods for Class I and IIa paediatric mobility devices.
- Manual wheelchair substitution:Standing frames and gait trainers are capturing portions of the ambulatory paediatric population previously assigned to passive seating solutions.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland, Romania, and Bulgaria maintain reimbursement gaps for powered paediatric mobility that EU structural funds and cross-border care directives could address.
- Seating-as-a-service models:Pressure-mapping calibration and postural reassessment subscriptions are migrating margin pools from hardware sales toward recurring clinical support revenue.
- Telehealth integration:Remote seating assessment protocols combined with 3D scanning technologies are collapsing geographic barriers between specialist clinicians and rural patient populations.
Industry Challenges
- Paediatric seating specialist scarcity:Certified assistive technology professionals with paediatric biomechanics training are concentrated in metropolitan academic medical centers, creating service delivery deserts.
- ISO 7176 testing timeline compression:Durability and dimensional stability certification requirements are extending product development cycles while reimbursement windows contract.
- Legacy fleet interoperability:Smart wheelchair connectivity modules must integrate with existing vehicle tie-down systems and school transportation infrastructure, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Wheelchairs Market |
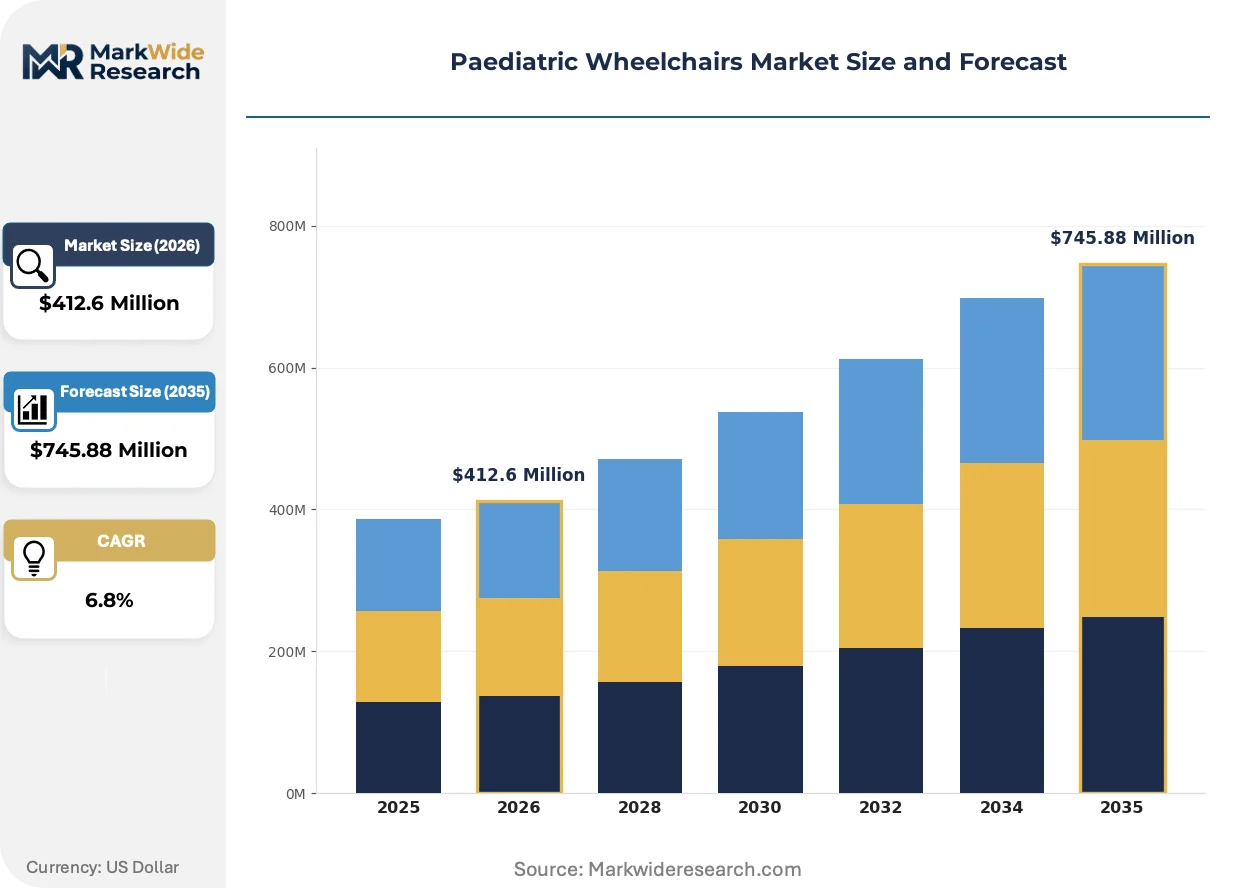
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Electric Wheelchairs, Sports Wheelchairs, Lightweight Wheelchairs End User: Pediatric Patients, Rehabilitation Centers, Hospitals, Home Care Technology: Smart Wheelchairs, Customizable Designs, Lightweight Materials, Assistive Tech Integration Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Healthcare Distributors |
| Companies Covered | Sunrise Medical, Invacare, Permobil, MEYRA GmbH, SORG Rollstuhltechnik GmbH, Ottobock, Medline, Drive Medical, Karman Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Wheelchairs Market Evolving Landscape
Digital twin technologies are virtualizing the traditional seating assessment workflow, compressing the iteration cycle between clinical measurement and manufactured product while enabling remote specialist consultation across distributed care networks.
Pressure-mapping sensor arrays embedded within seat cushions are virtualizing the conventional hands-on tissue viability assessment, allowing occupational therapists to quantify interface forces with objective data. Paediatric rehabilitation hospitals in Germany and the Netherlands are deploying these systems for remote monitoring of spinal deformity progression. The technology is virtualizing the geographic constraints that previously tethered complex seating cases to major academic centers.
The EU Medical Device Regulation's tightened clinical evidence requirements are extending pre-market documentation burdens for configurable frame systems. Manufacturers serving multiple jurisdictions must now maintain parallel technical files satisfying both MDR Annex II requirements and FDA paediatric device guidance. Powered mobility segments with programmable drive controls face the steepest compliance cost escalation, prompting some suppliers to narrow their geographic focus.
Caregiver purchasing committees are consolidating vendor relationships around suppliers offering integrated growth-adjustment programs spanning multiple chair generations. Hospital procurement departments in France and Belgium are negotiating multi-year frame expansion contracts that bundle initial fitting with scheduled dimensional modifications. This concentration pattern favors manufacturers with modular platform architectures and established clinical education networks over point-product competitors.
Paediatric Wheelchairs Market Segmentation
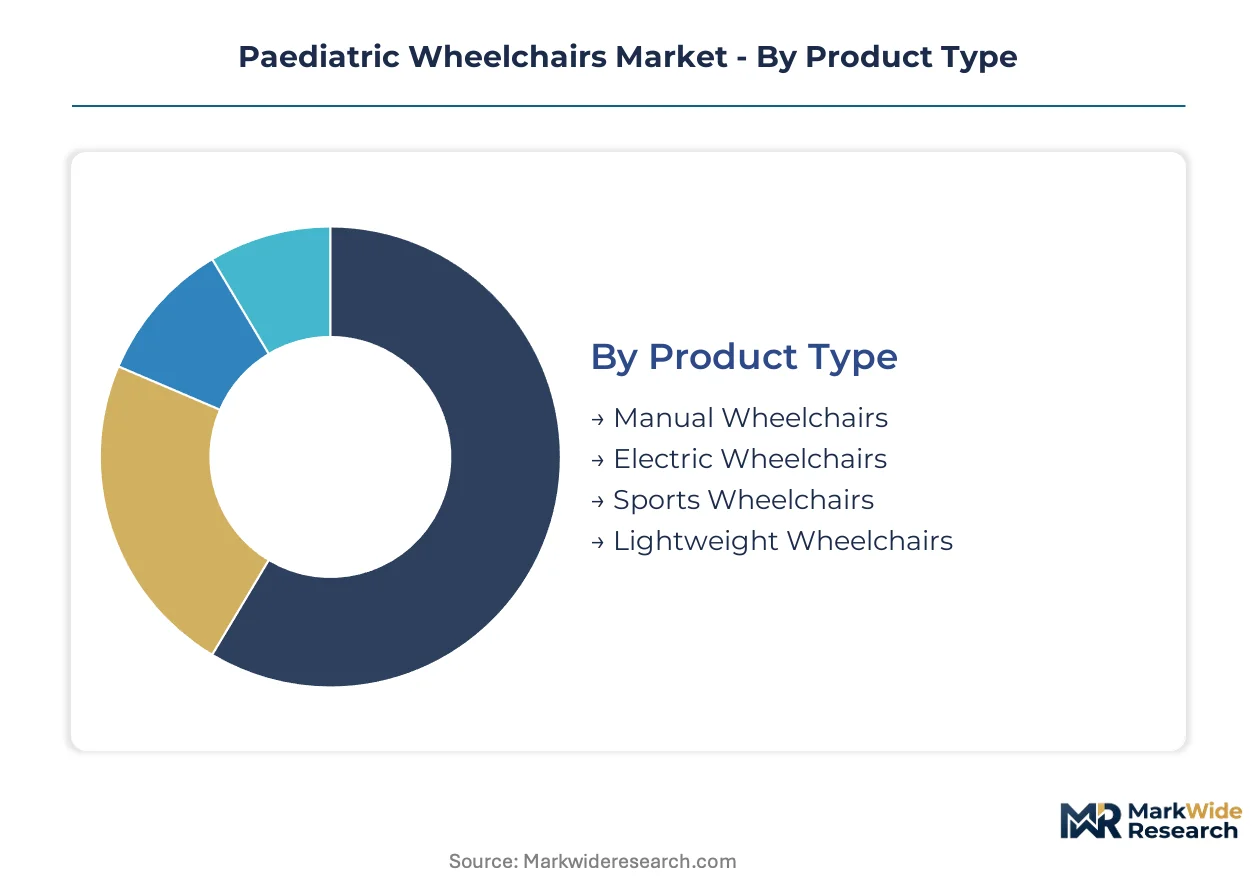
Paediatric wheelchair segmentation reveals distinct procurement patterns across clinical settings and reimbursement pathways. Product configuration, technology integration, and distribution access determine vendor selection criteria for cerebral palsy clinics, rehabilitation hospitals, and home-based care programs.
Product Type:
Use-case spectrum spans passive mobility support to competitive athletic participation, with frame material and propulsion mechanism defining clinical appropriateness and funding eligibility.
- Manual Wheelchairs:Aluminium and steel frame configurations with 20-35 centimetre seat widths dominate ambulatory paediatric populations with sufficient upper extremity function. German statutory health insurance covers custom-fitted manual frames with growth-adjustable components, sustaining predictable procurement volumes from rehabilitation centers.
- Electric Wheelchairs:Programmable joystick controls and tilt-in-space actuation serve complex neurological conditions including cerebral palsy with severe motor impairment. Demand concentrates in Germany and the Netherlands where funding bodies recognize functional independence outcomes from powered mobility.
- Sports Wheelchairs:Cambered wheels and rigid frames optimize for basketball, tennis, and track competition.
- Lightweight Wheelchairs:Carbon fibre and advanced aluminium alloys reduce caregiver strain and vehicle load limits.
The dominant share belongs to manual wheelchairs, while electric wheelchairs are closing the gap fastest as programmable controls expand neurological indications.
End User:
Procurement authority varies across reimbursement gatekeepers, with statutory frameworks concentrating purchasing power in institutional settings.
- Pediatric Patients:Individual beneficiaries under 18 years receive devices through prescription pathways that mandate seating assessment by certified assistive technology professionals. Family purchasing committees in France and Belgium increasingly negotiate multi-year growth-adjustment contracts.
- Rehabilitation Centers:Specialized clinics in Germany and the Netherlands operate centralized seating services with in-house pressure-mapping calibration and 3D scanning capabilities. These centers are expanding procurement of configurable seating systems for cerebral palsy patients.
- Hospitals:Acute care settings provide initial mobility evaluation and temporary seating during inpatient rehabilitation.
- Home Care:Community-based programs deliver ongoing postural reassessment and frame modification services.
Rehabilitation centers command the largest procurement volumes, while home care is expanding most quickly as telehealth integration collapses geographic barriers to specialist assessment.
Technology:
Margin migration from hardware sales toward clinical support services is accelerating adoption of sensor-enabled and remotely configurable systems.
- Smart Wheelchairs:Obstacle detection arrays and connectivity modules enable independent navigation for users with visual or cognitive comorbidities. Scandinavian funding bodies have recognized functional independence outcomes from these systems, accelerating technology adoption curves.
- Customizable Designs:Modular frame architectures accommodate growth adjustments without full chair replacement, aligning with multi-year procurement contracts. EU Medical Device Regulation compliance costs for configurable systems are prompting some manufacturers to narrow geographic focus.
- Lightweight Materials:Aerospace-grade aluminium and carbon fibre compete with automotive and aviation sectors for composite supply pools.
- Assistive Tech Integration:Communication device mounts and environmental control interfaces expand functional capabilities.
Customizable designs retain the largest installed base, though smart wheelchairs are gaining share fastest as outcome-based funding expands.
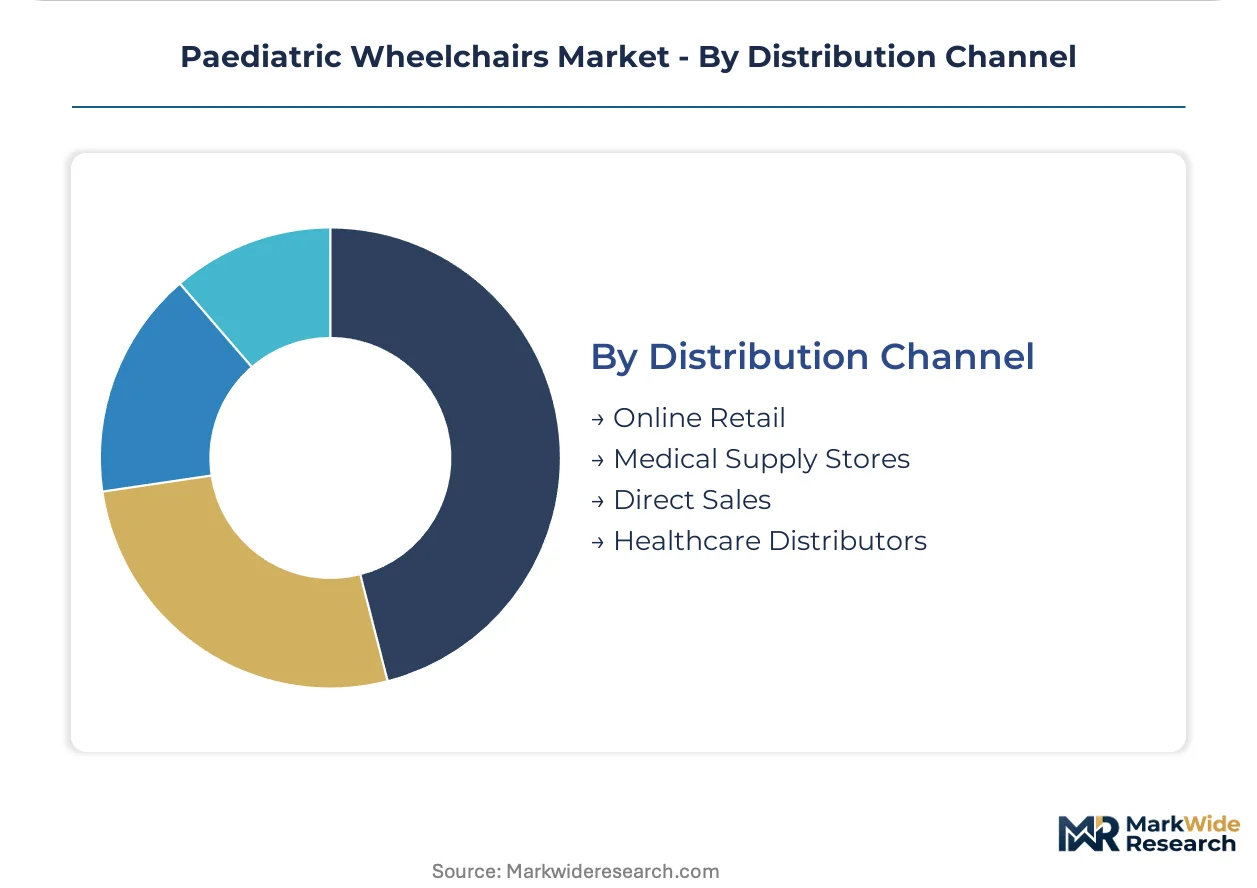
Distribution Channel:
Channel selection reflects product complexity, with configurable seating requiring clinical assessment that pure e-commerce cannot fulfill.
- Online Retail:Standardized manual frames and replacement parts move through digital channels where prescription requirements permit. This channel serves established users with known sizing requirements.
- Medical Supply Stores:Local distributors provide fitting services for basic mobility products with limited configuration needs.
- Direct Sales:Manufacturers maintain field clinical specialists for complex powered mobility and custom seating cases requiring pressure-mapping assessment.
- Healthcare Distributors:Regional networks aggregate procurement for hospital systems and rehabilitation chains, bundling multiple vendor products under single contract vehicles.
Direct sales capture the highest-value transactions, while online retail is climbing the fastest for standardized replacement components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across reimbursement environments. German buyers face minimal out-of-pocket exposure under statutory coverage, while Eastern European purchasers operate with fragmented public funding and higher private burden-sharing.
Germany
Statutory health insurance mandates full coverage for custom-fitted paediatric wheelchairs, eliminating price sensitivity for prescribed devices. The EU Medical Device Regulation tightens conformity assessment through notified body reviews in Berlin and Munich. Rehabilitation technology clusters in North Rhine-Westphalia concentrate seating assessment services for cerebral palsy patients.
Netherlands
Funding bodies recognize functional independence outcomes from smart wheelchair connectivity, accelerating technology procurement. The Dutch Healthcare Authority regulates reimbursement through outcome-based purchasing frameworks. Medical device distribution networks in Utrecht and Eindhoven coordinate cross-border seating services for Belgian and German patients.
United States
Medicaid waiver programs create patchwork coverage with state-level variation in prior authorization requirements. FDA paediatric device guidance shapes clinical evidence standards for powered mobility submissions. Rehabilitation hospitals in Chicago and Philadelphia maintain centralized seating centers serving multi-state referral networks.
France
Hospital procurement departments negotiate multi-year growth-adjustment contracts bundling initial fitting with scheduled modifications. The ANSM oversees post-market surveillance for Class IIa mobility devices. Medical supply clusters in Lyon and Toulouse specialize in configurable frame distribution for paediatric neurological conditions.
Poland
Reimbursement gaps for powered paediatric mobility create reliance on EU structural funds and cross-border care directives. The national pharmaceutical regulator manages medical device registration through simplified procedures for lower-risk categories. Rehabilitation centers in Warsaw and Kraków are expanding seating assessment capacity through telehealth integration with German specialists.
Paediatric Wheelchairs Market Competitive Landscape
Capability concentration sits with specialized seating engineers; scale advantage sits with diversified rehabilitation technology conglomerates. The vendor base organizes around three tiers: premium configurability specialists, mid-market modular platform suppliers, and value-oriented standard frame distributors. Dominant competitive moves include backward integration into pressure-mapping sensor production and geographic narrowing to reduce multi-jurisdiction compliance burdens.
Among European seating specialists, Sunrise Medical and Ottobock occupy positions emphasizing modular platform architectures and clinical education networks respectively. Permobil represents the powered mobility archetype with programmable control specialization. MEYRA GmbH exemplifies German-engineered configurability for complex neurological indications. These three anchors illustrate how capability depth in biomechanical assessment separates premium positioning from commodity competition.
| Leading Market Players |
|---|
| Sunrise Medical |
| Invacare |
| Permobil |
| MEYRA GmbH |
| SORG Rollstuhltechnik GmbH |
| Ottobock |
| Medline |
| Drive Medical |
| Karman Healthcare |
| Others |
Value Network & Pricing Analysis
German statutory health insurance coverage concentrates purchasing power among rehabilitation centers, anchoring margin pools in multi-year clinical service contracts rather than transactional hardware sales. Aerospace and automotive sectors compete for carbon fibre and aluminium supply pools, compressing frame manufacturer margins and accelerating aftermarket revenue migration.
Pricing Analysis
Seating assessment subscriptions and pressure-mapping calibration contracts now drive lifetime value for configurable frame suppliers. Three-tier pricing structure across premium, standard, and economy levels separates powered mobility with programmable controls from growth-adjustable manual frames and basic transit chairs. Cost compression in lightweight materials is intensifying because aerospace demand absorbs composite supply. Hospital procurement committees in France and Belgium exhibit lowest price sensitivity under bundled multi-year contracts, while Eastern European purchasers face highest out-of-pocket burden.
Supply Chain Analysis
Export-control scrutiny on sensor arrays and connectivity modules limits smart wheelchair component flows from US and East Asian suppliers. Manufacturing concentrates in Germany, the Netherlands, and China, with frame fabrication resting on carbon fibre, aerospace-grade aluminium, and pressure-mapping sensor inputs. Single-source vulnerability runs through notified body capacity for EU MDR conformity assessments. Distribution runs through rehabilitation technology networks and direct field clinical specialist deployment for complex seating cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated hospital procurement committees negotiating multi-year vendor contracts, fragmenting price competition among frame suppliers.
For Market Incumbents: Insulate positioning through backward integration into pressure-mapping sensor production and captive clinical education networks. Standing frames and gait trainers threaten substitution for passive manual wheelchair assignments. Certification investment in ISO 7176 durability testing protocols extends competitive moats against mid-market modular platform suppliers. For New Entrants and Emerging Players: Underpenetrated powered mobility reimbursement in Poland, Romania, and Bulgaria represents the most penetrable entry point for configurable seating systems. Telehealth-integrated remote assessment protocols collapse geographic barriers to specialist clinician access. Partner with German rehabilitation centers for cross-border seating service delivery under EU structural fund programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart wheelchair connectivity modules with obstacle-detection arrays. Platform architecture suppliers with established clinical education networks offer superior long-term viability over point-product competitors. Watch for EU MDR notified body capacity expansion as the signal for compliance cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex II technical documentation satisfies notified body reviews in Berlin and Munich. |
| Hospital System Partnership | French procurement departments bundle multi-year growth-adjustment contracts with scheduled modifications. |
| Software Companion Development | Digital twin technologies compress iteration cycles between clinical measurement and manufactured product. |
| Reimbursement Strategy | German statutory health insurance mandates coverage for custom-fitted paediatric wheelchairs. |
| Backward Integration | In-house pressure-mapping sensor production captures margin pools migrating from hardware sales. |
Research Methodology
A standing panel of rehabilitation physicians, certified assistive technology professionals, hospital procurement managers, and biomedical engineers provided ongoing calibration across the analysis window. Secondary validation drew from EU MDR notified body documentation, ISO 7176 technical standards filings, hospital procurement databases, and GPO contract repositories. Bottom-up unit economics triangulated against top-down reimbursement expenditure estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, end-user setting, technology integration level, and distribution channel. CAGRs derived from fitted trend extrapolation anchored in statutory reimbursement expansion trajectories and telehealth integration adoption curves. Powered mobility penetration rates and configurable frame replacement cycles served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates or composite material pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding notified body capacity expansion and reimbursement policy continuity. Material shifts in EU MDR implementation timelines or statutory coverage scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Perfusion Products Market