
 Dental Infection Treatment Market | 2026-2036
Dental Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Infection Treatment Market Analysis
Project finance for dental clinic networks is reshaping competitive dynamics in infection control procurement. Henry Schein leverages its distribution infrastructure to supply bundled infection management protocols across multi-site practices. Pfizer anchors its position through sustained R&D investment in novel antibiotic formulations targeting resistant oral pathogens. Dentsply Sirona differentiates by integrating consumable sterilization workflows with its digital dentistry platforms.
Dental infection treatment encompasses pharmaceutical and device-based interventions designed to eliminate or suppress pathogenic microorganisms within the oral cavity, typically employing beta-lactam antibiotics, chlorhexidine-based antiseptics, and sterile irrigation systems manufactured to USP <797> compounding standards. The primary purpose is to prevent systemic dissemination from odontogenic foci while preserving hard and soft tissue structures. Antibiotics remain the largest product category by revenue, though antiseptic adjuncts are capturing expanded share as prophylactic protocols tighten. Among applications, endodontics generates the highest procedure-linked consumption of antimicrobial agents due to the complexity of polymicrobial canal infections. Delivery mode selection increasingly favors topical and intraosseous routes to minimize systemic exposure and comply with stewardship mandates.
The FDA regulates antimicrobial labeling and post-market surveillance for dental indications, while the EPA oversees sterilization byproduct emissions from clinic autoclave operations. State dental boards enforce infection control protocol compliance through continuing education requirements and unannounced practice inspections. Stakeholders must monitor evolving FDA guidance on narrow-spectrum antibiotic prioritization and adapt formularies accordingly.
Market Dynamics
Antimicrobial stewardship mandates from the FDA are compressing prescribing latitude for broad-spectrum agents and forcing formularies toward narrow-spectrum alternatives with lower resistance selection pressure.
Growth Catalysts
- Hospital dental department expansion:Rising procedural volumes in acute-care settings are broadening the addressable patient base for infection management protocols.
- USP <797> compounding standards:Stricter sterile preparation requirements are driving replacement cycles for irrigation systems and compounding infrastructure.
- Polymicrobial canal complexity:Endodontic applications generate sustained demand for combination antimicrobial therapies targeting biofilm-resistant infections.
Market Restraints
- API supply concentration:Beta-lactam active pharmaceutical ingredient production clusters in China, creating vulnerability to export restriction cascades.
- Chlorhexidine price volatility:Petrochemical feedstock fluctuations transmit directly to antiseptic manufacturing costs.
- Narrow-spectrum development timelines:FDA antimicrobial stewardship guidelines extend clinical trial requirements for novel agents, stretching R&D payback periods.
Strategic Opportunities
- Rural clinic penetration:Federally Qualified Health Centers in the United States remain underpenetrated for integrated infection control bundles.
- Topical delivery convergence:Intraosseous injection systems combined with sustained-release matrices offer alternatives to systemic exposure.
- Digital workflow integration:Sterilization tracking software linked to practice management platforms creates new recurring revenue attachment points.
Industry Challenges
- Compounding pharmacy certification:USP <797> compliance timelines stretch 18-24 months for clinic-level sterile preparation facilities.
- Legacy autoclave integration:EPA sterilization byproduct monitoring requirements force retrofit costs on installed equipment bases.
- Antimicrobial resistance surveillance:State dental boards mandate reporting protocols that strain practice administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Infection Treatment Market |
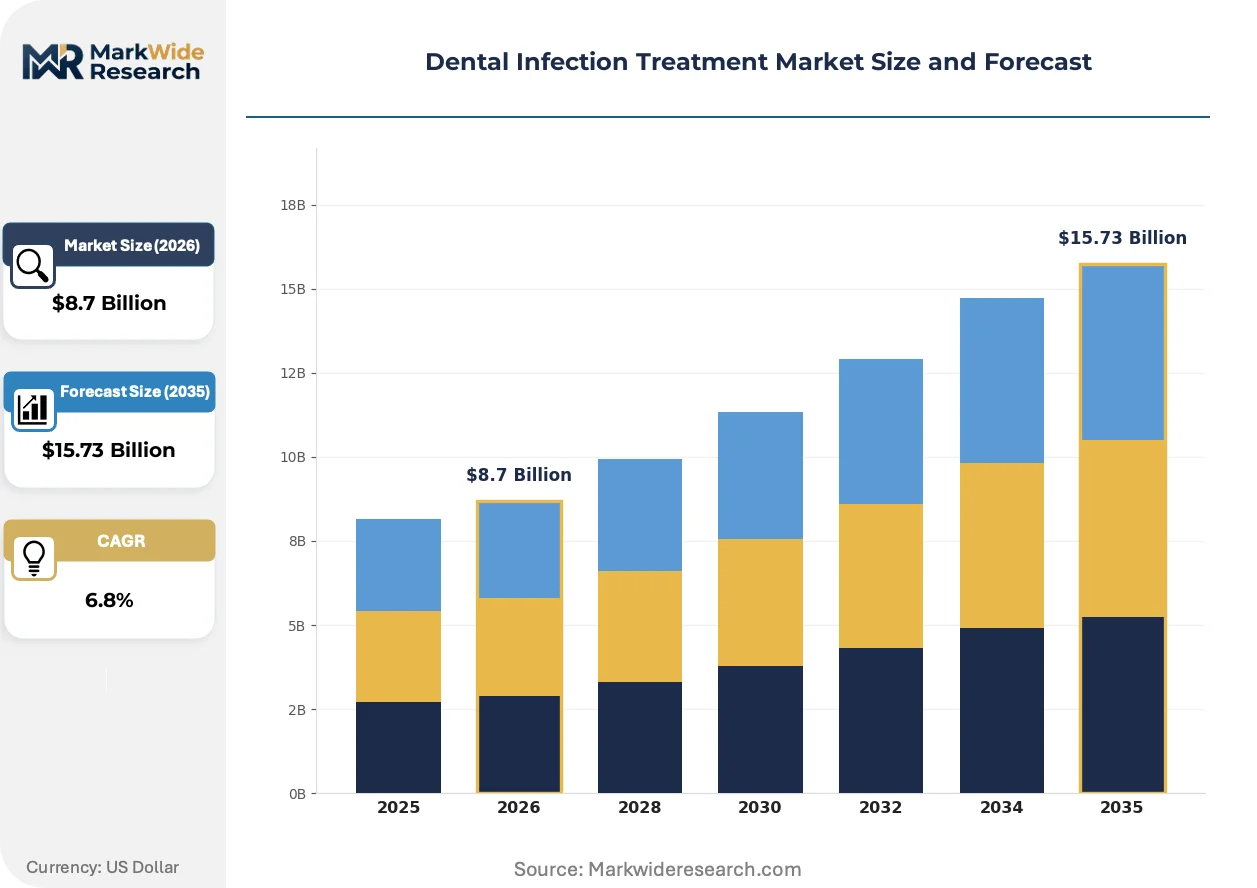
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Surgical Kits, Analgesics Application: Endodontics, Periodontics, Oral Surgery, General Dentistry Delivery Mode: Topical, Intraosseous, Injectable, Oral End User: Dentists, Hospitals, Dental Clinics, Research Institutions |
| Companies Covered | Dentsply Sirona, 3M, Henry Schein, Kerr Corporation, Johnson & Johnson, Pfizer, COLTENE Group, Young Innovations, Steris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Infection Treatment Market Emerging Trajectories
Photodynamic therapy systems are penetrating endodontic workflows as antibiotic adjuncts, while regulatory pressure on resistance selection reshapes product development priorities across formulation categories.
Photosensitizer-activated disinfection is collapsing the traditional boundary between mechanical debridement and chemical antimicrobial action in root canal therapy. Multi-site dental service organizations in the United States are piloting chairside photodynamic units at replacement rates exceeding conventional irrigation protocols. The technology is collapsing reimbursement complexity for complex canal cases by reducing follow-up antibiotic prescriptions.
REACH authorization requirements for residual antiseptic characterization are forcing reformulation of chlorhexidine rinses across European markets. ECHA substance evaluation deadlines are compressing product registration timelines for legacy formulations. German and French dental distributors are prioritizing suppliers with completed REACH dossiers to avoid supply interruption.
Integrated dental service organizations are consolidating infection control procurement through centralized formulary committees rather than practice-level purchasing. Multi-site operators are displacing independent distributors with direct manufacturer contracts tied to volume-tiered sterilization consumable bundles. This concentration is most visible in the United States, where DSO-affiliated locations now account for the majority of hospital-grade autoclave placements.
Dental Infection Treatment Market Segmentation
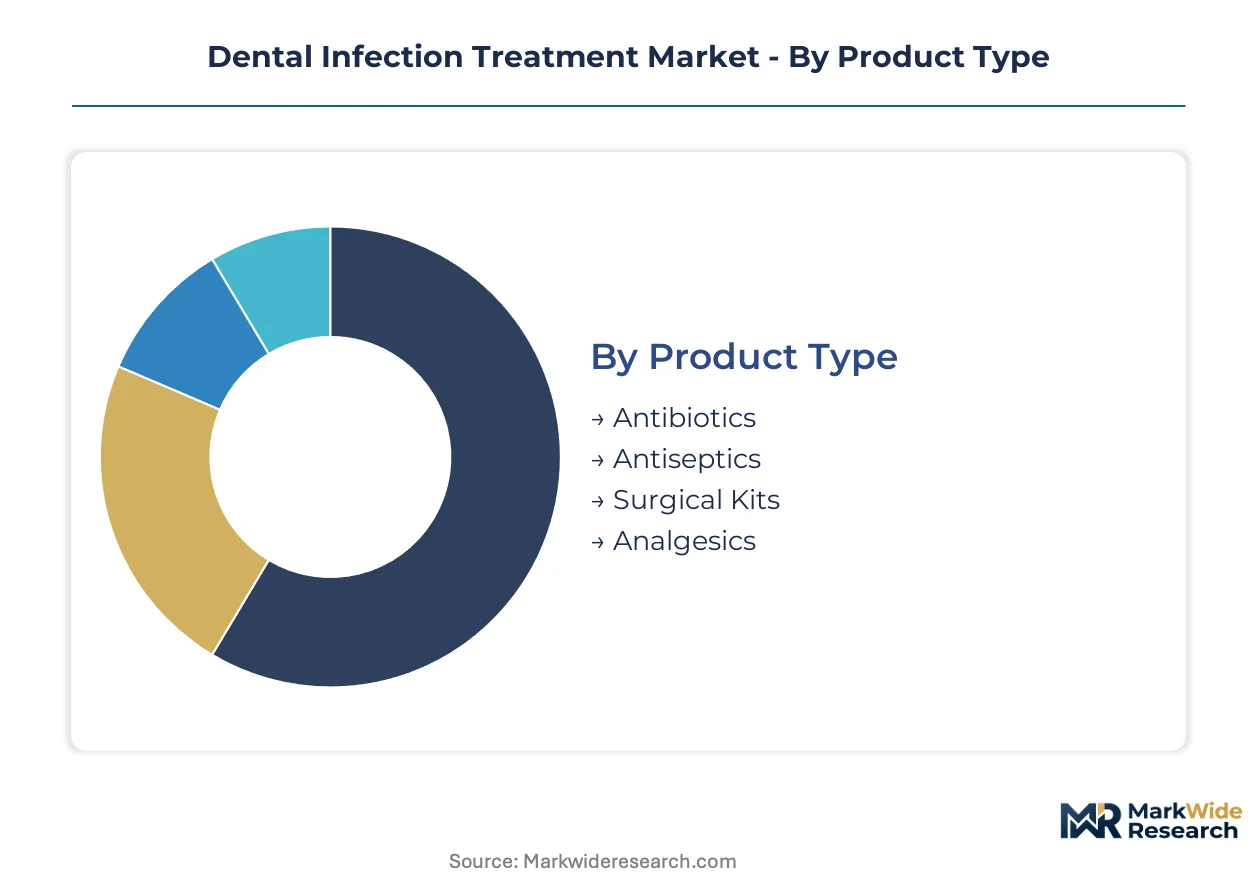
Segmentation in dental infection treatment reveals distinct procurement patterns across product categories and care settings. After-sales service intensity varies sharply between device-intensive segments requiring sterilization maintenance and pharmaceutical categories governed by formulary compliance.
Product Type:
After-sales service intensity peaks with surgical kits requiring autoclave calibration and instrument tracking, while pharmaceutical segments demand regulatory documentation support.
- Antibiotics:Beta-lactam formulations dominate prescribing volumes for odontogenic infections, with narrow-spectrum agents displacing broad-spectrum alternatives under FDA stewardship mandates. Demand concentrates in United States hospital dental departments where integrated service organizations enforce centralized formulary compliance.
- Antiseptics:Chlorhexidine-based rinses and irrigation solutions serve as first-line prophylaxis across procedure types. European REACH authorization requirements are compressing supplier qualification timelines, favoring manufacturers with completed ECHA dossiers in Germany and France.
- Surgical Kits:Sterile instrument bundles with integrated irrigation systems require USP <797> compliant compounding infrastructure.
- Analgesics:NSAID and acetaminophen combinations manage post-procedural pain alongside antimicrobial protocols.
Antibiotics holds the largest share; momentum sits with antiseptics as prophylactic protocols tighten.
Application:
Cost tier stratification separates complex specialty procedures from routine preventive care, with reimbursement differentials driving technology adoption rates.
- Endodontics:Root canal therapy generates the highest antimicrobial consumption per procedure due to polymicrobial canal biofilms and repeated irrigation cycles. Photodynamic therapy systems are penetrating this segment in United States multi-site practices as antibiotic adjuncts.
- Periodontics:Sustained-release antimicrobial matrices target subgingival biofilms in periodontal maintenance protocols.
- Oral Surgery:Extraction and implant placement procedures drive demand for comprehensive surgical kits with sterile irrigation.
- General Dentistry:Routine restorative work relies on standard antiseptic prophylaxis with minimal antibiotic prescribing.
Endodontics commands premium pricing; general dentistry delivers volume scale.
Delivery Mode:
Volume concentration favors routes minimizing systemic exposure, aligning with antimicrobial stewardship objectives and patient safety protocols.
- Topical:Rinses, gels, and sustained-release matrices deliver localized antimicrobial action without systemic absorption. United States dental service organizations are standardizing topical protocols to reduce antibiotic-related adverse event liability.
- Intraosseous:Injection systems target alveolar bone infections with precision delivery, reducing collateral tissue exposure.
- Injectable:Parenteral antibiotics serve acute odontogenic infections with systemic dissemination risk.
- Oral:Tablet and liquid formulations remain the default for outpatient post-procedural prophylaxis.
Topical delivery holds the largest share; intraosseous systems are climbing the fastest as precision medicine protocols advance.
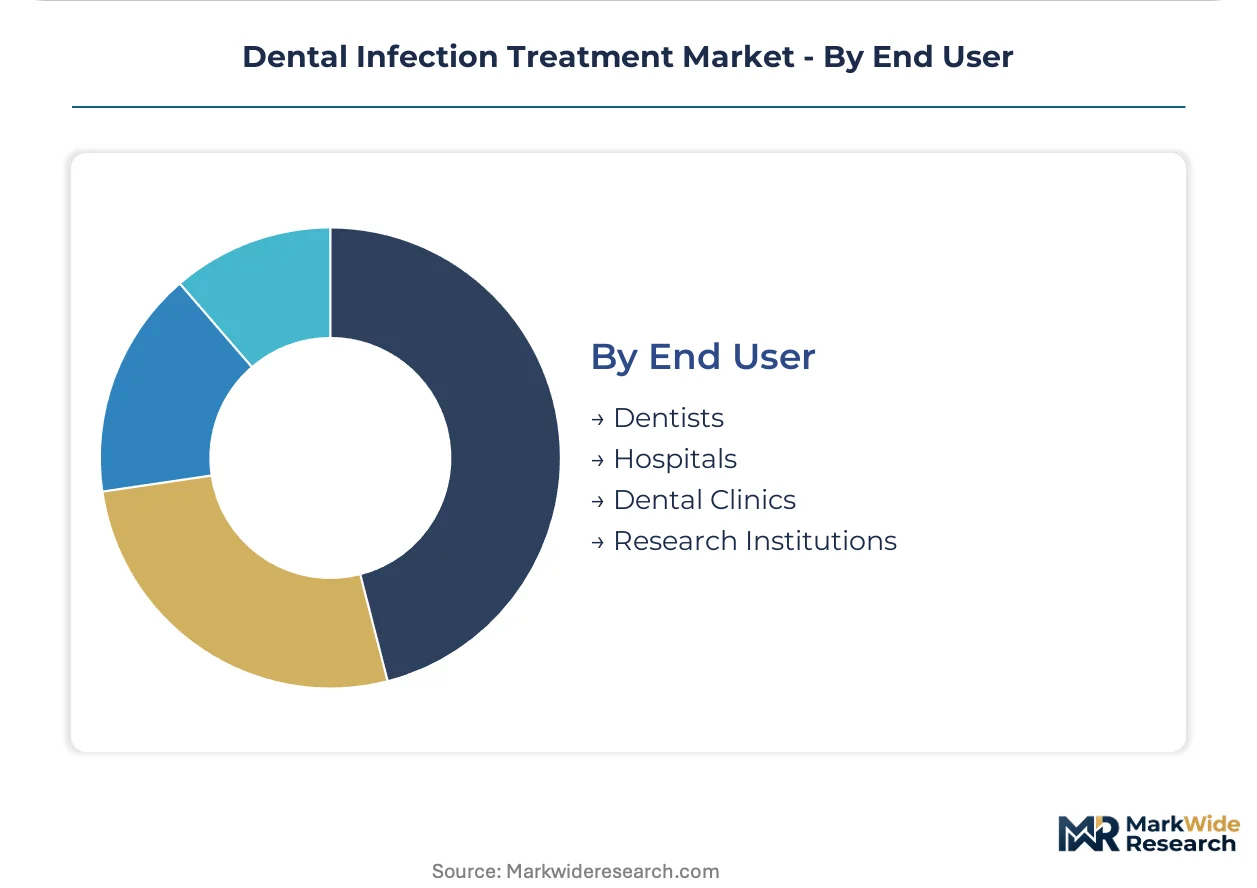
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging scale against independent practice fragmentation.
- Dentists:Solo and small-group practices rely on distributor-mediated supply chains with limited formulary control.
- Hospitals:Acute-care dental departments enforce centralized procurement tied to antimicrobial stewardship committees.
- Dental Clinics:Multi-site dental service organizations in the United States are displacing distributors with direct manufacturer contracts for sterilization consumable bundles.
- Research Institutions:Academic centers pilot novel delivery technologies and resistance surveillance protocols.
Dental clinics hold the largest share; hospitals are gaining share fastest through department expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dental infection treatment products reflect concentrated manufacturing clusters against dispersed clinical demand. Import dependency for beta-lactam active pharmaceutical ingredients shapes procurement vulnerability profiles across major consuming markets.
United States
Hospital dental department expansion and dental service organization consolidation drive antimicrobial consumption growth. FDA antimicrobial stewardship guidelines redirect formularies toward narrow-spectrum agents through tightened labeling requirements. The Dallas-Fort Worth metroplex anchors multi-site practice headquarters where centralized procurement committees negotiate direct manufacturer contracts for sterilization consumables.
Germany
Endodontic specialty clinics generate premium demand for photodynamic therapy systems as antibiotic adjuncts. ECHA REACH authorization deadlines compress supplier qualification timelines for chlorhexidine-based formulations. The Rhine-Ruhr industrial corridor hosts compounding pharmacy networks upgrading to USP <797> equivalent sterile preparation standards.
China
Domestic beta-lactam API production capacity serves regional export demand while clinic infrastructure modernization accelerates device imports. NMPA tightened sterile medical device registration requirements extend product approval timelines for imported irrigation systems. Shanghai's Pudong district concentrates dental equipment distributors managing cross-border sterilization consumable logistics.
Japan
Aging-related periodontal disease prevalence sustains antimicrobial rinse consumption in preventive care protocols. PMDA post-market surveillance requirements for dental pharmaceuticals mandate resistance reporting infrastructure investments. The Osaka-Kobe manufacturing belt produces precision intraosseous injection systems for regional and export markets.
Brazil
Private dental clinic chain expansion in urban centers drives standardized infection control bundle procurement. ANVISA antimicrobial resistance surveillance mandates impose administrative compliance costs on practice networks. São Paulo's medical device distribution hub channels imported surgical kits to Southeast regional markets.
Dental Infection Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. Market structure tilts toward consolidation as multi-site dental service organizations disintermediate traditional distribution channels. Three archetypes dominate: diversified healthcare conglomerates with dental divisions, pure-play dental equipment manufacturers, and pharmaceutical firms with oral care portfolios. Competitive moves concentrate on vertical integration into sterilization consumable production and direct contracting bypassing distributor networks.
Within the pharmaceutical archetype, Pfizer anchors narrow-spectrum antibiotic development portfolios targeting resistant oral pathogens. Henry Schein exemplifies the distribution-integrated model, leveraging logistics infrastructure to supply bundled infection management protocols across multi-site practices. Dentsply Sirona occupies the device-platform position, linking consumable sterilization workflows to digital dentistry ecosystems. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M |
| Henry Schein |
| Kerr Corporation |
| Johnson & Johnson |
| Pfizer |
| COLTENE Group |
| Young Innovations |
| Steris |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Los Angeles container freight corridors transmit petrochemical feedstock volatility directly into chlorhexidine antiseptic landed costs, compressing margins for distributors while amplifying price spreads between USP <797> certified surgical kits and standard irrigation bundles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates FDA-cleared narrow-spectrum antibiotic formulations from legacy broad-spectrum generics, with volume-scale procurement by dental service organizations commanding steepest discounts. Pricing pressure stems from API supply concentration in China and REACH compliance costs for European antiseptic registrations. Independent solo practices exhibit highest price sensitivity, while hospital dental departments prioritize formulary compliance over unit cost.
Supply Chain Analysis
Contract manufacturing for beta-lactam APIs concentrates among Chinese pharmaceutical intermediaries and Indian finished-dose formulators, with sterile irrigation system assembly anchored in German precision engineering clusters. Raw material dependencies include petrochemical-derived chlorhexidine base, pharmaceutical-grade beta-lactam precursors, and medical-grade polymers for disposable delivery systems. Single-source vulnerability in Chinese API production creates tariff exposure and export restriction risk. Distribution runs through Henry Schein and regional dental distributors to multi-site practice networks, with direct manufacturer contracting displacing traditional wholesale channels among consolidated dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment via FDA antimicrobial stewardship compliance and USP <797> certification timelines erect formidable barriers to challenger brands.
For Market Incumbents: Entrench formulary control through captive supply of narrow-spectrum antibiotic pipelines and backward integration into chlorhexidine raw material sourcing. Lock in multi-year sterilization consumable contracts with expanding dental service organizations before emerging photodynamic therapy systems displace antibiotic adjunct protocols in endodontic workflows. Prioritize REACH dossier completion for European antiseptic registrations to preempt supply interruption. For New Entrants and Emerging Players: Build out topical delivery system portfolios targeting rural Federally Qualified Health Centers in the United States, where integrated infection control bundles remain underpenetrated and procurement fragmentation permits direct manufacturer engagement. Exploit the 18-24 month USP <797> compliance gap facing independent compounding pharmacies by offering pre-certified sterile irrigation kits with embedded practice management software integration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates with underoptimized dental divisions lacking digital workflow integration capabilities. Long-term viability hinges on sterilization tracking software attachment rates and recurring consumable revenue per practice seat. Monitor photodynamic therapy reimbursement code establishment as the critical inflection signal for antibiotic displacement velocity in endodontic protocols.| Strategic Initiative | Industry Significance |
|---|---|
| USP <797> Certification Investment | Compounding pharmacy networks in the Rhine-Ruhr corridor upgrade sterile infrastructure to capture hospital dental department contracts. |
| Photodynamic Therapy Platform Launch | Chairside photosensitizer systems in Dallas-Fort Worth multi-site practices reduce antibiotic prescription volumes and reimbursement complexity. |
| REACH Dossier Completion | German and French distributors prioritize ECHA-compliant chlorhexidine suppliers to avoid authorization deadline supply gaps. |
| Direct Manufacturer Contracting | Dental service organizations disintermediate Henry Schein distribution to secure volume-tiered sterilization consumable bundles. |
| Narrow-Spectrum Pipeline Advancement | Pfizer R&D investment targets resistant oral pathogens under FDA stewardship guidelines extending clinical trial requirements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA antimicrobial stewardship guidance documents, ECHA REACH substance evaluation dossiers, and hospital dental department procurement databases. Interviews with formulary directors at dental service organizations, USP <797> compliance officers at compounding pharmacies, and sterilization equipment procurement managers at multi-site practices inform demand-side validation. Secondary sources include EPA sterilization byproduct emission filings, NMPA medical device registration records, and trade flow data for beta-lactam API imports. Bottom-up procedure volume modeling triangulates against top-down pharmaceutical consumption estimates.
Forecast inputs span product type segmentation across antibiotics, antiseptics, surgical kits, and analgesics; application segmentation across endodontics, periodontics, oral surgery, and general dentistry; delivery mode differentiation between topical, intraosseous, injectable, and oral routes; and end-user stratification across dentists, hospitals, dental clinics, and research institutions. CAGRs derive from procedure volume trajectories, antimicrobial stewardship policy implementation timelines, and dental service organization expansion rates across the analysis window. Resistance surveillance reporting mandates and photodynamic therapy reimbursement code development constitute industry-specific forecast sensitivities.
Sensitivities concentrate around FDA narrow-spectrum prioritization guidance revisions, Chinese API export restriction cascades, and photodynamic therapy clinical adoption curves. Forecasts reflect documented assumptions regarding dental service organization consolidation velocity and USP <797> compliance timeline adherence. Quarterly review of EMA antimicrobial resistance surveillance data and ANVISA reporting protocol changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Wipes Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Sterilization Monitoring Market
Infection Control
Infection Control Supplies Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Medical Washer Disinfector Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Hospital Acquired Infections Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Salivary Gland Infection Market