
 Niemann Pick Disease Market | 2026-2036
Niemann Pick Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Niemann Pick Disease Market Outlook
Gene therapy-grade manufacturing standards is reorganizing competitive dynamics across the Niemann Pick disease landscape. Sanofi leverages its lysosomal storage disorder infrastructure to sustain European regulatory relationships. Cyclo Therapeutics anchors North American clinical development with cyclodextrin-based platforms. Zevra Therapeutics differentiates through small molecule innovation for Type C patients.
Niemann Pick disease comprises a family of inherited metabolic disorders characterized by sphingomyelin and cholesterol accumulation in lysosomes, driven by deficient acid sphingomyelinase (Type A/B) or NPC1/NPC2 protein dysfunction (Type C). The primary commercial purpose centers on halting neurodegeneration and extending survival through substrate reduction, enzyme replacement, or genetic correction. Enzyme Replacement Therapy occupies the mature revenue base while Gene Therapy represents the fastest-expanding development pipeline. Antisense Oligonucleotide approaches concentrate in Type C indications where CNS penetration determines clinical value.
The FDA's orphan drug and fast-track programs shape U.S. trial economics, while the EMA's PRIME designation streamlines European market access for breakthrough therapies. WHO inclusion of Niemann Pick on its rare disease registry strengthens international diagnostic standards and patient identification. Stakeholders must monitor evolving payer evidence requirements for one-time gene therapies versus chronic maintenance regimens.
Market Dynamics
Gene therapy manufacturing scale-up is compressing clinical timelines and forcing biologics infrastructure investments across the Niemann Pick landscape, with single-use bioreactor capacity emerging as the binding constraint for late-stage trials.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits for clinical trial costs and seven-year market exclusivity accelerate sponsor commitment to ultra-rare indications.
- Substrate Reduction Chemistry:Small-molecule blood-brain barrier penetration advances expand addressable patient pools in Type C neurodegenerative progression.
- Academic Medical Center Concentration:Johns Hopkins, Mount Sinai, and Cincinnati Children's anchor referral networks that compress diagnostic delays and treatment initiation.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production depends on a handful of North American and European contract manufacturers with 18-month queue times.
- Reimbursement Evidence Thresholds:CMS and commercial payers demand survival endpoint data that requires decade-long natural history studies.
- Bioreactor Capacity Scarcity:Stainless steel infrastructure at CDMOs limits AAV batch sizes for systemic gene delivery programs.
Strategic Opportunities
- EMA PRIME Designation Pathway:Accelerated assessment and enhanced regulatory dialogue reduce time-to-authorization for breakthrough therapies.
- Neonatal Screening Expansion:State-level newborn screening panels in Texas, New York, and Illinois create presymptomatic treatment windows.
- Patient Advocacy Data Networks:NPC1/NPC2 registries sponsored by the National Niemann Pick Disease Foundation enable real-world evidence generation.
Industry Challenges
- Gene Therapy Manufacturing Talent Gap:Cell culture specialists and analytical development scientists command premium compensation in a shallow labor pool.
- CMC Documentation Burden:FDA chemistry, manufacturing, and controls requirements for lentiviral and AAV platforms extend IND preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niemann Pick Disease Market |
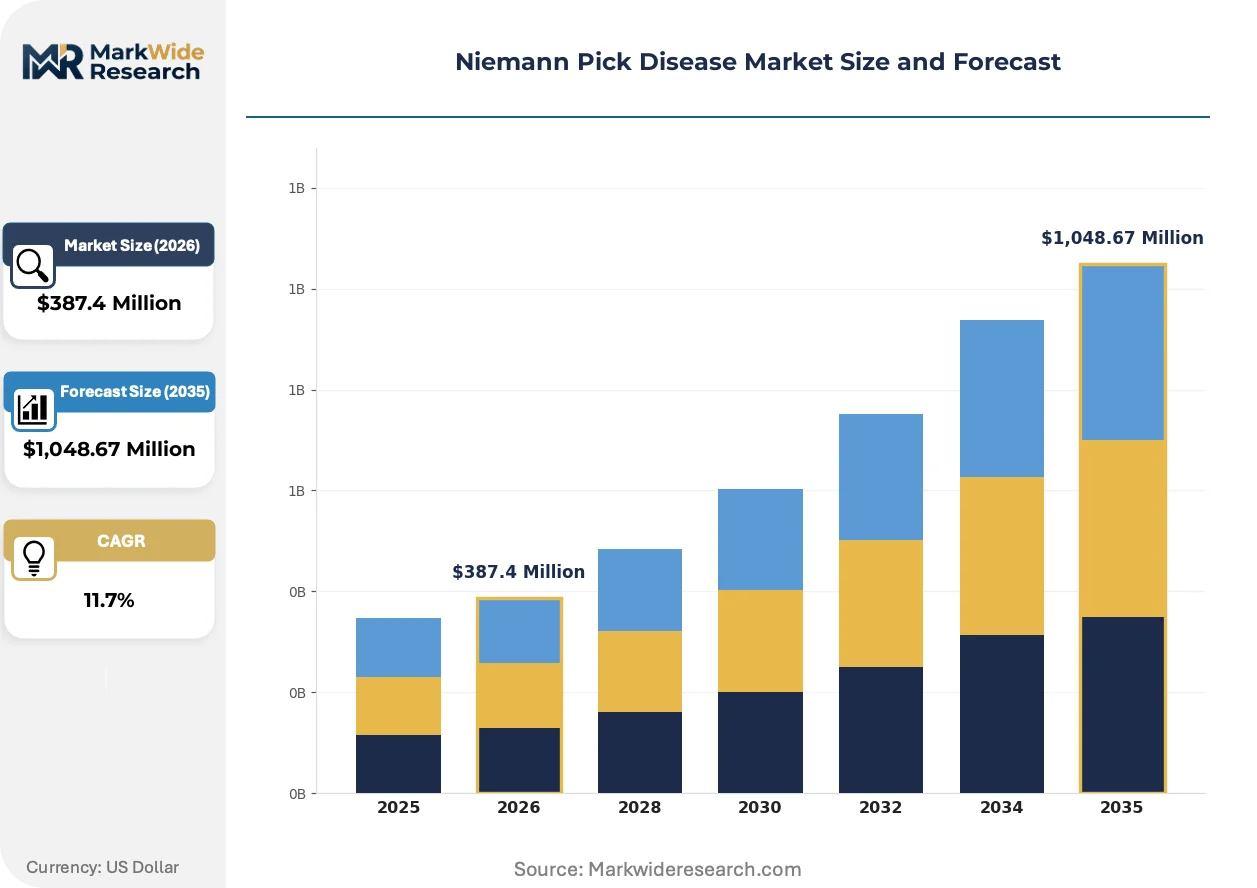
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Antisense Oligonucleotide, Small Molecule Inhibitors, Gene Therapy Indication: Niemann-Pick Type A, Niemann-Pick Type B, Niemann-Pick Type C, Type A/B Combination Delivery Mode: Intravenous, Subcutaneous, Oral, Intrathecal End User: Hospitals, Clinics, Homecare Settings, Research Laboratories |
| Companies Covered | Sanofi, Novartis, Cyclo Therapeutics, Zevra Therapeutics, Pfizer, IntraBio, Sarepta Therapeutics, Janssen Global Services, Azafaros, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niemann Pick Disease Market Strategic Shifts
Bioprocessing intensification and regulatory science advances are compressing the gap between preclinical proof-of-concept and commercial readiness, with manufacturing economics now determining program viability earlier than clinical endpoints.
AAV9 capsid engineering is miniaturizing payload delivery systems while preserving CNS tropism. Gene therapy developers at academic spinouts and mid-cap biotechs adopt these refined serotypes for intrathecal administration routes. The structural consequence is a compression of required dosing volumes and manufacturing batch sizes, reducing COGS pressure for single-administration curative therapies.
WHO inclusion of Niemann Pick on its rare disease registry is harmonizing diagnostic nomenclature across member states. The industrial consequence is standardized ICD coding that enables cross-border patient identification and clinical trial recruitment. European reference networks and North American academic centers are responding by aligning natural history study protocols to this common framework.
Specialized treatment center accreditation is consolidating patient volume into designated excellence hubs. Independent community neurology practices lose referral relationships to certified lysosomal storage disorder programs at Cleveland Clinic, Children's Hospital of Philadelphia, and similar institutions. This channel compression is most visible in the United States, where payer carve-out contracts steer ultra-rare disease management toward credentialled centers with dedicated biochemical genetics teams.
Niemann Pick Disease Market Segmentation
Segmentation in the Niemann Pick disease market reveals divergent competitive pressures across therapeutic modalities. Each dimension carries distinct substitution dynamics that reshape investment allocation and clinical trial prioritization for sponsors.
Product Type:
Substitution pressure intensifies most acutely against chronic maintenance regimens as one-time curative platforms advance through late-stage development.
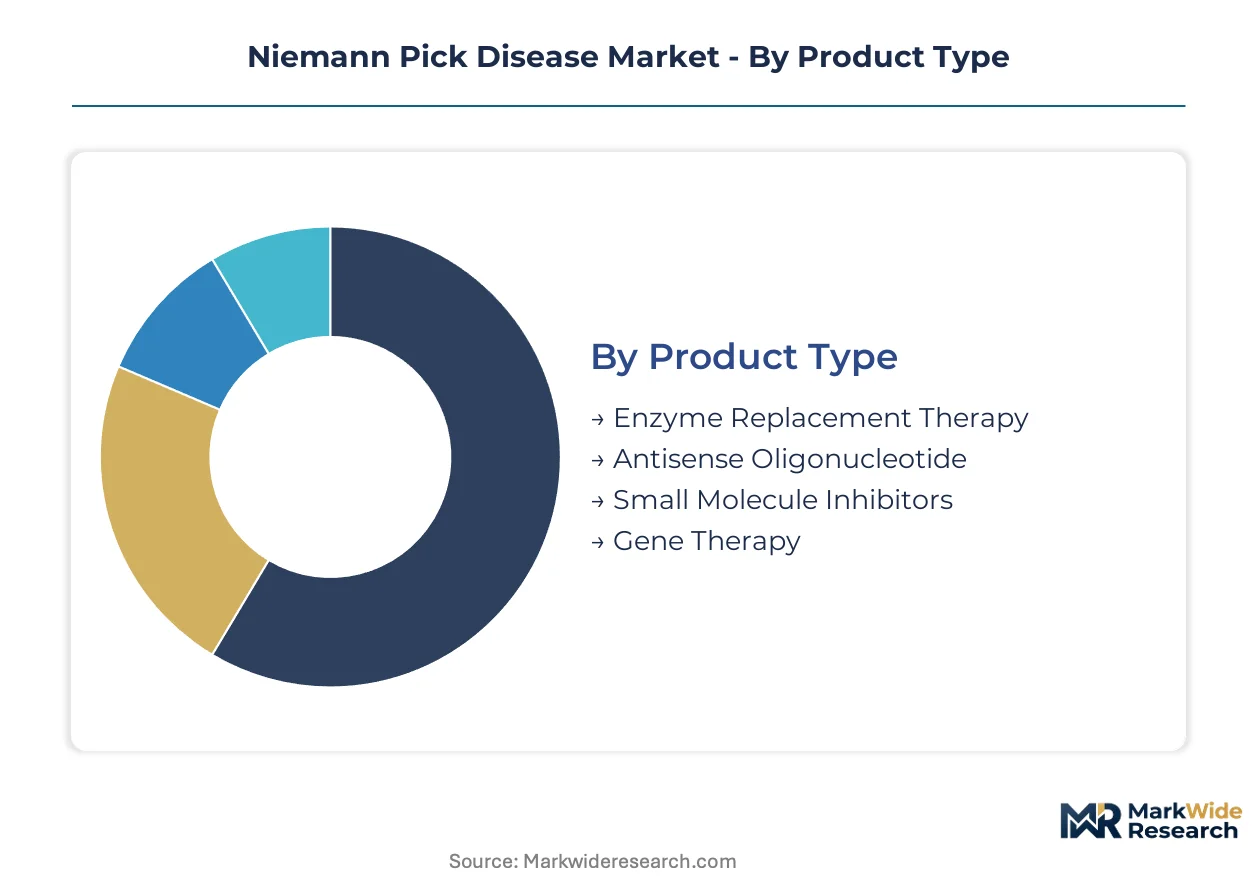
- Enzyme Replacement Therapy:Intravenous acid sphingomyelinase infusions constitute the established revenue base for Type B patients with systemic manifestations. Hospital-based administration requirements limit patient convenience while creating durable reimbursement relationships with commercial payers.
- Gene Therapy:AAV9 and lentiviral vector platforms target definitive correction through single administration, with CNS-directed delivery routes commanding premium development investment. Manufacturing scale constraints at CDMOs create 18-month enrollment bottlenecks for systemic dosing programs.
- Antisense Oligonucleotide:Sequence-specific modulation of NPC1/NPC2 expression pathways.
- Small Molecule Inhibitors:Blood-brain barrier penetrant substrate reduction chemistry for Type C neurodegenerative progression.
Enzyme Replacement Therapy retains volume leadership; Gene Therapy holds the steepest expansion curve.
Indication:
Addressable patient pools contract sharply across phenotypes, with infantile-onset forms presenting the narrowest commercial windows despite highest unmet need.
- Niemann-Pick Type C:Cholesterol trafficking dysfunction produces progressive neurodegeneration with variable age of onset, extending treatment windows into adolescence and adulthood. Substrate reduction therapy with miglustat anchors current standard of care while gene therapy candidates target CNS correction.
- Niemann-Pick Type A:Severe infantile neurovisceral form driven by acid sphingomyelinase deficiency carries rapid mortality trajectory. Clinical development focuses on CNS-penetrant delivery systems for enzyme replacement or genetic correction.
- Niemann-Pick Type B:Visceral predominant phenotype with preserved cognitive function.
- Type A/B Combination:Intermediate phenotypes with overlapping clinical features.
Type C indications concentrate commercial activity; Type A presentations face the steepest therapeutic development barriers.
Delivery Mode:
Route selection determines manufacturing complexity, with CNS-directed administration requiring specialized formulation and handling infrastructure.
- Intravenous:Established vascular access for enzyme replacement and gene therapy systemic distribution. Infusion center capacity at academic medical centers anchors patient throughput for commercial programs.
- Intrathecal:Direct CNS delivery via lumbar puncture or intraventricular reservoir enables therapeutic concentrations in brain parenchyma. AAV9 capsid engineering reduces required dosing volumes while preserving neuronal tropism.
- Subcutaneous:Patient-administered maintenance regimens for substrate reduction therapy.
- Oral:Small-molecule blood-brain barrier penetration for chronic Type C management.
Intravenous administration dominates current treatment volume; Intrathecal delivery is gaining share fastest among development-stage programs.
End User:
Patient concentration into accredited excellence hubs reshapes channel economics and referral pattern capture for therapeutic sponsors.
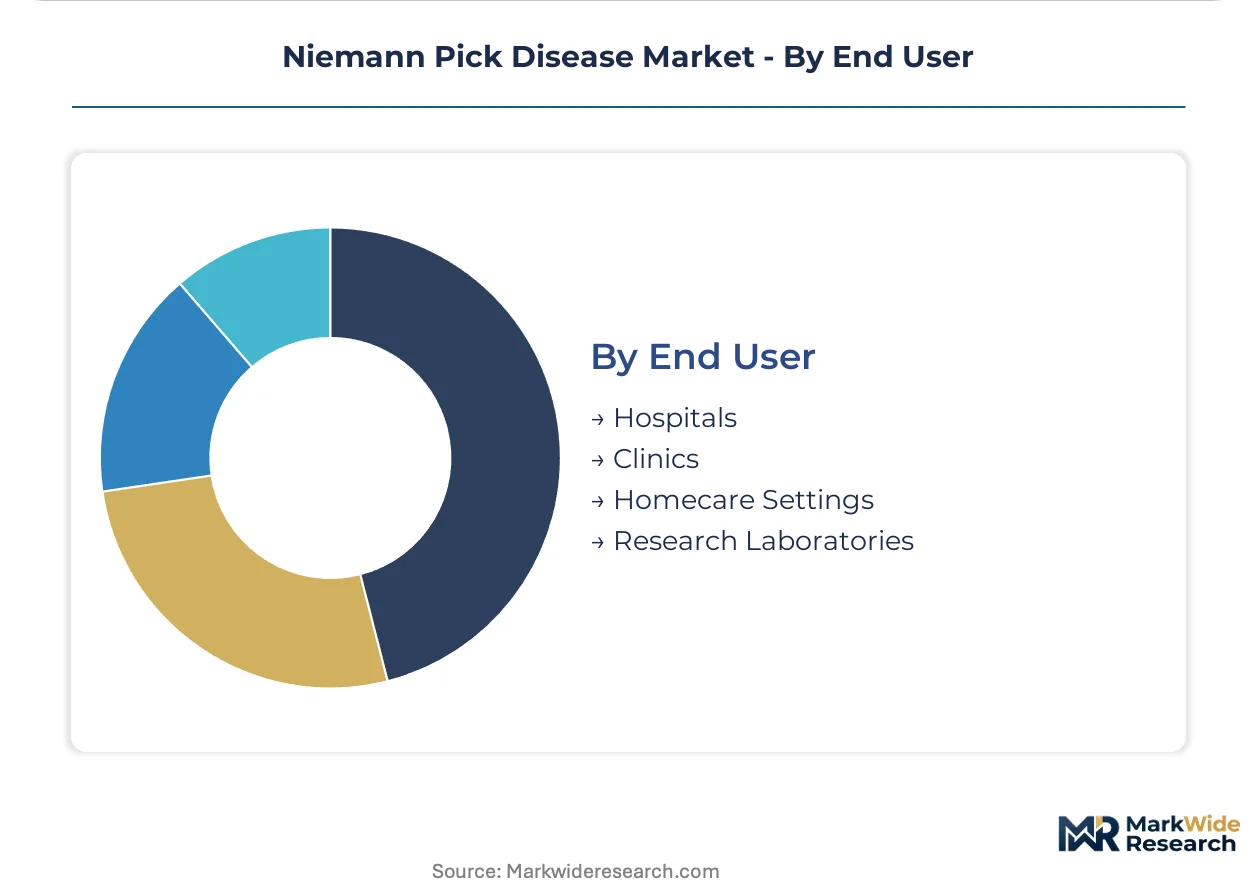
- Hospitals:Tertiary academic centers with dedicated biochemical genetics programs anchor complex lysosomal storage disorder management. FDA-recognized centers of excellence at Cincinnati Children's, Mount Sinai, and Johns Hopkins compress diagnostic delays and treatment initiation timelines.
- Research Laboratories:Natural history study coordination and biomarker validation for regulatory submission packages. NPC1/NPC2 patient registries sponsored by the National Niemann Pick Disease Foundation enable real-world evidence generation.
- Clinics:Community neurology and metabolic practices for stable patient monitoring.
- Homecare Settings:Subcutaneous enzyme administration and nursing support for chronic maintenance.
Hospitals retain volume leadership; Research Laboratories hold the steepest expansion curve as gene therapy trials proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing capacity concentrates in the United States and Western Europe, with viral vector production queues stretching across eighteen months at contract development organizations. Academic medical centers in North America and Europe anchor patient identification networks for ultra-rare lysosomal storage disorders.
United States
The FDA's orphan drug tax credits and seven-year market exclusivity provisions drive sponsor investment in Niemann-Pick clinical programs. Johns Hopkins, Mount Sinai, and Cincinnati Children's operate FDA-recognized centers of excellence that compress diagnostic delays. Texas, New York, and Illinois have expanded newborn screening panels to capture presymptomatic Type C cases.
Germany
The EMA's PRIME designation pathway accelerates assessment timelines for breakthrough therapies targeting neurodegenerative progression. German academic hospitals coordinate natural history studies through European reference networks for rare diseases. Heidelberg and Munich anchor biochemical genetics programs that feed cross-border patient referral flows.
Switzerland
Swissmedic maintains streamlined authorization procedures for gene therapy platforms addressing ultra-rare indications. Basel and Zurich concentrate pharmaceutical development infrastructure with specialized viral vector manufacturing capabilities. The country's proximity to EMA headquarters facilitates regulatory dialogue for sponsors pursuing centralized marketing authorization.
United Kingdom
NHS England's specialized commissioning framework directs ultra-rare disease funding toward designated treatment centers. London and Manchester host national referral pathways for lysosomal storage disorder management. The MHRA's innovative licensing pathway offers conditional approval mechanisms for therapies demonstrating early efficacy signals.
Japan
PMDA's Sakigake designation system prioritizes review resources for regenerative medicine and gene therapy candidates. Tokyo and Osaka academic medical centers maintain patient registries that align with WHO diagnostic nomenclature standards. The country's aging demographics expand the addressable pool of adult-onset Type C presentations.
Niemann Pick Disease Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Niemann-Pick disease landscape. Large-cap pharmaceutical sponsors leverage lysosomal storage disorder infrastructure and established regulatory relationships, while mid-cap biotechs concentrate on platform-specific innovation. The competitive terrain separates into three strategic archetypes: diversified rare disease incumbents, gene therapy specialists, and small-molecule platform developers. Dominant competitive moves include strategic partnerships for viral vector manufacturing access and portfolio diversification into complementary CNS delivery technologies.
Within the diversified rare disease tier, Sanofi and Novartis occupy positions anchored by broad lysosomal storage disorder portfolios and European regulatory experience. Among gene therapy specialists, Sarepta Therapeutics exemplifies the archetype of platform developers pursuing CNS-directed AAV delivery for neurodegenerative indications. Cyclo Therapeutics represents the small-molecule platform category with cyclodextrin-based chemistry for Type C substrate reduction. Zevra Therapeutics sits within the innovation-focused segment pursuing blood-brain barrier penetrant approaches for neurodegenerative progression.
| Leading Market Players |
|---|
| Sanofi |
| Novartis |
| Cyclo Therapeutics |
| Zevra Therapeutics |
| Pfizer |
| IntraBio |
| Sarepta Therapeutics |
| Janssen Global Services |
| Azafaros |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month viral vector production queues at North American and European contract manufacturers compress sponsor cash runways and concentrate pricing power among CDMOs with stainless steel bioreactor infrastructure. This lead-time bottleneck forces gene therapy developers to accept premium manufacturing contracts or delay clinical enrollment, embedding cost escalation into one-time curative therapy economics.
Pricing Analysis
FDA's orphan drug exclusivity provisions dictate the pricing tier structure for Niemann-Pick therapies, with seven-year market protection enabling value-based pricing for enzyme replacement and gene therapy candidates. Price differentiation rests on CNS penetration capability and administration route complexity, with intrathecal delivery commanding premium positioning over intravenous alternatives. Cost compression in chronic maintenance regimens is intensifying because gene therapy candidates threaten to displace recurring infusion revenues. Hospital procurement committees exhibit highest price sensitivity for standard-of-care enzyme replacement, while specialized treatment centers show lowest sensitivity for breakthrough gene therapy access.
Supply Chain Analysis
Plasmid DNA supply concentration at a handful of North American and European contract manufacturers creates the dominant chokepoint for AAV vector production. Manufacturing feedstocks draw from specialized cell culture media suppliers in the United States, Germany, and Switzerland, with proprietary serum-free formulations anchoring batch consistency. Single-source vulnerability in lentiviral vector packaging cell lines threatens program continuity for late-stage gene therapy trials. Distribution runs through cold-chain logistics networks serving FDA-recognized centers of excellence at Cincinnati Children's, Mount Sinai, and Johns Hopkins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
One-time gene therapy administration threatens to collapse recurring revenue streams for chronic enzyme replacement incumbents, forcing defensive portfolio restructuring before clinical substitution materializes.
For Market Incumbents: Shield revenue concentration in Type B enzyme replacement by securing exclusive supply agreements with academic medical center infusion networks. Accelerate intrathecal delivery platform investments to match gene therapy CNS penetration before AAV9 candidates reach Phase III. Vertical integration into viral vector manufacturing capacity in Switzerland or Germany reduces CDMO queue dependency. For New Entrants and Emerging Players: Lead with blood-brain barrier penetrant small-molecule platforms for Type C neurodegenerative progression, where substrate reduction therapy gaps persist and regulatory pathways are established. Target presymptomatic patient identification through Texas, New York, and Illinois newborn screening expansion. Pursue EMA PRIME designation to compress European authorization timelines ahead of larger competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical lysosomal storage disorder divisions facing gene therapy disruption. Five-to-ten-year viability hinges on CNS-directed delivery capabilities and manufacturing infrastructure access rather than molecule exclusivity alone. Monitor AAV9 capsid engineering patent filings as the inflection signal for platform differentiation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO capacity reservation at European viral vector facilities secures eighteen-month clinical enrollment timelines. |
| Regulatory Approval Pathway | FDA fast-track designation compresses review periods for Type A CNS-penetrant enzyme replacement candidates. |
| Pipeline Diversification | Intrathecal delivery platform expansion spreads development risk across systemic and CNS administration routes. |
| Licensing Agreement | AAV9 capsid engineering partnerships with academic spinouts accelerate neuronal tropism optimization programs. |
| Reimbursement Strategy | CMS new technology add-on payment applications anchor hospital margin protection for one-time gene therapy administration. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down therapeutic modality revenue allocation converged across the analysis window.
Sensitivity analysis tested forecast robustness against manufacturing capacity constraints, regulatory timeline variations, and newborn screening expansion scenarios. Segmentation dimensions spanned treatment modality, indication type, delivery route, and regional regulatory cluster. CAGRs derived from natural history study enrollment trajectories and payer coverage expansion curves, with gene therapy manufacturing bottlenecks and academic medical center referral network density as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA orphan drug incentive continuity or CDMO capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding clinical trial success rates and reimbursement pathway clarity. Practitioners should keep alternative scenarios live as EMA PRIME designation utilization and neonatal screening panel adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Spina Bifida Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Lennox-Gastaut Syndrome Market