
 Pediatric Obesity Management Market | 2026-2036
Pediatric Obesity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Obesity Management Market Analytics
Evidence-based clinical intervention standards are unwinding outdated lifestyle-only protocols and elevating reimbursement thresholds for reimbursed pediatric obesity programs. Novo Nordisk leverages its endocrinology pipeline depth to anchor metabolic drug development for adolescent populations. Eli Lilly and Company competes through scaled GLP-1 manufacturing capacity that sustains supply security for pediatric indications.
Pediatric obesity management encompasses structured clinical, nutritional, pharmacological, and behavioral interventions targeting adiposity reduction and metabolic risk mitigation in patients under eighteen years, typically involving BMI percentile assessment, caloric modulation protocols, and supervised physical activity regimens designed to prevent progression to type 2 diabetes and cardiovascular comorbidity. The delivery mode dimension shows telehealth services capturing disproportionate growth as rural access gaps and post-pandemic care preferences reshape channel economics, while in-person counseling retains premium reimbursement positioning for complex metabolic cases. Nutritional supplements within the product type category occupy mature volume positions with thin margin profiles, whereas weight management apps concentrate venture funding and user acquisition investment.
The FDA maintains stringent pediatric trial requirements for anti-obesity pharmacotherapies through its Division of Metabolism and Endocrinology Products, while the EMA's Paediatric Committee mandates juvenile investigation plans that extend development timelines and inflate regulatory costs for sponsors. HIPAA compliance frameworks and state-level telehealth licensing boards additionally shape how online programs and mobile apps architect data governance and provider credentialing across jurisdictions. Stakeholders must monitor evolving payer prior authorization criteria for pharmacological interventions versus lifestyle program coverage to align portfolio investments with reimbursement trajectories.
Market Dynamics
GLP-1 receptor agonist approvals for adolescent populations are restructuring clinical protocols and payer reimbursement frameworks across hospital systems and outpatient networks.
Growth Catalysts
- FDA Pediatric Label Expansions:The FDA Division of Metabolism and Endocrinology Products has cleared weight-loss pharmacotherapies for patients aged twelve and above, creating reimbursable treatment pathways that hospital-based programs can operationalize.
- Telehealth Infrastructure:Rural health systems in the United States are deploying remote patient monitoring platforms to extend metabolic specialist access into underserved counties with no pediatric endocrinology presence.
- Metabolic Comorbidity Screening Mandates:State Medicaid programs are embedding BMI percentile tracking with automatic referral triggers into early childhood health supervision visits.
Market Restraints
- EMA Paediatric Investigation Plans:The European Medicines Agency mandates extended juvenile toxicology studies that inflate development timelines and regulatory costs for sponsors seeking adolescent indications.
- Specialist Workforce Concentration:Board-certified pediatric obesity physicians cluster in academic medical centers across fifteen US metropolitan areas, leaving exurban and micropolitan markets with coverage gaps.
- Behavioral Intervention Substitution:Family-based lifestyle modification programs remain the first-line covered benefit under most commercial payers, limiting pharmacotherapy penetration to step-therapy failures.
Strategic Opportunities
- Digital Therapeutics Integration:Prescription-grade mobile applications for dietary self-monitoring are securing FDA 510(k) clearance as software-as-a-medical-device, opening pharmacy benefit coverage pathways.
- School-Based Screening Contracts:District-level health services in Texas, California, and Florida are procuring outsourced BMI assessment and care coordination platforms for K-12 populations.
- Continuous Glucose Monitoring Convergence:Wearable metabolic sensors paired with weight management apps are creating closed-loop feedback systems that endocrinology practices can bill as remote physiologic monitoring.
Industry Challenges
- Pediatric Endocrinology Fellowship Pipeline:Accreditation Council for Graduate Medical Education slots produce fewer than fifty new specialists annually, constraining program scale-up capacity.
- Prior Authorization Administrative Burden:GLP-1 agonist coverage requires documented lifestyle intervention failure, step therapy completion, and comorbidity verification that consumes 4.2 full-time-equivalent staff hours per approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Obesity Management Market |
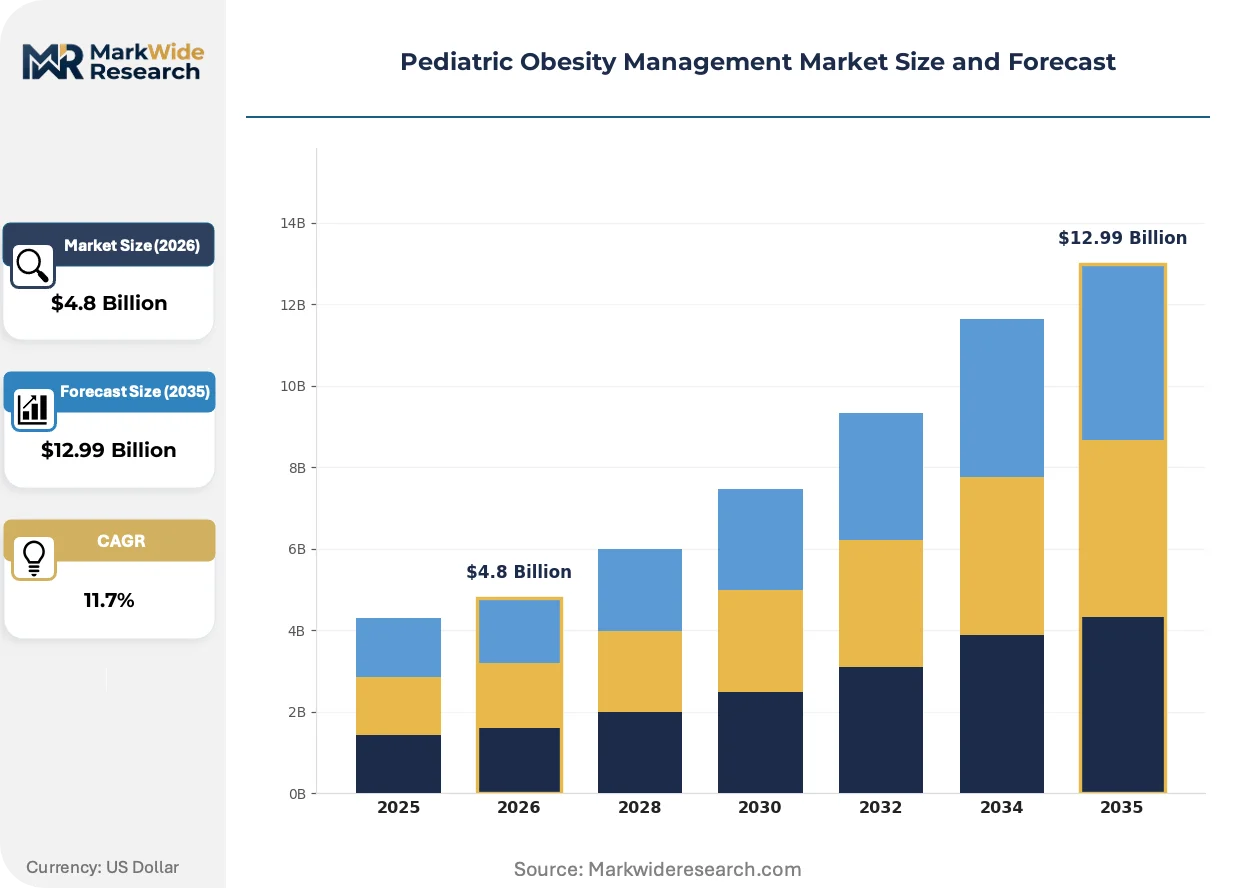
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Supplements, Fitness Equipment, Weight Management Apps, Meal Plans Delivery Mode: In-person Counseling, Online Programs, Mobile Apps, Telehealth Services End User: Children, Parents, Schools, Healthcare Providers Service Type: Individual Counseling, Group Sessions, Workshops, Nutritional Education |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Medtronic, Pfizer, Johnson & Johnson, F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb, Abbott Laboratories, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Obesity Management Market Evolving Landscape
Continuous metabolic monitoring hardware and AI-enabled dietary coaching platforms are compressing the interval between clinical encounters and enabling real-time intervention adjustment.
Implantable gastric stimulation devices designed for adolescent anatomy are miniaturizing from laparoscopic-pacemaker scale to endoscopically-deployable form factors. Pediatric surgery departments at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center are piloting these systems for patients failing pharmacologic therapy. The technology is miniaturizing procedural risk profiles and expanding candidacy to younger age brackets previously excluded from device trials.
The FDA's 2023 guidance on pediatric obesity drug development mandates cardiovascular outcome data and growth velocity tracking that extends Phase III programs by eighteen to twenty-four months. Sponsors must enroll sufficient pubertal-stage diversity across Tanner classifications to satisfy the Division of Metabolism and Endocrinology Products. These requirements are compressing venture financing timelines and forcing development-stage firms toward partnership structures with established endocrinology players.
Employer-sponsored health plans are unbundling pediatric weight management from bundled maternity-pediatric contracts and negotiating direct agreements with regional children's hospital networks. This purchasing pattern is disintermediating traditional managed care organizations in markets where dominant pediatric systems command narrow-network leverage. The shift is most visible in self-insured manufacturing and logistics employers across the Midwest and Southeast seeking onsite clinic integration with metabolic programming.
Pediatric Obesity Management Market Segmentation
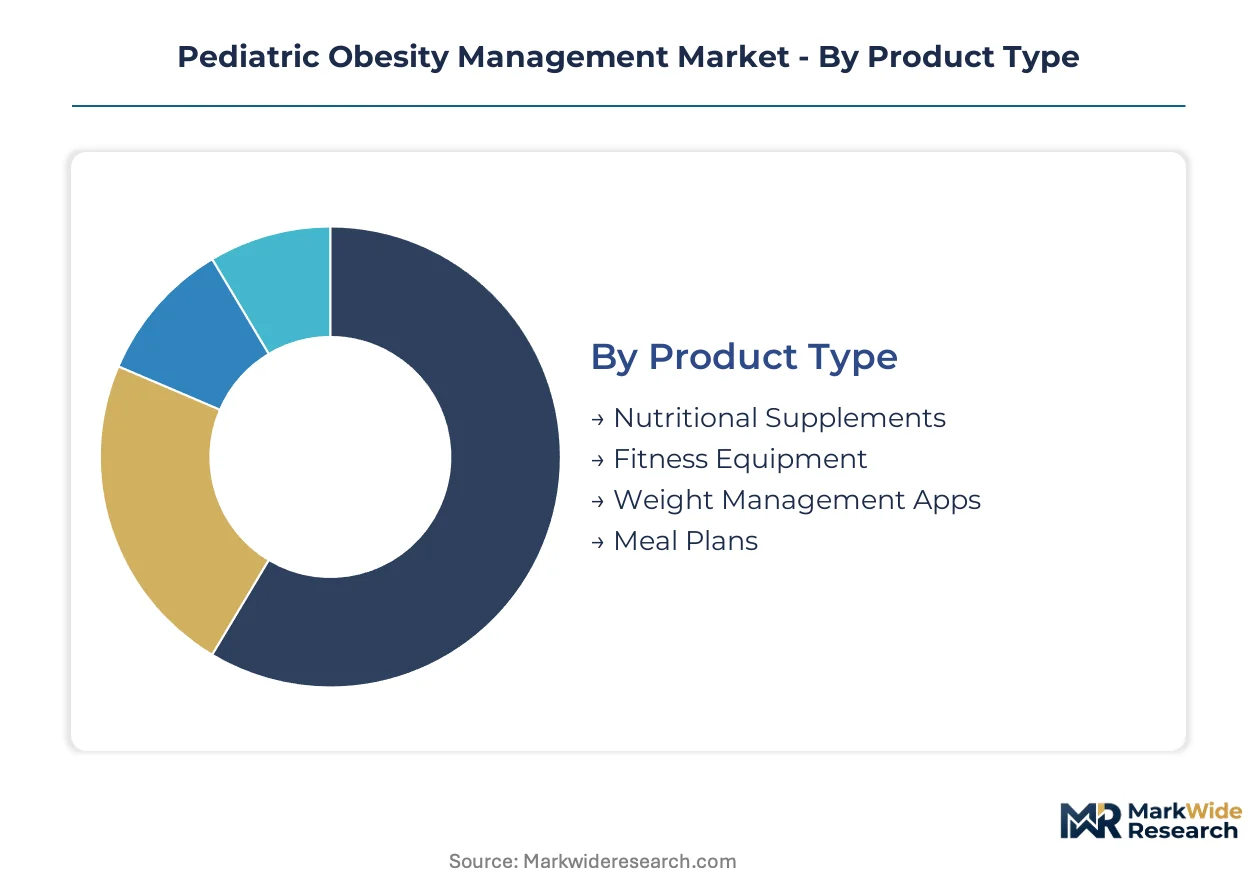
Segmentation in pediatric obesity management reveals how substitution pressures reshape competitive boundaries across product and service categories. Each dimension carries distinct margin profiles and regulatory exposure that determine portfolio prioritization for hospital systems, digital health firms, and pharmaceutical sponsors.
Product Type:
Substitution pressure from GLP-1 pharmacotherapies threatens legacy hardware and supplement categories most severely, while software-enabled solutions capture displaced investment.
- Nutritional Supplements:Formulations include protein powders, micronutrient complexes, and fiber-based satiety aids positioned as adjuncts to clinical protocols. Demand concentrates in retail pharmacy chains across the United States where Medicaid formulary inclusion drives volume, though margin compression from private-label competition limits manufacturer profitability.
- Weight Management Apps:Prescription-grade platforms with FDA 510(k) clearance for dietary self-monitoring integrate continuous glucose monitoring data streams. Venture funding concentrates on adolescent-specific UX design and HIPAA-compliant data architecture that satisfies state telehealth licensing requirements.
- Fitness Equipment:Pediatric-calibrated resistance bands, activity trackers, and home exercise systems designed for BMI percentile improvement protocols.
- Meal Plans:Clinician-prescribed caloric modulation programs delivered through hospital-based registered dietitian networks.
Nutritional Supplements anchors the volume base while Weight Management Apps gains share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium reimbursed encounters from self-pay digital access, with reimbursement eligibility determining channel economics.
- Telehealth Services:Remote patient monitoring platforms extend pediatric endocrinology access into rural counties lacking specialist presence. Texas and Florida Medicaid programs now reimburse synchronous video visits for BMI percentile counseling, creating viable unit economics for regional children's hospital outreach.
- In-person Counseling:Hospital-based programs deliver supervised physical activity regimens and metabolic risk assessment through academic medical centers. Board-certified pediatric obesity physicians cluster in fifteen US metropolitan areas, constraining scale-up capacity and sustaining premium pricing for complex cases.
- Online Programs:Asynchronous educational modules and progress tracking portals with lower reimbursement positioning.
- Mobile Apps:Consumer-facing wellness applications operating outside prescription pathways with direct-to-family revenue models.
In-person Counseling anchors the volume base while Telehealth Services expands most quickly as rural access gaps persist.
End User:
Application concentration varies sharply across institutional procurement versus individual purchase decision-making.
- Healthcare Providers:Hospital systems and outpatient clinics operationalize reimbursable treatment pathways using FDA-cleared pharmacotherapies for patients aged twelve and above. EMA Paediatric Committee mandates for juvenile investigation plans delay European market entry, concentrating near-term revenue in US-based provider networks.
- Schools:District-level health services in California, Texas, and Florida procure outsourced BMI assessment platforms with automatic referral triggers embedded in K-12 health supervision visits.
- Children:Direct-to-patient interventions requiring parental consent frameworks and age-appropriate engagement design.
- Parents:Family-based lifestyle modification programs that remain first-line covered benefits under most commercial payers.
Healthcare Providers anchors the volume base while Schools climbs the fastest as district procurement scales.
Service Type:
Margin profiles separate high-touch clinical encounters from scalable educational programming with lower credentialing requirements.
- Individual Counseling:One-on-one sessions with registered dietitians or board-certified pediatric obesity physicians deliver personalized caloric modulation and behavioral intervention. Prior authorization requirements for GLP-1 agonist coverage demand documented lifestyle intervention failure, sustaining demand for documented individual encounters.
- Nutritional Education:Structured curricula on macronutrient balance, portion control, and metabolic risk mitigation delivered through group formats. Employer-sponsored health plans negotiate direct agreements with children's hospital networks for onsite clinic integration, disintermediating traditional managed care organizations.
- Group Sessions:Peer-supported interventions with lower per-patient cost and reduced specialist time requirements.
- Workshops:Time-limited intensive programs targeting specific skills such as meal preparation or activity planning.
Individual Counseling anchors the volume base while Nutritional Education shows the steepest expansion trajectory as employer direct contracting grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified pediatric obesity physicians cluster in fifteen United States metropolitan areas, creating supply-side concentration that shapes regional access patterns and reimbursement arbitrage opportunities across developed markets.
United States
Hospital-based weight management programs at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center anchor clinical innovation. The FDA Division of Metabolism and Endocrinology Products has cleared GLP-1 receptor agonists for patients aged twelve and above, creating reimbursable treatment pathways. Texas and Florida Medicaid programs now reimburse synchronous video visits for BMI percentile counseling, extending specialist reach into rural counties.
Germany
Academic medical centers in Munich and Heidelberg operationalize structured family-based lifestyle modification protocols. The EMA Paediatric Committee mandates extended juvenile toxicology studies that inflate regulatory costs for sponsors seeking adolescent indications. Bavarian pediatric endocrinology networks are piloting continuous glucose monitoring convergence with weight management apps for closed-loop metabolic feedback.
United Kingdom
NHS England's tiered weight management services embed BMI percentile tracking with automatic referral triggers into primary care. The National Institute for Health and Care Excellence maintains stringent cost-effectiveness thresholds for pharmacotherapy coverage that limit GLP-1 agonist penetration. London-based pediatric obesity programs are securing direct agreements with employer-sponsored health plans, disintermediating traditional managed care structures.
France
ANSM maintains pediatric trial requirements that align with EMA juvenile investigation plans, extending development timelines for metabolic drug sponsors. The country's national pharmaceutical regulator coordinates with hospital-based nutrition networks in Paris and Lyon to standardize caloric modulation protocols. French pediatric endocrinology fellowship programs produce fewer than fifteen specialists annually, constraining program scale-up capacity.
Japan
PMDA pediatric obesity drug approvals require growth velocity tracking and cardiovascular outcome data that extend Phase III programs. METI-funded telehealth infrastructure projects extend metabolic specialist access into rural prefectures lacking pediatric endocrinology presence. Tokyo and Osaka academic medical centers are piloting implantable gastric stimulation devices miniaturized for adolescent anatomy.
Pediatric Obesity Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pediatric obesity management market. The structure fragments across pharmaceutical sponsors with endocrinology pipeline depth, medical device manufacturers with metabolic monitoring hardware, and digital health firms with software-as-a-medical-device platforms. Three archetypes dominate: GLP-1 agonist developers with manufacturing scale, continuous glucose monitoring specialists with sensor convergence capabilities, and prescription-grade app developers with FDA 510(k) clearance. Competitive moves concentrate on strategic partnerships between pharmaceutical sponsors and digital therapeutics firms, plus capacity expansion for adolescent-specific drug manufacturing.
Within the pharmaceutical developer tier, Novo Nordisk and Eli Lilly and Company exemplify divergent strategic positioning. Novo Nordisk anchors metabolic drug development through endocrinology pipeline depth and pediatric label expansion capabilities. Eli Lilly and Company occupies a scale-driven position through GLP-1 manufacturing capacity that sustains supply security for adolescent indications. Medtronic sits within the device convergence archetype, representing continuous monitoring hardware integration with weight management platforms.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Medtronic |
| Pfizer |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb |
| Abbott Laboratories |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
GLP-1 receptor agonist substitution of legacy nutritional supplements and behavioral hardware simultaneously concentrates manufacturing geography around Novo Nordisk's Danish production network and Eli Lilly's Indianapolis campus while compressing pricing power for incumbent supplement manufacturers facing Medicaid formulary exclusion pressures.
Pricing Analysis
FDA pediatric label expansion requirements dictate the pricing tier structure across pharmacological and non-pharmacological interventions. Three-tier pricing structure across premium reimbursed GLP-1 therapies, mid-tier telehealth counseling bundles, and economy self-pay mobile applications separates hospital-based programs from direct-to-consumer wellness tools. Cost compression in the nutritional supplement tier intensifies because private-label competition and Medicaid generic preference policies squeeze branded formulations. Employer-sponsored health plans demonstrate lowest price sensitivity for FDA-cleared prescription platforms, while individual families purchasing direct-to-patient apps exhibit highest sensitivity to out-of-pocket costs.
Supply Chain Analysis
Denmark and the United States anchor GLP-1 active pharmaceutical ingredient fermentation and fill-finish capacity for adolescent indications. Raw material dependencies center on recombinant DNA cell lines, specialized bioreactor media, and cold-chain distribution infrastructure for temperature-sensitive peptide therapies. Single-source vulnerability runs through concentrated API manufacturing sites subject to FDA inspection scheduling and EMA import certification delays. Distribution runs through specialty pharmacy networks and hospital outpatient infusion centers rather than retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against GLP-1 pharmacotherapy substitution that threatens legacy hardware and supplement revenue streams while capturing displaced investment flows into digital therapeutics integration.
For Market Incumbents: Consolidate hospital system partnerships through exclusive provider network agreements that lock in referral pathways for complex metabolic cases. Deepen backward integration into continuous glucose monitoring hardware to create closed-loop feedback systems that endocrinology practices can bill as remote physiologic monitoring, defending against pure-play digital health entrants. For New Entrants and Emerging Players: Differentiate on adolescent-specific UX design and HIPAA-compliant data architecture that satisfies Texas and Florida state telehealth licensing requirements. White-space targets include school district procurement contracts for K-12 BMI assessment platforms in California and employer direct agreements for onsite clinic metabolic programming across Midwest manufacturing corridors. Go-to-market angle: prescription-grade mobile applications securing FDA 510(k) clearance as software-as-a-medical-device to unlock pharmacy benefit coverage. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors digital therapeutics firms with FDA 510(k) clearance and established hospital system distribution. Long-term viability over the next decade hinges on convergence between pharmaceutical sponsors and software-enabled platforms rather than standalone device or supplement manufacturers. Acquisition target archetype: prescription-grade app developers with adolescent-specific engagement metrics and existing payer contracts. Signal to watch: employer-sponsored health plan unbundling of pediatric weight management from bundled maternity-pediatric contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA pediatric label expansions for GLP-1 agonists create reimbursable treatment pathways for hospital-based programs. |
| Strategic Partnership | Digital therapeutics integration with pharmaceutical sponsors enables closed-loop metabolic feedback systems for endocrinology practices. |
| Reimbursement Strategy | Pharmacy benefit coverage for prescription-grade mobile applications opens sustainable revenue models beyond direct-to-consumer subscriptions. |
| Hospital System Partnership | Exclusive provider network agreements with regional children's hospitals secure referral pathways and narrow-network leverage. |
| Software Companion Development | Continuous glucose monitoring convergence with weight management apps creates billable remote physiologic monitoring encounters. |
Research Methodology
Cross-validation between regulatory filing databases and hospital procurement records anchors the qualitative findings on payer coverage expansion and clinical protocol adoption. Primary interviews with pediatric endocrinology fellowship directors, hospital formulary committee members, Medicaid program administrators, and digital health venture capitalists combined with secondary validation through FDA Division of Metabolism and Endocrinology Products guidance documents, EMA Paediatric Committee investigation plans, state Medicaid fee schedules, and employer health plan benefit design filings. Bottom-up triangulation across service line revenue estimates and top-down validation through pharmaceutical sponsor pipeline disclosures ensure analytical consistency.
Sensitivity analysis around GLP-1 penetration rates and telehealth reimbursement policy scenarios frames the forecast uncertainty bands across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and service type, with additional granularity on pediatric age brackets and regional regulatory clusters. CAGRs derive from weighted average of historical adoption curves for analogous metabolic interventions and scenario-adjusted uptake assumptions. Industry-specific forecast inputs incorporate pediatric endocrinology fellowship graduation rates and FDA pediatric trial enrollment timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA pediatric label expansion and employer direct contracting acceleration would require recalibration. Forecasts reflect assumptions on payer prior authorization burden reduction and specialist workforce pipeline expansion that remain exposed to policy reversal or training program accreditation constraints. Recalibration cycles align with material shifts in GLP-1 formulary positioning and state Medicaid telehealth parity legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Paediatric Influenza Treatment Market