
 Pediatric MRI Market | 2026-2036
Pediatric MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric MRI Market Analytics
Pediatric hospitals are reorganizing procurement priorities around sedation-free imaging protocols, shifting volume away from general diagnostic centers. Siemens Healthineers leverages its MAGNETOM platform to dominate high-field installations across tertiary children's hospitals. GE Healthcare anchors its position through specialized pediatric coil arrays and protocol packages. Koninklijke Philips NV competes on ambient experience designs that reduce anesthesia dependency in claustrophobic young patients.
Pediatric MRI denotes magnetic resonance imaging systems engineered for neonatal through adolescent anatomy, typically operating at 1.5T or 3.0T field strength with specialized radiofrequency coils sized for smaller body habitus and enhanced gradient performance for motion-robust sequences. These systems serve primarily to diagnose congenital neurological malformations, characterize pediatric tumors, and monitor musculoskeletal development without ionizing radiation exposure. Closed MRI systems command the largest installed base due to superior signal-to-noise ratios for cranial imaging, though open MRI architectures gain traction among anxiety-prone populations where claustrophobia drives protocol failure. Low-field MRI technology represents the fastest-expanding technology segment as Hyperfine Inc. and emerging vendors validate point-of-care deployment models. Neurological disorders anchor application demand through epilepsy protocol volumes and pre-surgical functional mapping.
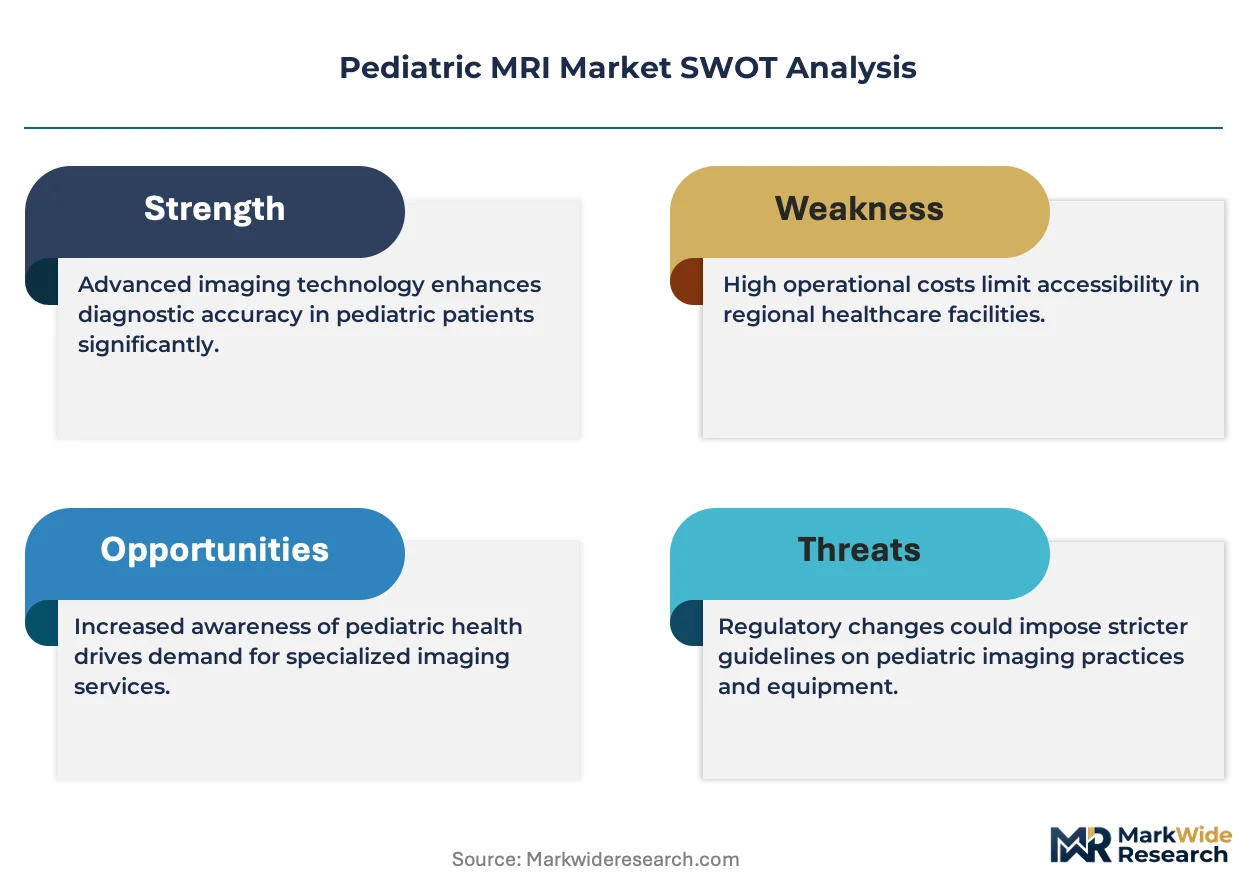
FDA 510(k) premarket notification requirements govern device clearance for pediatric-specific indications, while IEC 60601-2-33 standards constrain electromagnetic field exposure limits for vulnerable populations. The EU Medical Device Regulation imposes additional clinical evidence thresholds for pediatric labeling, shaping manufacturer R&D allocation toward European market access. Stakeholders must monitor how decentralized low-field deployment disrupts traditional capital-equipment purchasing models and whether reimbursement parity follows hardware democratization.
Market Dynamics
Pediatric MRI procurement is pivoting around sedation-free protocol adoption, forcing capital allocation toward ambient-design systems and low-field point-of-care alternatives that reduce anesthesia dependency.
Growth Catalysts
- FDA 510(k) Pediatric Pathways:Streamlined clearance for pediatric-specific imaging protocols accelerates equipment replacement cycles at tertiary children's hospitals seeking protocol differentiation.
- Congenital Anomaly Screening Networks:Dense referral infrastructure in the United States, Germany, and Japan concentrates demand for high-resolution neurological imaging in dedicated pediatric suites.
- Low-Field Point-of-Care Deployment:Hyperfine Inc. and emerging vendors validate bedside MRI models that bypass traditional radiology department workflows for NICU and emergency settings.
Market Restraints
- Helium Supply Concentration:Superconducting magnet cooling depends on helium sourcing from Qatar and the United States, exposing high-field system operators to input cost volatility and supply disruption.
- EU MDR Clinical Evidence Thresholds:The European Medical Device Regulation imposes additional pediatric labeling requirements that extend R&D timelines and compress European market access for specialized coil manufacturers.
- Ionizing Radiation Substitution:CT protocols retain cost and speed advantages for trauma and acute abdominal indications, limiting MRI penetration in time-sensitive diagnostic pathways.
Strategic Opportunities
- India Pediatric Imaging Gap:Underpenetrated tertiary care infrastructure in Maharashtra and Tamil Nadu creates whitespace for 1.5T systems with pediatric coil packages as hospital chains expand.
- AI-Accelerated Scanning Convergence:Deep learning reconstruction algorithms combined with motion-robust sequences enable diagnostic-quality imaging without sedation, opening ambulatory pediatric settings.
- Japan METI Carbon Neutrality Incentives:Government subsidies for energy-efficient medical equipment favor low-field and permanent-magnet MRI deployments in municipal children's hospitals.
Industry Challenges
- Pediatric Radiologist Workforce Scarcity:Specialized training programs in neuroradiology and pediatric body imaging produce insufficient fellowship graduates to staff expanding imaging suite capacity.
- Legacy PACS Integration Friction:Point-of-care low-field systems require middleware development to communicate with hospital-wide radiology information systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric MRI Market |
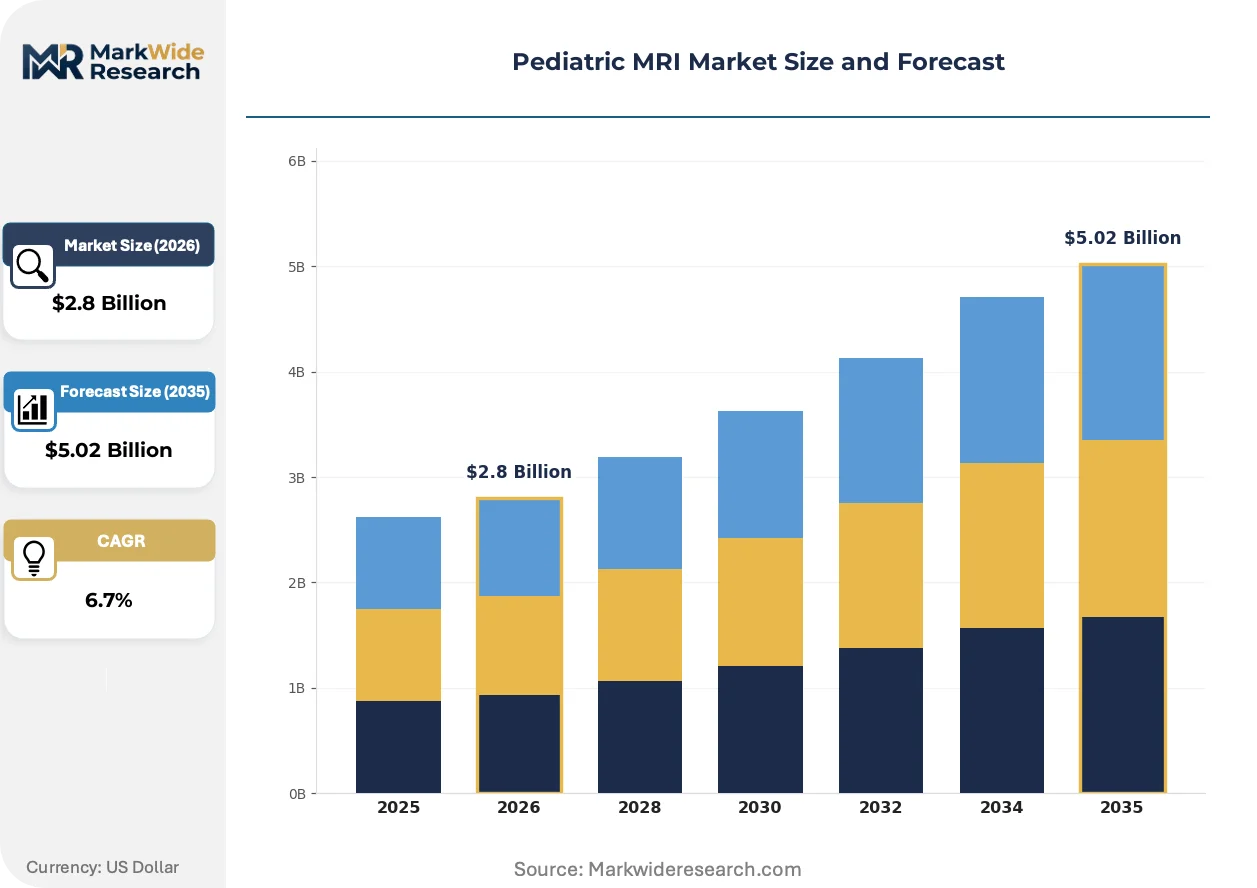
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Technology: High-Field MRI, Low-Field MRI, Magnetic Resonance Angiography, Specialized Pediatric Protocols End User: Pediatric Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Clinics Application: Neurological Disorders, Musculoskeletal Issues, Oncology, Cardiac Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Hyperfine Inc., Aspect Imaging Ltd, Neoscan Solutions GmbH, LMT Medical Systems GmbH, NORAS MRI Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric MRI Market Evolving Landscape
Low-field MRI architectures are disrupting traditional capital-equipment hierarchies by validating clinical utility outside radiology departments. Three forces are compressing conventional procurement patterns.
Permanent-magnet and resistive low-field systems operating below 0.5T are supplanting superconducting high-field scanners in NICU and emergency settings where patient transport risks and anesthesia contraindications dominate clinical decision-making. Children's Hospital of Philadelphia and Cincinnati Children's Hospital Medical Center have piloted bedside deployment models. This shift is compressing the addressable market for conventional 1.5T installations in acute care environments.
The EU Medical Device Regulation's pediatric labeling requirements are forcing manufacturers to generate dedicated clinical evidence for neonatal and adolescent populations. Siemens Healthineers and GE Healthcare have restructured European regulatory submissions around age-stratified safety data. Pediatric-specific coil arrays and protocol packages now carry distinct CE marking pathways that lag adult-equivalent approvals by 18-24 months.
Hospital procurement committees are unbundling after-sales service contracts from capital purchases, pressuring OEMs to compete on discrete maintenance and upgrade pricing. Tertiary children's hospitals in Texas, California, and New York have led this disintermediation, sourcing third-party magnet maintenance and software support independently. This compression is most visible in academic medical centers with captive biomedical engineering capacity.
Pediatric MRI Market Segmentation
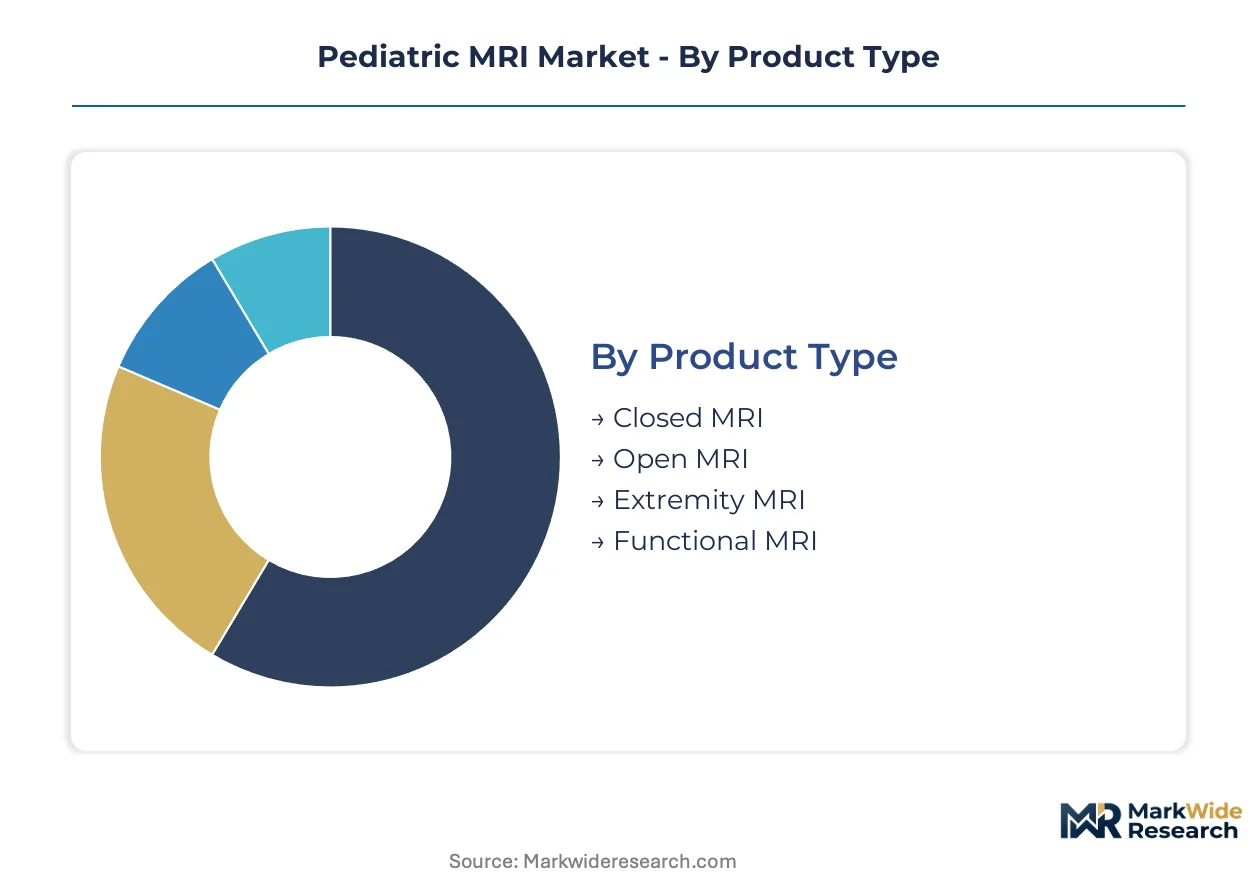
Pediatric MRI segmentation reveals how clinical priorities diverge from adult imaging markets. Procurement committees weight sedation reduction against diagnostic fidelity when allocating capital across product architectures and field strengths.
Product Type:
Margin pools concentrate in closed-system installations where superconducting magnet technology commands premium service contracts and multi-year maintenance agreements.
- Closed MRI:Superconducting cylindrical bore systems operating at 1.5T or 3.0T deliver superior signal-to-noise ratios for cranial imaging in neonates. Tertiary children's hospitals in Boston, Houston, and Philadelphia anchor procurement volume as congenital anomaly screening protocols expand. Magnet cooling requirements and helium sourcing constraints compress operating margins for independent imaging centers.
- Open MRI:Vertical-field or C-shaped architectures eliminate claustrophobia-driven protocol failures in anxiety-prone pediatric populations. Demand concentrates in ambulatory settings across Germany and Japan where anesthesia minimization ranks highest in clinical guidelines. Lower field strength limits resolution for fine neurological structures.
- Extremity MRI:Dedicated limb-only systems reduce scan times for sports medicine and orthopedic monitoring in adolescent athletes.
- Functional MRI:Blood-oxygen-level-dependent imaging for pre-surgical language and motor mapping in epilepsy patients.
The dominant share belongs to Closed MRI, while Open MRI is closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive high-field installations from emerging point-of-care alternatives that bypass traditional radiology infrastructure.
- High-Field MRI:Superconducting systems at 1.5T and 3.0T field strength remain the clinical standard for detecting subtle cortical dysplasias and white matter abnormalities. Siemens Healthineers and GE Healthcare dominate installations at academic medical centers in the United States where neuroradiology fellowship programs train specialized readers. Helium dependency and cryogen maintenance burden constrain deployment in cost-sensitive markets.
- Low-Field MRI:Permanent-magnet and resistive systems below 0.5T validate NICU bedside deployment without patient transport risks. Hyperfine Inc. pilots at Cincinnati Children's Hospital Medical Center and Children's Hospital of Philadelphia demonstrate workflow disruption potential. Image reconstruction algorithms compensate for reduced signal-to-noise ratios.
- Magnetic Resonance Angiography:Contrast-enhanced and non-contrast flow imaging for vascular malformations and congenital heart disease assessment.
- Specialized Pediatric Protocols:Age-optimized sequence libraries with motion-robust acquisition parameters and size-appropriate coil configurations.
High-Field MRI retains the dominant installed base, though Low-Field MRI shows the steepest expansion trajectory.
End User:
Volume concentration follows referral network density for congenital anomaly screening and subspecialty surgical planning.
- Pediatric Hospitals:Dedicated children's hospitals reorganize procurement around sedation-free imaging suites with ambient design features. Texas Children's Hospital, Boston Children's Hospital, and Ann & Robert H. Lurie Children's Hospital of Chicago lead capital replacement cycles. In-house biomedical engineering capacity enables unbundled service contracts.
- Diagnostic Imaging Centers:Independent operators face volume erosion as pediatric hospitals internalize referral flows for specialized protocols.
- Research Institutions:Academic medical centers with NIH-funded neurodevelopmental studies require advanced functional and spectroscopic capabilities.
- Outpatient Clinics:Limited penetration due to anesthesia requirements and radiologist workforce scarcity for pediatric interpretation.
Pediatric Hospitals command the dominant share, while Research Institutions gain share fastest through federal funding expansion.
Application:
Customer type differentiation separates high-acuity neurological indications from elective musculoskeletal monitoring in adolescent populations.
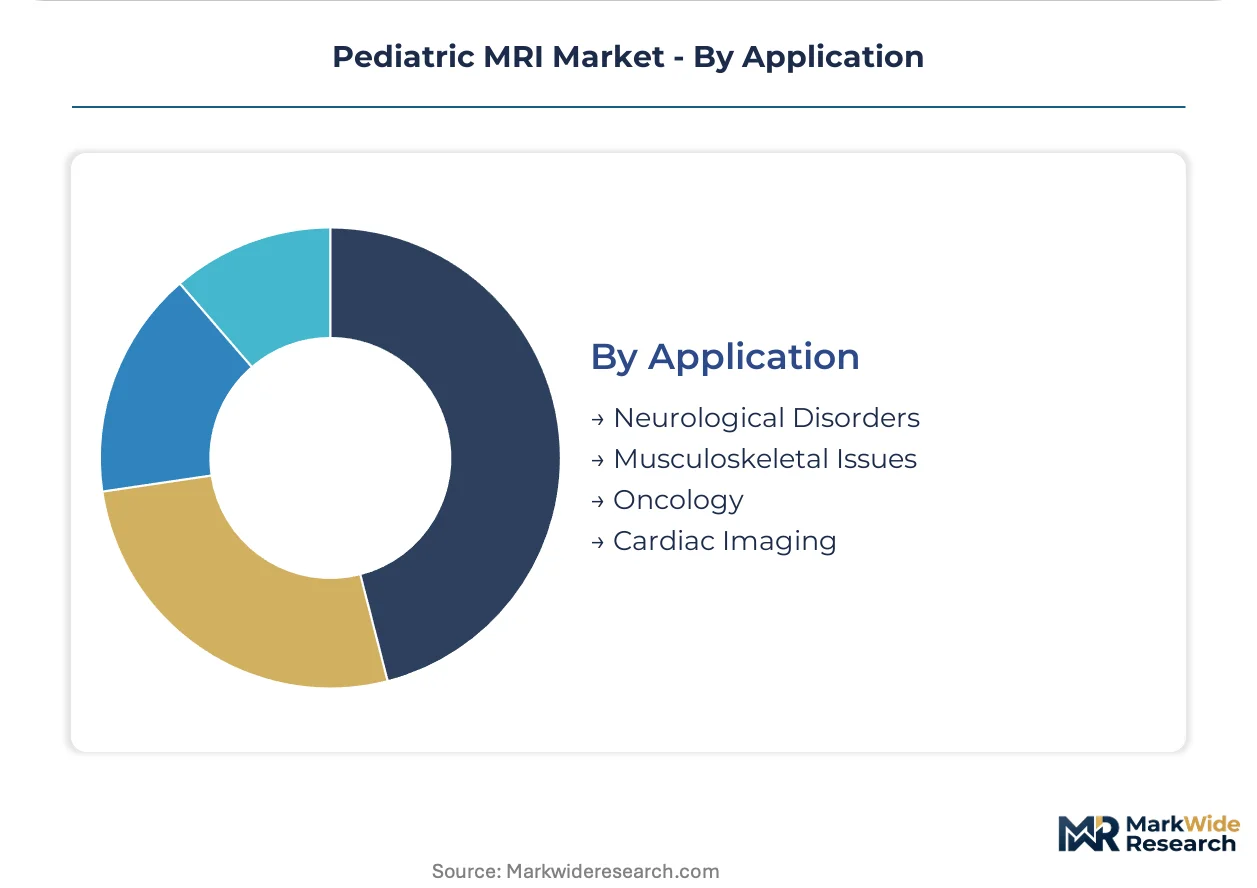
- Neurological Disorders:Epilepsy protocol volumes and pre-surgical functional mapping for tumor resection drive scanner utilization rates. Children's hospitals in Germany and Japan prioritize high-resolution diffusion tensor imaging for white matter tractography. MRI displaces CT for shunt malfunction evaluation to eliminate cumulative ionizing radiation exposure.
- Musculoskeletal Issues:Sports medicine applications in adolescent athletes require rapid turnaround for injury assessment.
- Oncology:Tumor characterization and treatment response monitoring without radiation burden for long-term survivors.
- Cardiac Imaging:Congenital heart disease evaluation competes with echocardiography and CT angiography for diagnostic workflow.
Neurological Disorders anchor the dominant application share, while Cardiac Imaging climbs the fastest as surgical planning protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ronald Reagan UCLA Medical Center's pediatric imaging corridor underwrites California's concentration of high-field MRI installations for congenital anomaly screening.
United States
Pediatric hospitals in Houston, Boston, and Philadelphia drive replacement cycles for 3.0T systems with specialized neonatal coils. FDA 510(k) clearance pathways accelerate protocol differentiation at tertiary children's hospitals. Texas Children's Hospital anchors demand in the Southwest, while Boston Children's Hospital trains neuroradiology fellows who staff expanding imaging suites nationwide.
Germany
Dense referral networks for epilepsy surgery planning concentrate demand in Munich, Heidelberg, and Berlin academic medical centers. EU Medical Device Regulation pediatric labeling requirements extend R&D timelines for coil manufacturers seeking CE marking. Bavaria's university hospitals validate motion-robust sequences that reduce anesthesia dependency in ambulatory settings.
Japan
METI carbon neutrality subsidies favor energy-efficient low-field and permanent-magnet deployments in municipal children's hospitals. Osaka and Nagoya pediatric centers prioritize ambient-design systems for claustrophobia-prone young patients. Kansai-region hospital chains unbundle service contracts to source third-party magnet maintenance independently.
India
Underpenetrated tertiary care infrastructure in Maharashtra and Tamil Nadu creates whitespace for 1.5T systems with pediatric coil packages. CDSCO regulatory pathways for imported medical devices shape procurement timelines at expanding hospital chains. Apollo Hospitals and Fortis Healthcare anchor installations in Chennai and Mumbai metropolitan clusters.
United Kingdom
NHS England specialized commissioning frameworks concentrate pediatric MRI capacity at designated children's hospital trusts in London, Birmingham, and Manchester. MHRA post-Brexit regulatory divergence from EU MDR creates parallel submission requirements for coil manufacturers. Great Ormond Street Hospital pilots AI-accelerated scanning protocols that enable sedation-free ambulatory imaging.
Pediatric MRI Market Competitive Landscape
Concentration sits with diversified imaging conglomerates that leverage installed base scale to lock in multi-year service contracts at tertiary children's hospitals. Siemens Healthineers, GE Healthcare, and Koninklijke Philips NV anchor the premium tier through superconducting high-field platforms with pediatric-specific protocol packages. Strategic moves center on unbundling resistance—defending attach rates for maintenance contracts—and low-field point-of-care expansion to capture NICU bedside workflows outside traditional radiology departments.
Among diversified medical technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the high-field installation archetype, while Hyperfine Inc. occupies a position representing the point-of-care disruption vector. These three anchors illustrate how competitive tension now runs between capital-intensive superconducting platforms and emerging permanent-magnet alternatives that bypass helium dependency and traditional department infrastructure.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Hyperfine Inc. |
| Aspect Imaging Ltd |
| Neoscan Solutions GmbH |
| LMT Medical Systems GmbH |
| NORAS MRI Products GmbH |
| Others |
Value Network & Pricing Analysis
FDA 510(k) pediatric clearance tiers gate both supplier qualification and price differentiation simultaneously, separating OEMs with dedicated protocol packages from generalist competitors while compressing margins for independent service providers lacking in-house regulatory affairs capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates superconducting 3.0T installations with bundled multi-year service contracts from unbundled 1.5T configurations and emerging low-field point-of-care alternatives. Price differentiation hinges on helium dependency and after-sales attach rates, with tertiary children's hospitals leveraging captive biomedical engineering to drive service contract disintermediation. Cost compression in the standard tier intensifies because hospital procurement committees unbundle maintenance from capital purchases. Independent imaging centers exhibit highest price sensitivity; academic medical centers with NIH funding streams demonstrate lowest.
Supply Chain Analysis
Magnet component lead times stretching eighteen to twenty-four months force pediatric hospitals to carry safety stock for coil arrays and gradient amplifiers. Superconducting wire production concentrates in Germany, Japan, and the United States, while helium refining rests on Qatar and North American sources. Rare earth permanent magnets for low-field systems draw from Chinese processing facilities. Single-source vulnerability in cryogen supply chains exposes operators to price volatility. Distribution runs through authorized OEM service networks with regional parts depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric MRI hardware margins are flattening while software companion and AI reconstruction licensing layers expand faster than equipment sales, creating a service-attach opportunity that favors vendors with recurring revenue architecture.
For Market Incumbents: Secure multi-year software subscription attach rates at tertiary children's hospitals before third-party reconstruction algorithms gain FDA 510(k) clearance. Defend against Hyperfine Inc.'s point-of-care disruption by accelerating ambient-design system deployment in NICU settings. Prioritize backward integration into cryogen recycling infrastructure to offset helium supply volatility.
For New Entrants and Emerging Players: Differentiate on sedation-free protocol packages targeting ambulatory pediatric settings where anesthesia minimization ranks highest in clinical guidelines. Maharashtra and Tamil Nadu hospital chains represent the most penetrable geography given underpenetrated tertiary infrastructure. Pursue CDSCO fast-track pathways for imported 1.5T systems with pediatric coil configurations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates seeking to divest non-core pediatric coil manufacturing units. Five-to-ten year viability hinges on AI-accelerated scanning convergence displacing conventional high-field installations. Watch FDA 510(k) clearance velocity for low-field bedside systems as the inflection signal indicating point-of-care workflow disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Accelerated Scanning Development | Deep learning reconstruction enables diagnostic-quality imaging without sedation at Cincinnati Children's Hospital. |
| Helium Recycling Infrastructure Investment | Cryogen recovery systems reduce operating cost exposure for Qatar-sourced helium at Texas pediatric centers. |
| Pediatric-Specific FDA 510(k) Pathway | Streamlined clearance accelerates protocol differentiation for tertiary children's hospitals in Boston and Philadelphia. |
| Ambient Design System Deployment | Claustrophobia-reducing installations capture anesthesia-minimization demand across German and Japanese guidelines. |
| Third-Party Service Contract Disintermediation | Independent magnet maintenance sourcing compresses OEM attach rates at academic medical centers with captive engineering. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pediatric neuroradiologists, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers; and secondary validation against FDA 510(k) databases, CMS Medicare reimbursement schedules, hospital procurement records, and IEC 60601-2-33 standards documentation. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning field strength tier, product architecture, end-user facility type, and application indication. CAGRs derived from installed base replacement cycles and point-of-care deployment trajectories. Key inputs included helium supply elasticity coefficients and EU MDR pediatric labeling timeline compression factors.
The analysis sits within stated boundaries; outcomes outside sustained NIH funding levels or helium supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding sedation-free protocol adoption velocity and low-field clinical validation progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Global Pediatric Radiology Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Cerebral Palsy Treatment Market