
 High Frequency Ventilators Market | 2026-2036
High Frequency Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Ventilators Market Outlook
Hospital procurement is bifurcating between centralized health system contracts and point-of-care unit purchases. Medtronic plc leverages its integrated critical care portfolio to anchor multi-year service agreements with IDN networks. Hamilton Medical AG differentiates through open-architecture ventilator platforms that sustain software upgrade revenue streams.
High frequency ventilators deliver respiratory support through oscillatory or jet mechanisms operating at breath rates exceeding 150 cycles per minute, primarily serving patients with compliant lungs or severe gas-exchange impairment. Infant ventilators occupy the highest-margin segment due to precision engineering requirements and limited supplier pools, while high-frequency oscillatory ventilation leads technology adoption in academic pediatric centers. Adult ventilators within the product type dimension face commoditization pressure as volume-controlled and pressure-controlled platforms mature across emergency services and long-term care facilities.
The FDA's 510(k) pathway and ISO 80601-2-80 standards govern electrical safety and alarm performance for critical care ventilators, directly shaping R&D allocation and clinical trial design. The EU MDR's heightened post-market surveillance obligations extend compliance costs for manufacturers serving European hospitals and homecare providers. Stakeholders must monitor evolving CMS reimbursement codes for prolonged mechanical ventilation and align product roadmaps with emerging metrics for ventilator-induced lung injury reduction.
Market Dynamics
Neonatal intensive care units are consolidating purchasing authority through health system procurement offices while simultaneously demanding point-of-care customization, creating dual-channel pressure on ventilator manufacturers.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services has broadened coverage codes for prolonged mechanical ventilation in skilled nursing facilities, pulling adult high-frequency systems into post-acute settings previously served by conventional ventilation.
- Pediatric academic medical centers:Tertiary children's hospitals in the United States are standardizing high-frequency oscillatory ventilation protocols for congenital diaphragmatic hernia and meconium aspiration syndrome, generating protocol-driven replacement cycles.
- ISO 80601-2-80 harmonization:Electrical safety and alarm performance standards are converging across regulatory regimes, reducing engineering overhead for multi-territory product launches and accelerating clearance timelines for oscillatory platforms.
Market Restraints
- Piezoelectric valve supply concentration:Precision flow control components for oscillatory mechanisms source predominantly from Japanese and German specialty manufacturers, exposing assemblers to single-source fragility.
- EU MDR post-market surveillance:Heightened clinical evidence requirements for Class IIb respiratory devices extend recertification costs and compress margin structures for European market participation.
- Conventional ventilator substitution:Volume-controlled and pressure-controlled platforms with advanced lung-protective modes capture price-sensitive adult segments, constraining high-frequency premium positioning.
Strategic Opportunities
- Homecare ventilation transition:The United States is witnessing payer pressure to discharge chronically ventilated pediatric patients to residential settings, opening demand for compact, caregiver-operable high-frequency jet systems.
- India neonatal infrastructure:Central government allocation to district hospital NICU expansion under the National Health Mission creates first-time equipment procurement windows for cost-optimized oscillatory platforms.
- Sensor fusion convergence:Integration of diaphragmatic electrical activity monitoring with oscillatory breath delivery enables closed-loop adaptation, differentiating next-generation platforms from algorithm-limited competitors.
Industry Challenges
- Pediatric perfusionist training scarcity:Specialized clinical expertise for high-frequency oscillatory management concentrates in academic centers, limiting deployment to community hospitals and constraining addressable market expansion.
- FDA 510(k) predicate drift:Evolving substantial equivalence standards for respiratory devices extend premarket notification preparation timelines and demand expanded clinical validation budgets.
- Legacy EMR integration:Proprietary data architectures in incumbent hospital information systems obstruct seamless ventilator-to-record flow, requiring costly interface development for each IDN deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Frequency Ventilators Market |
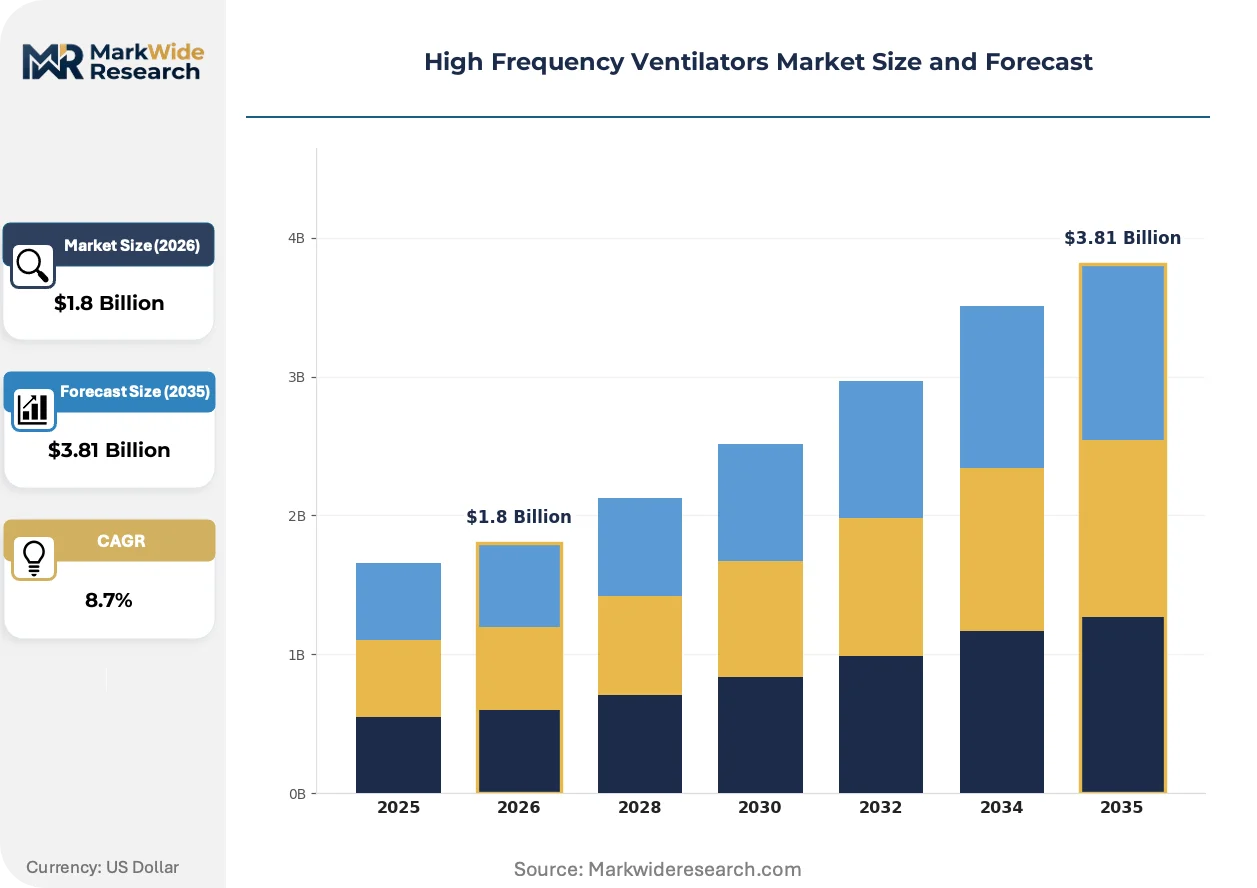
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Ventilators, Adult Ventilators, Transport Ventilators, Homecare Ventilators End User: Hospitals, Long-term Care Facilities, Homecare Providers, Emergency Services Technology: High-Frequency Jet Ventilation, High-Frequency Oscillatory Ventilation, Volume Controlled Ventilation, Pressure Controlled Ventilation Application: Respiratory Distress Syndrome, Acute Respiratory Failure, Bronchopulmonary Dysplasia, Post Operative Care |
| Companies Covered | Medtronic plc, GE HealthCare, Vyaire Medical, Drägerwerk AG & Co. KGaA, Hamilton Medical AG, Getinge AB, Philips Healthcare, Fisher & Paykel Healthcare, Mindray Medical International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Ventilators Market Strategic Shifts
Software-defined ventilation architectures are displacing fixed-function hardware platforms, enabling post-installation capability expansion and recurring revenue capture through firmware subscriptions.
Adaptive lung recruitment algorithms are decomposing the traditional separation between high-frequency oscillatory ventilation and conventional pressure-controlled modes. Academic pediatric centers in the United States are piloting hybrid platforms that switch modalities based on real-time compliance measurements. This capability convergence is compressing the addressable market for standalone oscillatory systems by absorbing their functional differentiation into generalized critical care platforms.
The FDA's evolving 510(k) predicate requirements for respiratory devices are tightening clinical evidence standards for alarm performance validation. Manufacturers must now submit expanded human factors testing for high-frequency mode transitions, extending premarket timelines by six to twelve months. Pediatric-focused product lines face disproportionate impact due to limited predicate availability for neonatal-specific oscillatory indications.
Health system procurement offices are consolidating ventilator purchasing through multi-year managed equipment service agreements. Academic medical centers and integrated delivery networks are unbundling capital acquisition from preventive maintenance and training certification, shifting vendor relationships toward outcome-guaranteed contracts. This restructuring is most visible in the United States, where IDN consolidation has concentrated negotiating leverage among ten to fifteen national systems.
High Frequency Ventilators Market Segmentation
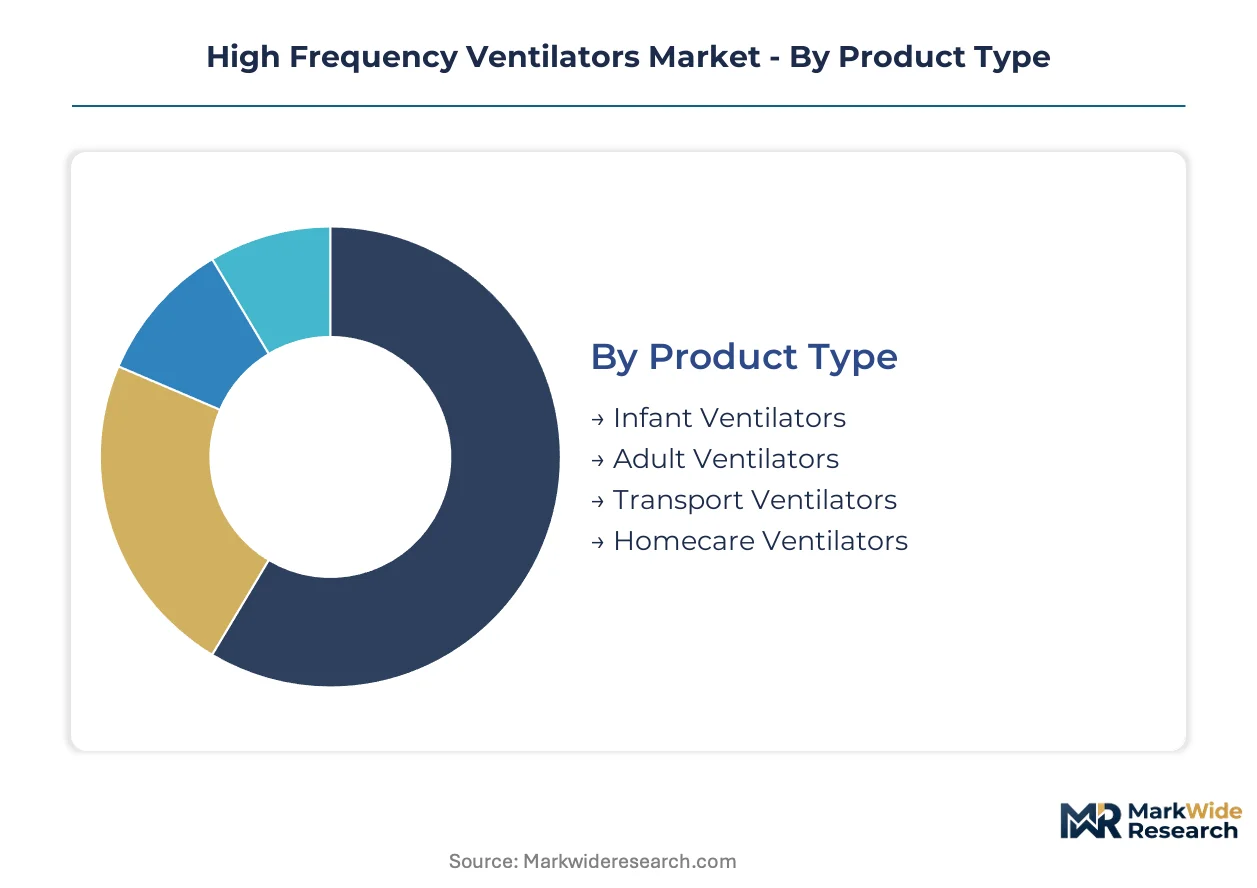
High frequency ventilator purchasing splits sharply across clinical settings, with technology choices and patient acuity driving divergent procurement specifications. Manufacturers must calibrate engineering investments against substitution threats from conventional platforms and channel-specific margin structures.
Product Type:
Adult ventilators face the most acute substitution pressure as volume-controlled and pressure-controlled platforms absorb price-sensitive demand, while infant systems defend premium positioning through precision engineering barriers.
- Infant Ventilators:These systems deliver breath rates exceeding 300 cycles per minute with tidal volumes below 2 milliliters, requiring piezoelectric valve assemblies and specialized flow sensors. Tertiary children's hospitals in the United States concentrate procurement for congenital diaphragmatic hernia protocols, though limited supplier pools constrain price competition.
- Adult Ventilators:Oscillatory mechanisms for acute respiratory distress syndrome operate at 180-300 cycles per minute, but lung-protective conventional modes capture growing share in community hospitals. Academic medical centers remain the primary defenders of high-frequency protocols for salvage therapy in severe gas-exchange impairment.
- Transport Ventilators:Compact oscillatory platforms for inter-facility transfer prioritize battery endurance and vibration resistance over precision tuning.
- Homecare Ventilators:Caregiver-operable jet systems with simplified interfaces address payer pressure for pediatric discharge to residential settings.
Adult ventilators retain volume leadership across installed base; homecare ventilators hold the steepest expansion curve as reimbursement codes shift toward post-acute settings.
End User:
Procurement authority concentrates differently across channels, with health system centralization reshaping vendor access and point-of-care customization demands fragmenting standardization efforts.
- Hospitals:NICU and PICU units in academic centers drive protocol standardization for oscillatory ventilation, with integrated delivery networks consolidating multi-year service agreements. The FDA's 510(k) requirements for Class II respiratory devices extend evaluation timelines for new platform adoption.
- Long-term Care Facilities:CMS reimbursement expansion for prolonged mechanical ventilation pulls adult high-frequency systems into skilled nursing settings previously served by conventional ventilation, though clinical expertise scarcity limits penetration.
- Homecare Providers:Pediatric discharge programs create demand for compact jet systems with remote monitoring capabilities.
- Emergency Services:Pre-hospital applications favor rapid-deployment conventional platforms over oscillatory complexity.
Hospitals command the largest capital allocation; homecare providers are expanding most quickly as payer incentives restructure care delivery.
Technology:
Capability convergence between high-frequency and conventional modes is compressing the addressable market for standalone oscillatory systems as hybrid platforms absorb functional differentiation.
- High-Frequency Jet Ventilation:Pulsed gas delivery at 150-600 cycles per minute through specialized injector cannulas serves bronchopleural fistula and airway disruption cases. Pediatric academic centers in the United States standardize protocols for meconium aspiration syndrome, generating replacement cycles tied to equipment amortization schedules.
- High-Frequency Oscillatory Ventilation:Active exhalation mechanisms operating at 3-15 Hertz maintain lung recruitment through constant mean airway pressure. Tertiary children's hospitals anchor demand for congenital diaphragmatic hernia management, with ISO 80601-2-80 electrical safety standards governing alarm performance validation.
- Volume Controlled Ventilation:Fixed tidal volume delivery with high-frequency adaptation captures price-sensitive adult segments through algorithmic lung-protective modes.
- Pressure Controlled Ventilation:Decelerating flow patterns with oscillatory adjuncts serve intermediate acuity levels in community hospital settings.
High-frequency oscillatory ventilation maintains installed base dominance; high-frequency jet ventilation is gaining share fastest in transport and homecare niches.
Application:
Clinical indication severity determines reimbursement coding and equipment specification intensity, with neonatal conditions defending premium pricing against adult commoditization.
- Respiratory Distress Syndrome:Surfactant-deficient neonatal lungs require precise mean airway pressure maintenance through oscillatory platforms with active exhalation valves. Academic NICUs in the United States concentrate protocol development, with training certification programs limiting deployment to qualified centers.
- Acute Respiratory Failure:Salvage therapy for refractory hypoxemia in adult populations faces substitution from prone positioning and ECMO, constraining high-frequency premium capture in price-sensitive settings.
- Bronchopulmonary Dysplasia:Chronic lung disease in premature infants sustains prolonged ventilation episodes with oscillatory weaning protocols.
- Post Operative Care:Cardiac surgery recovery units employ short-duration high-frequency support for atelectasis prevention.
Respiratory distress syndrome anchors revenue concentration; acute respiratory failure shows the steepest adoption compression from alternative modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision piezoelectric valve assemblies to ventilator manufacturers across the United States and Japan, anchoring the critical component trade corridor for oscillatory platforms. This supply dependency shapes procurement timelines for health systems in destination markets.
United States
Academic medical centers in Boston and Philadelphia drive protocol standardization for high-frequency oscillatory ventilation in congenital diaphragmatic hernia cases. The FDA's 510(k) premarket notification requirements for Class II respiratory devices extend product clearance timelines. Tertiary children's hospitals in California concentrate training certification programs that limit deployment to qualified NICU centers.
Germany
Specialty manufacturers in Baden-Württemberg supply precision flow control components for oscillatory mechanisms to global ventilator assemblers. The EU MDR's post-market surveillance obligations for Class IIb respiratory devices extend recertification costs for manufacturers serving European hospitals. Industrial clusters around Stuttgart anchor precision engineering capabilities for neonatal ventilator subsystems.
Japan
Domestic demand concentrates in Tokyo and Osaka metropolitan medical centers for transport ventilator applications. METI standards for electrical safety in medical devices align with ISO 80601-2-80 harmonization efforts. Component suppliers in Nagoya prefecture face capacity constraints as ventilator manufacturers diversify sourcing away from single-source dependencies.
India
Central government allocation under the National Health Mission funds district hospital NICU expansion in Maharashtra and Karnataka. The CDSCO regulates Class C and D medical devices with escalating clinical evidence requirements for imported respiratory equipment. Manufacturing clusters in Gujarat assemble cost-optimized oscillatory platforms for domestic public procurement.
United Kingdom
Pediatric academic centers in London and Manchester standardize high-frequency jet ventilation protocols for meconium aspiration syndrome. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific device registrations. NHS procurement consolidation through regional commissioning groups centralizes ventilator purchasing authority.
High Frequency Ventilators Market Competitive Environment
Player mix skews toward diversified critical care conglomerates with integrated respiratory portfolios. Market structure concentrates around three to five vertically integrated manufacturers controlling precision valve supply chains and multi-year service agreements. Strategic archetypes include critical care portfolio anchors, open-architecture platform specialists, and regional cost-optimized assemblers. Dominant competitive moves encompass backward integration into sensor manufacturing and geographic expansion through distributor partnerships in emerging NICU markets.
Among diversified critical care conglomerates, Medtronic plc and GE HealthCare exemplify portfolio-anchored positioning through multi-year managed equipment service agreements with integrated delivery networks. Hamilton Medical AG represents the open-architecture specialist archetype, sustaining software upgrade revenue streams through modular ventilator platforms. Drägerwerk AG & Co. KGaA occupies a precision engineering position within the German industrial base, while Vyaire Medical anchors respiratory-focused specialization. Getinge AB, Philips Healthcare, and Fisher & Paykel Healthcare sit within the tier of diversified medtech players with critical care divisions, with Mindray Medical International Ltd. exemplifying cost-optimized platform assembly for price-sensitive procurement channels.
| Leading Market Players |
|---|
| Medtronic plc |
| GE HealthCare |
| Vyaire Medical |
| Drägerwerk AG & Co. KGaA |
| Hamilton Medical AG |
| Getinge AB |
| Philips Healthcare |
| Fisher & Paykel Healthcare |
| Mindray Medical International Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Baden-Württemberg precision engineering clusters shapes both supply concentration and price floors for oscillatory ventilator platforms. Scale economies in piezoelectric valve manufacturing concentrate component sourcing among German and Japanese specialty suppliers, creating asymmetric pricing power that propagates through finished-device cost structures.
Pricing Analysis
Next-generation oscillatory platforms with adaptive lung recruitment algorithms command substantial premiums over volume-controlled conventional systems, while prior-generation fixed-function hardware faces accelerating price erosion. Three-tier pricing structure across premium oscillatory, standard hybrid, and economy conventional levels stratifies by ISO 80601-2-80 certification tier and after-sales service bundling. Cost compression in adult ventilator segments is intensifying because lung-protective conventional modes absorb price-sensitive demand. Long-term care facilities exhibit highest price sensitivity due to CMS reimbursement constraints; academic medical centers defend premium positioning through protocol-driven procurement.
Supply Chain Analysis
Germany and Japan anchor precision flow control component manufacturing for oscillatory mechanisms, with Stuttgart-area industrial clusters producing piezoelectric valve assemblies and Nagoya prefecture suppliers contributing specialized sensors. Finished ventilator assembly draws from Taiwanese electronics for control systems and Chinese battery modules for transport platforms. Single-source vulnerability concentrates in Japanese piezoelectric ceramics, exposing assemblers to capacity constraints and geopolitical disruption. Distribution runs through integrated delivery network procurement offices in the United States and regional commissioning groups in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
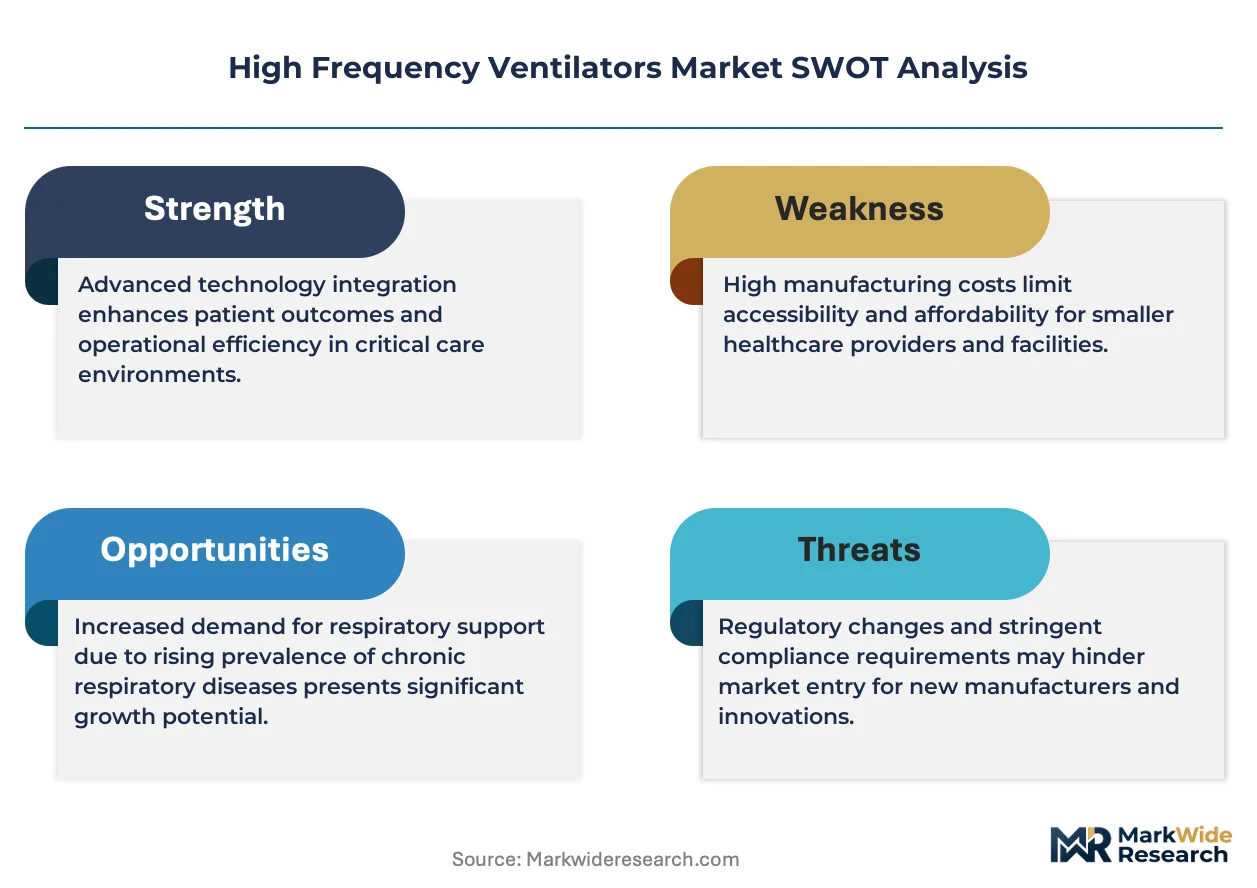
The high frequency ventilators market represents early-cycle expansion as CMS reimbursement codes broaden coverage for prolonged mechanical ventilation in post-acute settings, pulling oscillatory platforms into skilled nursing facilities and homecare environments previously served by conventional ventilation.
For Market Incumbents: Shield neonatal installed base dominance through backward integration into sensor manufacturing and exclusive multi-year service agreements with academic medical center networks. The threat of hybrid conventional-oscillatory platforms absorbing functional differentiation demands accelerated R&D investment in closed-loop diaphragmatic monitoring. Certification investment in FDA 510(k) predicate expansion for pediatric-specific indications remains the critical defensive lever. For New Entrants and Emerging Players: Anchor in India's district hospital NICU expansion under the National Health Mission, where central government procurement creates first-time equipment windows for cost-optimized oscillatory platforms. The most penetrable segment lies in transport ventilators for inter-facility pediatric transfer, underserved by incumbent precision-engineering focus. A go-to-market angle through distributor partnerships with regional medical device assemblers in Gujarat bypasses direct competition with vertically integrated global manufacturers. For Investors and Strategic Acquirers: Respiratory-focused specialists with proprietary valve engineering capabilities and established training certification programs represent the highest-conviction acquisition archetype. Long-term viability across the five-to-ten year window hinges on software-defined architectures enabling recurring firmware revenue. The signal to watch is FDA substantial equivalence standard tightening for pediatric oscillatory predicates, which would accelerate consolidation toward clinical evidence-rich incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Premarket notification preparation for pediatric oscillatory indications extends clearance timelines and demands expanded human factors testing budgets. |
| Hospital System Partnership | Multi-year managed equipment service agreements with integrated delivery networks unbundle capital acquisition from preventive maintenance revenue streams. |
| Software Companion Development | Adaptive lung recruitment algorithms enable post-installation capability expansion through firmware subscriptions, displacing fixed-function hardware platforms. |
| CE Marking Pathway | EU MDR post-market surveillance obligations for Class IIb respiratory devices extend recertification costs and compress margin structures. |
| Reimbursement Strategy | Alignment with emerging CMS codes for prolonged mechanical ventilation and ventilator-induced lung injury metrics shapes product roadmap prioritization. |
Study Parameters
Initial hypotheses were tested against primary input from NICU clinical directors, biomedical engineering managers, hospital procurement committee members, and GPO contracts specialists, and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO standards documentation. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated to reconcile volume and value estimates.
Variance decomposition across the projection horizon isolates contribution from technology substitution effects, regulatory clearance timeline shifts, and reimbursement code expansion. Segmentation dimensions modeled encompass product type, end-user channel, technology mechanism, and clinical application severity, with regional regulatory clusters capturing FDA, EU MDR, and CDSCO framework differences. CAGRs were derived from logistic diffusion curves fitted to protocol adoption timelines in academic medical centers.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement trajectories and continued ISO 80601-2-80 harmonization; material deviation in pediatric perfusionist training availability or piezoelectric valve supply concentration would warrant model refresh. Recalibration cycles align with material shifts in regulatory predicate standards and health system consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Cardioscope Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Band Ligators Market
Medical Devices
Lactation Massager Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Global Pediatric Medical Devices Market