
 Patient Lifting Equipment Market | 2026-2036
Patient Lifting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Lifting Equipment Market Intelligence
The strategic shift towards home care settings is decoupling the market's growth trajectory from traditional hospital capital expenditure cycles. This trend creates distinct competitive arenas for key participants in the patient mobility space. Arjo leverages its extensive portfolio to sustain a strong position within acute and long-term care facilities. In contrast, Invacare Corporation specializes in products specifically designed for the home care environment, while Stryker Corporation competes with solutions tailored for hospital-based patient handling and transport.
Patient lifting equipment comprises mechanical devices designed to safely transfer individuals with mobility impairments, thereby reducing injury risk for caregivers. These systems are engineered with specific load capacities, often ranging from 300 to over 1000 pounds, and operate via electric, hydraulic, or manual mechanisms. Ceiling lifts represent a high-growth product category, particularly in new constructions of assisted living facilities, due to their space-saving design. Electric technology has become the standard over manual variants, offering superior ergonomics and safety for both the patient and the operator.
Regulatory oversight from bodies like the US FDA, which classifies these as medical devices, and adherence to Europe's Medical Device Regulation (MDR) for CE marking are fundamental market access requirements. Workplace safety standards, enforced by agencies such as OSHA in the United States and its counterparts in Canada and the European Union, directly influence purchasing by mandating safe patient handling programs. Future success will depend on aligning product innovation with the dual demands of patient comfort and caregiver ergonomic safety.
Market Dynamics
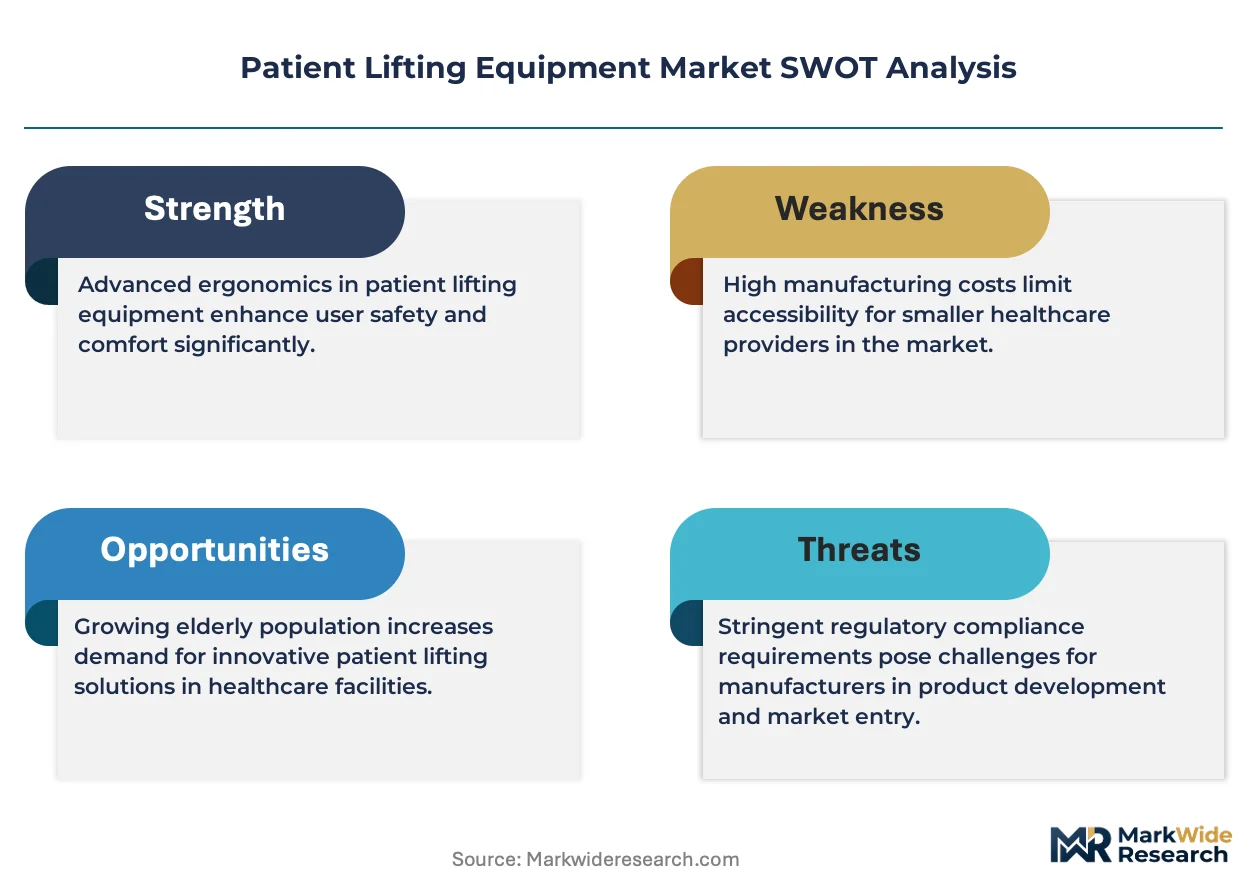
The market's fundamental dynamic is the tension between demographic necessity and fiscal constraint. An aging global population, particularly in Japan and Germany, creates a baseline of non-discretionary demand, while workplace safety mandates from bodies like OSHA compel investment in safe patient handling equipment.
Growth Catalysts
- Safe Patient Handling Mandates:Regulations enforced by agencies like the US Occupational Safety and Health Administration (OSHA) that require healthcare facilities to implement programs to reduce caregiver injuries directly stimulate the procurement of mechanical lifting equipment.
- Aging Demographics:Countries with rapidly aging populations, including Japan and Germany, exhibit sustained demand for mobility support infrastructure in hospitals, long-term care facilities, and private residences to manage age-related mobility impairments.
- Home Care Expansion:The strategic shift of care delivery into home settings is creating a significant growth vector for portable, user-friendly patient lifts that do not require permanent structural installation, catering to both patients and non-professional caregivers.
Market Restraints
- High Capital Costs:The substantial initial investment required for sophisticated equipment, such as facility-wide ceiling lift systems, acts as a significant barrier for smaller healthcare providers, long-term care homes, and individual consumers with limited budgets.
- Infrastructural Limitations:Retrofitting older buildings and private residences with integrated systems like ceiling lifts is often structurally complex and prohibitively expensive, limiting adoption to new constructions or major renovations.
- Regulatory Compliance Burden:The stringent and time-consuming process for obtaining medical device clearance, such as meeting Europe's Medical Device Regulation (MDR) for CE marking, can delay product launches and increase development costs for manufacturers.
Strategic Opportunities
- Smart Technology Integration:Incorporating IoT sensors and connectivity into electric lifts offers opportunities for value-added services, including remote monitoring, predictive maintenance alerts, and usage data analytics for facility managers to optimize asset deployment.
- Bariatric Patient Care:The global increase in obesity rates creates a specific, high-value market for specialized bariatric lifting equipment with load capacities exceeding 1000 pounds, addressing a critical need in hospitals and specialty care centers.
- Emerging Market Penetration:Developing economies with expanding healthcare infrastructure and a growing middle class present untapped opportunities for manufacturers to introduce mid-range, cost-effective patient lifting solutions tailored to local needs.
Industry Challenges
- Caregiver Training and Adherence:Ensuring consistent and correct use of patient lifting equipment requires extensive and ongoing training for healthcare staff, posing a logistical and financial challenge for providers aiming to maximize safety benefits and ROI.
- Lack of Sling Standardization:The absence of universal compatibility standards for slings and lifts among different manufacturers creates interoperability problems, leading to vendor lock-in for healthcare facilities and potential safety risks from mismatched components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Lifting Equipment Market |
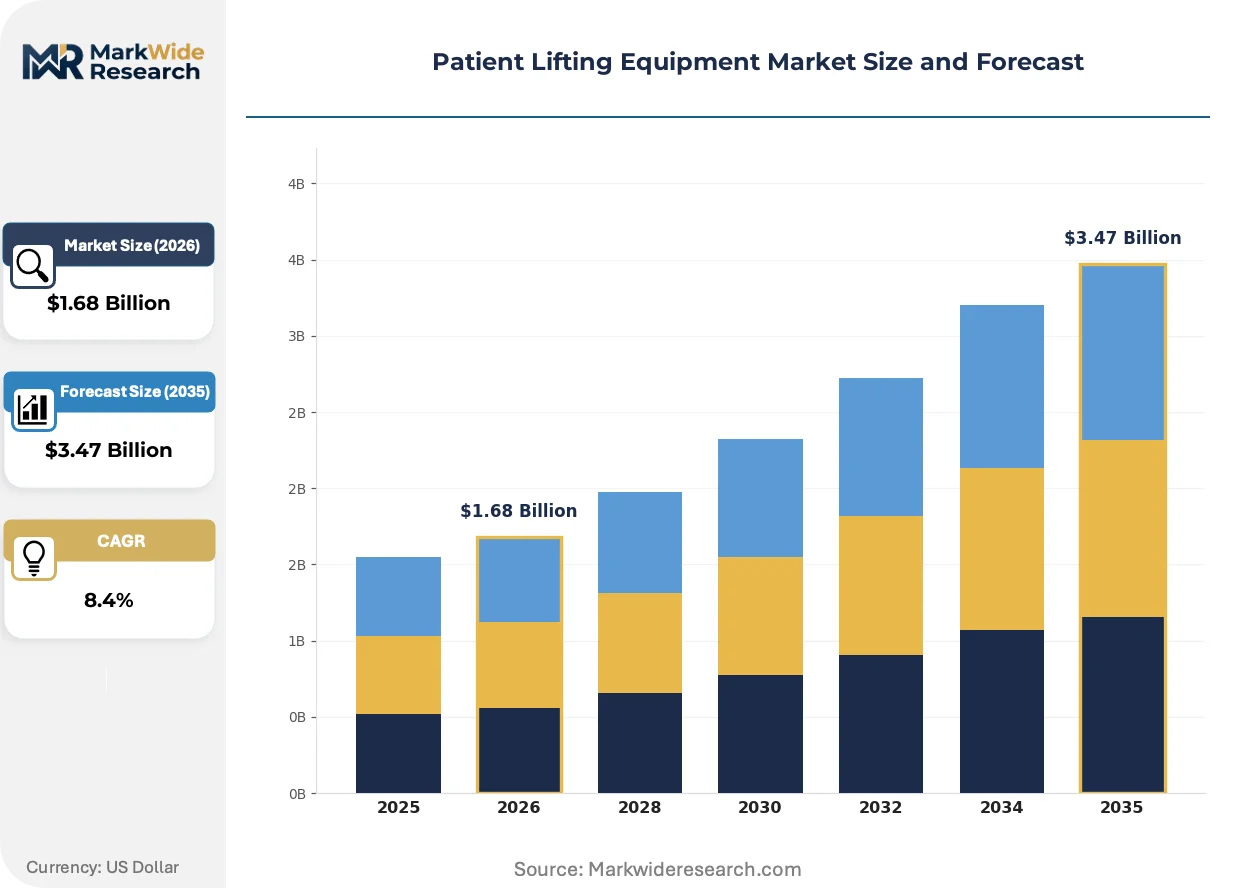
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Lifts, Mobile Lifts, Standing Lifts, Slings, Stair Climber Lifts Application: Assisted Transfer, Bathing & Hygiene, Physical Therapy, Patient Rehabilitation, Mobility Support End User: Nursing Homes, Rehabilitation Centers, Home Care, Assisted Living Facilities, Long-Term Care Facilities Technology: Electric, Hydraulic, Manual, Pneumatic, Mechanical |
| Companies Covered | Arjo, Baxter International, Stryker Corporation, Invacare Corporation, Savaria, GF Health Products, Joerns Healthcare, Guldmann, Etac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Lifting Equipment Market Strategic Shifts & Innovations
Product evolution is moving towards adaptable, user-centric designs that serve patients across the care continuum. This shift prioritizes modularity and connectivity, moving away from single-environment, institution-focused equipment. Technology and evolving service models are reshaping the competitive landscape for patient handling solutions.
Portable and modular lift systems provide flexible patient handling capabilities without requiring permanent structural installations. Home care agencies and assisted living communities are rapidly adopting these devices to support clients with varying mobility needs. This trend is decentralizing patient handling, shifting the capability from fixed, room-specific installations toward more adaptable, person-centered models of care.
Europe's Medical Device Regulation (MDR) is forcing a higher standard of clinical validation and post-market surveillance. This regulation requires manufacturers to provide more extensive technical documentation and evidence of safety and performance. The change most affects producers of Class I medical devices, including many patient lifters, who must now invest more heavily in their quality management systems to maintain CE marking and market access.
A notable behavioral shift among healthcare providers is the growing preference for equipment rental and leasing models over direct capital purchases. This disrupts the traditional sales cycle for durable medical equipment, particularly for managing short-term needs in post-acute care or for facilities seeking to conserve capital. The model is gaining significant traction in the US and UK home care sectors, where financial flexibility is a key operational priority.
Patient Lifting Equipment Market Segmentation
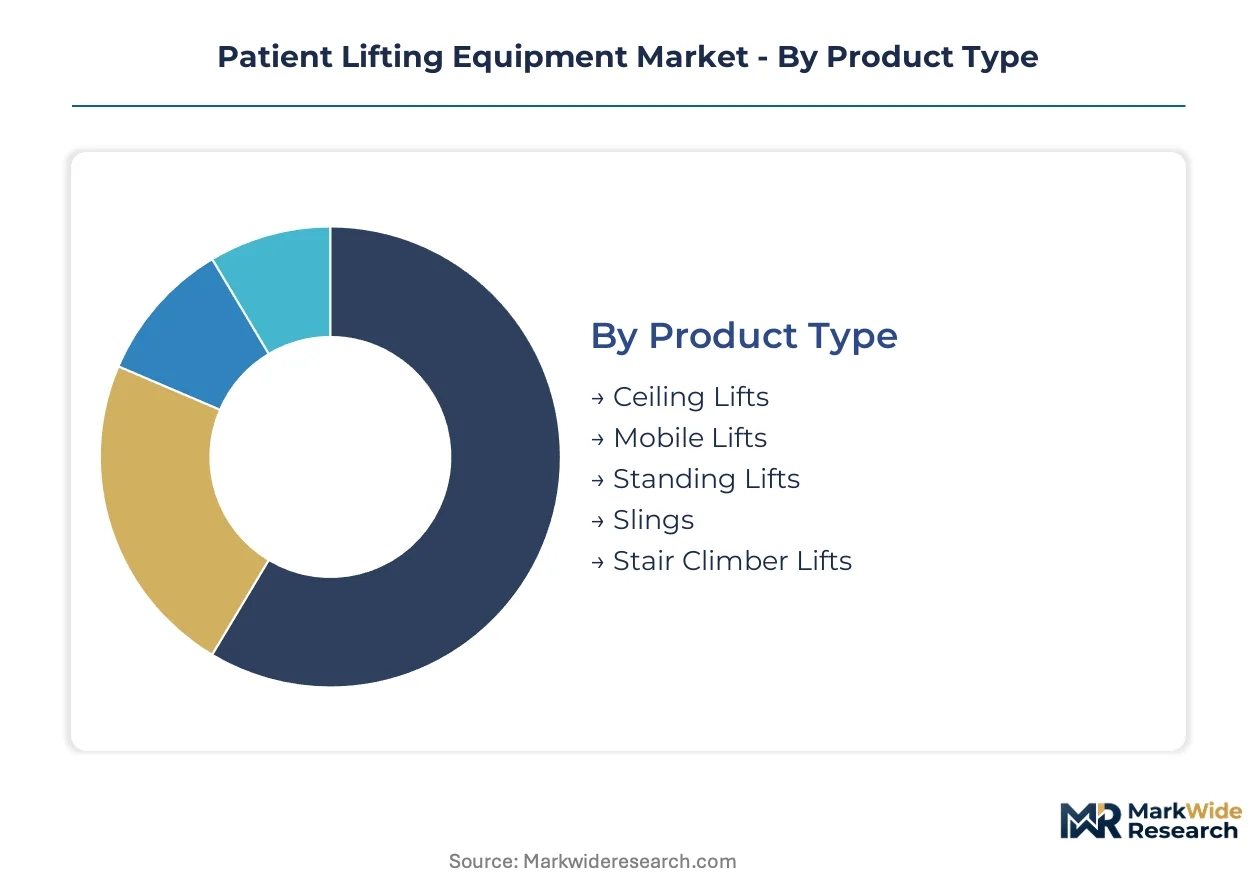
The patient lifting equipment market segments across diverse product types, applications, end-users, and underlying technologies. Each segment reflects distinct operational requirements and patient care needs. Understanding these granular divisions reveals specific demand patterns and strategic growth areas for manufacturers.
Product Type:
Product types differentiate based on their functional complexity and installation requirements, often influencing their price point and market volume.
- Ceiling Lifts:These systems integrate into overhead structures, providing extensive coverage within a room for patient transfers. Demand exists primarily in new assisted living facility constructions due to their space-saving design and enhanced caregiver ergonomics.
- Mobile Lifts:Mobile lifts offer portability and flexibility, allowing for patient transfers across various locations without fixed installation. Their versatility makes them essential for home care settings, supporting non-professional caregivers with diverse mobility challenges.
- Standing Lifts:These devices assist patients with partial weight-bearing capabilities, facilitating rehabilitation and stand-assist transfers.
- Slings:Slings are essential accessories for all lift types, providing secure and comfortable patient support during transfers.
- Stair Climber Lifts:Stair climber lifts enable safe patient transport up and down stairs, addressing accessibility challenges in multi-level residences.
Mature deployment sits with Mobile Lifts, offering broad utility. Newer deployment focuses on Ceiling Lifts, particularly for modern healthcare infrastructure.
Application:
Applications for patient lifting equipment span the entire care continuum, addressing specific patient needs and care protocols.
- Assisted Transfer:This core application focuses on moving patients between beds, wheelchairs, and commodes, minimizing caregiver strain. High volume demand exists across all healthcare settings, driven by universal patient mobility requirements.
- Bathing & Hygiene:Equipment for bathing and hygiene provides safe and dignified patient access to showers and toilets.
- Physical Therapy:Specialized lifts aid in rehabilitation exercises, supporting patients during gait training and mobility restoration.
- Patient Rehabilitation:This application involves using lifts to support therapeutic exercises and regain patient independence. Rehabilitation centers in Germany increasingly integrate these devices for post-operative recovery programs.
- Mobility Support:Lifts provide general mobility assistance, enhancing patient independence and reducing fall risks in daily activities.
Assisted Transfer remains the foundational application, while Patient Rehabilitation applications are expanding most quickly due to an aging population requiring therapeutic interventions.
End User:
End-user segments reflect varying institutional structures and care delivery models, dictating equipment scale and feature requirements.
- Nursing Homes:Nursing homes represent a traditional high-volume end-user segment, requiring robust and durable lifting solutions for long-term resident care. Regulatory mandates from OSHA in the United States directly influence procurement decisions for these facilities.
- Rehabilitation Centers:These specialized facilities use patient lifts for intensive therapy and functional recovery programs.
- Home Care:The home care segment is experiencing significant expansion, favoring portable and user-friendly equipment for non-professional caregivers. This shift decouples growth from traditional hospital capital expenditure cycles.
- Assisted Living Facilities:Assisted living facilities integrate lifts to support residents with varying degrees of mobility needs, promoting independence.
- Long-Term Care Facilities:These facilities require comprehensive lifting solutions for residents with chronic conditions and extensive mobility impairments.
The strategic shift towards home care settings is the primary driver for new equipment procurement, while nursing homes maintain consistent demand for established solutions.
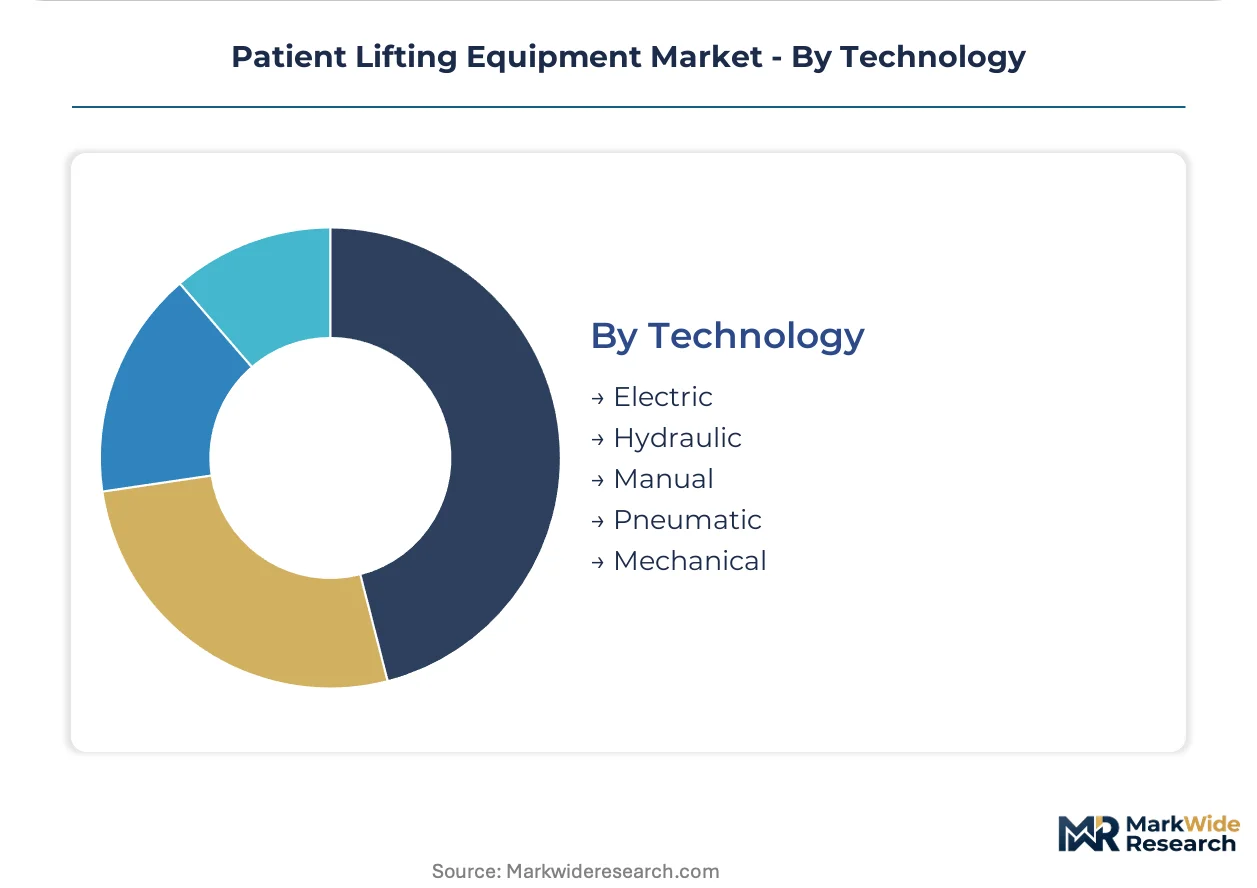
Technology:
Technology choices in patient lifting equipment prioritize operational efficiency, safety, and ease of use for both caregivers and patients.
- Electric:Electric lifts offer superior ergonomics and safety through powered operation, making them the industry standard for modern patient handling. Their adoption is widespread in hospitals in Japan due to stringent safety protocols.
- Hydraulic:Hydraulic systems provide robust lifting power, often found in heavy-duty or bariatric equipment, offering reliability for demanding transfers. These systems are prevalent in long-term care facilities requiring high load capacities.
- Manual:Manual lifts provide basic, cost-effective patient transfer solutions, primarily used in settings with infrequent needs or budget constraints.
- Pneumatic:Pneumatic technology uses compressed air for lifting, offering smooth operation and reduced maintenance requirements in specialized applications.
- Mechanical:Mechanical lifts rely on levers and gears for operation, representing an older technology largely superseded by electric and hydraulic variants.
Innovation is concentrated in electric technologies, enhancing user experience and data integration, while manual and mechanical variants address niche cost-sensitive requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The strategic shift towards home care settings, acting as a distinct growth zone for patient lifting equipment, drives market concentration in specific geographies. These regions prioritize comprehensive elder care infrastructure and medical device innovation, often supported by public health initiatives. Demand is particularly pronounced in countries grappling with significant demographic shifts and robust healthcare regulatory frameworks.
Japan
Japan's rapidly aging population creates a baseline of non-discretionary demand for mobility support infrastructure. Stringent safety protocols, often influenced by the PMDA, drive the adoption of electric patient lifts in hospitals. Tokyo's extensive network of elder care facilities and hospitals actively integrate advanced patient handling systems to manage age-related mobility impairments.
Germany
Germany experiences sustained demand for patient lifting equipment, particularly in rehabilitation centers and long-term care facilities. Adherence to Europe's Medical Device Regulation (MDR) for CE marking ensures high product quality and safety standards. Bavaria, a hub for medical technology manufacturing, sees significant investment in patient rehabilitation devices for post-operative recovery programs.
United States
The United States market responds directly to workplace safety standards, with OSHA mandates compelling investment in safe patient handling equipment. The US FDA classifies patient lifting equipment as medical devices, enforcing rigorous market access requirements. California's healthcare innovation clusters, particularly around Los Angeles and San Francisco, lead in adopting smart technology integration for remote monitoring and predictive maintenance.
United Kingdom
United Kingdom's home care sector is experiencing significant expansion, favoring portable and user-friendly patient lifts. Health and Safety Executive (HSE) guidelines influence procurement decisions in healthcare settings to reduce caregiver injuries. London's burgeoning home care agencies increasingly utilize equipment rental and leasing models to manage short-term needs and conserve capital.
China
China represents a significant emerging market with expanding healthcare infrastructure and a growing middle class. The NMPA regulates medical devices, ensuring product safety and efficacy for domestic use. The Yangtze River Delta region, including cities like Shanghai, is a key area for both medical device production and increasing adoption of patient lifting solutions in hospitals and assisted living facilities.
Patient Lifting Equipment Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized mid-tier players compete in niche applications, creating a tiered market structure. This market features archetypes such as comprehensive solution providers, home care specialists, and hospital-focused equipment manufacturers. Dominant competitive moves include portfolio diversification to cover the entire care continuum and strategic partnerships to expand geographic reach.
Specialists in patient mobility solutions, Arjo and Stryker Corporation, offer extensive portfolios tailored for acute, long-term, and hospital-based care environments. Arjo leverages its broad product range to sustain a strong position within institutional settings. Invacare Corporation, a US-based entity, occupies a distinct position by specializing in products specifically designed for the home care environment, supporting non-professional caregivers with user-friendly equipment.
| Leading Market Players |
|---|
| Arjo |
| Baxter International |
| Stryker Corporation |
| Invacare Corporation |
| Savaria |
| GF Health Products |
| Joerns Healthcare |
| Guldmann |
| Etac |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) for CE marking gates both qualified supply and premium-tier pricing access for patient lifting equipment. This stringent regulatory framework necessitates significant investment in product development and quality management systems, directly influencing market entry and pricing strategies.
Pricing Analysis
Lead-time-driven pricing for specialized patient lifting equipment favors premium rates for rapid deployment, while bulk orders or standard configurations may receive volume discounts. The dominant pricing model is contract-based long-term off-take for institutional buyers, often bundled with maintenance and training services. Price differentiation drivers include adherence to regulatory certifications like FDA clearance and CE marking, alongside bariatric load capacities. Pricing pressure stems from budget constraints within the home care segment, where cost-effective solutions are paramount. Home care entities exhibit the highest price sensitivity, whereas large hospital networks prioritize advanced features and comprehensive service bundles.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China and Germany significantly influences the patient lifting equipment supply chain. Supply concentration for advanced components such as electric motors and IoT sensors is observed in East Asia, particularly China. Raw material dependencies include specialized steel alloys for structural integrity and medical-grade plastics for patient contact surfaces. A structural risk involves potential logistics chokepoints, particularly for large-volume equipment, impacting delivery timelines. Distribution runs primarily through direct sales channels to large hospitals and rehabilitation centers, complemented by a network of specialized medical equipment distributors for the home care sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient lifting equipment market is in a technology-transition phase, with smart technology integration replacing legacy manual and basic electric systems. This shift enhances operational efficiency and patient safety across care settings.
For Market Incumbents: Extend product portfolios to encompass the entire care continuum, from acute hospital settings to home care environments. Focus on R&D in smart technology integration, incorporating IoT sensors and predictive maintenance features to enhance value propositions. This strategy helps mitigate the threat of specialized new entrants focusing solely on the high-growth home care segment. Deepen channel control within long-term care facilities through comprehensive service contracts.
For New Entrants and Emerging Players: A price-point gap exists between premium, feature-rich institutional equipment and basic, cost-effective home care solutions. Target the home care segment with portable, user-friendly equipment that does not require permanent installation. Emphasize rental and leasing models as a go-to-market angle, addressing the financial flexibility needs of individual consumers and smaller home care agencies. Focus on specific applications like bathing and hygiene support, which have consistent demand.
For Investors and Strategic Acquirers: Increased enforcement of safe patient handling mandates by agencies like OSHA is the leading indicator that market demand will continue to strengthen. Look for acquisition targets specializing in bariatric patient care solutions or those with robust smart technology platforms. Long-term viability over a 5-10 year window remains strong due to aging demographics and expanding home care. Monitor home care penetration rates as a key inflection signal for market expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach across acute, long-term, and home care settings, reducing reliance on single segments. |
| Smart Technology Integration | Enhances product functionality with IoT capabilities, offering value-added services like remote monitoring. |
| Rental and Leasing Models | Addresses capital expenditure constraints for smaller facilities and individual users, expanding market access. |
| Bariatric Equipment Development | Captures a specific, high-value market segment driven by increasing obesity rates and specialized patient needs. |
| Regulatory Compliance Investment | Ensures market access and strengthens competitive advantage by adhering to stringent medical device regulations. |
Research Approach
Industry association publications, government healthcare expenditure reports, and medical device regulatory filings formed the secondary backbone of this analysis. This was combined with primary interviews conducted with hospital procurement managers, home care agency directors, medical device engineers, and regulatory compliance officers. Bottom-up and top-down triangulation ensured data consistency and validated market sizing estimates.
Historical trendline analysis across the analysis window informed the projection framework for the patient lifting equipment market. The quantitative model segmented the market by product type, application, end-user, technology, and regional adoption patterns. Compound annual growth rates were derived through a regression analysis of historical data and forward-looking market drivers. Key forecast inputs included aging population growth rates and healthcare infrastructure development trends.
Inputs from published regulatory guidelines and industry reports were available through the study window; gaps in emerging market healthcare expenditure data introduce uncertainty bands into regional forecasts. Forecasts reflect assumptions regarding continued regulatory enforcement and technological advancements. Material deviation in global demographic shifts or healthcare policy changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Electric Bed Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Operating Table Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market