
 Pet Mobility Aids Market | 2026-2036
Pet Mobility Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Mobility Aids Market Analytics
Premium-grade veterinary certification is bifurcating the competitive landscape between clinical suppliers and mass-market retailers. Walkin' Pets leverages its direct-to-consumer platform to sustain brand loyalty among owners of large-breed dogs requiring custom-fitted wheelchairs. Bionic Pets specializes in 3D-printed prosthetic limbs, competing on precision-fit technology that anchors its position in specialty veterinary referrals. PetSafe controls mass-market distribution through big-box retail partnerships, extending its reach into entry-level harness and ramp categories.
Pet mobility aids encompass orthotic devices, supportive harnesses, wheeled carts, and access ramps engineered from aluminum tubing, high-density nylon webbing, closed-cell foam padding, and injection-molded plastics to restore or augment ambulatory function in animals with musculoskeletal impairment, neurological deficit, or post-operative recovery needs. Wheelchairs and harnesses command the largest installed base among product types, though rehabilitation-focused slings are gaining traction in clinical settings where veterinary staff require adjustable lift support for intraoperative and postoperative patient handling. Aluminum-framed devices dominate material selection for outdoor and daily mobility usage types due to strength-to-weight ratio and corrosion resistance, while nylon and foam configurations concentrate in indoor applications where comfort and surface protection take priority.
FDA Center for Veterinary Medicine regulates therapeutic claims on orthopedic devices sold into the United States, pushing manufacturers toward clinical validation or restricted marketing language. The EU Veterinary Medicines Regulation and REACH chemical compliance frameworks govern product safety and biocompatibility testing for devices distributed across European member states. ISO 10993 biocompatibility standards provide a harmonized reference for material safety assessments that facilitate cross-border market access. Stakeholders must monitor evolving veterinary reimbursement policies and specialty clinic accreditation requirements that will determine channel prioritization and product development roadmaps.
Market Dynamics
Veterinary rehabilitation service expansion is compressing the traditional retail channel for pet mobility devices, as specialty clinics in the United States, Germany, and Japan now capture a growing share of high-acuity cases requiring custom-fitted orthotics and prosthetics.
Growth Catalysts
- ISO 10993 biocompatibility harmonization:Cross-border material safety standards reduce redundant testing burdens for manufacturers distributing aluminum-framed wheelchairs and nylon harness configurations across multiple jurisdictions.
- Geriatric companion animal populations:Aging large-breed dogs in suburban North America generate sustained demand for wheeled carts and supportive slings addressing degenerative joint disease and post-surgical recovery.
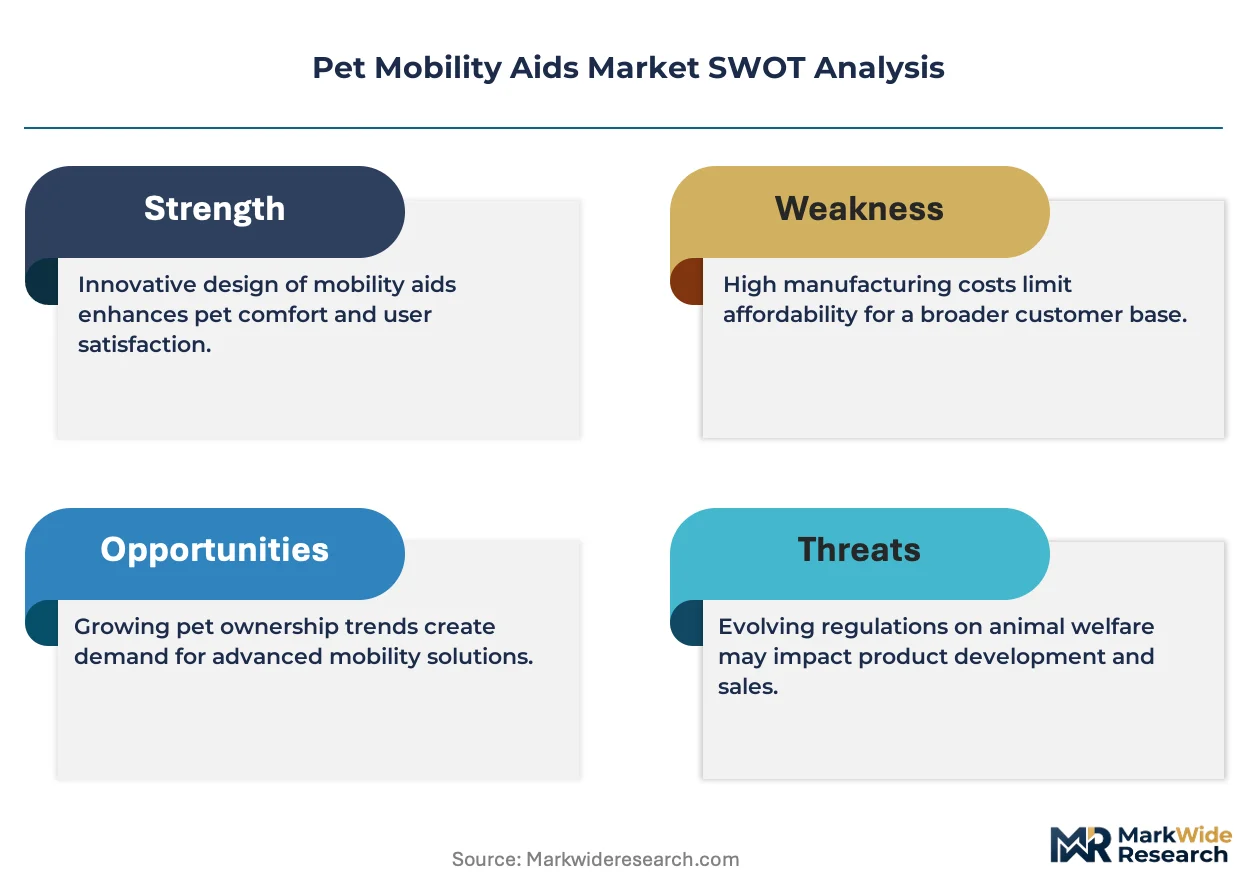
- EU Veterinary Medicines Regulation substantiation requirements:Tightened product claims documentation elevates clinical-grade suppliers over mass-market competitors, creating channel differentiation for veterinary-certified devices.
Market Restraints
- Aluminum price volatility:Raw material cost swings for corrosion-resistant tubing compress margins on outdoor-rated mobility carts, forcing manufacturers toward fixed-price supplier contracts or alternative alloy specifications.
- FDA Center for Veterinary Medicine therapeutic claim restrictions:Orthopedic device marketing language constraints limit direct-to-consumer messaging, pushing promotional spend toward veterinary professional education and clinic detailing.
- Closed-cell foam padding supply concentration:Domestic specialty chemical producers in select Asian manufacturing clusters control high-density comfort material output, creating geographic dependency for indoor-application harness lines.
Strategic Opportunities
- 3D-printed prosthetic precision convergence:Additive manufacturing and veterinary digital imaging integration enable patient-specific limb replacement geometries previously unavailable through conventional casting methods.
- Specialty e-commerce platform penetration:Direct-to-consumer channels bypass big-box retail markups for custom-fitted large-breed wheelchairs, capturing owner willingness to pay premium prices for personalized measurement support.
- Japan METI aging society initiative alignment:National pet longevity programs subsidize rehabilitative care access, opening reimbursement pathways for certified mobility aid procurement through veterinary specialty networks.
Industry Challenges
- Veterinary orthopedic technician certification scarcity:Qualified professionals capable of custom device fitting and gait analysis remain concentrated in major metropolitan clinic clusters, limiting service scalability.
- Biocompatibility testing timeline compression:ISO 10993 material safety validation protocols extend product development cycles, delaying market entry for novel foam padding formulations and injection-molded plastic geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Mobility Aids Market |
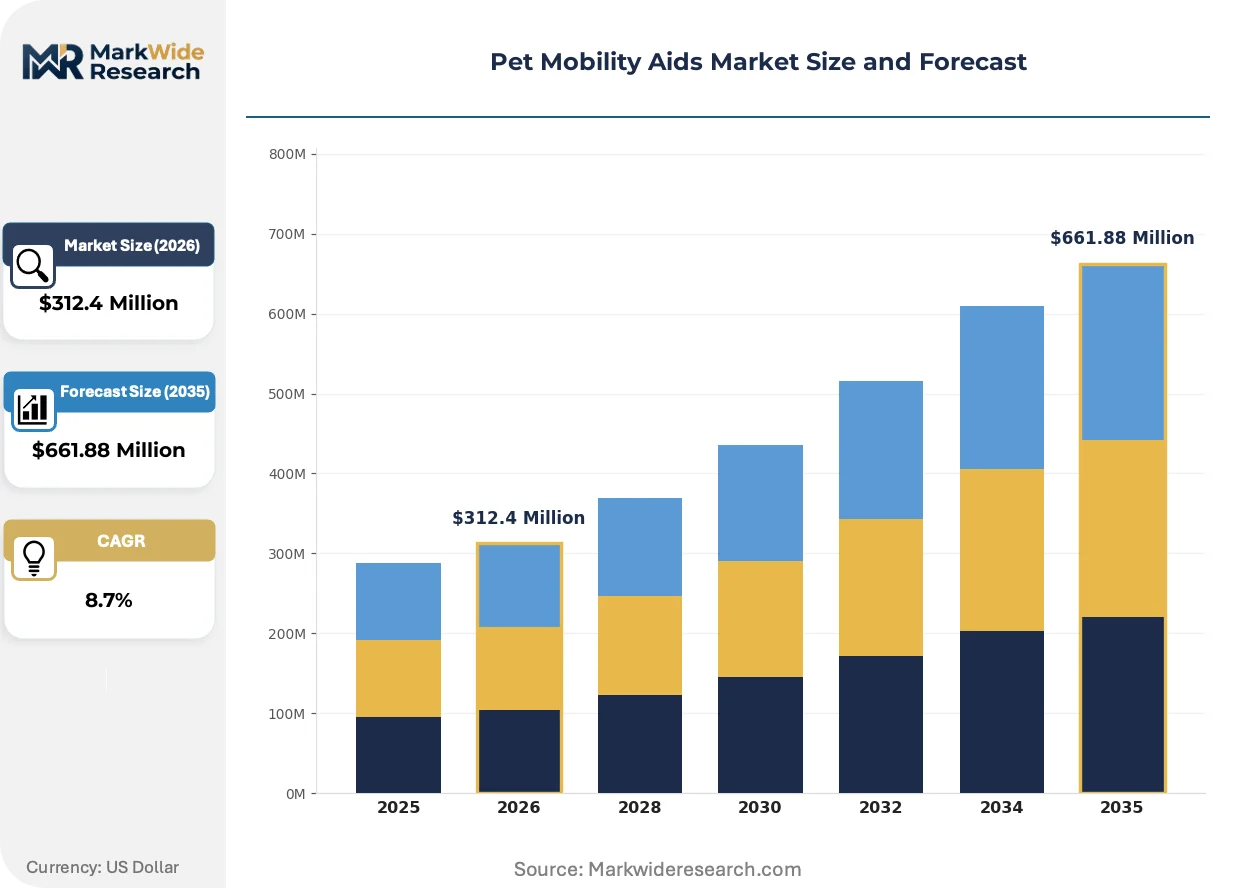
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Slings, Harnesses, Ramps End User: Pet Owners, Veterinary Clinics, Shelters, Trainers Material: Aluminum, Nylon, Foam, Plastic Usage Type: Indoor, Outdoor, Rehabilitation, Daily Mobility |
| Companies Covered | K-9 Orthotics & Prosthetics Inc., PetSafe, Walkin' Pets, WIMBA, Petmate, Bionic Pets, Paw Prosper, OrthoVet LLC, Animal Ortho Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Mobility Aids Market Evolving Landscape
Digital manufacturing workflows and regulatory documentation automation are restructuring how mobility aid suppliers engage veterinary channels, compressing the gap between clinical measurement and device delivery while elevating compliance investment thresholds.
3D-printed titanium and carbon fiber composite prosthetics are bifurcating the limb replacement segment. Specialty veterinary referral centers in Germany and Japan now specify additive-manufactured sockets for trauma and congenital defect cases. Precision-fit technology is compressing demand for standardized pre-sized prosthetic catalog offerings, forcing traditional suppliers toward clinical partnership models or exit from high-acuity segments.
REACH chemical compliance frameworks and EU MDR veterinary device alignment are tightening biocompatibility documentation requirements for European distribution. Manufacturers must now submit comprehensive material safety data for nylon webbing and foam padding components previously exempt from human-medical scrutiny. German and French veterinary distributors are consolidating supplier bases toward pre-certified clinical-grade portfolios, excluding mass-market catalog entrants lacking dedicated regulatory affairs capacity.
Subscription-based rehabilitation equipment access is displacing outright purchase for multi-stage recovery protocols. Veterinary clinics in the United States now lease adjustable slings and harness systems for defined post-operative periods, transferring capital burden to suppliers while capturing recurring revenue streams. This model concentrates in orthopedic specialty practices serving sporting and working dog populations where injury recurrence rates justify ongoing equipment rotation.
Pet Mobility Aids Market Segmentation
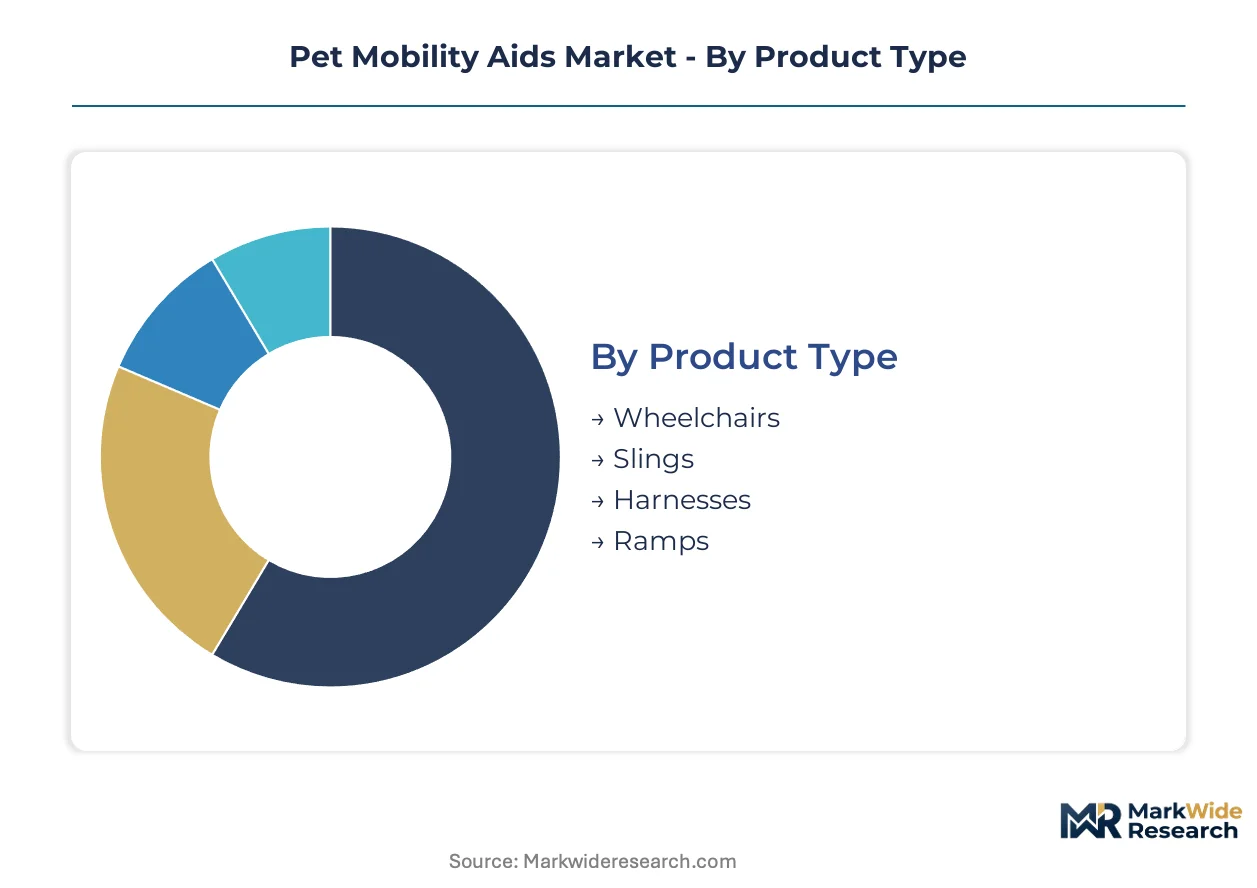
Channel differentiation in pet mobility aids hinges on whether devices require professional fitting or suit direct-to-consumer purchase. Veterinary clinics now control high-acuity segments demanding custom measurement, while mass retail and specialty e-commerce capture standardized configurations.
Product Type:
Veterinary clinics and specialty e-commerce platforms split demand based on fitting complexity and acuity level.
- Wheelchairs:Aluminum-framed wheeled carts with adjustable harness systems restore ambulatory function for large-breed dogs with degenerative joint disease or spinal injury. Demand concentrates in suburban United States and Germany through veterinary rehabilitation centers requiring gait analysis and custom fitting.
- Harnesses:Supportive lift configurations constructed from high-density nylon webbing with closed-cell foam padding distribute weight across the torso for assisted standing and controlled movement. PetSafe and mass-market retailers dominate distribution for standardized sizing, though specialty e-commerce captures premium custom-fit demand for non-standard body types.
- Slings:Adjustable fabric supports enable veterinary staff to maneuver patients during intraoperative and postoperative handling.
- Ramps:Portable access solutions bridge elevation changes for vehicles and furniture in home environments.
Wheelchairs dominate installed base. Slings represent the fastest-growing trajectory as veterinary rehabilitation service lines expand.
End User:
Customer type determines price tolerance, service expectations, and regulatory compliance exposure for suppliers.
- Veterinary Clinics:Accredited rehabilitation facilities in the United States, Germany, and Japan procure FDA Center for Veterinary Medicine-compliant devices with biocompatibility documentation. These customers demand ISO 10993-certified materials, professional training support, and warranty structures aligned with clinical utilization rates.
- Pet Owners:Individual purchasers of companion animals drive volume in standardized harness and ramp categories through big-box retail and direct-to-consumer platforms. This segment exhibits sharp price sensitivity for entry-level products but pays premium prices for custom-fitted wheelchairs when large-breed mobility failure occurs.
- Shelters:Non-profit and municipal animal control facilities source durable, sanitizable equipment for temporary housing of injured or geriatric animals.
- Trainers:Sporting and working dog professionals acquire specialized supportive gear for conditioning and injury prevention protocols.
Veterinary clinics capture margin concentration. Pet owners represent volume scale.
Material:
Raw material selection maps directly to performance requirements across indoor comfort and outdoor durability applications.
- Aluminum:Corrosion-resistant tubing with anodized finishes delivers strength-to-weight ratios essential for outdoor-rated wheelchairs and ramps subjected to weather exposure and daily transport. Price volatility in primary metal markets compresses margins, forcing manufacturers toward fixed-price supplier contracts or alternative alloy specifications.
- Foam:Closed-cell padding formulations provide pressure distribution and skin protection for indoor harness and sling applications where animal comfort takes priority. Supply concentration among Asian specialty chemical producers creates geographic dependency for comfort-material sourcing.
- Nylon:High-tenacity webbing with breaking strength ratings supports load-bearing harness configurations.
- Plastic:Injection-molded components enable cost-efficient production of adjustment hardware and protective housings.
Aluminum commands outdoor application share. Foam is climbing the fastest as indoor rehabilitation protocols expand.
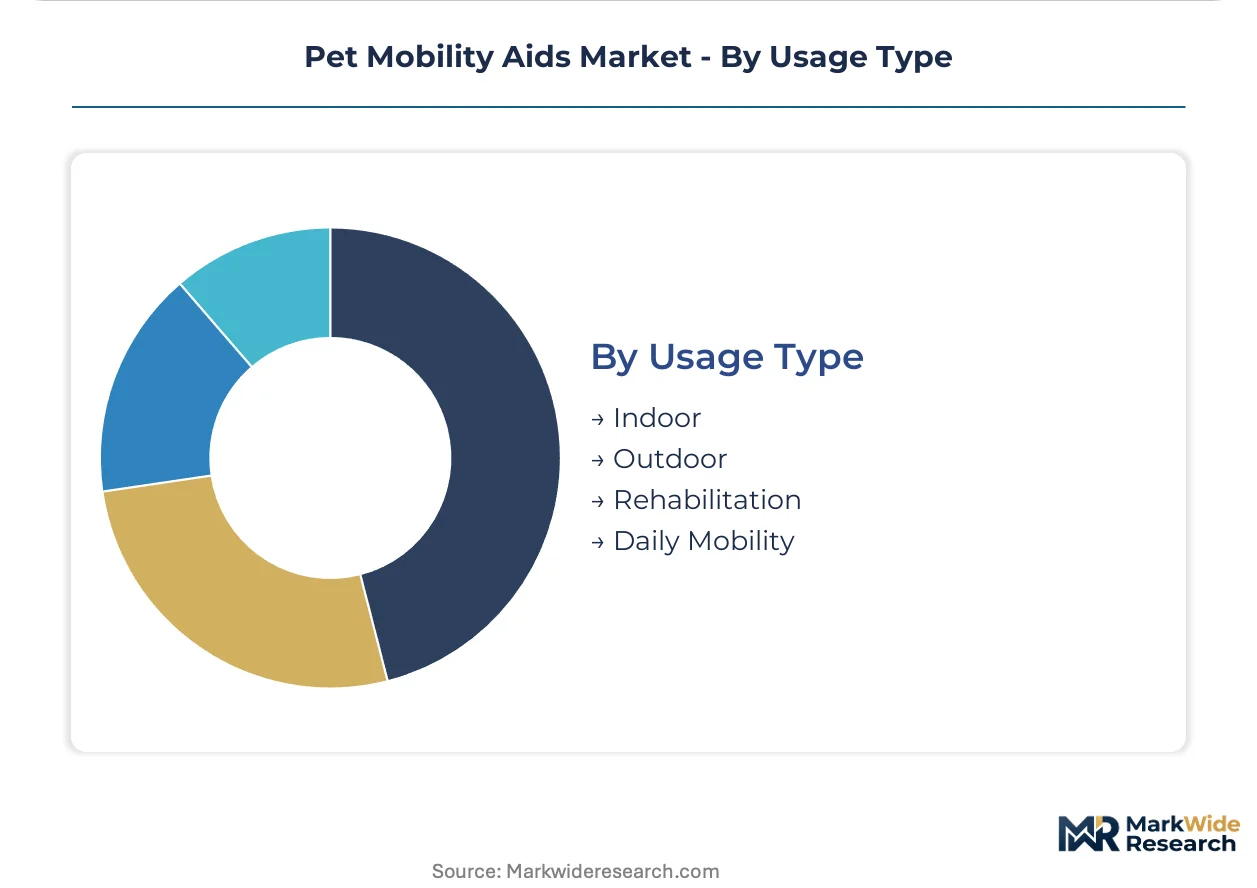
Usage Type:
Application context dictates material specifications, cleaning protocols, and replacement cycles for device portfolios.
- Daily Mobility:Permanent-use wheelchairs and harnesses engineered for continuous wear require veterinary-grade durability certifications and adjustable growth accommodation for young animals with congenital conditions. German and Japanese specialty clinics specify these configurations for long-term patient management.
- Rehabilitation:Temporary-support slings and adjustable harness systems facilitate controlled exercise progression during post-surgical recovery periods. United States orthopedic specialty practices increasingly lease rather than purchase this equipment, transferring capital burden to suppliers while capturing recurring revenue.
- Indoor:Surface-protection-focused configurations prioritize floor compatibility and furniture clearance.
- Outdoor:Weather-resistant specifications emphasize corrosion protection and terrain adaptability.
Daily mobility anchors revenue stability. Rehabilitation is gaining share fastest through subscription-based access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net exporters of precision-manufactured aluminum components and injection-molded plastics supply veterinary device fabricators across import-dependent markets. Trade flows concentrate among economies with established pet care infrastructure and regulatory harmonization.
United States
Suburban large-breed dog ownership and veterinary rehabilitation service expansion drive wheelchair and harness procurement. FDA Center for Veterinary Medicine oversight of therapeutic claims shapes product substantiation requirements. Greater Boston and Pacific Northwest metro areas host specialty veterinary referral centers specifying custom-fitted orthotics.
Germany
Geriatric companion animal populations and working dog rehabilitation protocols sustain demand for precision prosthetics. EU Veterinary Medicines Regulation and REACH chemical compliance frameworks govern biocompatibility documentation. Bavaria and North Rhine-Westphalia concentrate veterinary orthopedic technician certification programs and device distribution networks.
Japan
METI aging society initiatives subsidize rehabilitative care access for companion animals. National pet longevity programs open reimbursement pathways for certified mobility aids through veterinary specialty networks. Kanto and Kansai regions anchor specialty clinic clusters serving metropolitan pet-owning households.
United Kingdom
Specialty e-commerce platform penetration and direct-to-consumer custom fitting services capture premium wheelchair demand. Veterinary Medicines Directorate alignment with EU regulatory frameworks post-Brexit maintains material safety standards. London and Southeast England concentrate veterinary rehabilitation service lines and import distribution.
Canada
Cross-border supply chain integration with US manufacturers supports domestic veterinary clinic procurement. Health Canada veterinary device oversight parallels FDA frameworks for therapeutic claim substantiation. Ontario and Quebec host the majority of accredited rehabilitation facilities serving aging pet populations.
Pet Mobility Aids Market Competitive Landscape
Listed leaders compete with private specialists across channel positioning and certification tiers. Market structure bifurcates between clinical-grade suppliers capturing veterinary clinic volume and mass-market retailers serving standardized harness and ramp categories. Three archetypes dominate: precision-fit prosthetic specialists, direct-to-consumer wheelchair fabricators, and big-box retail distributors. Competitive moves center on veterinary professional education investments and specialty e-commerce platform development.
Within the precision-fit tier, K-9 Orthotics & Prosthetics Inc. and Bionic Pets exemplify patient-specific device capabilities anchored in veterinary referral relationships. Walkin' Pets occupies a position bridging direct-to-consumer accessibility with custom measurement support for large-breed applications. PetSafe represents mass-market distribution scale through retail channel partnerships. These three players illustrate the competitive spectrum from clinical certification to consumer accessibility.
| Leading Market Players |
|---|
| K-9 Orthotics & Prosthetics Inc. |
| PetSafe |
| Walkin' Pets |
| WIMBA |
| Petmate |
| Bionic Pets |
| Paw Prosper |
| OrthoVet LLC |
| Animal Ortho Care |
| Others |
Value Network & Pricing Analysis
Carbon fiber substitution for aluminum framing in premium wheelchair chassis simultaneously shifts sourcing toward East Asian composite manufacturers and compresses per-unit material costs for corrosion-resistant outdoor configurations. This substitution dynamic redistributes supplier power from primary metal processors to specialized polymer fabricators while enabling tiered pricing separation between aerospace-grade composite devices and standard aluminum offerings.
Pricing Analysis
Veterinary clinic procurement teams anchor pricing stratification across premium, standard, and economy tiers based on ISO 10993 certification status and custom-fitting service bundling. Price differentiation hinges on biocompatibility documentation completeness and after-sales gait analysis support, with FDA-substantiated clinical-grade devices commanding substantial premiums over mass-market catalog equivalents. Cost compression in economy harness lines is intensifying because PetSafe and big-box retailers leverage volume scale against Asian contract manufacturers. Individual pet owners exhibit acute price sensitivity for standardized ramps and entry-level slings, while specialty e-commerce buyers of large-breed wheelchairs demonstrate minimal elasticity when congenital mobility failure demands immediate intervention.
Supply Chain Analysis
Inventory buffers for closed-cell foam padding have thinned to eight-week cycles as domestic US and European veterinary device assemblers confront concentrated specialty chemical production in South Korea and Taiwan. Raw material flows draw from Chinese aluminum extrusion facilities, German precision-machining centers for titanium prosthetic hardware, and Japanese injection-molding operations for adjustment components. Single-source vulnerability concentrates in high-density comfort material formulations where three Asian producers control global output. Distribution runs through veterinary distributor networks in Germany and Japan, direct-to-consumer platforms in the United States, and specialty clinic consignment arrangements across North American metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary clinic consolidation into multi-site specialty networks concentrates procurement leverage among fewer buyers with standardized device specifications. This buyer-power shift fragments pricing power away from fragmented individual pet owners toward organized clinical purchasing committees.
For Market Incumbents: Secure exclusive supplier agreements with German and Japanese veterinary orthopedic technician certification programs to lock referral channel access before emerging 3D-printing specialists capture precision-fit volume. Defend margin position through backward integration into captive aluminum tubing supply and ISO 10993 pre-certification of all foam padding formulations. Regulatory tightening under EU Veterinary Medicines Regulation elevates clinical documentation as the priority defensive lever against mass-market competitors lacking dedicated compliance infrastructure. For New Entrants and Emerging Players: Differentiate on additive-manufacturing speed-to-fit by partnering with United States veterinary rehabilitation centers lacking in-house prosthetic fabrication capability. White-space availability concentrates in subscription-based rehabilitation equipment leasing for multi-stage recovery protocols, particularly within orthopedic specialty practices serving sporting dog populations. The most penetrable entry vector targets mid-sized US clinic chains seeking to expand service lines without capital-intensive device inventory. A direct-to-clinic digital measurement platform with 48-hour custom prosthetic turnaround anchors viable go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-fit specialists holding concentrated veterinary referral relationships in Germany and Japan. Long-term viability across the five-to-ten-year window hinges on regulatory compliance scalability rather than manufacturing scale alone. Acquisition targets should display pre-established ISO 10993 documentation libraries and existing FDA Center for Veterinary Medicine correspondence histories. The critical inflection signal to monitor is METI reimbursement pathway expansion for certified mobility aids, which would trigger accelerated clinic procurement cycles and vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Professional Education Investment | Clinic detailing programs build referral loyalty ahead of EU regulatory tightening. |
| Direct-to-Consumer Platform Development | Custom measurement tools capture premium wheelchair demand outside big-box retail. |
| 3D-Printed Prosthetic Precision Convergence | Additive manufacturing integration enables patient-specific geometries for trauma cases. |
| Backward Integration into Aluminum Supply | Captive tubing production insulates margins from primary metal price volatility. |
| Subscription-Based Equipment Access Model | Recurring revenue streams displace outright purchase in US orthopedic practices. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary rehabilitation directors, orthopedic device procurement managers at specialty clinic chains, biomedical engineers at prosthetic fabrication facilities, and regulatory affairs specialists navigating FDA Center for Veterinary Medicine pathways. Secondary validation drew from FDA 510(k) veterinary device filings, EU Veterinary Medicines Regulation guidance documents, ISO 10993 biocompatibility standard revisions, and trade flow data for aluminum and specialty polymer imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for pet care expenditure.
Across the analysis window, forecasts employed a segmented analytical framework spanning product type, end-user channel, raw material composition, and geographic regulatory cluster. Modeled dimensions included wheelchair versus harness versus prosthetic demand splits, veterinary clinic versus direct-to-consumer procurement patterns, and aluminum versus carbon fiber versus foam material trajectories. CAGRs were derived from regression analysis against geriatric companion animal population projections and veterinary service line expansion rates. Industry-specific inputs incorporated METI subsidy program enrollment data and German veterinary orthopedic technician certification throughput.
The analysis sits within stated boundaries; outcomes outside sustained veterinary reimbursement policy expansion or aluminum price stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and specialty clinic accreditation growth. Specific risks that could revise projections include REACH chemical compliance enforcement intensity, single-source foam padding supply disruption, and FDA therapeutic claim restriction expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Vortex Mixer Market
Medical Devices
Spectacle Lens Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Venturi Mask Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Cervical Spine System Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Inversion Table Market