
 Patient Mechanical Lift Handling Equipment Market | 2026-2036
Patient Mechanical Lift Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Mechanical Lift Handling Equipment Market Analysis
Buyer consolidation among hospital systems and multi-facility nursing home chains is repositioning procurement power toward centralized supply agreements. Arjo leverages its integrated ceiling lift architecture to dominate acute care retrofit projects across Nordic and North American installations. Stryker Corporation sustains competitive pressure through its bed-to-lift workflow systems that reduce transfer time in perioperative settings. Medline Industries controls distribution density in the long-term care channel, competing on logistics reach rather than proprietary lift engineering.
Patient mechanical lift handling equipment comprises powered and non-powered assistive devices designed to transfer individuals with limited mobility, typically incorporating sling attachment points, boom articulation ranges of 180 to 360 degrees, and load ratings validated to IEC 60601 safety standards for medical electrical equipment. Floor lifts retain the largest installed base due to their deployment flexibility in retrofit environments, though ceiling lifts command premium positioning in new construction where structural integration reduces floor clutter and improves infection control. Electric technology leads volume shipments as battery systems and smart charging protocols displace hydraulic units in institutional settings where maintenance standardization drives total cost decisions.
The U.S. Food and Drug Administration classifies powered patient lifts as Class I medical devices, requiring compliance with quality system regulations that elevate barriers for unvalidated imports. OSHA's Safe Patient Handling Standards and the EU Medical Device Regulation together mandate injury-reduction documentation and post-market surveillance, forcing manufacturers to invest in clinical outcome data and traceability systems. Stakeholders must monitor how reimbursement coding for safe patient handling programs in Medicare and Medicaid shapes whether facilities prioritize capital purchase or equipment leasing models.
Market Dynamics
Centralized procurement by multi-facility healthcare systems is compressing vendor margins and favoring suppliers with integrated service networks over standalone equipment manufacturers.
Growth Catalysts
- OSHA Safe Patient Handling Standards:US facilities face mandated injury-reduction targets that require powered lift adoption, creating replacement demand across acute and post-acute settings.
- Lithium-ion battery systems:Smart charging protocols and extended cycle life are displacing hydraulic power units in institutional maintenance contracts.
- Home-based care reimbursement:Medicare and Medicaid coding expansion for residential mobility assistance is extending equipment lifecycles beyond traditional facility boundaries.
Market Restraints
- Steel and aluminum input volatility:Boom arm fabrication costs fluctuate with commodity pricing, squeezing margin on floor lift categories where material intensity runs highest.
- Ceiling lift installation complexity:Structural assessment requirements and HVAC coordination extend project timelines in retrofit environments, limiting same-year revenue recognition.
- Manual transfer aids:Low-cost sling and slide sheet alternatives persist in budget-constrained long-term care, fragmenting upgrade pathways.
Strategic Opportunities
- India long-term care infrastructure:Private nursing home construction and medical tourism facilities lack installed lift bases, creating first-mover positioning for IEC 60601-certified suppliers.
- AI-enabled fall prediction:Sensor-integrated ceiling tracks that anticipate transfer instability before sling attachment are opening premium hardware-software bundles.
- Rental and subscription channels:Home medical equipment distributors are piloting monthly billing models that reduce upfront patient burden and improve manufacturer cash flow predictability.
Industry Challenges
- Biomedical technician certification gaps:Complex boom articulation and load cell calibration require specialized training that community college programs have not scaled to match equipment deployment rates.
- IEC 60601-1 third edition compliance timelines:Electromagnetic compatibility testing and risk management documentation extend product launch cycles by 8-14 months for mid-tier manufacturers.
- Legacy sling inventory incompatibility:Proprietary attachment hook geometries lock facilities into single-vendor replacement cycles, complicating competitive displacement efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Mechanical Lift Handling Equipment Market |
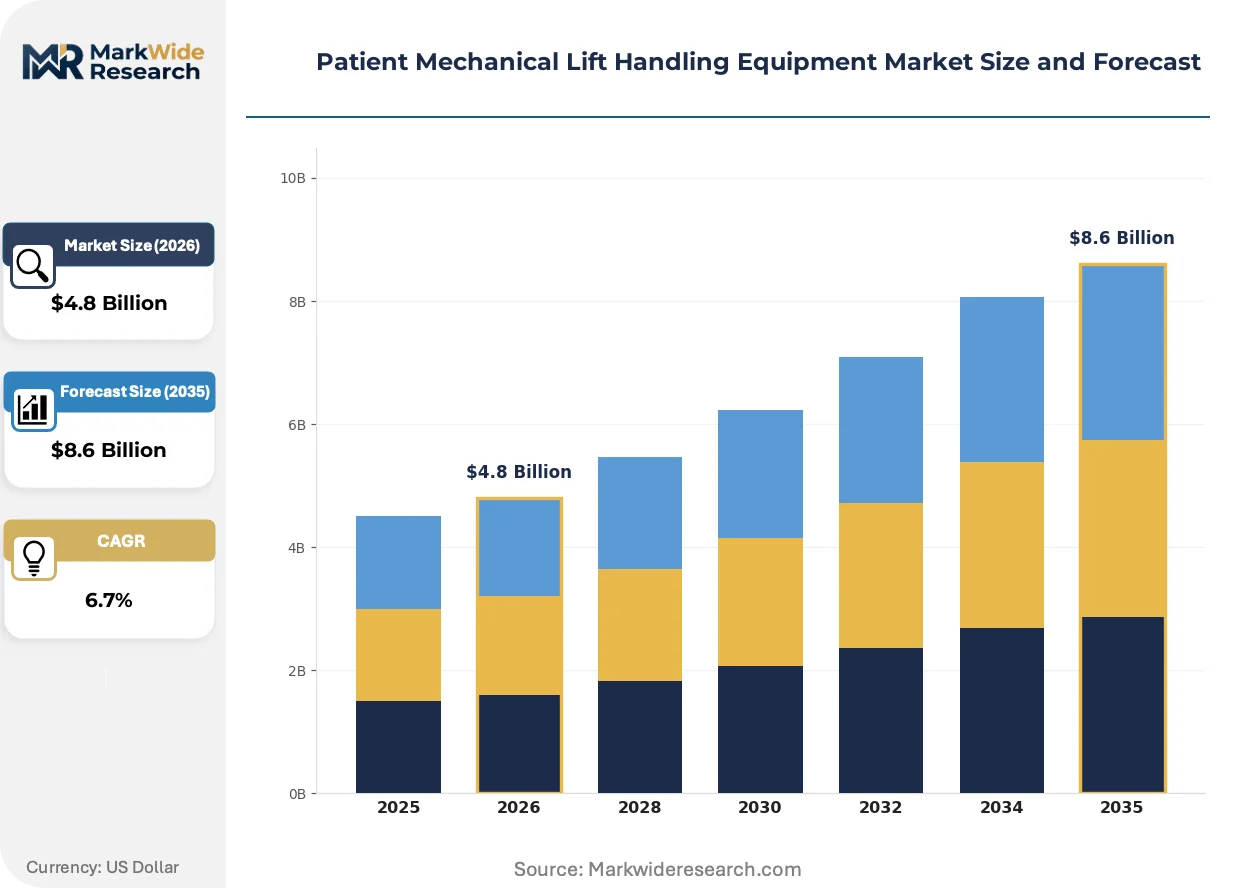
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Lifts, Ceiling Lifts, Sit-to-Stand Lifts, Pool Lifts End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Technology: Hydraulic, Electric, Manual, Pneumatic Capacity: Up to 300 lbs, 301-500 lbs, 501-700 lbs, 701 lbs & Above |
| Companies Covered | Arjo, Stryker Corporation, Invacare Corporation, Sunrise Medical, Savaria Corporation, Medline Industries, Etac, Guldmann, Joerns Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Mechanical Lift Handling Equipment Market Emerging Trajectories
Digital integration and predictive maintenance capabilities are transforming mechanical lifts from passive transfer tools into connected care infrastructure that generates operational data.
Smart load sensing with real-time weight distribution feedback is rewriting how perioperative teams manage bariatric patient transfers. Surgical units in US academic medical centers are retrofitting ceiling tracks with strain-gauge arrays that communicate directly with electronic health records. This convergence is compressing documentation time while creating liability archives that reshape malpractice exposure calculations.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to maintain clinical outcome databases across their installed base. Device history records must now trace individual sling usage cycles and maintenance events. European hospital procurement teams are prioritizing vendors with established traceability systems, effectively filtering out smaller competitors lacking compliance infrastructure.
Consolidated buying cooperatives are displacing individual facility purchasing authority in the US long-term care channel. Multi-state operators now mandate standardized lift specifications across their properties, favoring suppliers with national service networks. This concentration is most visible in the Southeast and Midwest, where regional chains have merged into national platforms with centralized capital budgeting.
Patient Mechanical Lift Handling Equipment Market Segmentation
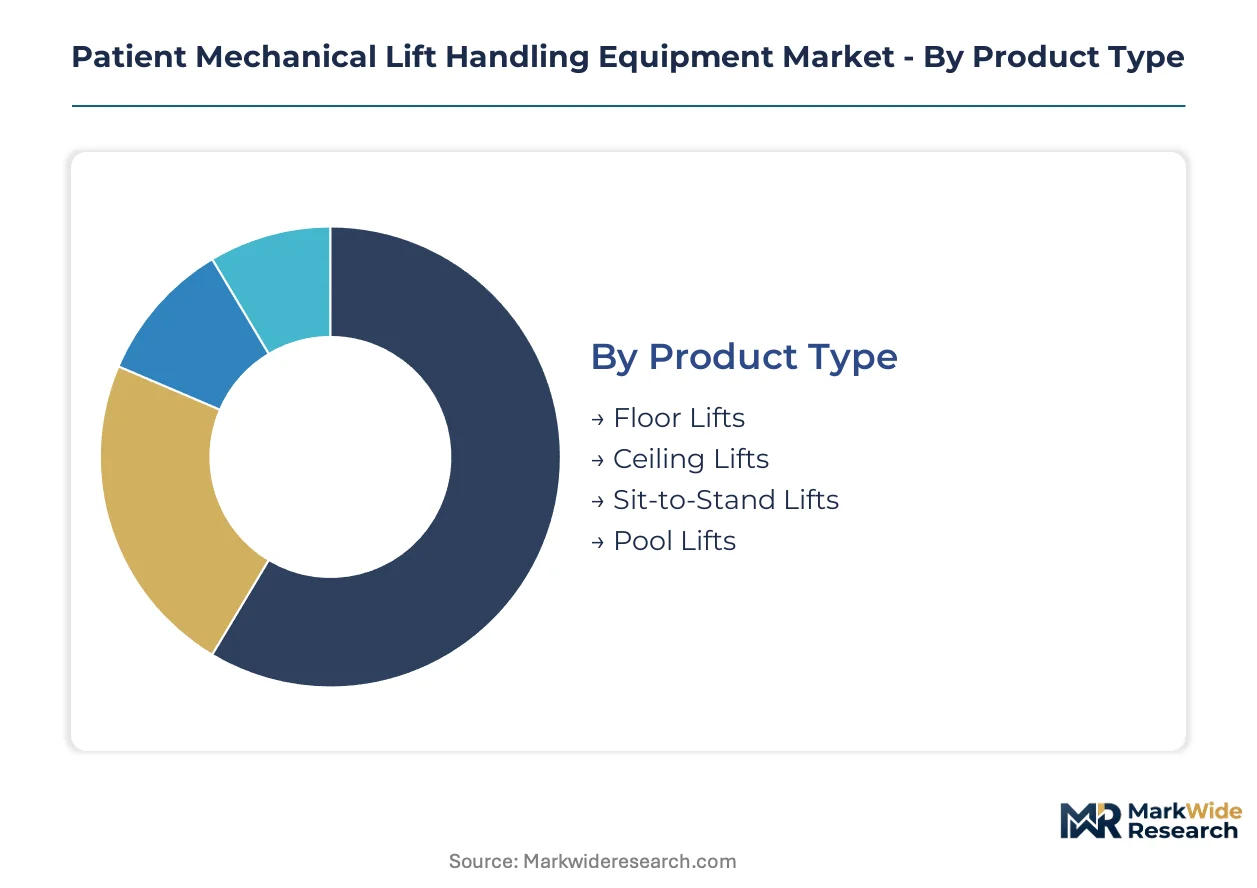
Segmentation in patient mechanical lift handling equipment reveals how procurement priorities diverge across care settings and patient acuity levels. Product architecture, power systems, and load specifications create distinct competitive arenas with margin profiles.
Product Type:
Facility infrastructure constraints and infection control protocols differentiate buyer preferences across these four lift configurations.
- Floor Lifts:Mobile units with wheeled bases and telescoping booms deploy without structural modification. Demand concentrates in US nursing home retrofits where ceiling reinforcement costs deter permanent installation and Medicaid reimbursement caps limit capital budgets.
- Ceiling Lifts:Track-mounted systems integrate into structural framing with motorized trolleys spanning room coverage areas. Academic medical centers in Germany and Sweden prioritize these for bariatric surgery suites where floor clearance and sterile field maintenance drive specifications.
- Sit-to-Stand Lifts:Knee support platforms and torso harnesses assist partial-weight-bearing transfers. Rehabilitation centers in Japan favor these for stroke recovery protocols where early mobilization accelerates discharge timelines.
- Pool Lifts:Water-resistant drive mechanisms and corrosion-resistant frames enable aquatic therapy access. Spinal cord injury centers in Australia and Canada specify these for hydrotherapy programs where buoyancy-assisted movement rebuilds motor function.
Volume sits with Floor Lifts; growth tilts toward Ceiling Lifts.
End User:
Capital availability and reimbursement pathways shape procurement authority across these four care environments.
- Hospitals:Integrated perioperative workflows demand lifts with electronic health record connectivity and rapid cycle times. US health systems with centralized supply agreements negotiate multi-year service contracts that bundle preventive maintenance with equipment lease payments.
- Nursing Homes:OSHA compliance mandates and staff injury liability exposure drive powered lift adoption. Multi-facility chains in the US Southeast standardize on single-vendor fleets to simplify technician training and spare parts inventory.
- Home Care:Medicare Part B durable medical equipment billing codes determine patient cost-sharing obligations. Compact floor lifts with quick-disassembly shipping profiles dominate this channel where residential door widths and ceiling heights constrain installation.
- Rehabilitation Centers:Intensive therapy schedules require lifts with high-duty-cycle motors and rapid battery recharge. German neurological rehabilitation clinics specify premium electric units with programmable patient positioning memory.
Revenue concentrates in Hospitals; expansion accelerates fastest in Home Care.
Technology:
Maintenance standardization and total cost of ownership calculations separate institutional buyers from cost-sensitive purchasers.
- Electric:Brushless DC motors with lithium-ion battery packs and smart charging docks dominate US hospital procurement. Extended cycle life and reduced hydraulic fluid disposal costs justify premium pricing in multi-shift acute care environments.
- Hydraulic:Manual foot-pump or battery-assisted fluid power systems persist in budget-constrained long-term care. Indian private nursing homes favor these where technician training for electronic diagnostics remains scarce and import tariffs elevate spare parts costs.
- Manual:Sling-based transfer aids and slide sheets require no power infrastructure. UK home care agencies distribute these for short-term post-discharge support where equipment rental economics favor disposable solutions.
- Pneumatic:Compressed air drives enable explosion-safe operation in hyperbaric and oxygen-enriched environments. Specialized wound care centers in France specify these for burn unit transfers where electrical spark risks are prohibited.
Electric commands institutional volume; pneumatic carves niche premium positioning.
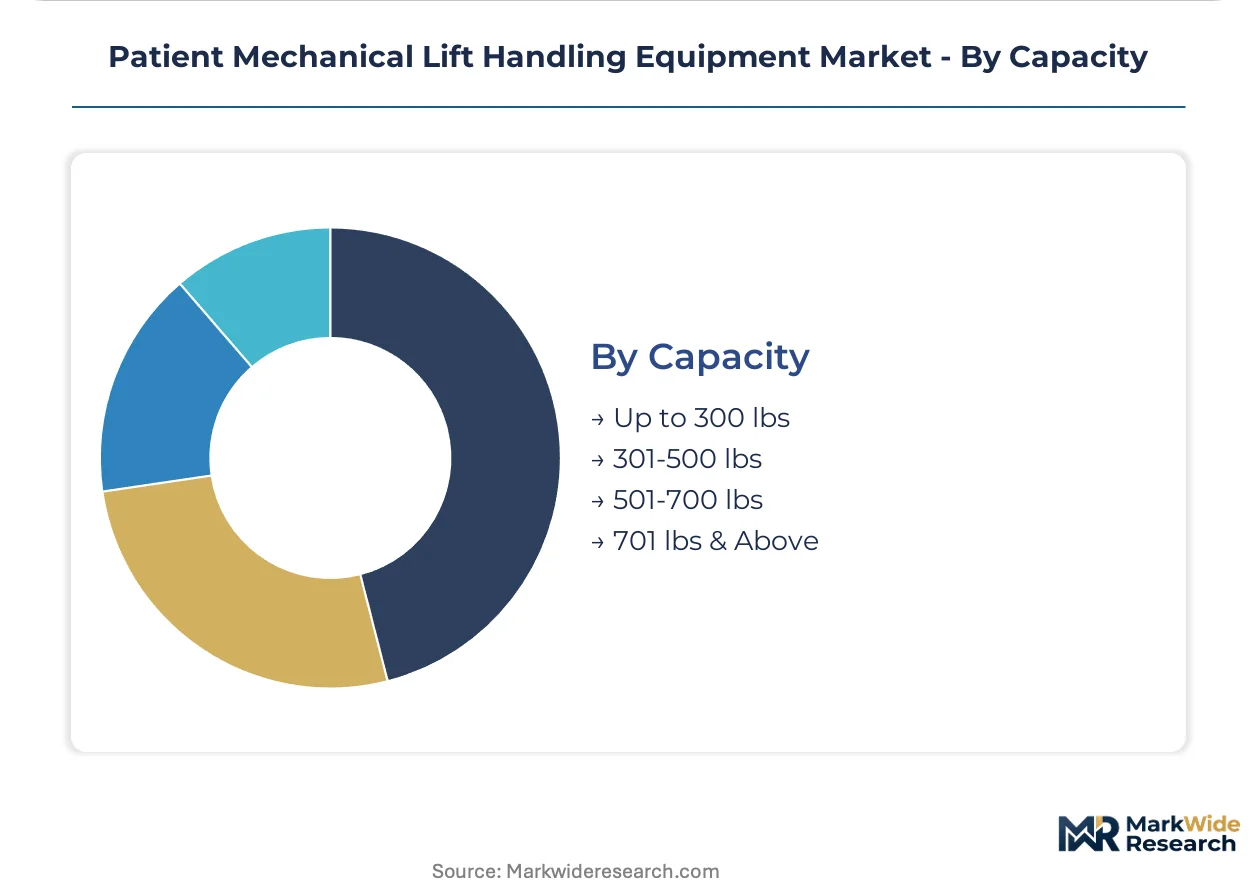
Capacity:
Patient demographics and bariatric surgery volumes determine load rating requirements across care settings.
- Up to 300 lbs:Standard-duty frames with aluminum boom construction serve general medical-surgical populations. Japanese elder care facilities specify these for the majority of transfers given population body mass distributions.
- 301-500 lbs:Reinforced steel structures with wider sling attachment geometries address overweight patient cohorts. US hospitals in the Midwest and South report these ratings as minimum viable specifications given regional obesity prevalence.
- 501-700 lbs:Heavy-duty motors and dual-mast stabilization systems manage severely obese patients. Bariatric surgery centers in Texas and Florida require these for post-operative mobility protocols.
- 701 lbs & Above:Custom-engineered frames with redundant load cells and extended boom reach serve super-obese patients. Academic medical centers with specialized metabolic surgery programs maintain limited inventory given low encounter frequency but catastrophic liability exposure.
301-500 lbs ratings generate highest shipment volumes; 701 lbs & Above carries steepest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in northern Indiana and western Pennsylvania anchor North American lift manufacturing, with aluminum extrusion networks in Quebec supplying boom arm components. Regional demand patterns track closely to aging demographics and reimbursement policy structures.
United States
OSHA's Safe Patient Handling Standards mandate powered lift adoption across acute care and nursing home settings, driving replacement cycles in the Southeast and Midwest where multi-facility chains dominate. Medicare Part B durable medical equipment billing codes shape home care procurement economics, with Texas and Florida bariatric surgery centers requiring 500+ lb capacity specifications.
Germany
The EU Medical Device Regulation's post-market surveillance requirements filter procurement toward vendors with established clinical outcome databases. Bavarian neurological rehabilitation clinics specify premium electric units with programmable positioning memory, while North Rhine-Westphalia's hospital networks prioritize ceiling lift retrofits with electronic health record connectivity.
Japan
METI's elder care infrastructure subsidies accelerate powered lift deployment in Tokyo and Osaka metropolitan facilities. Stroke recovery protocols in Kansai-region rehabilitation centers favor sit-to-stand configurations, with domestic body mass distributions keeping standard 300 lb ratings viable for majority transfers.
India
Private nursing home construction in Maharashtra and Karnataka lacks installed lift bases, creating first-mover positioning for IEC 60601-certified suppliers. Import tariffs elevate spare parts costs, favoring hydraulic units where electronic diagnostic training remains scarce in Delhi-NCR medical corridors.
Australia
TGA's medical device conformity assessment procedures align with IEC 60601 standards, streamlining approval for European and North American imports. Spinal cord injury centers in New South Wales and Victoria specify pool lifts for hydrotherapy programs, with buoyancy-assisted movement protocols rebuilding motor function in Sydney and Melbourne rehabilitation clusters.
Patient Mechanical Lift Handling Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue rental and subscription service models to bypass capital purchase barriers. The vendor base stratifies across integrated system architects, distribution-focused logistics operators, and specialized ceiling lift fabricators. Three archetypes dominate: full-stack providers controlling design-to-installation workflows, channel masters competing on national service reach, and regional specialists capturing retrofit niches. Consolidated buying cooperatives and centralized hospital procurement are compressing margins while favoring multi-year service bundling over standalone equipment sales.
Within the integrated system tier, Arjo and Stryker Corporation exemplify divergent positioning strategies—Arjo anchors acute care retrofit projects through ceiling lift architecture dominance, while Stryker represents workflow-centric perioperative optimization. Medline Industries occupies the channel-master archetype, leveraging distribution density rather than proprietary engineering. Guldmann and Joerns Healthcare sit within the specialized fabricant category, with Etac representing European-centric compliance expertise.
| Leading Market Players |
|---|
| Arjo |
| Stryker Corporation |
| Invacare Corporation |
| Sunrise Medical |
| Savaria Corporation |
| Medline Industries |
| Etac |
| Guldmann |
| Joerns Healthcare |
| Others |
Supply Flow & Price Mechanics
Backward integration into aluminum extrusion and steel fabrication anchors supply positioning and pricing power for patient lift manufacturers serving North American acute care networks. Captive production of boom arm components in Quebec and northern Indiana insulates integrated suppliers from commodity volatility while enabling bundled service contracts that capture multi-year revenue streams.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium ceiling lift vendors from unbundled floor lift competitors in procurement evaluations. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 60601 certification grade and aftermarket service network density. Pricing pressure stems from consolidated buying cooperatives extracting volume discounts across multi-state nursing home chains. Home care distributors exhibit highest price sensitivity due to Medicare Part B reimbursement caps, while academic medical centers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Domestic content mandates in Indian medical device procurement are reshaping sourcing strategies for multinational suppliers seeking public hospital access. Steel and aluminum feedstock draws from US Great Lakes fabrication clusters and Quebec extrusion networks, with lithium-ion battery cells resting on South Korean and Japanese cell manufacturing. Tariff exposure on Chinese-sourced electronic motor controllers creates single-source vulnerability for mid-tier manufacturers. Distribution runs through group purchasing organizations and home medical equipment distributors with regional service technician coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
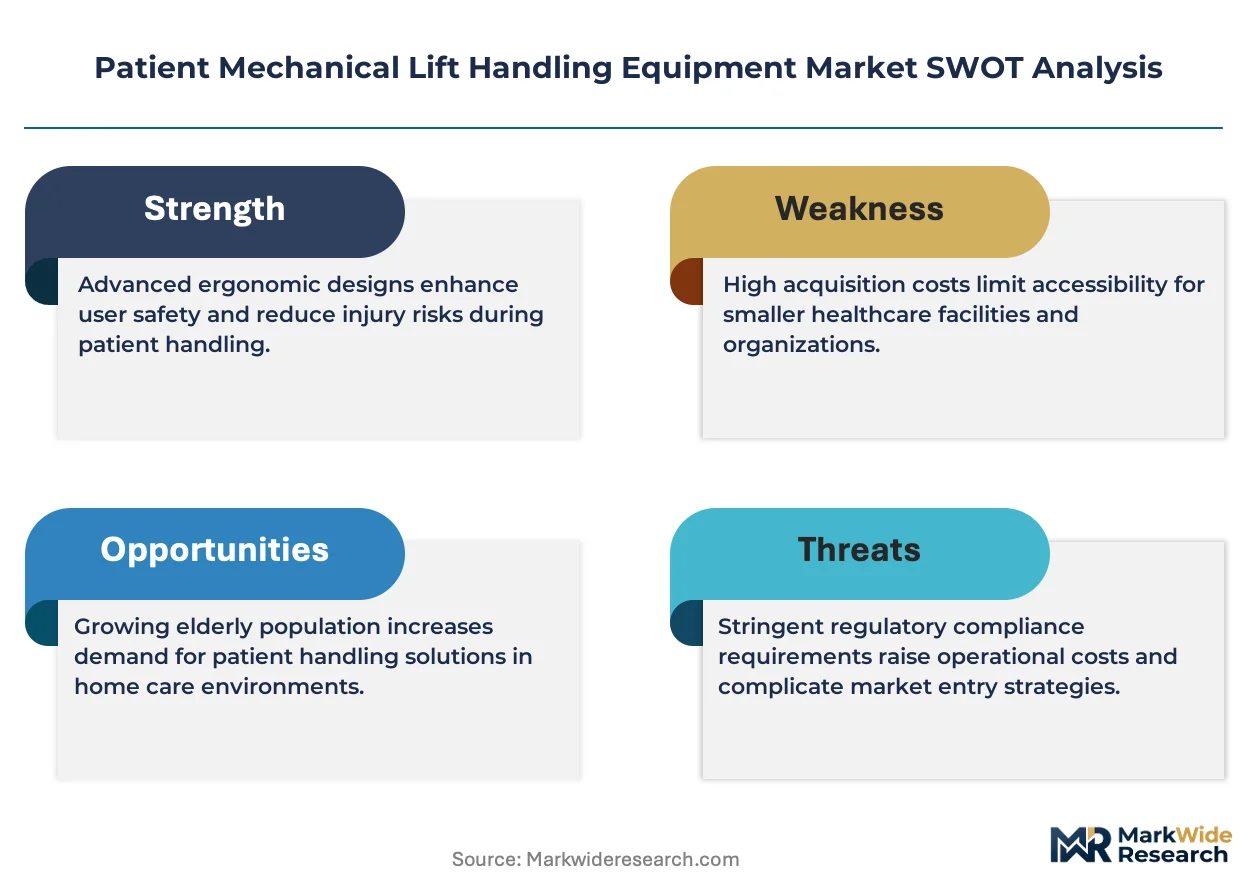
The patient mechanical lift handling equipment market operates as a cost-of-compliance story where FDA Class I device regulations and OSHA Safe Patient Handling Standards erect barrier-to-entry moats favoring established clinical outcome databases.
For Market Incumbents: Extend ceiling lift service contract penetration into existing installed bases to lock out retrofit competitors. Arjo's integrated track architecture demonstrates how proprietary hook geometries create replacement cycle capture. Consolidated buying cooperatives threaten margin compression; respond with national technician certification programs that match multi-facility chain standardization requirements.
For New Entrants and Emerging Players: EU Medical Device Regulation post-market surveillance requirements in Germany and Sweden open a window for software-enabled predictive maintenance platforms that incumbent hardware vendors underinvest in. Target India's private nursing home construction corridor where IEC 60601 certification scarcity filters competition. Pursue rental and subscription revenue models that bypass capital purchase barriers in home care channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-stack medical device conglomerates seeking perioperative workflow integration. The five-to-ten year viability window favors targets with established traceability systems and GPO contract penetration. Monitor Medicare reimbursement coding expansion for residential mobility assistance as the inflection signal for home care channel acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks procurement access in German and Swedish hospital networks. |
| Hospital System Partnership | Multi-year service bundling with US health systems captures replacement cycle revenue. |
| Software Companion Development | AI-enabled fall prediction sensors differentiate ceiling lift hardware-software bundles. |
| Reimbursement Strategy | Medicare Part B coding alignment determines home care distributor economics. |
| Backward Integration | In-house aluminum extrusion insulates margin from commodity price volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and home medical equipment distributors combined with FDA 510(k) databases, OSHA injury reporting statistics, and Medicare claims data. Bottom-up shipment modeling and top-down reimbursement flow analysis provided triangulation validation.
Granularity-level modeling deployed product type, end user facility category, power system technology, and patient weight capacity ratings as core segmentation dimensions across the projection horizon. CAGRs derived from replacement cycle analysis tied to OSHA compliance mandate timelines and facility construction permit data. Input assumptions incorporated lithium-ion battery cost curves and steel commodity futures.
Caveats apply where reimbursement coding revisions or IEC standard updates could materially shift the outlook. Forecasts reflect assumptions regarding OSHA enforcement continuity and Medicare durable medical equipment billing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Global Countertop Platelet Incubator Market