
 Surgical Lighting System Market | 2026-2036
Surgical Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Lighting System Market Intelligence
IEC 60601-2-41 is reorganizing competitive entry in surgical lighting, forcing manufacturers to recalibrate electromagnetic compatibility and optical safety documentation before market access. Stryker Corporation leverages its integrated surgical suite portfolio to bundle lighting with visualization systems, while Trumpf Medical sustains German engineering credibility through precision optics manufacturing. Getinge anchors its position via sterile processing adjacencies that cross-sell into operating room infrastructure.
A surgical lighting system comprises ceiling-mounted, wall-mounted, portable, or floor-standing luminaires delivering adjustable intensity and color temperature for operative visualization, typically employing LED arrays rated above 160,000 lux with correlated color temperatures near 4,500K to minimize tissue color distortion. LED product type commands the dominant share as halogen and xenon installations face phase-out from thermal load and mercury disposal constraints, while dimmable technology captures margin pools through software-controlled ambient adaptation. Wireless connectivity segments grow fastest as operating rooms integrate lighting into centralized building management protocols.
FDA 510(k) clearance requirements govern US market entry for surgical lighting systems, while the EU Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations than predecessor directives. Germany's KBA-equivalent health technology assessment bodies evaluate operating room equipment procurement at federal-state levels, creating heterogeneous approval timelines. Stakeholders must monitor how IEC revision cycles synchronize with national adoption schedules to avoid certification lag.
Market Dynamics
LED array miniaturization and IEC 60601-2-41 electromagnetic compatibility mandates are compressing product development cycles while elevating certification barriers for new entrants into surgical lighting manufacturing.
Growth Catalysts
- EU Medical Device Regulation:Stricter post-market surveillance obligations in European markets are filtering out marginal suppliers and concentrating procurement among certified incumbents with established quality management systems.
- Ambulatory surgical centers:Freestanding outpatient facilities are retrofitting surgical suites with LED-based systems to meet tightening energy efficiency mandates in healthcare infrastructure codes.
- German hospital modernization:Federal-state procurement programs prioritizing operating room upgrades are channeling capital expenditure toward integrated lighting-visualization bundles in tertiary care facilities.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control critical lens and reflector manufacturing, creating single-source vulnerability for mid-tier lighting assemblers.
- IEC 60601-2-41 revision cycles:Electromagnetic compatibility retesting requirements during standard updates impose recurring certification costs that disadvantage smaller manufacturers without dedicated regulatory affairs teams.
- Halogen phase-out stranded assets:Healthcare systems with recent xenon or halogen installations face accelerated depreciation pressure as thermal load and mercury disposal constraints render legacy systems non-compliant with environmental regulations.
Strategic Opportunities
- Wireless building management integration:Operating rooms in US academic medical centers are adopting DALI-2 and Bluetooth Mesh protocols that enable lighting control through centralized facility automation platforms.
- India's PLI scheme for medical devices:Production-linked incentive structures for domestic manufacturing are attracting component suppliers to establish LED driver and heat sink fabrication near Pune and Chennai medical device clusters.
- Color-tunable surgical task lighting:Multi-LED array systems enabling real-time correlated color temperature adjustment between 3,500K and 5,500K are penetrating neurosurgical and plastic surgery suites where tissue color discrimination is critical.
Industry Challenges
- Optical engineering talent scarcity:Precision illumination design expertise resides with aging specialists in German and Japanese manufacturing centers, constraining R&D expansion for emerging market competitors.
- Legacy surgical suite integration:Ceiling-mounted luminaire replacement in older hospital infrastructure requires structural reinforcement and electrical rewiring that extends installation timelines and disrupts operating room utilization.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel LED configurations increasingly reference discontinued halogen predicates, complicating clearance pathways for innovative optical designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Lighting System Market |
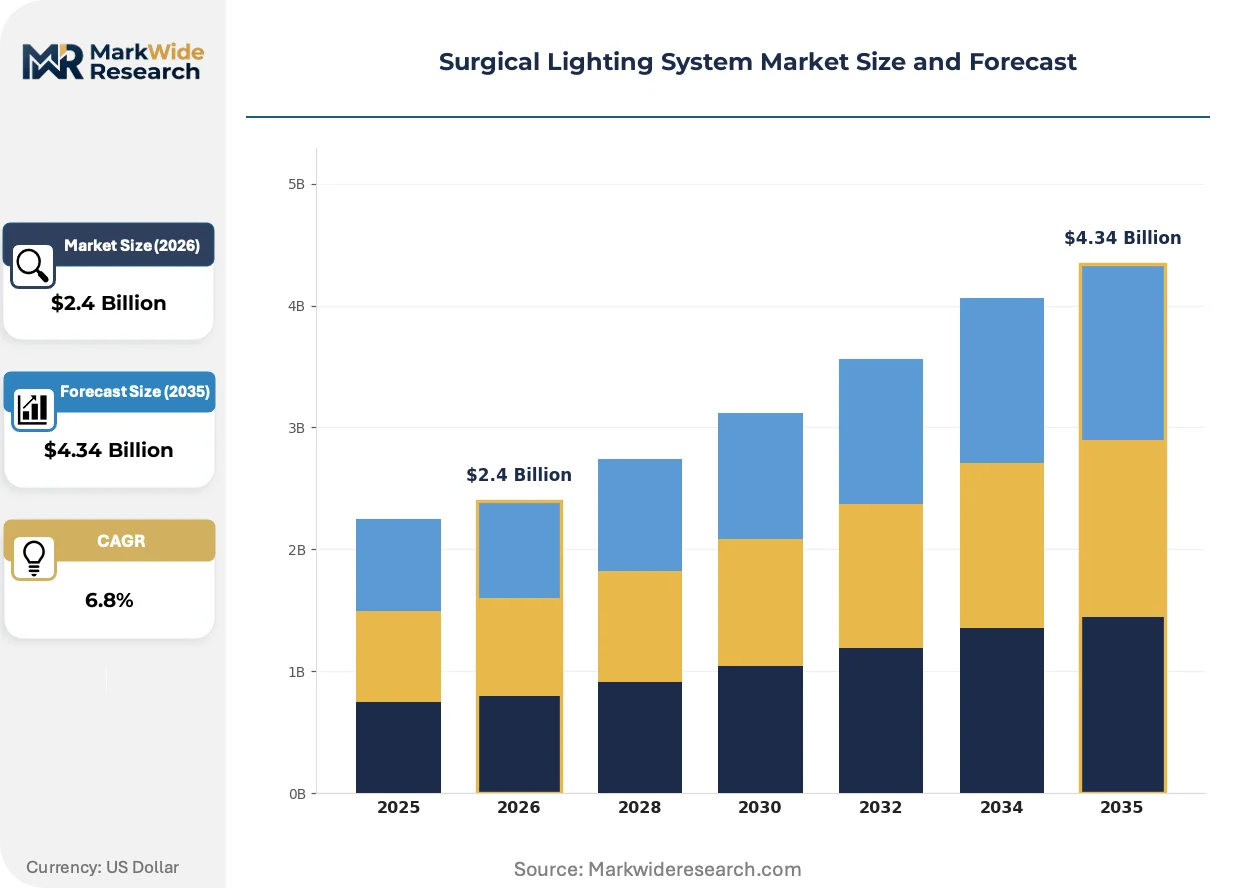
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent End User: Hospitals, Surgical Centers, Clinics, Research Labs Technology: Wireless, Dimmable, Fixed, Mobile Installation: Ceiling Mounted, Wall Mounted, Portable, Floor Standing |
| Companies Covered | Skytron, Trumpf Medical, STERIS, Stryker Corporation, Getinge, Amico Group of Companies, Burton Medical, NUVO, Herbert Waldmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Lighting System Market Strategic Shifts & Innovations
Active reshaping of surgical lighting centers on three vectors: component miniaturization enabling new mounting configurations, regulatory harmonization compressing certification timelines, and procurement centralization altering vendor-buyer power dynamics.
Chip-on-board LED packaging is miniaturizing emitter arrays while maintaining output above 160,000 lux, allowing ambulatory surgical centers to deploy wall-mounted and floor-standing configurations previously restricted to ceiling-suspended systems. German manufacturers are adopting these compact modules to serve renovation-constrained urban hospitals where structural ceiling loads prohibit traditional pendant installations. The technology is miniaturizing physical footprints without sacrificing illuminance uniformity, opening procurement channels in satellite surgical facilities and military field hospitals.
EU Medical Device Regulation clinical evaluation requirements are extending technical documentation obligations for Class I surgical lighting systems previously exempt under Medical Device Directive frameworks. German notified bodies are interpreting post-market surveillance mandates to require real-time failure reporting from installed luminaires, forcing manufacturers to embed connectivity modules as standard rather than optional features. Tertiary care systems in France and the Netherlands are prioritizing vendors with established EU MDR certificates, compressing competitive windows for transitional suppliers.
Consolidated procurement through US group purchasing organizations is unbundling lighting from broader operating room capital equipment packages, enabling specialized vendors to compete against integrated suite providers. Academic medical centers in Boston and Cleveland are issuing standalone surgical lighting tenders that separate illuminance specifications from visualization and boom system integrations. This disaggregation is most visible in mid-tier community hospitals seeking to modernize single suites without full surgical platform replacements, creating entry points for focused lighting specialists against diversified incumbents.
Surgical Lighting System Market Segmentation
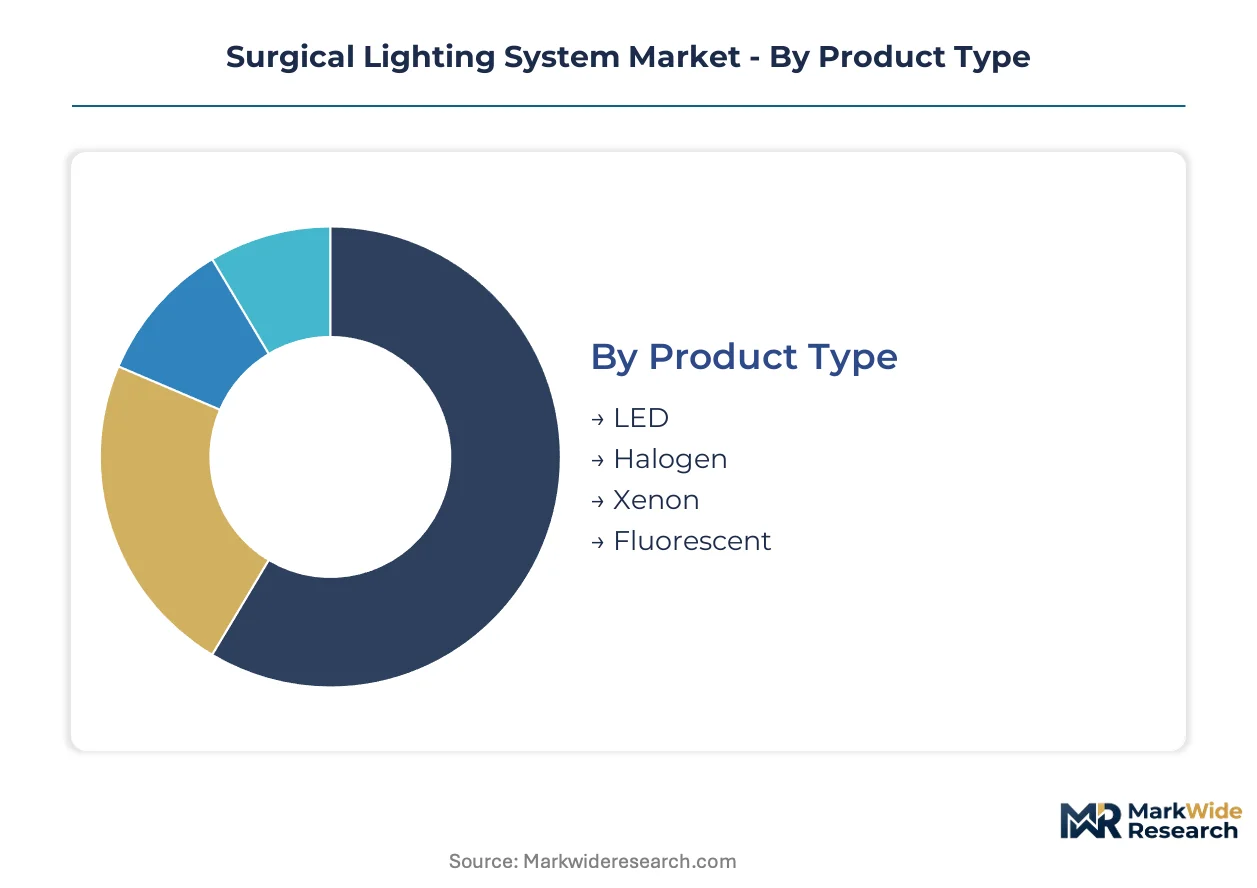
Surgical lighting segmentation reveals how technology substitution and regulatory pressure reshape procurement patterns across healthcare infrastructure. Product type and installation configuration drive capital allocation decisions, while end-user scale determines connectivity and integration requirements.
Product Type:
LED arrays face minimal substitution threat as thermal and disposal regulations accelerate legacy system phase-outs.
- LED:Chip-on-board packaging delivers illuminance above 160,000 lux with correlated color temperatures near 4,500K. German hospital modernization programs and US ambulatory surgical center retrofits concentrate procurement of these systems as IEC 60601-2-41 compliance mandates tighten.
- Halogen:Tungsten-filament technology generates excessive thermal loads that distort tissue visualization and strain HVAC systems. Stranded asset risk mounts as environmental regulations in developed markets prohibit mercury-bearing component disposal.
- Xenon:High-intensity discharge lamps maintain presence in legacy surgical suites but face accelerated depreciation from energy efficiency benchmarking.
- Florescent:Linear tube configurations persist in minor procedure rooms and developing market clinics where capital constraints delay LED conversion.
LED retains volume leadership; wireless-enabled variants hold the steepest expansion curve.
End User:
Facility scale determines integration complexity and connectivity specification tiers.
- Hospitals:Tertiary care systems in Germany and academic medical centers in Boston and Cleveland procure integrated lighting-visualization bundles with DALI-2 building management protocols.
- Surgical Centers:Freestanding outpatient facilities drive LED retrofit demand as energy efficiency mandates tighten across healthcare infrastructure codes.
- Clinics:Minor procedure rooms prioritize wall-mounted and portable configurations over ceiling-suspended systems.
- Research Labs:Specialized illumination requirements for microsurgical training and tissue analysis sustain demand for color-tunable arrays.
Hospitals dominate installed base; surgical centers are climbing fastest in annual procurement volume.
Technology:
Control sophistication separates premium installations from commodity replacements.
- Wireless:Bluetooth Mesh and DALI-2 protocols enable centralized facility automation integration. US academic medical centers prioritize these systems for operating room building management synchronization.
- Dimmable:Software-controlled ambient adaptation captures margin pools through real-time intensity adjustment during procedure phases.
- Fixed:Basic on-off operation persists in cost-constrained installations and emergency backup configurations.
- Mobile:Battery-powered units serve field hospitals and temporary surgical facilities where permanent infrastructure is unavailable.
Wireless commands premium positioning; dimmable systems scale most rapidly across mid-tier facility upgrades.
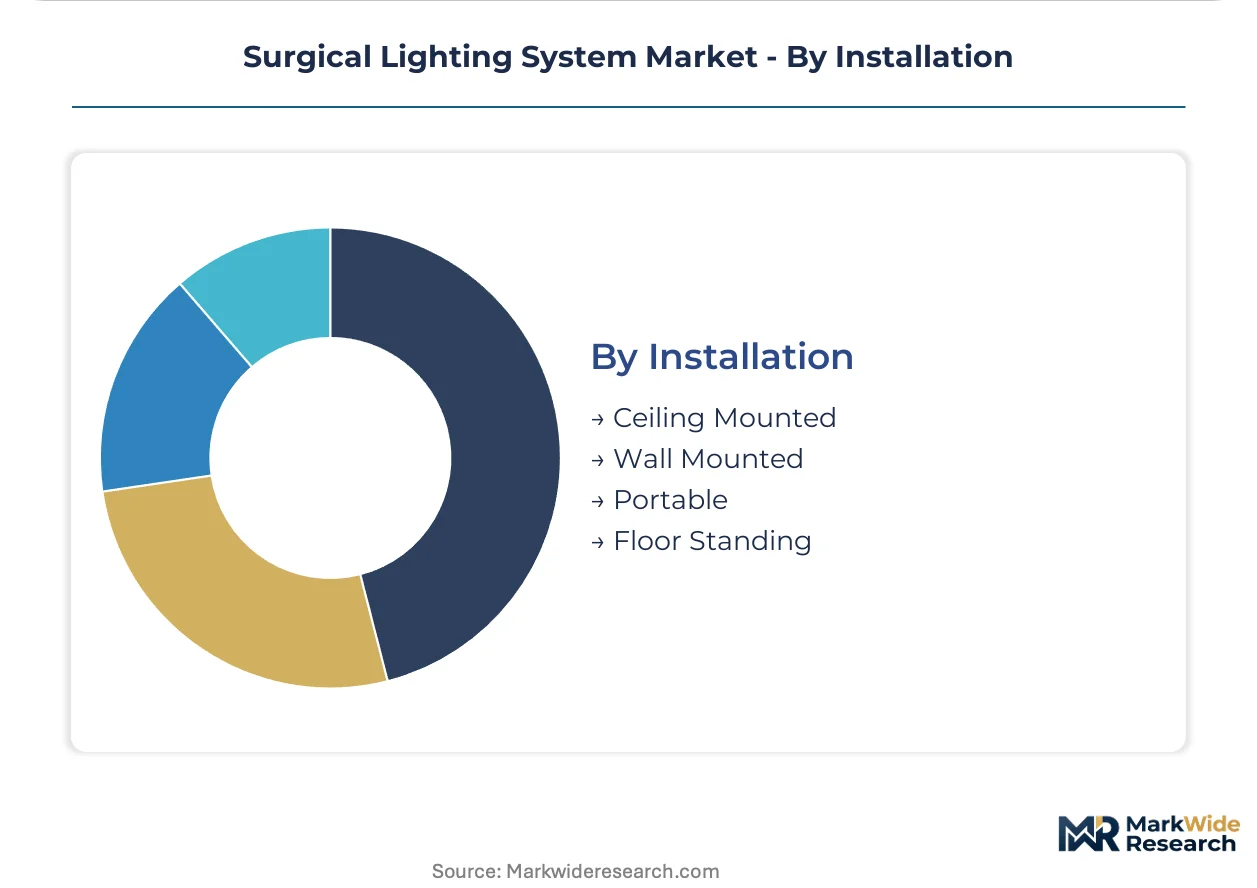
Installation:
Mounting configuration constraints dictate procurement options in renovation versus new construction scenarios.
- Ceiling Mounted:Pendant-suspended luminaires require structural reinforcement and electrical rewiring that extends installation timelines in older hospital infrastructure.
- Wall Mounted:Compact LED modules enable deployment in urban hospitals where structural ceiling loads prohibit traditional installations.
- Portable:Floor-standing units with casters serve military field hospitals and satellite surgical facilities requiring rapid redeployment.
- Floor Standing:Stabilized base configurations support minor procedure rooms and outpatient clinics with limited ceiling access.
Ceiling mounted maintains dominant share; wall mounted gains fastest in renovation-constrained metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement programs and energy efficiency mandates are redirecting capital expenditure toward surgical suite modernization across developed healthcare systems. Hospital infrastructure codes in multiple jurisdictions now mandate LED conversion timelines. Certification requirements under IEC 60601-2-41 are synchronizing at uneven speeds across national adoption schedules.
United States
Ambulatory surgical centers in Texas and Florida are retrofitting suites with LED-based systems to comply with tightening healthcare infrastructure energy codes. FDA 510(k) clearance pathways govern market entry, with substantial equivalence determinations increasingly referencing legacy halogen predicates. Boston and Cleveland academic medical centers are issuing standalone surgical lighting tenders that separate illuminance specifications from integrated suite bundles.
Germany
Federal-state hospital modernization programs are channeling capital toward operating room upgrades in tertiary care facilities. KBA-equivalent health technology assessment bodies evaluate equipment procurement at regional levels, creating heterogeneous approval timelines. Precision optics manufacturing clusters in Baden-Württemberg and Bavaria sustain engineering credibility for domestic lighting assemblers serving renovation-constrained urban hospitals.
China
Domestic medical device production is expanding under NMPA regulatory frameworks that align with IEC electromagnetic compatibility standards. Yangtze River Delta medical device clusters near Shanghai are attracting LED driver and heat sink fabrication capacity. Hospital construction in provincial capitals is prioritizing ceiling-mounted configurations with building management protocol integration.
India
Production-linked incentive schemes for medical devices are drawing component suppliers to establish fabrication near Pune and Chennai clusters. CDSCO regulatory pathways are streamlining for Class I surgical lighting systems with established international certifications. Metropolitan hospital networks in Maharashtra and Karnataka are modernizing surgical suites with wall-mounted LED configurations where structural constraints prohibit pendant installations.
Japan
PMDA quality management system requirements are filtering procurement toward established incumbents with documented post-market surveillance capabilities. METI energy efficiency benchmarks are accelerating halogen phase-out in metropolitan hospital systems. Osaka and Nagoya medical device manufacturing centers maintain precision illumination design expertise that constrains R&D expansion for emerging competitors.
Surgical Lighting System Market Key Industry Players
Listed leaders compete with private specialists across certification bandwidth and integrated suite portfolios. The vendor base stratifies between diversified medical technology conglomerates and focused illumination manufacturers. Three archetypes dominate: integrated surgical suite providers bundling lighting with visualization systems, precision optics specialists leveraging German engineering credibility, and component-scale assemblers serving cost-constrained retrofit markets. Competitive moves concentrate on M&A for regulatory certification assets and strategic partnerships for wireless protocol integration.
Within the integrated suite tier, Stryker Corporation and Getinge exemplify diversified incumbents leveraging sterile processing and visualization adjacencies to cross-sell operating room infrastructure. Trumpf Medical occupies a position among precision optics specialists, its German engineering origin aligning with federal-state procurement preferences for documented electromagnetic compatibility. Skytron represents the mid-scale specialist archetype, competing through standalone lighting tenders that disaggregate illuminance specifications from broader capital equipment packages in US academic medical centers and community hospital renovations.
| Leading Market Players |
|---|
| Skytron |
| Trumpf Medical |
| STERIS |
| Stryker Corporation |
| Getinge |
| Amico Group of Companies |
| Burton Medical |
| NUVO |
| Herbert Waldmann GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Ninety-day optical component lead times from Baden-Württemberg suppliers compress inventory buffers for mid-tier assemblers while amplifying pricing power for certified incumbents with strategic stockpiles. This inventory constraint tightens procurement leverage for German precision optics manufacturers serving renovation-driven hospital demand.
Pricing Analysis
Certification level (ISO/IEC 60601-2-41/FDA-grade) creates the primary spread between premium LED surgical luminaires and commodity replacements. Three-tier pricing structure across premium, standard, and economy levels reflects electromagnetic compliance documentation depth and wireless protocol integration. Cost compression in mid-tier segments intensifies because halogen phase-out accelerates replacement demand without proportional supply expansion. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German tertiary care systems prioritize certification pedigree over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate LED driver procurement as manufacturers buffer against semiconductor lead-time volatility in medical-grade component markets. German, Japanese, and Chinese manufacturing clusters anchor precision lens, heat sink, and emitter array fabrication. Supply chains draw from specialized optical glass, aluminum thermal substrates, and medical-grade power electronics. Single-source vulnerability concentrates in German precision reflector manufacturing. Distribution runs through hospital group purchasing organizations and specialized medical device distributors serving regional procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from wireless connectivity modules and predictive maintenance contracts expands faster than hardware sales as EU MDR mandates embed monitoring capabilities as standard features. Recurring software licensing for building management protocol integration captures margin pools beyond initial luminaire installation.
For Market Incumbents: Compound sterile processing adjacencies into bundled operating room infrastructure contracts that cross-sell lighting with visualization and boom systems. Deepen backward integration into LED driver manufacturing to offset semiconductor supply volatility. Prioritize IEC 60601-2-41 pre-certification for next revision cycles to maintain regulatory lead time advantage over emerging competitors.
For New Entrants and Emerging Players: CDSCO fast-track pathways for Class I surgical lighting with established FDA or CE predicates offer accelerated Indian market entry. Target wall-mounted LED configurations in metropolitan hospital renovations where structural ceiling constraints exclude pendant specialists. Pursue standalone lighting tenders from US academic medical centers disaggregating illuminance specifications from integrated suite bundles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized medical lighting divisions lacking dedicated regulatory affairs infrastructure. Five-to-ten year viability hinges on wireless protocol integration capabilities and EU MDR certificate maintenance. Monitor IEC revision cycle synchronization with national adoption schedules as inflection indicator for certification asset valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements compress competitive windows for transitional suppliers without notified body relationships. |
| Hospital System Partnership | Bundled procurement through GPOs enables lighting specialists to compete against integrated suite providers in standalone tenders. |
| Software Companion Development | DALI-2 and Bluetooth Mesh integration captures building management protocol margins beyond hardware installation. |
| Backward Integration into Optics | In-house precision reflector manufacturing mitigates single-source vulnerability from German component suppliers. |
| Reimbursement Strategy | Federal-state health technology assessment alignment in Germany accelerates capital expenditure approval for certified systems. |
Research Approach
The analysis maps LED surgical luminaires, halogen legacy systems, and wireless-enabled configurations, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and IEC standard revision documentation. Bottom-up installation data triangulates against top-down healthcare infrastructure expenditure estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, installation configuration, end-user facility scale, and technology control sophistication. CAGRs derived from procedure volume growth, replacement cycle acceleration, and energy efficiency mandate compliance curves. Forecast inputs incorporate LED penetration rates in ambulatory surgical centers and German federal-state modernization program allocations.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions about IEC 60601-2-41 adoption timelines and semiconductor supply normalization. Revision becomes warranted when electromagnetic compatibility retesting requirements or optical component lead times cross volatility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Blood Bank Refrigerators Market