
 Surgical Generators Market | 2026-2036
Surgical Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Generators Market Analytics
EU MDR is recalibrating the cost-of-entry calculus for surgical generator manufacturers seeking CE-marked distribution across European territories. Medtronic leverages its vertically integrated energy platform to sustain compliance economies that mid-scale competitors cannot replicate. Erbe Elektromedizin GmbH anchors its position through specialized electrosurgical R&D intensity centered in Tuebingen, while Olympus Corporation competes by extending its visualization-integrated generator systems into hybrid surgical workflows.
Surgical generators are electromechanical devices that convert electrical energy into thermal or plasma-based tissue effects, typically operating at frequencies between 300 kHz and 3 MHz for cutting, coagulation, and vessel sealing during operative procedures. Electrosurgical generators occupy the largest installed base among product categories, though advanced energy systems within the technological offering dimension command premium positioning as hospitals phase out legacy monopolar platforms. Radiofrequency generators are gaining procedural share in orthopedic surgery and pain management interventions where tissue ablation precision determines reimbursement eligibility.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for manufacturers serving transatlantic markets. BIS certification in India and NMPA registration in China add parallel compliance layers that favor established multinationals with dedicated regulatory affairs infrastructure. Stakeholders must monitor how automated systems and disposable electrode configurations reshape capital-versus-consumable revenue models across consolidated hospital networks.
Market Dynamics
EU MDR recertification deadlines are compressing supplier qualification windows, forcing hospital procurement departments to consolidate vendor relationships around platforms with pre-validated technical documentation and established notified body partnerships.
Growth Catalysts
- Minimally invasive procedure expansion:Laparoscopic and robotic-assisted surgeries in gynecology and general surgery drive installed base refresh cycles for electrosurgical units with advanced vessel-sealing capabilities.
- FDA 510(k) streamlined pathways:Predicate device referencing for RF generator modifications accelerates commercial launch sequencing for manufacturers with established regulatory affairs infrastructure.
- Germany hospital consolidation:Large university medical centers in Baden-Wuerttemberg and Bavaria standardize procurement around integrated energy platforms, concentrating demand among qualified suppliers.
Market Restraints
- Notified body capacity constraints:EU MDR technical documentation review queues extend certification timelines, freezing new product introductions for mid-scale manufacturers lacking dedicated compliance teams.
- High-purity copper and semiconductor shortages:Power electronics supply concentration in East Asian foundries creates input cost volatility for RF amplifier modules and switching components.
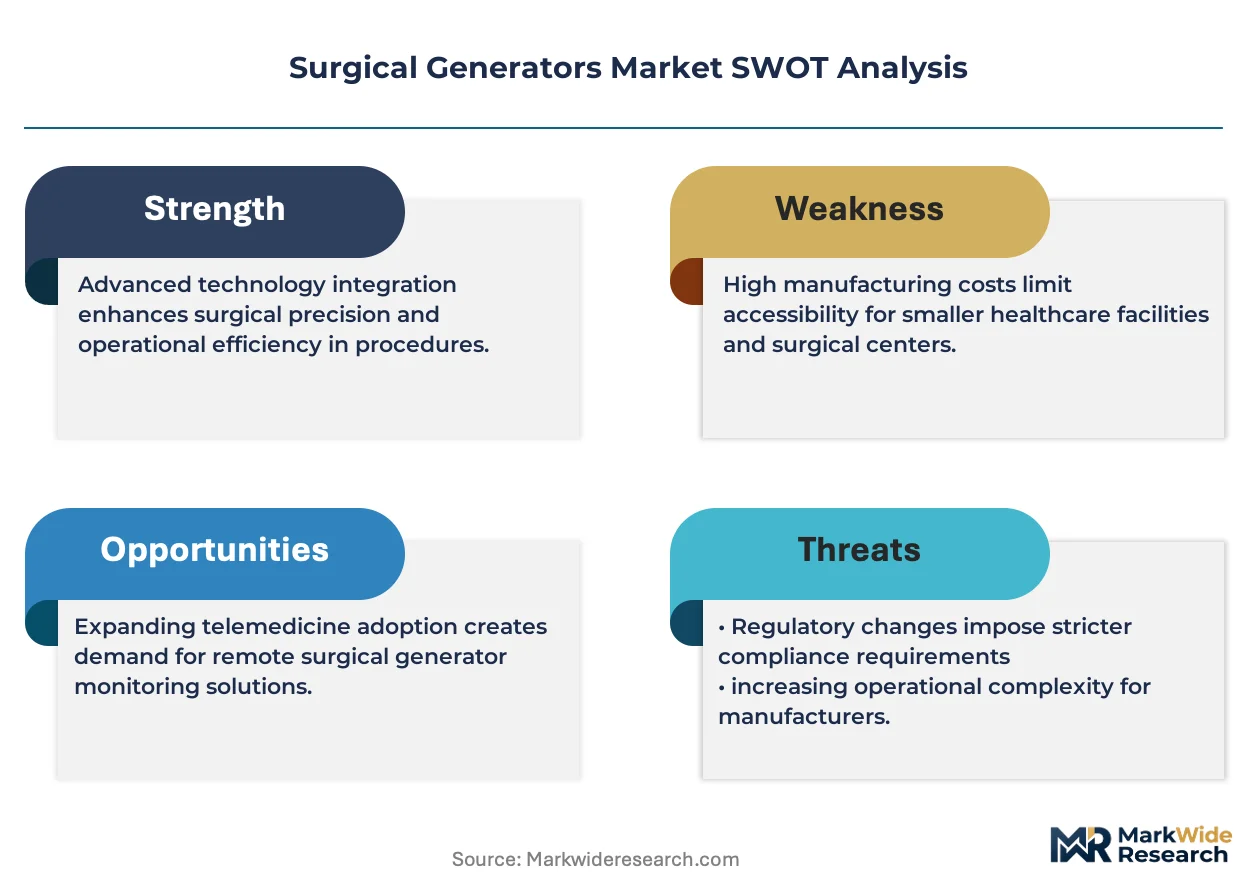
- Plasma-based vessel sealers:Advanced bipolar systems with tissue impedance feedback reduce procedural time for general surgery applications, threatening monopolar generator replacement demand.
Strategic Opportunities
- India tertiary hospital expansion:CDSCO fast-track registration for Class B electrosurgical devices opens procurement channels in Delhi and Mumbai metropolitan clusters where surgical volume growth outpaces equipment availability.
- AI-powered tissue recognition:Machine learning algorithms for real-time power modulation are integrating with generator firmware to enable autonomous coagulation endpoint detection.
- Outpatient ambulatory surgery center penetration:Compact, portable RF units with disposable electrode configurations address capital constraints in US freestanding ASC networks.
Industry Challenges
- Biomedical engineering talent scarcity:Electromechanical design expertise for high-frequency power electronics concentrates in Germany and Japan, constraining R&D scaling for emerging market manufacturers.
- Legacy system integration complexity:Hospital IT departments face protocol mismatches when connecting new generator platforms to existing surgical navigation and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Generators Market |
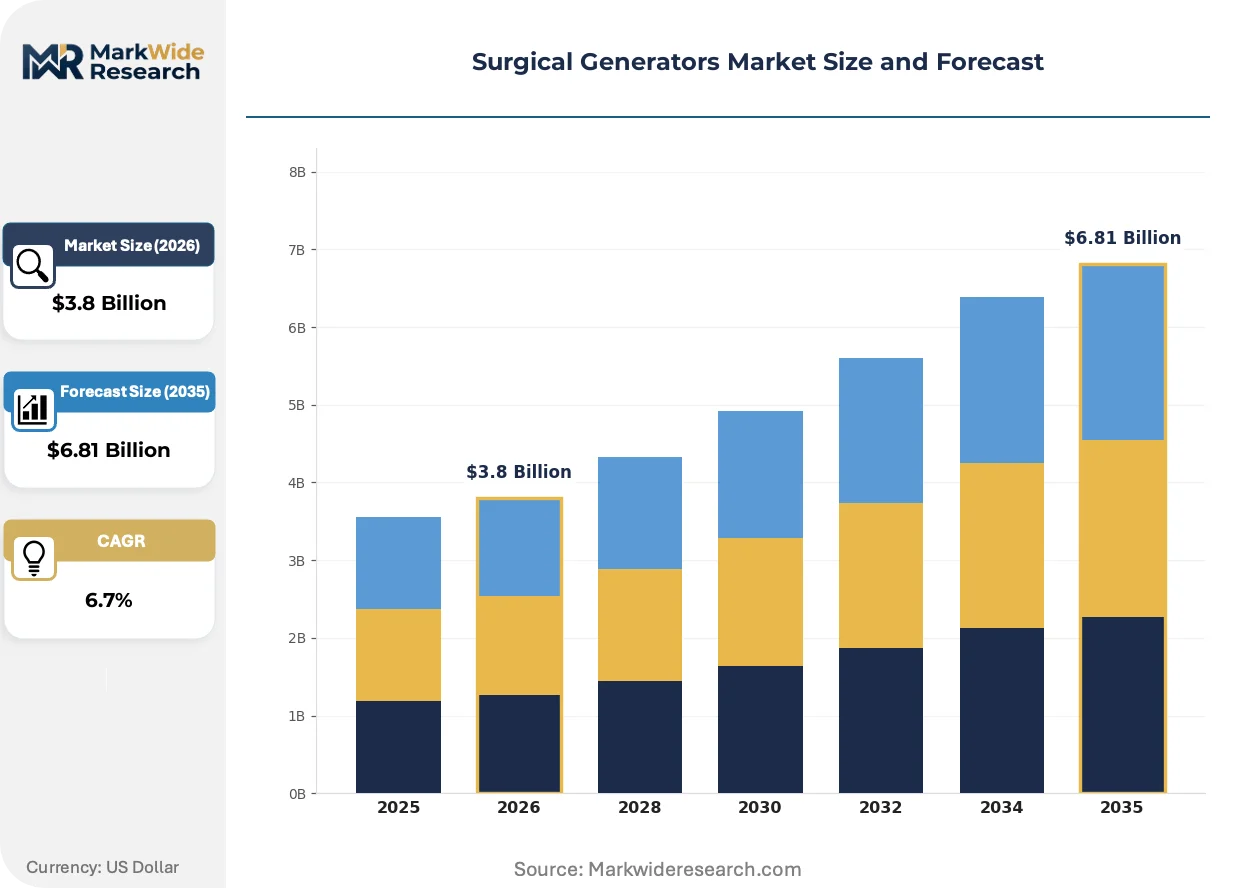
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Generators, Radiofrequency Generators, Laser Generators, Argon Plasma Generators Application: General Surgery, Gynecology, Urology, Orthopedic Surgery End User: Hospitals, Surgical Centers, Clinics, Academic Institutions Technological Offering: Advanced Energy Systems, Hybrid Generators, Disposable Electrode Systems, Automated Systems |
| Companies Covered | Medtronic, Olympus Corporation, CONMED Corporation, Johnson & Johnson Services, Inc., B. Braun Melsungen AG, Erbe Elektromedizin GmbH, Stryker, Boston Scientific Corporation, KARL STORZ GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Generators Market Evolving Landscape
Smart energy delivery systems are redefining tissue interaction protocols, shifting competitive advantage from raw power output to real-time adaptive control and procedural outcome predictability.
Intelligent impedance-sensing generators are integrating machine learning-based tissue classification algorithms to automate power modulation during vessel sealing. Academic medical centers in Japan and Germany are piloting these systems for hepatic and pancreatic resections. The technology is integrating predictive coagulation models into surgical workflow software, compressing training curves for residents and standardizing outcomes across operator experience levels.
EU MDR Annex XIV post-market surveillance requirements mandate systematic clinical follow-up for electrosurgical devices with novel energy modalities. Manufacturers must establish quality management system extensions for proactive adverse event reporting. High-frequency surgical equipment with plasma-based cutting functions faces the most intensive scrutiny, driving consolidation of technical documentation resources among firms with established European regulatory infrastructure.
Hospital procurement departments are unbundling capital equipment purchases from long-term service agreements, forcing generator manufacturers to compete on transparent lifecycle cost models. German purchasing cooperatives now separate device acquisition from preventive maintenance contracts, enabling multi-vendor equipment rooms. This pattern is most visible in Baden-Wuerttemberg and North Rhine-Westphalia, where hospital network consolidation has centralized sourcing decisions for energy platforms across 40-plus facility clusters.
Surgical Generators Market Segmentation
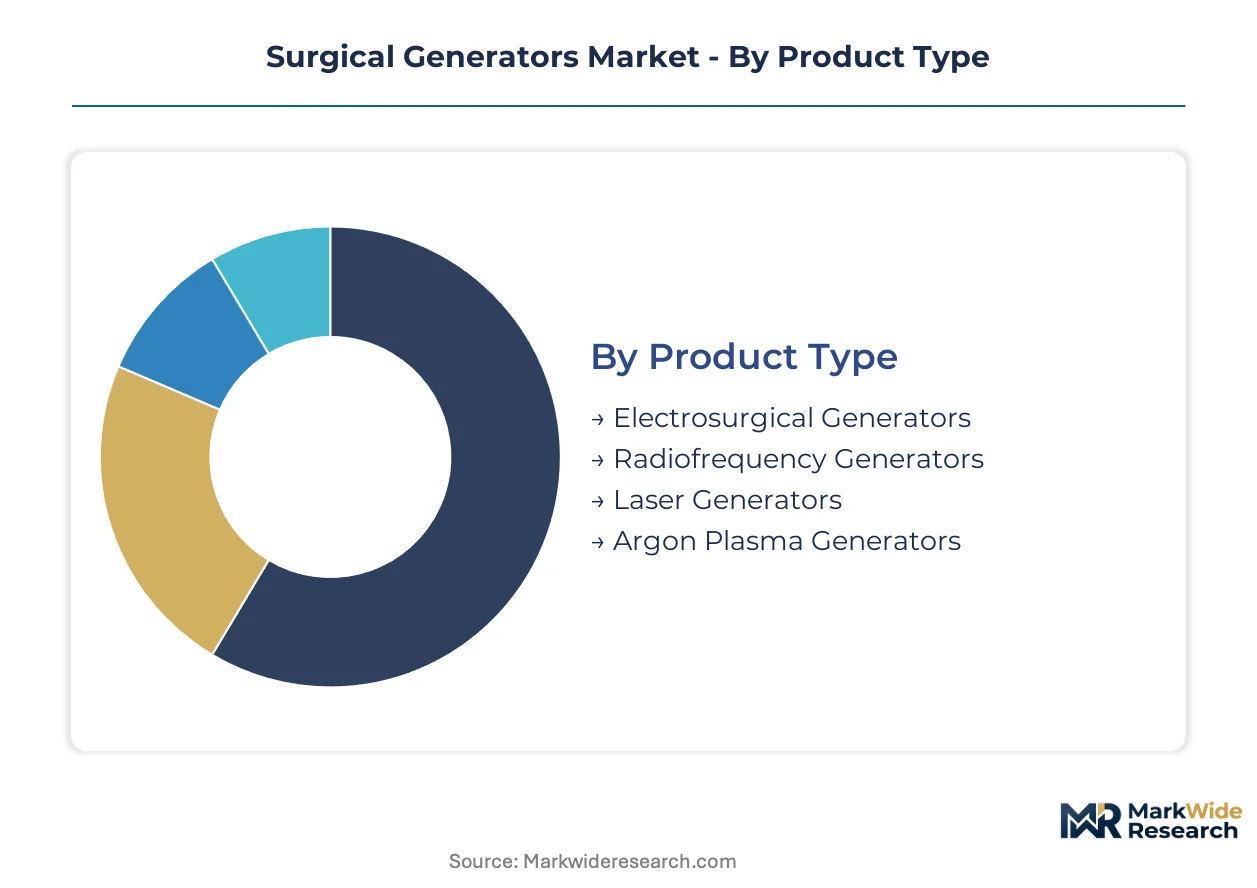
Surgical generator purchasing decisions hinge on procedure-specific energy requirements and capital refresh cycles. Hospital procurement teams segment investments by platform compatibility, consumable lock-in potential, and regulatory pre-certification status.
Product Type:
Upgrade cycles concentrate where legacy monopolar platforms face replacement pressure from sealed vessel technologies with lower thermal spread profiles.
- Electrosurgical Generators:High-frequency power electronics operating between 300 kHz and 3 MHz deliver cutting and coagulation through monopolar or bipolar electrode configurations. Demand clusters in German university hospitals and US integrated delivery networks phasing out decade-old installed bases ahead of EU MDR technical documentation deadlines.
- Radiofrequency Generators:Tissue ablation systems deploy precisely controlled thermal energy for orthopedic interventions and pain management procedures. Japanese orthopedic surgery centers in Osaka and Tokyo metropolitan areas drive procurement as reimbursement eligibility tightens around demonstrable tissue precision outcomes.
- Laser Generators:Coherent light emission systems target specialized urological and ophthalmic applications requiring micron-level cutting accuracy.
- Argon Plasma Generators:Non-contact coagulation platforms deploy ionized argon gas for diffuse bleeding control in hepatic and splenic surgeries.
Electrosurgical generators sit at the top of the volume ranking, with radiofrequency generators climbing the fastest.
Application:
Procedure reimbursement rates and operative volume trajectories determine capital allocation priority across surgical service lines.
- General Surgery:Open and laparoscopic abdominal procedures consume the broadest generator utilization hours across hospital operating rooms. Baden-Wuerttemberg purchasing cooperatives standardize on integrated energy platforms spanning cholecystectomy, colectomy, and hernia repair workflows.
- Gynecology:Hysteroscopic and laparoscopic interventions require precise thermal control to preserve fertility-critical structures. Mumbai and Delhi tertiary hospitals expand minimally invasive gynecological surgery capacity under CDSCO fast-track registration pathways for Class B electrosurgical devices.
- Urology:Transurethral resection and laser lithotripsy procedures demand specialized generator-electrode compatibility.
- Orthopedic Surgery:Radiofrequency ablation for chronic pain and soft tissue procedures drives compact generator demand in ambulatory settings.
General surgery captures the largest installed base, while gynecology applications expand most quickly in metropolitan hospital clusters.
End User:
Capital availability and procedure complexity stratify purchasing authority across facility types with divergent equipment financing mechanisms.
- Hospitals:Multi-specialty academic centers and community hospitals deploy high-throughput generator platforms across 10-plus operating rooms. Bavarian hospital networks consolidate vendor relationships around pre-validated EU MDR technical documentation packages.
- Surgical Centers:Freestanding ambulatory surgery centers prioritize portable RF units with disposable electrode configurations to minimize capital deployment. US ASC networks in Texas and Florida drive demand for compact units with simplified sterilization protocols.
- Clinics:Office-based procedural clinics select lower-wattage generators for dermatological and minor surgical applications.
- Academic Institutions:Teaching hospitals balance clinical throughput against resident training requirements for multiple energy modalities.
Hospitals dominate capital deployment volume, with surgical centers gaining share fastest among outpatient migration trends.
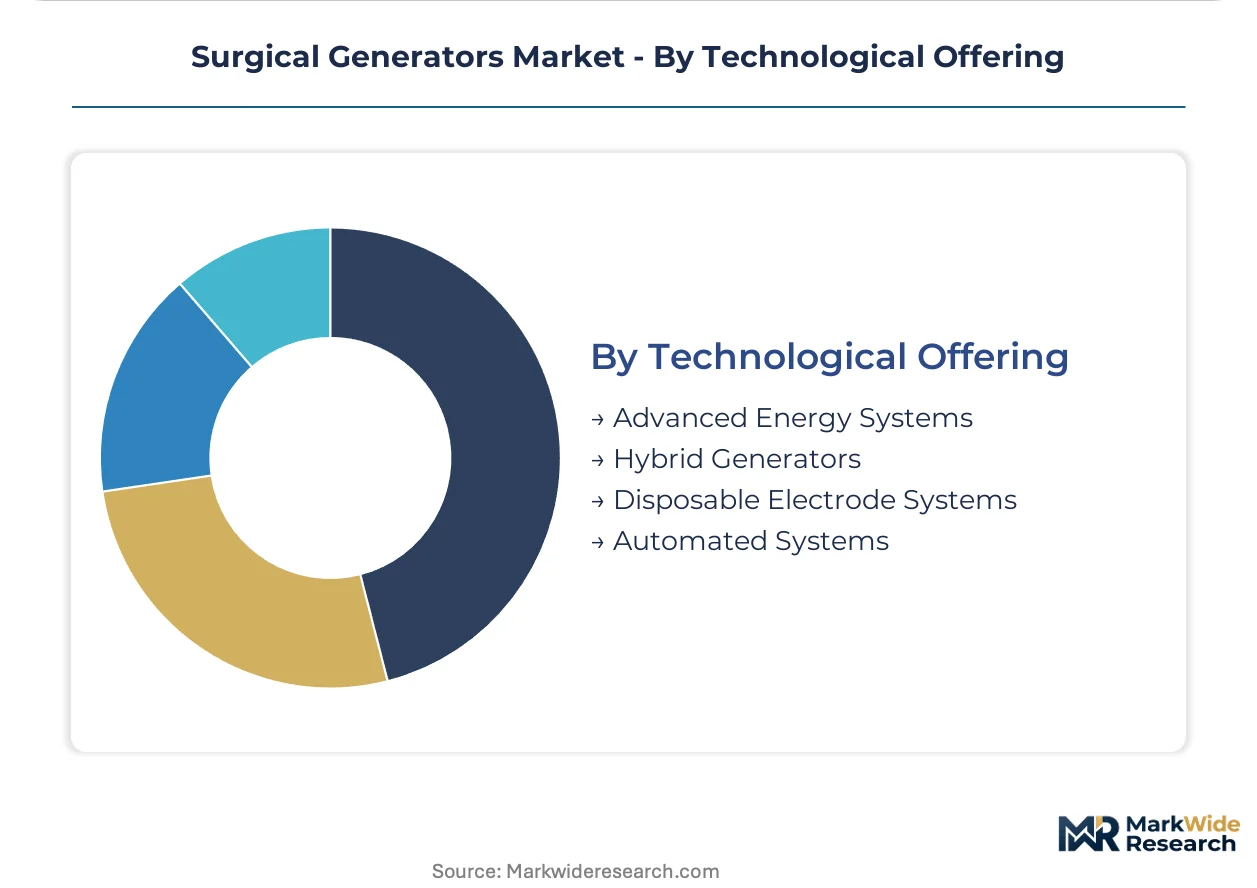
Technological Offering:
Margin structure and consumable revenue attach rates differentiate competitive positioning across technology tiers.
- Advanced Energy Systems:Intelligent impedance-sensing platforms with tissue feedback algorithms automate power modulation during vessel sealing. German and Japanese academic medical centers pilot predictive coagulation models for hepatic resections.
- Hybrid Generators:Multi-modality platforms integrate monopolar, bipolar, and advanced bipolar outputs within single console architectures. Olympus Corporation extends visualization-integrated systems into hybrid surgical workflows combining electrosurgical and ultrasonic energy.
- Disposable Electrode Systems:Single-use instrument configurations reduce cross-contamination risk and sterilization logistics burden.
- Automated Systems:Machine learning firmware enables autonomous endpoint detection for standardized tissue effects.
Advanced energy systems command the highest revenue per unit placement, with automated systems showing the steepest expansion trajectory among AI-integrated surgical platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered electrosurgical generator manufacturing through Tuebingen-centered engineering clusters that established high-frequency power electronics standards adopted across European hospital systems. The industry's technical lineage traces through German precision instrumentation traditions before radiating into North American and Asia-Pacific markets.
United States
FDA 510(k) clearance pathways for predicate device modifications accelerate commercial launches for established regulatory affairs teams. Hospital procurement consolidation across integrated delivery networks concentrates demand in Texas and Florida ASC clusters. Freestanding ambulatory surgery centers in these states drive compact RF unit adoption with disposable electrode configurations.
Germany
Baden-Wuerttemberg and Bavarian purchasing cooperatives standardize procurement around integrated energy platforms with pre-validated EU MDR technical documentation. The EU MDR recertification timeline compresses supplier qualification windows for mid-scale competitors. Tuebingen anchors specialized electrosurgical R&D intensity with university medical center pilot programs for intelligent impedance-sensing systems.
Japan
METI-supported medical device innovation programs accelerate predictive coagulation model development in academic medical centers. Osaka and Tokyo metropolitan orthopedic surgery centers tighten reimbursement eligibility around demonstrable tissue precision outcomes. Kanto region teaching hospitals balance clinical throughput against resident training requirements for multiple energy modalities.
India
CDSCO fast-track registration for Class B electrosurgical devices opens procurement channels in Delhi and Mumbai tertiary hospitals. Surgical volume growth in these metropolitan clusters outpaces equipment availability for minimally invasive gynecological procedures. Maharashtra and Gujarat hospital networks expand laparoscopic capacity under streamlined regulatory pathways.
China
NMPA registration requirements add compliance layers that favor multinationals with dedicated regulatory affairs infrastructure. Yangtze River Delta hospital procurement departments consolidate vendor relationships around platforms with established notified body partnerships. Shanghai and Suzhou medical centers phase out legacy monopolar platforms during capital refresh cycles.
Surgical Generators Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with vertically integrated energy platforms. Consolidation pressures squeeze mid-scale manufacturers lacking dedicated EU MDR compliance teams and established notified body partnerships. Three archetypes dominate: integrated energy platform operators, visualization-integrated system specialists, and precision electrosurgical R&D-focused engineering houses. M&A activity concentrates on regulatory infrastructure acquisition, while portfolio diversification moves target hybrid generator architectures spanning monopolar, bipolar, and advanced bipolar outputs.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson Services, Inc. represent integrated platform operators with compliance economies that mid-scale competitors cannot replicate. Erbe Elektromedizin GmbH exemplifies the specialized electrosurgical engineering archetype through its Tuebingen-centered R&D intensity. Olympus Corporation occupies a position within the visualization-integrated tier, extending generator systems into hybrid surgical workflows. Stryker and Boston Scientific Corporation sit within the interventional technology segment with regulatory infrastructure spanning transatlantic markets. B. Braun Melsungen AG anchors the German precision instrumentation tradition with established European technical documentation resources.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CONMED Corporation |
| Johnson & Johnson Services, Inc. |
| B. Braun Melsungen AG |
| Erbe Elektromedizin GmbH |
| Stryker |
| Boston Scientific Corporation |
| KARL STORZ GmbH |
| Others |
Value Network & Pricing Analysis
Hospital procurement unbundling of capital equipment from long-term service agreements is forcing generator manufacturers to compete on transparent lifecycle cost models, compressing margins for suppliers lacking established preventive maintenance networks in consolidated German purchasing cooperatives.
Pricing Analysis
Bundled-vs-unbundled service splits now define competitive positioning as Baden-Wuerttemberg purchasing cooperatives separate device acquisition from preventive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification status and vessel-sealing algorithm sophistication. Cost compression in mid-tier electrosurgical platforms is intensifying because semiconductor input volatility feeds through to RF amplifier module costs. Freestanding US ambulatory surgery centers exhibit highest price sensitivity, while Japanese academic medical centers prioritize predictive coagulation capabilities over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries for high-purity copper and RF switching components that power electrosurgical generator architectures. Manufacturing concentration in Taiwan, South Korea, and Japan feeds into power electronics assembly for global OEMs. Raw material dependencies span high-purity copper, gallium nitride semiconductors, and medical-grade aluminum housings. Tariff exposure on semiconductor imports from East Asia threatens margin stability for mid-scale manufacturers. Distribution runs through hospital GPO contracts and specialized medical device distributors with sterile field expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU MDR recertification deadlines compress supplier qualification windows around platforms with pre-validated technical documentation and established notified body partnerships.
For Market Incumbents: Anticipate margin erosion from plasma-based vessel sealers displacing monopolar generator replacement demand in general surgery applications. Deepen backward integration into RF amplifier module production to offset East Asian semiconductor supply volatility. Prioritize certification investment for EU MDR Annex XIV post-market surveillance extensions to maintain Baden-Wuerttemberg purchasing cooperative eligibility.
For New Entrants and Emerging Players: Begin with CDSCO fast-track registration pathways for Class B electrosurgical devices targeting Delhi and Mumbai tertiary hospital clusters where surgical volume growth outpaces equipment availability. India's minimally invasive gynecological surgery expansion offers the most penetrable segment. Pursue hospital system partnership models bundling compact RF units with disposable electrode configurations to minimize capital deployment friction.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized electrosurgical R&D-focused engineering houses possessing Tuebingen-centered technical documentation resources and established notified body partnerships. Long-term viability hinges on regulatory infrastructure moats widening as EU MDR compliance costs escalate. Target acquisition archetype: mid-scale manufacturers with captive impedance-sensing algorithm IP and European QMS extensions. Watch for AI-powered tissue recognition integration velocity as inflection indicator for platform differentiation sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Pre-validated packages secure Baden-Wuerttemberg purchasing cooperative eligibility against compressed qualification windows. |
| AI-Powered Tissue Recognition Integration | Machine learning firmware for autonomous coagulation endpoint detection differentiates premium platforms in Japanese academic medical centers. |
| India CDSCO Fast-Track Registration | Streamlined Class B pathways open procurement channels in Delhi and Mumbai metropolitan clusters with equipment shortages. |
| Disposable Electrode System Development | Single-use configurations reduce sterilization logistics burden for US freestanding ambulatory surgery center penetration. |
| Impedance-Sensing Algorithm Patent Expansion | Predictive coagulation model IP protects margin structure in advanced energy systems commanding premium positioning. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned German university medical centers, US integrated delivery networks, and Japanese orthopedic surgery centers. Secondary sources included CMS Medicare reimbursement data, CDSCO registration filings, and METI-supported medical device innovation program disclosures.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed product type, application, end user, and technological offering tiers alongside regional regulatory cluster differentiation. CAGRs were derived from installed base refresh cycle analysis and procedure volume trajectories. Industry-specific forecast inputs incorporated EU MDR recertification timeline compression and semiconductor supply concentration effects on manufacturing cost structures.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement shifts, geopolitical disruptions to East Asian semiconductor supply chains, and radical surgical modality substitutions beyond plasma-based vessel sealing. Forecasts reflect documented assumptions regarding hospital consolidation velocity and reimbursement eligibility tightening patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Cell Washer Market