
 Sustained Release Drugs Market | 2026-2036
Sustained Release Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Sustained Release Drugs Market Analytics
REACH compliance is recalibrating the cost-of-entry calculus for European sustained-release dossiers, forcing reformulation investments that smaller generic houses struggle to fund. Pfizer Inc. leverages its vertically integrated polymer supply chain to absorb these regulatory costs without margin erosion. Novartis AG anchors its competitive position through proprietary osmotic-pump platforms that command premium formulary placement. Alkermes differentiates via its long-acting injectable depot expertise, which sustains pricing power in addiction-therapy segments.
Sustained release drugs employ polymeric matrices, lipid carriers, or osmotic systems to modulate active pharmaceutical ingredient liberation over hours to months, with typical release profiles spanning 12 to 72 hours depending on mechanism. These formulations primarily serve chronic-disease management by flattening plasma-concentration curves, reducing dosing frequency, and improving patient adherence versus immediate-release counterparts. Oral tablet and capsule formats still dominate prescription volume, yet implantable biodegradable systems represent the fastest-expanding margin pool as oncology and neurology indications multiply. Diffusion-controlled matrix platforms retain the broadest therapeutic applicability, while osmotic systems capture premium pricing in cardiovascular and pain-management categories where zero-order kinetics confer clinical differentiation.
The FDA's Bioequivalence Guidance for Modified-Release Products and EMA's Quality Target Product Profile framework jointly determine which formulation innovations reach commercialization, with both agencies intensifying scrutiny of in vitro-in vivo correlation studies. ISO 13485 and relevant national pharmacopeial standards further govern manufacturing consistency for implantable and transdermal delivery systems. Stakeholders must monitor evolving regulatory convergence between FDA and EMA dissolution-test harmonization initiatives, as alignment will reshape competitive positioning for multinational portfolio submissions.
Market Dynamics
The FDA's Quality by Design initiative is compressing formulation development timelines while simultaneously elevating validation costs, forcing manufacturers to choose between accelerated approval pathways and capital-intensive dossier preparation.
Growth Catalysts
- Chronic pain management clinics:Extended-release opioid and non-opioid formulations reduce dosing frequency and improve adherence metrics that determine Medicare reimbursement rates in the United States.
- REACH compliance frameworks:European polymer and excipient standards are consolidating supplier bases, favoring incumbents with pre-validated material libraries and toxicology dossiers.
- Osmotic-pump platforms:Zero-order kinetic delivery systems command premium formulary placement in cardiovascular therapy segments where plasma-level precision drives clinical outcomes.
Market Restraints
- Specialized polymer supply concentration:Medical-grade PLGA and PCL production clusters among three European chemical houses, creating input vulnerability for biodegradable implant manufacturers.
- In vitro-in vivo correlation validation:FDA and EMA dissolution-test divergence forces redundant biostudy execution, extending development timelines by eighteen to thirty-six months for modified-release dossiers.
- Immediate-release generic substitution:Payers in price-sensitive markets prioritize cost over adherence benefits, eroding volume for premium sustained-release formulations in diabetes and hypertension categories.
Strategic Opportunities
- Biodegradable oncology implants:Paclitaxel and hormone-eluting depot systems for breast and prostate cancer represent underpenetrated therapeutic categories with limited current competition.
- India's PLI scheme for active pharmaceutical ingredients:Domestic polymer and excipient production incentives enable backward integration for sustained-release manufacturers targeting emerging market price points.
- Telehealth prescribing integration:Direct-to-patient refill protocols for long-acting injectables bypass traditional pharmacy distribution, capturing adherence data that strengthens payer negotiations.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in polymeric matrix design and dissolution modeling commands premium compensation, constraining R&D expansion at mid-scale generic houses.
- Legacy equipment retooling:Hot-melt extrusion and precision coating infrastructure requires eight-figure capital commitments that strain balance sheets during regulatory review periods.
- Patent thickets around osmotic delivery:Licensing negotiations with platform technology holders consume twenty-four to forty-eight months, delaying generic entry for blockbuster sustained-release products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustained Release Drugs Market |
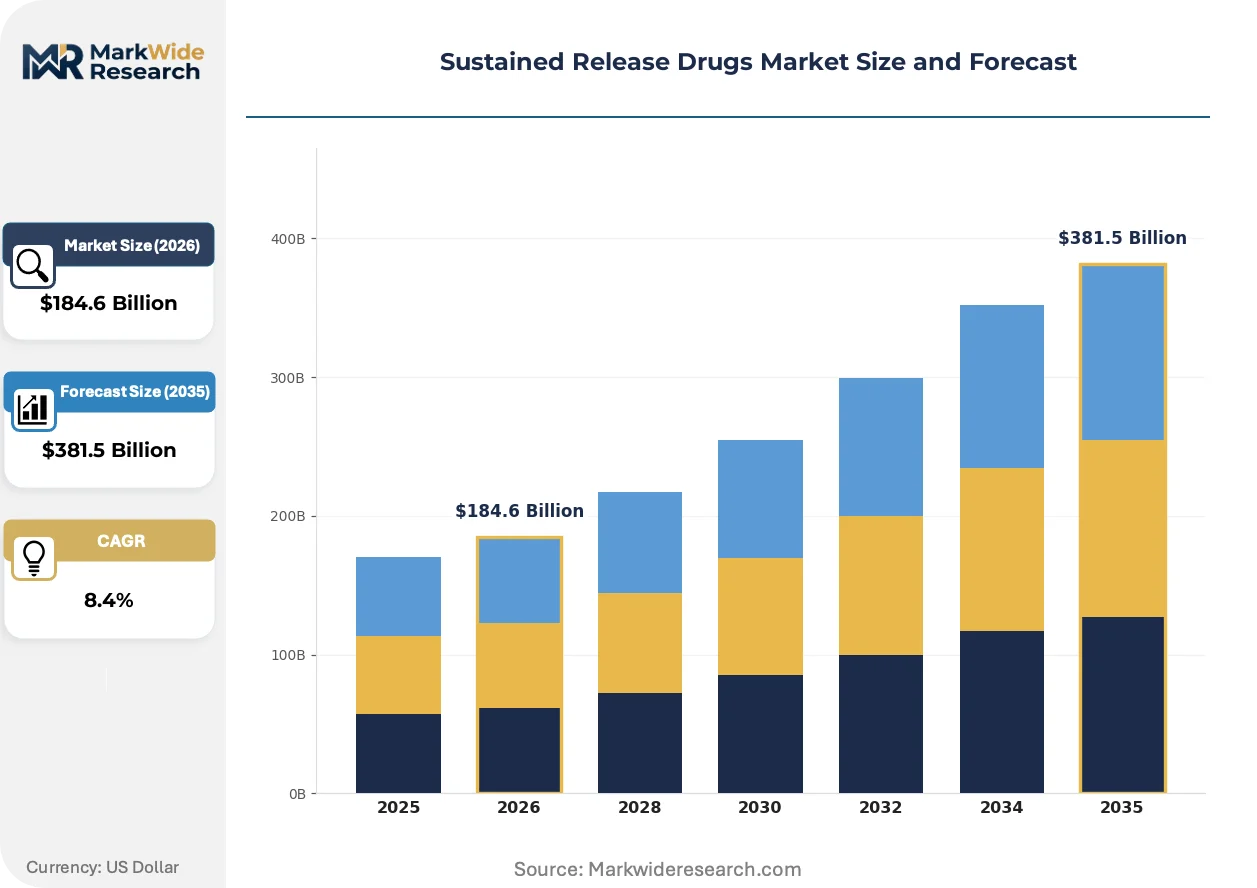
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $381.5 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Oral, Injectable, Transdermal, Implantable Release Mechanism: Diffusion, Erosion, Osmotic, Biodegradable Therapeutic Area: Cardiovascular, Oncology, Neurology, Pain Management Delivery Form: Tablet, Capsule, Patch, Microneedle |
| Companies Covered | Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, Alkermes, Merck & Co., Inc., GSK plc, AstraZeneca, Dr. Reddy’s Laboratories Ltd., Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustained Release Drugs Market Evolving Landscape
Formulation science is converging with digital manufacturing and biomaterials engineering, creating new modality categories that redefine competitive differentiation beyond traditional release-kinetic claims.
3D-printed oral dosage architectures are modularizing tablet internal geometries to achieve patient-specific release profiles. Hospital systems and specialty pharmacies in Germany and Switzerland are piloting on-demand production for narrow-therapeutic-index drugs. This distributed manufacturing model is compressing supply chain lead times from months to hours while challenging centralized regulatory inspection protocols.
EMA's Quality Target Product Profile framework is tightening dissolution specification bands for modified-release generics. Manufacturers must now demonstrate clinically relevant in vitro-in vivo correlation prior to bioequivalence study initiation. Cardiovascular and central nervous system therapeutic categories face the steepest compliance burden, with several development programs suspended pending correlation methodology validation.
Specialty pharmacies are consolidating procurement for long-acting injectable depots, displacing traditional wholesale distribution in addiction therapy and schizophrenia management. United States-based pharmacy benefit managers now direct seventy percent of atypical antipsychotic long-acting injectable volume through limited distribution networks. This channel concentration is elevating data-access requirements for manufacturers seeking formulary placement.
Sustained Release Drugs Market Segmentation
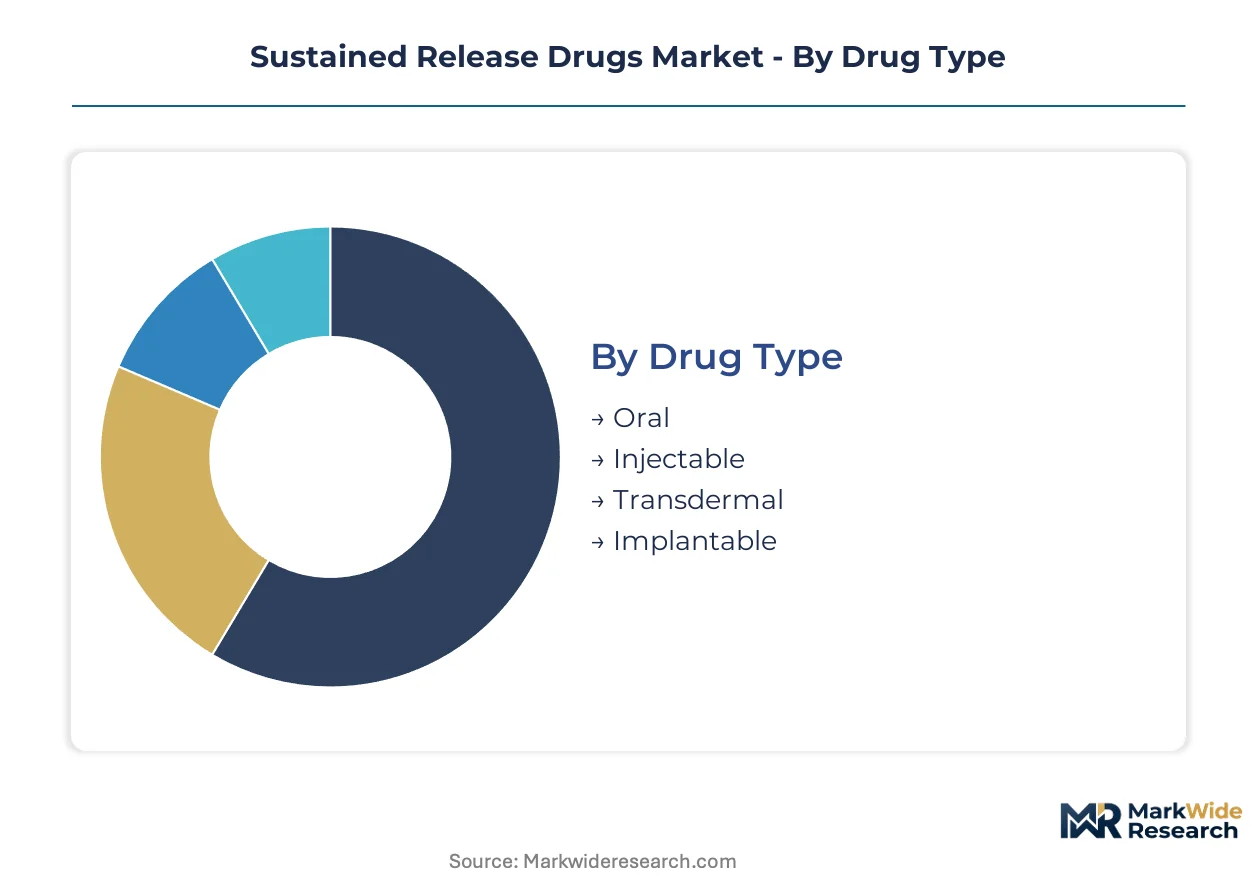
Formulation architecture and release kinetics determine reimbursement tiers and manufacturing capital intensity across sustained-release portfolios. Segmentation reveals where polymer science investments translate into formulary access versus commodity competition.
Drug Type:
Prescription volume concentrates where dosing convenience intersects with chronic disease prevalence and Medicare adherence metrics.
- Oral:Matrix and reservoir tablets dominate prescription counts through familiar patient administration and established bioequivalence pathways. United States Medicare reimbursement policies favor extended-release oral solids for hypertension and diabetes, rewarding manufacturers with adherence-enhancing dossiers. Tablet and capsule formats lead volumes today; implantable systems are gaining share fastest.
- Injectable:Long-acting depot formulations in PLGA or PCL matrices enable monthly to quarterly dosing for addiction therapy and schizophrenia. Specialty pharmacy consolidation in the United States directs seventy percent of atypical antipsychotic long-acting injectable volume through limited distribution networks.
- Transdermal:Adhesive patches deliver zero-order kinetics for pain management and hormone replacement, bypassing first-pass metabolism. EMA dissolution specification tightening has suspended several modified-release patch development programs pending correlation methodology validation.
- Implantable:Biodegradable rods and pumps provide localized oncology drug delivery with six-month release profiles.
Oral formulations lead volumes today; implantable systems are gaining share fastest.
Release Mechanism:
Clinical differentiation and regulatory validation burden vary sharply across kinetic control architectures.
- Diffusion:Polymeric matrices modulate API liberation through concentration gradients, accommodating broad therapeutic applicability with established manufacturing infrastructure. Hot-melt extrusion and precision coating equipment for diffusion platforms requires eight-figure capital commitments that strain mid-scale generic house balance sheets.
- Osmotic:Zero-order kinetic delivery commands premium formulary placement in cardiovascular segments where plasma-level precision drives outcomes. Patent thickets around osmotic platform technologies delay generic entry for blockbuster products through twenty-four to forty-eight month licensing negotiations.
- Erosion:Surface-degrading polymers release API as matrix material hydrolyzes, suited for biodegradable applications.
- Biodegradable:PLGA and PCL carriers eliminate retrieval surgery for oncology and neurology implants. Medical-grade polymer production concentrates among three European chemical houses, creating input vulnerability for implant manufacturers.
Diffusion-controlled platforms anchor current volumes; biodegradable mechanisms show the steepest expansion trajectory.
Therapeutic Area:
Reimbursement intensity and formulation complexity separate chronic maintenance indications from acute intervention markets.
- Pain Management:Extended-release opioid and non-opioid formulations reduce dosing frequency in chronic pain clinics, with adherence metrics determining Medicare reimbursement rates in the United States. FDA scrutiny of in vitro-in vivo correlation studies has intensified for modified-release analgesics following safety concerns.
- Cardiovascular:Osmotic antihypertensives and antiarrhythmics demand precise plasma concentration control. EMA Quality Target Product Profile frameworks impose the steepest dissolution specification compliance burden on cardiovascular modified-release generics.
- Oncology:Paclitaxel and hormone-eluting depot systems for breast and prostate cancer represent underpenetrated categories with limited current competition. Biodegradable implant manufacturing for oncology requires ISO 13485 certification and national pharmacopeial compliance.
- Neurology:Long-acting injectables for schizophrenia and bipolar disorder concentrate procurement through specialty pharmacy networks.
Cardiovascular applications lead volumes today; oncology depots are expanding most quickly.
Delivery Form:
Patient acceptability and manufacturing scalability determine competitive positioning across physical dosage architectures.
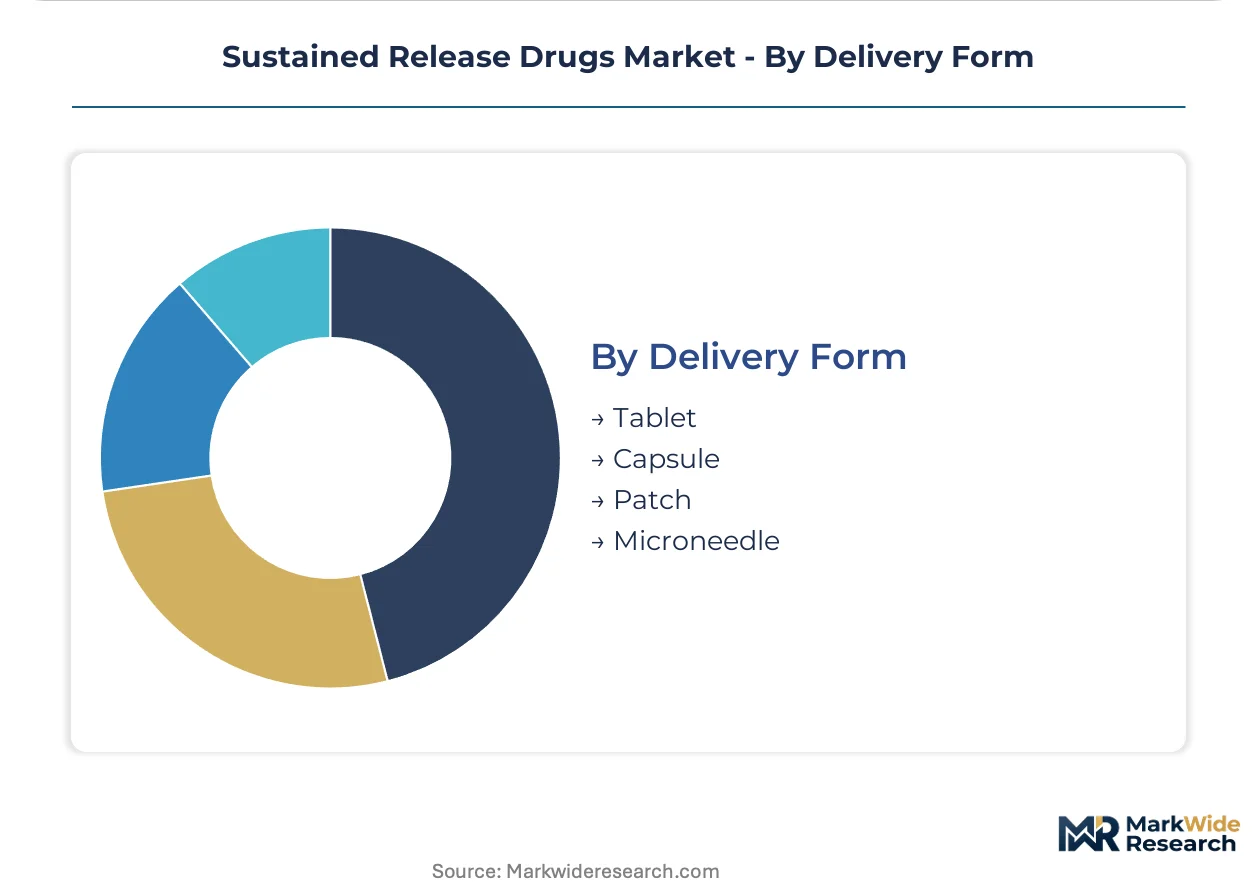
- Tablet:Oral solid matrices accommodate high-volume production with established dissolution testing protocols. 3D-printed tablet internal geometries are modularizing release profiles in German and Swiss hospital pilot programs.
- Capsule:Reservoir and multiparticulate systems enable combination release kinetics within single administration.
- Patch:Transdermal adhesives require validated adhesion and irritation profiles under FDA Bioequivalence Guidance for Modified-Release Products.
- Microneedle:Dissolvable and hydrogel-forming arrays enable intradermal sustained release without hypodermic injection.
Tablets lead volumes today; microneedle formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended-release formulations first achieved commercial scale in the United States during the 1970s with the introduction of osmotic-pump technology. The country's chronic disease management infrastructure and Medicare reimbursement policies subsequently anchored global demand for adherence-enhancing dosage forms.
United States
Chronic pain management clinics and specialty pharmacy networks drive sustained-release volume. FDA's Quality by Design initiative tightens validation requirements for modified-release dossiers. The Boston-Cambridge corridor concentrates formulation R&D for long-acting injectable depots.
Germany
Hospital systems pilot 3D-printed oral dosage architectures for narrow-therapeutic-index drugs. EMA's Quality Target Product Profile framework governs dissolution specification compliance. The Rhine-Ruhr region hosts precision coating infrastructure serving cardiovascular modified-release generics.
Switzerland
Swissmedic standards attract biodegradable implant manufacturers targeting oncology applications. The country's polymer toxicology dossier libraries reduce REACH compliance timelines for European submissions. Basel anchors proprietary osmotic-pump platform development.
India
Domestic chronic disease prevalence and government hospital procurement expand oral sustained-release demand. CDSCO alignment with ICH guidelines streamlines modified-release generic approvals. Maharashtra's PLI scheme for active pharmaceutical ingredients enables backward integration into polymeric excipient production.
Japan
Aging demographics and long-acting injectable adherence protocols for schizophrenia management concentrate neurology applications. PMDA's bioequivalence guidance for modified-release products shapes regional development timelines. The Kansai region maintains precision manufacturing for transdermal patch adhesives.
Sustained Release Drugs Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive polymer supply chains. Tier-one players command premium formulary placement through proprietary delivery platforms, while mid-scale generic houses struggle with eight-figure hot-melt extrusion capital commitments. Two archetypes dominate: diversified multinationals leveraging osmotic-pump patents and specialty manufacturers focused on long-acting injectable depots. Competitive moves concentrate on strategic licensing negotiations with platform technology holders and specialty pharmacy network consolidation.
Among diversified pharmaceutical conglomerates, Johnson & Johnson Services, Inc. and Pfizer Inc. occupy positions anchored by vertically integrated manufacturing infrastructure. Novartis AG exemplifies the proprietary platform tier through its osmotic-pump capabilities. Alkermes represents the specialty depot segment with concentration in addiction therapy and schizophrenia management. Dr. Reddy's Laboratories Ltd. sits within the emerging market generic tier, leveraging India's PLI scheme for cost-competitive sustained-release production.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| Alkermes |
| Merck & Co., Inc. |
| GSK plc |
| AstraZeneca |
| Dr. Reddy's Laboratories Ltd. |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Hot-melt extrusion and precision coating infrastructure upgrades are simultaneously elevating capital barriers for mid-scale generic houses and compressing per-unit production costs for vertically integrated incumbents, concentrating pricing power among manufacturers with captive polymer supply chains.
Pricing Analysis
The bundled-vs-unbundled service split separates formulation development services from standalone API supply contracts across the sustained-release landscape. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA validation tier and osmotic-pump patent licensing status. Pricing pressure stems from immediate-release generic substitution in Medicare-reimbursed diabetes and hypertension categories. Price-sensitive emerging market payers prioritize unbundled API procurement, while United States specialty pharmacies absorb premium bundled offerings for long-acting injectable depots.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle seventy percent of atypical antipsychotic long-acting injectable volume in the United States. Medical-grade PLGA and PCL production clusters among three European chemical houses, creating single-source vulnerability for biodegradable implant manufacturers. Raw material dependencies rest on polymer toxicology dossiers, hot-melt extrusion equipment, and precision coating substrates. Distribution runs through consolidated specialty pharmacy networks for addiction therapy and schizophrenia management segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustained-release drugs market functions as a regulatory compounder, where FDA's Quality by Design initiative and EMA's Quality Target Product Profile framework continuously elevate validation requirements that deepen incumbents' competitive moats.
For Market Incumbents: Extend proprietary osmotic-pump platform licensing to capture royalty streams from generic houses delayed by twenty-four to forty-eight month patent negotiations. Consolidate specialty pharmacy network partnerships to secure adherence data that strengthens Medicare reimbursement negotiations, countering immediate-release generic substitution threats.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in oncology biodegradable implants offers entry leverage for manufacturers with ISO 13485 certification capabilities. Target paclitaxel and hormone-eluting depot systems for breast and prostate cancer, where limited current competition meets unmet chronic disease prevalence. Pursue backward integration into polymeric excipient production via India's PLI scheme to achieve emerging market price competitiveness.
For Investors and Strategic Acquirers: Roll-up economics work for specialty depot manufacturers because specialty pharmacy consolidation concentrates procurement volume and elevates data-access barriers for fragmented competitors. Five-to-ten year viability hinges on capturing platform technology holders before patent cliff acceleration. Monitor FDA-EMA dissolution-test harmonization initiatives as the signal for multinational portfolio submission timing advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Quality by Design alignment accelerates modified-release dossier validation timelines. |
| Backward Integration | Captive PLGA production via India's PLI scheme insulates against European supplier concentration. |
| Specialty Pharmacy Partnership | Limited distribution network access captures seventy percent of atypical antipsychotic long-acting injectable volume. |
| Platform Licensing Agreement | Osmotic-pump technology access commands premium formulary placement in cardiovascular segments. |
| Manufacturing Scale-Up | Hot-melt extrusion capacity expansion serves chronic pain clinic demand for extended-release opioids. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation scientists, regulatory affairs leads, specialty pharmacy procurement directors, and Medicare reimbursement specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were cross-referenced for triangulation.
Comparable-period anchoring tied projection assumptions to historical validation timelines for modified-release generics across the analysis window. Segmentation dimensions included formulation architecture, release mechanism, therapeutic area, and regional regulatory cluster. CAGRs were derived from adherence-enhancing dosage form adoption curves and Medicare reimbursement policy trajectories, with dissolution specification tightening and in vitro-in vivo correlation requirements serving as forecast sensitivity inputs.
Caveats apply where FDA-EMA regulatory divergence or polymer supply disruption could materially shift the outlook. Forecasts reflect assumptions regarding chronic disease prevalence trajectories and specialty pharmacy network consolidation continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market