
 Patient Handling Equipment Market | 2026-2036
Patient Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Handling Equipment Market Analysis
Aluminum is broadening its replacement of steel in patient lift chassis and sling support frames, cutting unit weight by roughly one-third without sacrificing load ratings. Stryker Corporation leverages its integrated manufacturing footprint across North American and European plants to sustain margin control on powered stretcher systems. Baxter International anchors its position through deep specialization in acute-care transfer technologies, while Invacare Corporation competes aggressively in the home-care channel with battery-operated lift portfolios.
Patient handling equipment encompasses mechanical and electromechanical systems engineered to transfer, reposition, and support individuals with limited mobility, typically rated for load capacities between 150 kg and 450 kg and constructed from powder-coated steel or anodized aluminum with antimicrobial surface treatments. These devices serve the primary commercial purpose of reducing caregiver injury incidence while maintaining patient dignity during routine transfers. Hoists and powered lifts capture the dominant share of product-type revenue due to their indispensability in bariatric and critical-care workflows, while the home-care end-user segment exhibits the fastest structural expansion as aging-in-place policies shift reimbursement toward residential settings. Electric and battery-operated technologies command premium positioning over manual alternatives, reflecting both labor-cost arbitrage and the clinical preference for smooth, controlled transfer kinematics.
The FDA enforces 510(k) clearance pathways for powered patient handling devices, while the EU MDR imposes stricter clinical evidence requirements on hoist and sling manufacturers seeking CE marking. OSHA guidelines in the United States mandate safe patient handling programs for healthcare employers, directly institutionalizing equipment procurement budgets in hospital systems. Stakeholders must monitor how evolving ergonomic standards and reimbursement coding for preventive caregiver injury programs reshape capital allocation between acute and post-acute care settings.
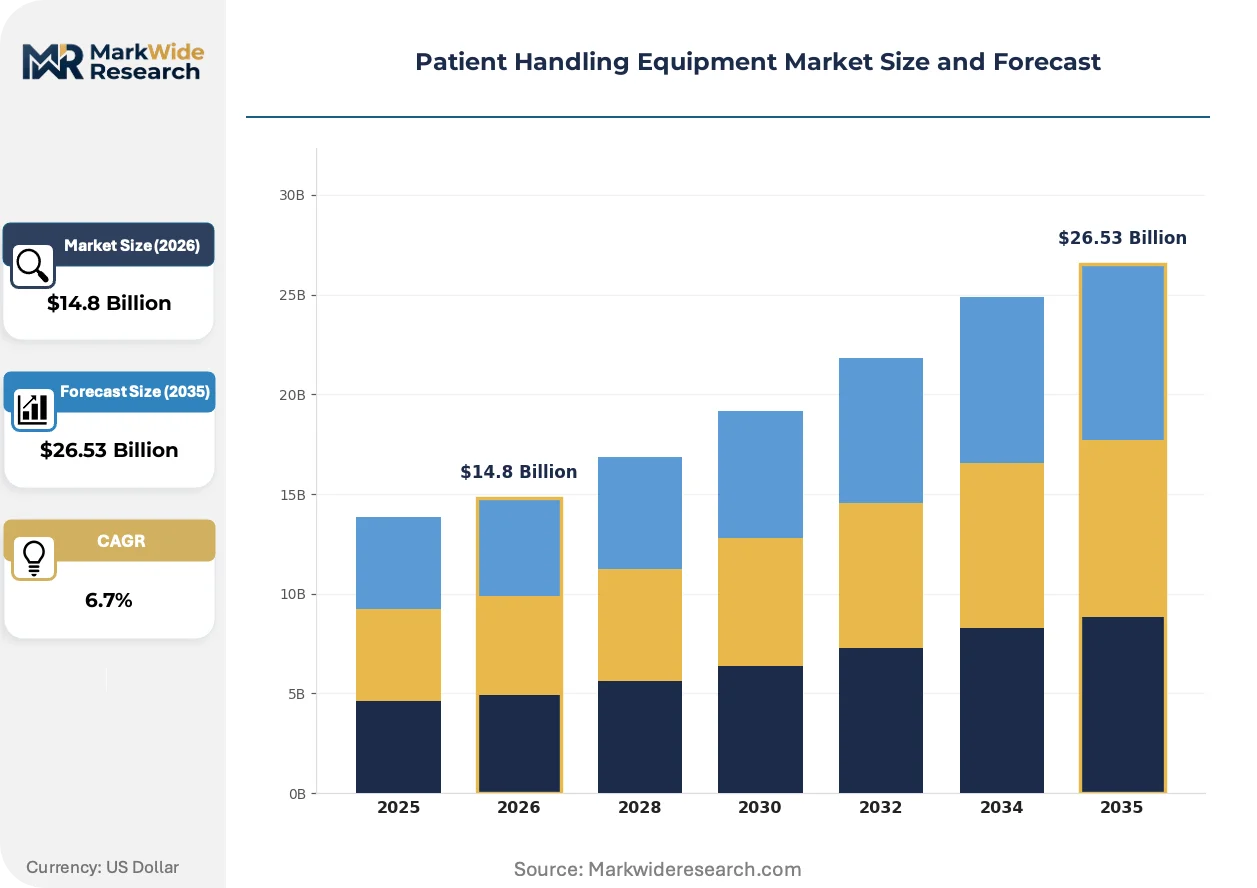
Market Dynamics
Powered lifting systems are displacing manual transfer devices as hospital systems confront caregiver injury liability and OSHA-mandated safe handling programs institutionalize capital budgets for electromechanical solutions.
Growth Catalysts
- Bariatric Patient Volumes:Rising obesity prevalence in the United States and Germany is forcing acute care facilities to procure hoists rated above 300 kg load capacity.
- EU MDR Compliance Deadlines:Stricter clinical evidence requirements for CE marking are accelerating replacement cycles for legacy sling and lift systems across European hospital networks.
- Battery Chemistry Advances:Lithium-ion power packs are extending operational runtime of portable patient lifts, enabling same-day discharge protocols in Japanese post-acute settings.
Market Restraints
- Aluminum Price Volatility:Surcharges on 6061-T6 alloy chassis material are compressing margins for hoist manufacturers dependent on lightweight frame construction.
- Supply Concentration in Southeast Asia:Motor drive assemblies and linear actuator components face single-source exposure from contract manufacturers in Vietnam and Thailand.
- Manual Lift Substitution:Low-cost hydraulic alternatives retain share in budget-constrained long-term care facilities, particularly in Southern and Eastern European markets.
Strategic Opportunities
- Home-Care Channel Expansion:Germany's Pflegeversicherung reimbursement reforms are redirecting procurement toward residential ceiling lift installations.
- AI-Enabled Load Sensing:Integration of pressure-mapping sensors with predictive sling positioning algorithms is creating premium positioning in critical care workflows.
- Telehealth-Linked Remote Monitoring:Cellular connectivity modules embedded in powered stretchers enable real-time location tracking and maintenance alerts for hospital fleet managers.
Industry Challenges
- Biomedical Technician Shortage:Hospitals in the United States lack sufficient trained staff to maintain electromechanical lift fleets, extending equipment downtime and forcing reliance on OEM service contracts.
- 510(k) Clearance Timelines:FDA review backlogs for novel patient transfer devices are delaying product launches by 8-14 months, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Handling Equipment Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slings, Hoists, Wheelchairs, Lifts End User: Hospitals, Nursing Homes, Rehabilitation Centers, Home Care Technology: Manual, Electric, Hydraulic, Battery-Operated Application: Patient Transfer, Mobility Assistance, Weight Support, Rehab Therapy |
| Companies Covered | Arjo, Stryker Corporation, Baxter International, Savaria Corporation, Invacare Corporation, Drive DeVilbiss Healthcare, Etac AB, GF Health Products, Joerns Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Handling Equipment Market Emerging Trajectories
Electromechanical architectures are converging with digital monitoring layers, transforming patient handling from isolated hardware into integrated care infrastructure that feeds operational data back to hospital logistics systems.
Smart sling systems equipped with RFID-tagged load cells and wireless weight transmission are unifying patient transfer with automated documentation. Acute care facilities in the United States and Germany are deploying these units at replacement-cycle velocity. The technology is unifying previously separate weighing, transfer, and electronic health record entry workflows into single-point-of-care interactions.
EU MDR clinical evidence requirements are forcing hoist manufacturers to conduct prospective safety studies for CE marking renewal. This regulatory burden is elevating compliance costs for mid-tier suppliers while creating certification moats for established players with dedicated clinical affairs teams. Sling manufacturers seeking renewed market access are responding by consolidating notified body relationships and pre-submission engagement strategies.
Acute care procurement committees are bundling lift fleet purchases with multi-year service and preventive maintenance agreements. Equipment distributors are ceding margin to capture recurring revenue streams, while hospital capital committees favor total-cost-of-ownership models over upfront acquisition pricing. This behavioral shift is most pronounced in United States health systems operating under value-based care contracts where equipment uptime directly affects quality metrics.
Patient Handling Equipment Market Segmentation
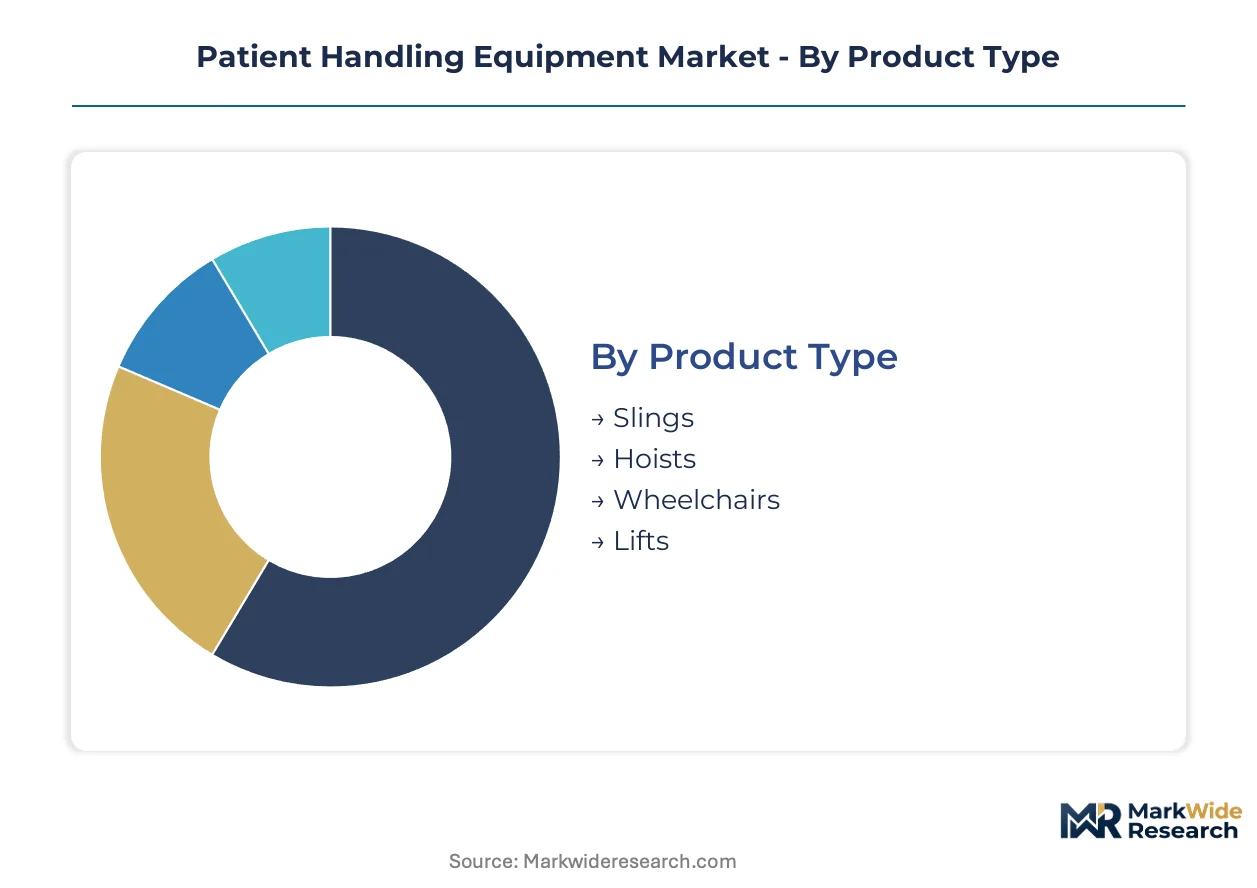
Segmentation in patient handling equipment reveals how procurement priorities diverge between acute care capital budgets and residential reimbursement flows. Equipment specifications, power architectures, and end-use settings each create distinct competitive arenas with separate margin profiles and replacement cadences.
Product Type:
Replacement cycles accelerate where caregiver injury liability intersects with bariatric load requirements, reshaping fleet composition across acute and post-acute networks.
- Slings:Fabricated from antimicrobial polyester mesh or solid vinyl with six-point or four-point attachment configurations rated for 200-450 kg. Demand concentrates in German and United States hospital systems where EU MDR and FDA 510(k) pathways force systematic inventory refresh. Washable RFID-tagged variants are displacing legacy unlabeled inventory to satisfy traceability mandates.
- Hoists:Ceiling-mounted and portable electromechanical systems with aluminum chassis construction dominate bariatric and critical-care workflows. Acute care facilities in the United States prioritize powered ceiling installations to satisfy OSHA safe handling program requirements, while Japanese post-acute settings favor portable units with lithium-ion power packs.
- Wheelchairs:Manual and powered mobility platforms with configurable seating systems serve institutional discharge planning and long-term residential use.
- Lifts:Floor-based and sit-to-stand configurations address specific transfer kinematics in nursing home and rehabilitation environments.
Volume placements concentrate in hoists; the faster expansion belongs to slings as regulatory traceability mandates force accelerated replacement.
End User:
Reimbursement coding reforms are redirecting procurement capital from institutional beds toward residential installations, fragmenting vendor go-to-market approaches.
- Hospitals:Acute care systems with centralized biomedical engineering departments and capital equipment committees. These buyers bundle fleet purchases with multi-year preventive maintenance agreements under total-cost-of-ownership evaluation frameworks.
- Nursing Homes:Budget-constrained long-term care facilities where manual hydraulic alternatives retain share against electromechanical upgrades, particularly in Southern and Eastern European markets.
- Rehabilitation Centers:Post-acute therapy settings where equipment uptime directly affects patient throughput metrics and value-based contract performance.
- Home Care:Residential settings where Germany's Pflegeversicherung reforms and United States aging-in-place policies are redirecting procurement toward ceiling lift installations and battery-operated portable systems.
Capital deployment tilts heaviest toward hospitals; home care is climbing the fastest as reimbursement structures favor residential alternatives.
Technology:
Power architecture selection tracks labor cost arbitrage and clinical preference for controlled transfer kinematics, with premium positioning commanding measurable price separation.
- Manual:Hydraulic and mechanical systems with hand-crank or foot-pump actuation retain installed base in budget-constrained segments where capital scarcity overrides ergonomic priorities.
- Electric:Mains-powered electromechanical systems with programmable lift paths and emergency lowering functions anchor acute care procurement in the United States and Germany.
- Hydraulic:Fluid-power alternatives without electrical dependency serve specific institutional niches where maintenance simplicity outweighs automation benefits.
- Battery-Operated:Lithium-ion and lead-acid portable systems with wireless charging docks are extending operational runtime and enabling same-day discharge protocols in Japanese post-acute settings and United States home care channels.
Unit economics favor electric installations in institutional settings; battery-operated configurations are gaining share fastest where portability determines purchase decisions.
Application:
Workflow integration requirements are unifying previously separate equipment categories into single-point-of-care interactions with automated documentation.
- Patient Transfer:Bed-to-chair and lateral repositioning operations represent the core functional requirement driving hoist and sling procurement volumes across all end-use settings.
- Mobility Assistance:Ambulation support and seated transport functions served by powered wheelchairs and gait trainers, with demand concentrated in rehabilitation center discharge planning.
- Weight Support:Bariatric load management and zero-gravity positioning for wound care and respiratory therapy, requiring 300-450 kg rated capacity systems.
- Rehab Therapy:Active and passive range-of-motion equipment with integrated data capture for outcome documentation in value-based reimbursement environments.
Procurement volume clusters around patient transfer; rehab therapy is expanding most quickly as outcome measurement requirements penetrate post-acute contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for patient handling equipment concentrates in economies with aging demographics and institutionalized safe handling mandates. The United States, Germany, and Japan absorb the dominant share of powered lift procurement. Hospital infrastructure investment and regulatory enforcement intensity determine regional growth velocity.
United States
OSHA-mandated safe patient handling programs institutionalize capital budgets for electromechanical solutions across acute care networks. The FDA enforces 510(k) clearance pathways for powered devices, extending review timelines and compressing product launch windows. Midwest health systems in Illinois and Michigan are consolidating lift fleet purchases under multi-year service agreements.
Germany
Pflegeversicherung reimbursement reforms redirect procurement toward residential ceiling lift installations and home-care battery systems. EU MDR clinical evidence requirements accelerate replacement cycles for legacy hoist and sling inventories. Industrial clusters in North Rhine-Westphalia and Bavaria host specialized notified body relationships and clinical affairs capabilities.
Japan
METI guidelines on caregiver injury prevention drive hospital adoption of powered transfer technologies. PMDA regulatory frameworks govern medical device market access with emphasis on electromechanical safety validation. Post-acute facilities in the Kanto region around Tokyo favor portable lithium-ion lifts to enable same-day discharge protocols.
United Kingdom
NHS capital allocation frameworks prioritize bariatric-rated equipment as obesity prevalence strains manual handling protocols. MHRA post-Brexit regulatory alignment maintains CE marking recognition while building independent conformity assessment capacity. Procurement committees in Greater Manchester and Birmingham health systems bundle fleet purchases with preventive maintenance contracts.
Canada
Health Canada medical device licensing requirements parallel FDA pathways for powered patient handling equipment. Provincial health authorities in Ontario and Quebec are standardizing safe handling program mandates across long-term care facilities. Vancouver and Toronto hospital networks are deploying smart sling systems with integrated weight transmission and electronic health record connectivity.
Patient Handling Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with acute care procurement favoring established OEMs while home-care channels tolerate private-label alternatives. The vendor base organizes around three archetypes: integrated healthcare conglomerates with diversified medical device portfolios, pure-play mobility specialists with concentrated sling and lift offerings, and regional fabricators serving price-sensitive institutional buyers. Consolidation activity clusters in hoist and stretcher categories where scale economies in regulatory compliance create defensive moats. Technology licensing partnerships are proliferating as battery and sensor suppliers seek embedded distribution through OEM channel relationships.
Among North American-based diversified healthcare manufacturers, Stryker Corporation and Baxter International occupy positions anchoring the premium acute-care tier with integrated manufacturing footprints and dedicated clinical affairs teams. Invacare Corporation exemplifies the mobility-specialist archetype, competing aggressively in residential and post-acute channels with battery-operated portable systems. European players including Arjo and Etac AB sit within the mid-tier specialist segment, leveraging EU MDR certification capabilities and regional service networks to defend positioning across German and Nordic hospital systems.
| Leading Market Players |
|---|
| Arjo |
| Stryker Corporation |
| Baxter International |
| Savaria Corporation |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Etac AB |
| GF Health Products |
| Joerns Healthcare |
| Others |
Supply Flow & Price Mechanics
Aluminum 6061-T6 alloy surcharges cascade through hoist chassis manufacturing into acute care procurement tiers, with lightweight frame specifications commanding premium positioning against powder-coated steel alternatives in bariatric-rated systems.
Pricing Analysis
Volume placements cluster in mid-tier electric installations while margins concentrate in premium battery-operated configurations with lithium-ion power packs and integrated load sensing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared powered systems with multi-year service bundling from manual hydraulic alternatives. Cost compression in economy-tier manual lifts is intensifying because low-cost Asian imports retain share in budget-constrained Southern European nursing homes. Long-term care facilities exhibit highest price sensitivity; United States health systems under value-based contracts demonstrate lowest sensitivity due to total-cost-of-ownership evaluation frameworks.
Supply Chain Analysis
Refurbishment flows for ceiling-mounted hoist motors and linear actuator assemblies create secondary supply channels that extend equipment lifecycle and compress new unit demand in mature European hospital networks. Motor drive components draw from contract manufacturing concentrations in Vietnam and Thailand, while aluminum extrusions and antimicrobial polyester sling fabrics source from Chinese and Indian textile processors. Single-source vulnerability in Southeast Asian electronics assembly exposes OEMs to logistics disruption. Distribution runs through specialized medical equipment distributors with biomedical technician service capabilities, particularly in United States and German acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with EU MDR clinical evidence requirements and FDA 510(k) backlogs forcing mid-tier suppliers toward exit or acquisition.
For Market Incumbents: Deploy multi-year preventive maintenance bundling to lock hospital capital committees into recurring revenue streams and raise switching costs against emerging competitors. Backward integration into aluminum chassis machining reduces exposure to 6061-T6 price volatility while accelerating response to bariatric load rating demands. Stryker Corporation and Baxter International already anchor this positioning through captive manufacturing footprints across North American and European plants. For New Entrants and Emerging Players: Enter via Germany's Pflegeversicherung reimbursement channel for residential ceiling lift installations, where regulatory complexity has kept incumbent pricing elevated and service coverage thin. Battery-operated portable systems for Japanese post-acute same-day discharge protocols represent the most penetrable application segment. Partner with regional home-care service networks rather than competing for institutional GPO contracts. For Investors and Strategic Acquirers: FDA 510(k) clearance backlogs extending product launch timelines is the leading indicator that regulatory affairs capabilities have become the scarcest competitive asset in this market. Targets with dedicated clinical teams and established notified body relationships command durable moats over the coming decade. Monitor EU MDR certificate renewal announcements for distressed mid-tier assets with compliant product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements are accelerating replacement cycles for legacy sling inventories across German hospital networks. |
| Hospital System Partnership | Multi-year fleet purchases with preventive maintenance agreements lock in recurring revenue under total-cost-of-ownership models. |
| Battery Chemistry Integration | Lithium-ion power pack partnerships extend portable lift runtime and enable same-day discharge protocols in Japanese post-acute settings. |
| Software Companion Development | AI-enabled load sensing with predictive sling positioning creates premium positioning in United States critical care workflows. |
| Reimbursement Strategy | Germany's Pflegeversicherung reforms redirect procurement capital toward residential ceiling lift installations and home-care channels. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare equipment reimbursement data underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home-care equipment distributors were validated against secondary sources including FDA 510(k) clearance databases, EU MDR notified body certificates, and OSHA safe patient handling program enforcement records. Bottom-up segmentation modeling triangulated against top-down macro healthcare expenditure trends.
Rate-of-change decomposition across product type, end user, technology, and application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from installed base replacement velocities, reimbursement coding shifts, and bariatric patient volume trajectories. Forecast inputs incorporated EU MDR compliance deadline clustering, lithium-ion battery cost curves, and aluminum alloy price volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended FDA review timelines or abrupt Pflegeversicherung reimbursement cuts. Practitioners should monitor EU MDR certificate suspension announcements and United States health system value-based contract penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market