
 Global Medical Copper Tubing Market | 2026-2036
Global Medical Copper Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Copper Tubing Market Intelligence
European specialty producers' capacity expansion is restructuring the supply base for high-purity tubing. Wieland-Werke AG leverages its metallurgical expertise to dominate the high-specification segment. Mueller Industries, Inc. competes on manufacturing scale and distribution reach in North America. The Lawton Tube Co. Ltd. specializes in coated and custom-sized tubes for niche medical applications.
Medical copper tubing is a seamless, high-purity product, typically 99.9% copper, specifically manufactured for healthcare applications. It undergoes a rigorous cleaning and capping process to ensure no internal contaminants compromise gas purity. Medical gas systems represent the dominant application, requiring long, continuous runs of tubing. Within product types, soft annealed forms offer the flexibility needed for complex installations, while hard drawn tubing provides structural rigidity for straight-line piping.
Product specifications are governed by a matrix of international and national standards. The U.S. FDA's purview extends to devices using the tubing, while the EU's Medical Device Regulation imposes strict traceability requirements. Standards like ISO 7396-1 and ASTM B819 define the material and installation criteria for medical gas pipelines. Future profitability hinges on manufacturers' ability to innovate with antimicrobial surfaces while navigating divergent regional certification pathways.
Market Dynamics
The central dynamic shaping this market is the tension between the global expansion of healthcare infrastructure and the non-negotiable, energy-intensive manufacturing processes required to meet stringent medical-grade purity standards like ASTM B819 for contaminant-free surfaces.
Growth Catalysts
- Hospital Infrastructure Expansion:Government-backed healthcare initiatives, particularly in China and India, are funding the construction of new hospitals and clinics, directly driving demand for extensive medical gas pipeline system installations.
- Medical Gas System Modernization:Aging healthcare facilities in developed economies are upgrading their medical gas systems to comply with updated safety and capacity standards, such as ISO 7396-1, requiring complete replacement of existing pipework.
- Adherence to Purity Standards:The global adoption of stringent cleanliness and material purity standards for medical devices creates a quality-driven demand floor, favoring specialized producers capable of meeting these specifications.
Market Restraints
- Raw Material Price Volatility:The market is directly exposed to fluctuations in the price of copper on the London Metal Exchange (LME), creating margin pressure and making long-term project cost estimation difficult for installers.
- Threat of Polymer Substitution:In certain non-critical, low-pressure medical gas applications, multilayer plastic tubing (PEX) presents a lower-cost alternative, though it cannot substitute copper for oxygen service due to fire safety regulations.
- Specialized Manufacturing Process:The rigorous cleaning, purging, and capping process required to achieve medical-grade internal surfaces is complex and capital-intensive, limiting the number of qualified manufacturers and creating supply bottlenecks.
Strategic Opportunities
- Antimicrobial Surfaces:Developing and marketing copper alloys with inherent antimicrobial properties offers a significant value-added opportunity to help healthcare facilities combat hospital-acquired infections (HAIs).
- Emerging Market Penetration:Targeting healthcare modernization projects in Southeast Asia and Latin America provides new growth avenues as these regions upgrade their medical infrastructure to higher international standards.
- High-Purity Niche Applications:Supplying tubing for specialized laboratory equipment, dental clinics, and veterinary hospitals represents a fragmented but high-margin opportunity outside the core hospital segment.
Industry Challenges
- Divergent Certification Pathways:Manufacturers face significant administrative and testing costs navigating different regional regulatory frameworks, such as the EU's Medical Device Regulation (MDR) versus the US FDA's requirements for medical devices.
- Skilled Labor Scarcity:A persistent shortage of certified technicians qualified to perform the specialized brazing and system verification for medical gas pipeline installations can delay project completion and increase labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Copper Tubing Market |
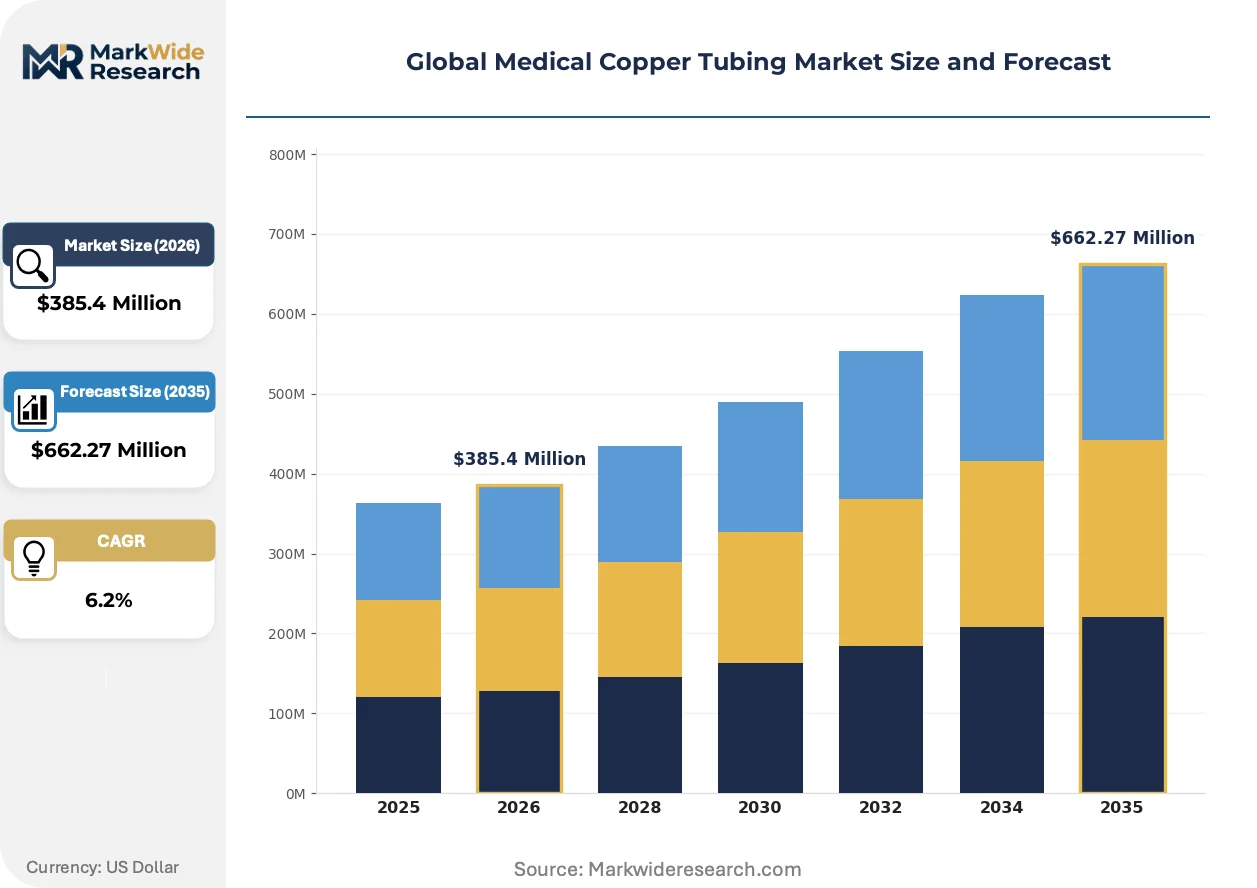
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Annealed Copper Tubing, Bare Copper Tubing, Coated Copper Tubing, Drawn Copper Tubing, Electronic Grade Tubing Application: Medical Gas Systems, Sterilization Equipment, Surgical Instruments, Laboratory Apparatus, Pharmaceutical Production End User: Hospitals, Medical Laboratories, Ambulatory Surgical Centers, Diagnostic Clinics, Research Institutions Form: Hard Drawn, Soft Annealed, Half Hard, Multi-Layered, Corrugated |
| Companies Covered | Mueller Industries, Inc., Wieland-Werke AG, KME Germany GmbH, Cerro Flow Products LLC, Cambridge-Lee Industries LLC, Great Lakes Copper Ltd., The Lawton Tube Co. Ltd., ABC Tube Company Pvt. Ltd., C&H Medical (Guangzhou) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Copper Tubing Market Strategic Shifts & Innovations
Product evolution is focused on enhancing material properties to improve patient safety, while regulatory shifts demand unprecedented levels of traceability. These forces are compelling manufacturers and installers to adopt more sophisticated production techniques and quality management systems to remain competitive.
Antimicrobial copper alloys are a key product innovation designed to actively kill pathogens on contact. Hospitals and specialized care facilities are adopting these materials for surfaces and components to supplement infection control protocols. This technology is integrating advanced material science directly into facility infrastructure, transforming passive tubing into an active component of a hospital's hygiene strategy.
The European Union's Medical Device Regulation (MDR) imposes strict lifecycle traceability requirements on all components used in medical systems. This regulation forces manufacturers to implement robust quality management systems and provide extensive documentation linking raw material to final installation. Tubing producers supplying the European market are most affected, now embedding unique identifiers to ensure compliance.
A notable behavioral shift is the move toward pre-fabricated medical gas system modules and headwall units. This disrupts the traditional model of installing and brazing individual tube lengths on-site, transferring value to off-site fabrication specialists. This trend is most prominent in large-scale hospital construction projects in North America and Western Europe, where reducing on-site labor time is a critical project management goal.
Global Medical Copper Tubing Market Segmentation
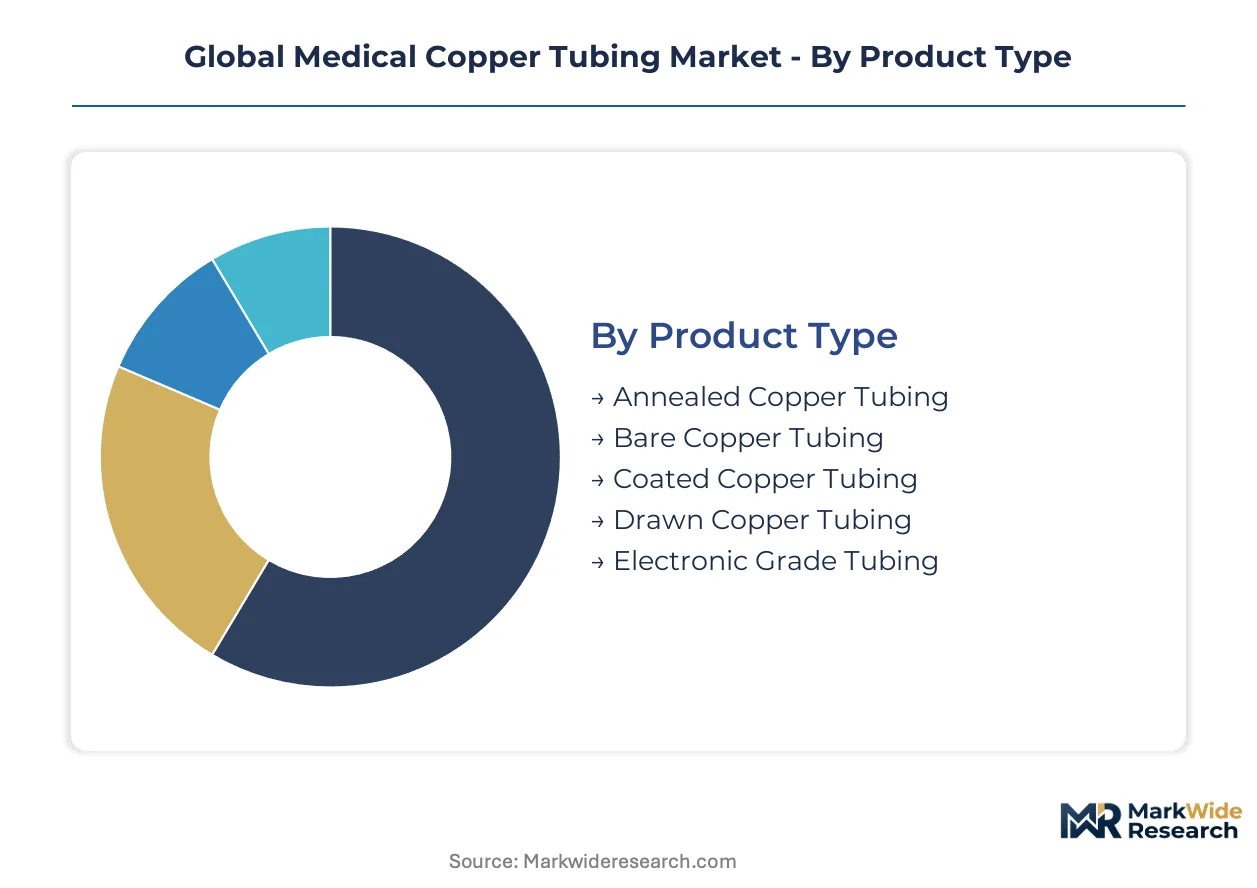
The Global Medical Copper Tubing Market differentiates across several critical dimensions, reflecting specialized material requirements and diverse healthcare applications. Understanding these segments provides clarity on demand drivers and manufacturing complexities within the medical gas and fluid delivery infrastructure.
Product Type:
The supply of medical copper tubing often concentrates among producers with specialized capabilities for specific product types, particularly those requiring advanced metallurgical processes.
- Annealed Copper Tubing:This product undergoes heat treatment for high flexibility, ideal for complex routing in medical gas systems. Demand is strong in new hospital construction across China and India.
- Drawn Copper Tubing:Characterized by structural rigidity, drawn tubing suits long, uninterrupted runs in hospital main lines. Its application is crucial in large-scale infrastructure upgrades in Germany.
- Bare Copper Tubing:This traditional form offers high purity without additional surface treatments.
- Coated Copper Tubing:An external polymer layer protects this tubing from corrosion and mechanical damage.
- Electronic Grade Tubing:Manufactured to tight tolerances and purity, this tubing serves sensitive laboratory and diagnostic equipment.
Today's leader: Annealed Copper Tubing. Tomorrow's challenger: Coated Copper Tubing.
Application:
The diverse applications of medical copper tubing reflect varying purity and pressure requirements, influencing the value captured across different end-use scenarios.
- Medical Gas Systems:This segment represents the largest application, distributing oxygen, medical air, and vacuum throughout healthcare facilities. Strict standards like ASTM B819 drive demand in hospital networks globally.
- Pharmaceutical Production:Copper tubing in this application requires exceptional purity and corrosion resistance for transporting process fluids in drug manufacturing. Demand concentrates in the United States and Ireland.
- Sterilization Equipment:Tubing provides critical pathways for steam and sterile gases within autoclaves.
- Surgical Instruments:Miniature copper tubing integrates into specialized surgical tools for precise fluid and gas delivery.
- Laboratory Apparatus:This application involves high-purity tubing for gas chromatography and mass spectrometry.
The dominant usage remains Medical Gas Systems, while Pharmaceutical Production presents an expanding frontier.
End User:
Customer types for medical copper tubing exhibit distinct purchasing patterns and volume demands, influencing distribution strategies and service requirements.
- Hospitals:These institutions are the largest consumers, requiring extensive networks of medical gas tubing for patient care. Demand is driven by new hospital construction in emerging markets and modernization in the United Kingdom.
- Ambulatory Surgical Centers:These facilities are expanding rapidly, driving demand for smaller-scale, often pre-fabricated medical gas systems. Standardized installations in these centers across the United States support growth.
- Medical Laboratories:Laboratories utilize high-purity tubing for gas supply to analytical instruments.
- Diagnostic Clinics:These clinics require medical copper tubing for oxygen delivery and other gases.
- Research Institutions:Academic and private research centers use medical-grade tubing for experimental setups.
Hospitals constitute the primary demand segment, with Ambulatory Surgical Centers demonstrating significant expansion.
Form:
The physical forms of medical copper tubing are tailored to specific installation requirements and mechanical properties, directly impacting flexibility and structural integrity.
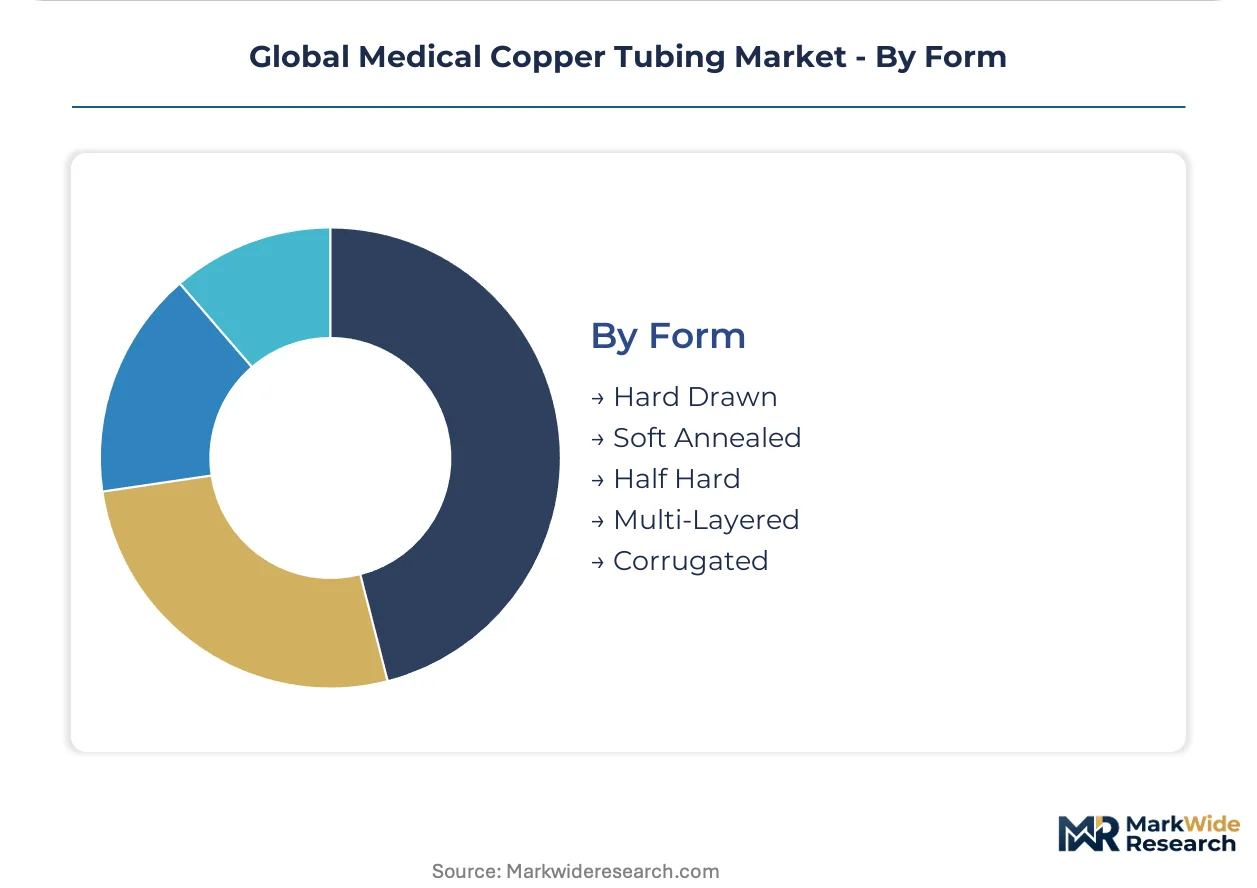
- Soft Annealed:This form is highly ductile and flexible, allowing easy bending during complex installations without compromising internal surface integrity. It is widely used in intricate medical gas system layouts.
- Hard Drawn:Characterized by rigidity and strength, hard drawn tubing is crucial for straight-line piping and structural support in medical gas risers. It is essential in high-pressure systems in large medical facilities.
- Half Hard:Offering a balance between rigidity and flexibility, half hard tubing provides versatility for various installation scenarios.
- Multi-Layered:These specialized tubes incorporate multiple material layers for enhanced barrier properties or specific functional requirements.
- Corrugated:Designed for extreme flexibility and vibration absorption, corrugated forms are used in equipment connections where movement is a factor.
The market is anchored by Soft Annealed and Hard Drawn forms, each serving distinct installation needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers face regulatory arbitrage, with production migrating to regions offering a more favorable balance between stringent quality mandates and operational costs. This dynamic influences investment in new facilities and the relocation of existing production lines. Germany, China, and the United States are pivotal markets, each presenting distinct demand characteristics and regulatory environments.
Germany
Germany's advanced healthcare sector drives consistent demand for high-specification medical copper tubing, particularly for hospital modernization projects. The country's adherence to ISO 7396-1 standards ensures a quality-driven procurement process. Bavarian medical technology clusters, such as those around Erlangen and Munich, actively integrate high-purity tubing into new medical device designs.
China
China's extensive hospital construction boom fuels a substantial demand for medical gas pipeline systems, directly impacting copper tubing consumption. Government-backed healthcare initiatives under the National Health Commission prioritize expanding medical infrastructure, requiring vast quantities of tubing. Major urban centers like Shanghai and Beijing are seeing rapid deployment of new medical facilities, necessitating large-scale installations.
United States
The United States market is characterized by robust demand from both large hospital networks and a rapidly expanding ambulatory surgical center segment. The U.S. FDA's comprehensive oversight of medical devices, including tubing, establishes a high bar for product quality. The Northeast Corridor, with its concentration of research hospitals and medical device manufacturers, remains a significant hub for specialized tubing applications.
India
India's healthcare sector is undergoing significant expansion, with both public and private investment driving new hospital construction and upgrades. The country's national pharmaceutical regulator is increasingly enforcing purity standards for medical infrastructure components. The states of Maharashtra and Karnataka are experiencing rapid development of healthcare facilities, creating substantial demand for medical gas system installations.
United Kingdom
The United Kingdom's National Health Service (NHS) consistently invests in upgrading and expanding its hospital infrastructure, driving demand for modern medical gas systems. Compliance with the EU's Medical Device Regulation (MDR) influences product specifications for suppliers to the UK market. London and the Southeast region remain central to healthcare innovation and large-scale hospital projects, requiring significant tubing volumes.
Global Medical Copper Tubing Market Key Industry Players
European specialty producers anchor one tier, leveraging deep metallurgical expertise to serve high-specification segments, while North American manufacturers hold positions based on manufacturing scale and distribution reach. The market exhibits a tiered structure, with a few large integrated players alongside numerous regional specialists. Two strategic archetypes include those focusing on high-purity niche applications and those prioritizing cost-effective volume production. Capacity expansion and strategic partnerships remain dominant competitive moves.
Within the high-specification tier, Wieland-Werke AG exemplifies a focus on metallurgical expertise and advanced material science. Mueller Industries, Inc. occupies a position as a North American leader, emphasizing manufacturing scale and extensive distribution networks. The Lawton Tube Co. Ltd. sits within the specialized segment, representing producers focused on coated and custom-sized tubes for niche medical applications.
| Leading Market Players |
|---|
| Mueller Industries, Inc. |
| Wieland-Werke AG |
| KME Germany GmbH |
| Cerro Flow Products LLC |
| Cambridge-Lee Industries LLC |
| Great Lakes Copper Ltd. |
| The Lawton Tube Co. Ltd. |
| ABC Tube Company Pvt. Ltd. |
| C&H Medical (Guangzhou) Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The London Metal Exchange (LME) copper price directly influences the cost structure of medical copper tubing, cascading through the supply chain into distinct pricing tiers for end-users. This commodity benchmark creates a baseline for material costs that specialized manufacturers must manage. Market dynamics then differentiate pricing based on product specifications and regional demand.
Pricing Analysis
Distributor margins significantly impact the final price for medical copper tubing, especially for smaller volume orders and specialized products. Project-based pricing dominates large hospital construction, while per-unit transactional pricing applies to smaller clinic upgrades. Price differentiation stems from the strict ASTM B819 purity standards, the level of customization for coated or special-sized tubes, and the sheer volume purchased by large hospital networks. Pricing pressure arises from raw material volatility and the threat of polymer substitution in non-critical applications. Ambulatory Surgical Centers typically exhibit higher price sensitivity compared to major hospital groups.
Supply Chain Analysis
Direct-to-contractor sales channels manage large-scale medical gas system installations, while specialized distributors handle niche applications and smaller facility requirements. Supply of high-purity copper tubing concentrates in Germany with advanced metallurgical producers and in North America for scaled manufacturing. The supply chain relies on consistent access to high-grade copper cathodes. Raw material price volatility on the LME represents a significant structural risk, impacting long-term project cost estimations. The increasing trend towards pre-fabricated medical gas system modules also shifts value creation within the distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by the continuous global expansion and modernization of healthcare infrastructure. Essential medical gas systems ensure consistent demand for high-purity copper tubing.
For Market Incumbents:Anchor market leadership by investing in advanced metallurgical processes for antimicrobial surface development. Expanding manufacturing capacity in strategic regions ensures supply for key markets like China and Germany. Navigating divergent EU MDR and US FDA certification pathways through dedicated regulatory teams mitigates market access threats. Focus on efficiency gains to counter raw material price volatility and maintain competitive positioning against polymer alternatives. Deepening vertical integration into specialized cleaning and capping processes can also reinforce quality control.
For New Entrants and Emerging Players:Underserved dental clinics and veterinary hospitals represent viable entry points for specialized tubing products. Target the rapidly expanding Ambulatory Surgical Center segment in the United States with pre-fabricated medical gas system solutions. A go-to-market angle focused on custom-sized or coated tubing for niche applications offers differentiation. Penetrating emerging markets in Southeast Asia with cost-effective, standards-compliant offerings also provides growth avenues. Emphasize agile manufacturing and rapid customization to address specific project needs.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized producers possessing unique metallurgical expertise or strong regional distribution networks. The market offers long-term viability due to its foundational role in healthcare infrastructure over the next five to ten years. Acquisition targets should include companies with proven innovation in antimicrobial alloys or robust compliance with stringent global standards like ASTM B819. The signal to watch is the accelerated adoption rate of antimicrobial copper alloys in new hospital construction projects, indicating a shift in infection control strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Tubing | Ensures supply for Germany's advanced healthcare sector and China's hospital boom. |
| Antimicrobial Surface R&D | Combats hospital-acquired infections (HAIs) in healthcare facilities. |
| EU MDR Compliance Investment | Navigates strict traceability requirements for European markets. |
| Emerging Market Distribution Partnerships | Penetrates healthcare modernization projects in Southeast Asia. |
| Pre-Fabricated Module Development | Captures value from off-site fabrication trends in North America. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the medical copper tubing market. Primary data collection involved discussions with hospital procurement managers, biomedical engineers, medical device manufacturers, and specialized tubing producers. Secondary research validated insights using ASTM B819 standards, ISO 7396-1 guidelines, EU Medical Device Regulation documentation, and US FDA device approval databases. This dual approach ensured robust bottom-up and top-down triangulation of market data.
The segment-weighting approach was applied to construct the market forecast across the analysis window. Segmentation dimensions modeled included product type, application, end user, form, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and projected healthcare infrastructure spending. Key forecast inputs included global hospital construction project pipelines and medical gas system modernization budgets in developed economies.
Inputs from industry reports and regulatory documents were available through the study window; gaps in real-time raw material cost data introduce uncertainty bands into short-term pricing forecasts. Forecasts reflect assumptions regarding continued healthcare infrastructure investment and stable regulatory environments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Medical Physics Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Medical Tubing Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Medical Computer Carts Market