
 Medical Linear Accelerators (MLA) Market | 2026-2036
Medical Linear Accelerators (MLA) Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Linear Accelerators (MLA) Market Analysis
Multi-energy beam capability is reorganizing competitive dynamics in the medical linear accelerator space. Varian Medical Systems leverages its installed base dominance across North American cancer centers to sustain recurring service revenue. Elekta AB anchors European market presence through specialized proton therapy partnerships. Siemens Healthineers competes by integrating imaging workflows directly into radiation delivery platforms.
Medical linear accelerators are high-frequency electromagnetic devices that generate X-ray or electron beams in the 4–25 MeV range for targeted tumor destruction, with isocenter precision measured in sub-millimeter tolerances. The machine's primary commercial purpose is to deliver fractionated radiation doses that maximize malignant cell death while sparing healthy tissue through computerized beam modulation. Stereotactic systems command premium positioning due to their convergence with real-time imaging and robotic patient positioning. IMRT and VMAT technology segments attract accelerated capital allocation because they reduce treatment session duration and improve dose conformity. Conventional systems retain volume share in emerging markets where infrastructure constraints limit advanced modality deployment.
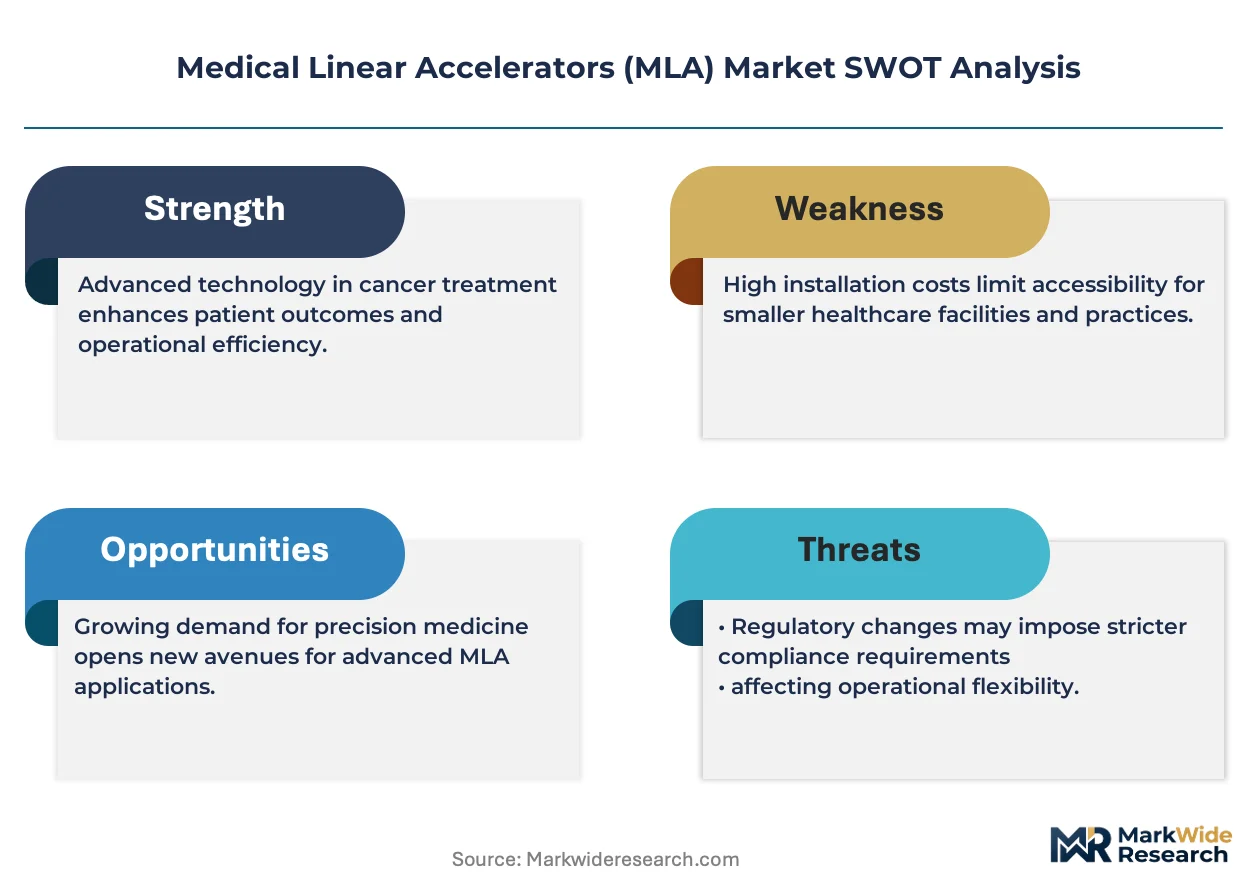
The FDA regulates MLA devices under 21 CFR 1020.32 performance standards for diagnostic x-ray systems, while the EU MDR imposes stricter clinical evidence requirements for Class IIb radiation therapy equipment. These frameworks elevate barriers for new entrants and compel incumbents to maintain dedicated regulatory affairs functions across multiple jurisdictions. Stakeholders must monitor reimbursement parity between hypofractionated and conventional treatment protocols, as payment policy shifts will determine capital recovery timelines for accelerator investments.
Market Dynamics
Fractionated radiation protocols are compressing treatment timelines and forcing capital equipment cycles to accelerate as oncology departments race to expand patient throughput capacity.
Growth Catalysts
- Hypofractionation reimbursement parity:CMS payment alignment between ultra-short and conventional radiation courses in the United States is accelerating capital recovery timelines for high-throughput systems.
- Proton therapy infrastructure:Specialized particle beam partnerships between European university hospitals and equipment vendors are expanding precision oncology access beyond photon-based modalities.
- Real-time imaging convergence:MRI-guided radiation delivery systems are enabling adaptive replanning mid-treatment, pulling demand from conventional linac configurations in major cancer centers.
Market Restraints
- Isotope supply concentration:Molybdenum-99 production relies on aging research reactors in Canada and the Netherlands, creating vulnerability in diagnostic imaging workflows that precede radiation therapy planning.
- EU MDR clinical evidence burden:Class IIb device re-certification demands prospective clinical data collection that extends regulatory timelines and elevates compliance costs for radiation therapy equipment.
- Technical staffing scarcity:Medical physicist training programs in Germany and the United States produce insufficient graduates to operate expanding radiotherapy departments.
Strategic Opportunities
- India's tier-two city penetration:Government-funded cancer center construction in Lucknow, Jaipur, and Indore is creating first-mover advantage for vendors willing to localize service infrastructure.
- Carbon ion therapy adoption:Japan's National Institute of Radiological Sciences licensing model is enabling replication in Chinese and German academic medical centers seeking radioresistant tumor capabilities.
- Artificial intelligence planning integration:Automated contouring and dose optimization algorithms are reducing physicist labor intensity, opening efficiency gains in high-volume community oncology settings.
Industry Challenges
- Legacy system interoperability:PACS and RIS integration with modern linac control systems requires custom middleware development that extends deployment timelines and elevates project risk.
- Commissioning timeline compression:Beam data acquisition and regulatory acceptance testing for multi-energy systems demands specialized expertise that outstrips available vendor field engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Linear Accelerators (MLA) Market |
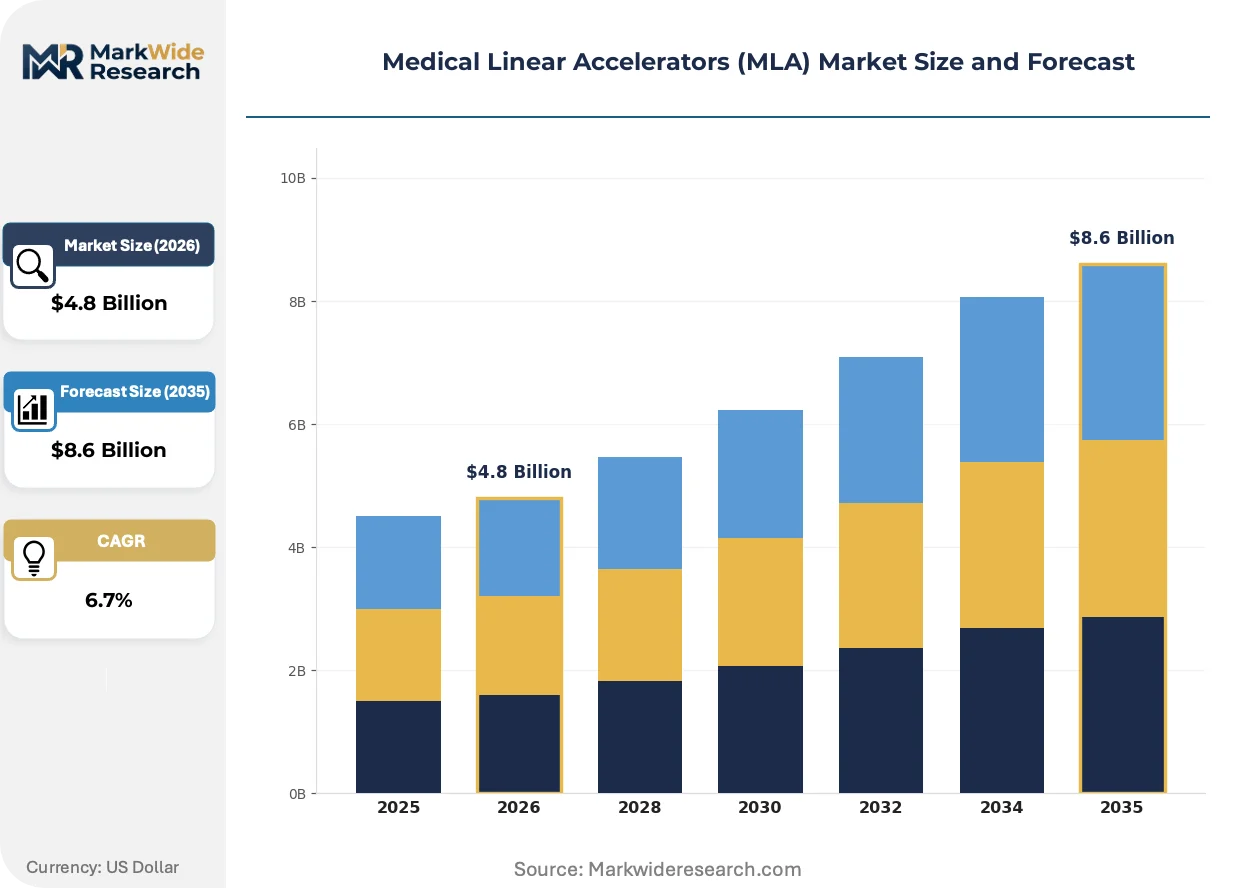
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Digital, Hybrid, Stereotactic Technology: Photon, Electron, IMRT, VMAT End User: Hospitals, Cancer Clinics, Research Institutes, Academic Centers Application: Radiotherapy, Clinical Research, Education, Quality Assurance |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, Siemens Healthineers, Hitachi Ltd., Shinva Medical Instrument Co. Ltd., Mitsubishi Heavy Industries Ltd., ViewRay Inc., Brainlab AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Linear Accelerators (MLA) Market Emerging Trajectories
Adaptive radiation therapy workflows are collapsing the boundary between imaging and treatment delivery, forcing equipment architectures to merge previously separate hardware categories.
Magnetic resonance linear accelerator systems are decomposing the traditional separation between diagnostic imaging suites and radiation bunkers. Major academic centers in the United States and Germany are consolidating these investments into single-vendor relationships to secure priority service access. The technology is decomposing conventional cobalt-60 backup strategies as real-time soft-tissue visualization eliminates the need for pretreatment verification imaging.
The EU MDR's post-market surveillance requirements are mandating systematic clinical follow-up data collection for radiation therapy devices. Manufacturers must now maintain active implant registries and adverse event reporting systems that parallel pharmaceutical vigilance standards. European notified bodies are prioritizing review capacity for Class IIb submissions, creating backlog risk for smaller vendors without dedicated regulatory affairs teams.
Hospital procurement departments are consolidating radiation oncology capital decisions into centralized value analysis committees that span multiple service lines. Equipment vendors now face extended sales cycles involving chief financial officers and supply chain executives alongside clinical champions. This pattern is most pronounced in United States integrated delivery networks where radiotherapy purchases require system-level capital allocation approval.
Medical Linear Accelerators (MLA) Market Segmentation
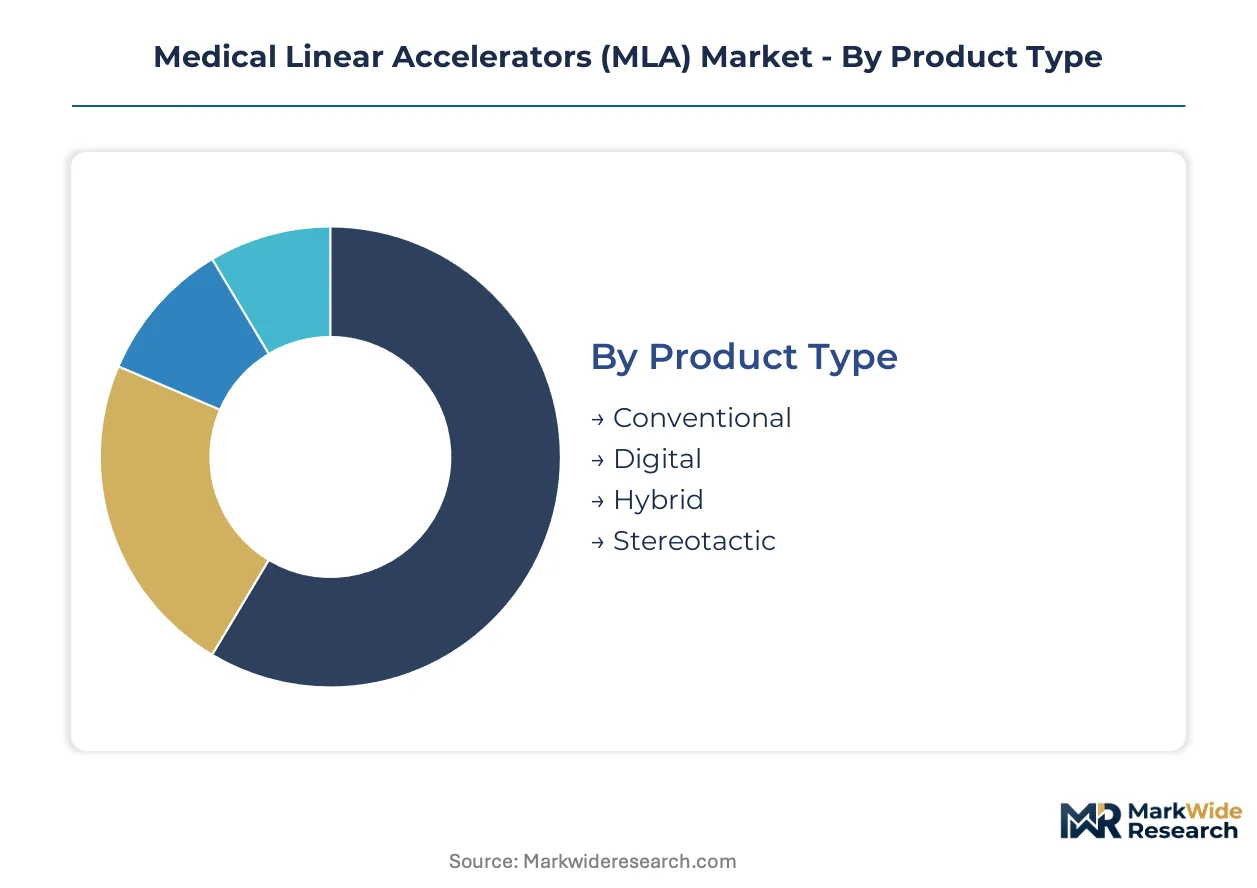
Segmentation in the MLA market reveals how beam generation architectures and treatment delivery protocols create distinct investment profiles. Procurement committees weigh throughput capacity against precision specifications when allocating capital across technology tiers.
Product Type:
Stereotactic configurations face intensifying substitution pressure from MRI-guided platforms that collapse imaging and treatment into unified workflows.
- Conventional:Fixed-energy systems deliver 4–6 MV photon beams through isocentric gantry designs. Demand concentrates in India's tier-two cities and Southeast Asian hospital networks where infrastructure budgets constrain advanced modality adoption.
- Digital:Fully integrated control systems enable remote beam monitoring and predictive maintenance protocols. German university hospitals prioritize these configurations to satisfy EU MDR documentation requirements while minimizing physicist labor intensity.
- Hybrid:Dual-modality platforms combine conventional linac bases with stereotactic cone attachments for versatility across fractionation protocols.
- Stereotactic:Sub-millimeter precision systems with robotic patient positioning and real-time tumor tracking capabilities.
Conventional systems retain volume leadership; stereotactic configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates research-intensive modalities from workhorse clinical applications.
- Photon:Megavoltage X-ray beams remain the clinical standard for deep-seated tumors. United States community oncology networks deploy these systems most densely where CMS reimbursement parity for hypofractionation accelerates capital recovery.
- Electron:Surface and shallow-target applications leverage variable electron energies without beam-hardening filtration. Chinese provincial cancer centers expanding skin cancer and intraoperative programs drive regional demand concentration.
- IMRT:Intensity-modulated beams use multileaf collimator sequencing to sculpt dose distributions around critical structures.
- VMAT:Volumetric arc delivery compresses treatment times through continuous gantry rotation during beam modulation.
Photon technology anchors installed base economics; VMAT protocols are climbing the fastest in new equipment specifications.
End User:
Customer type determines service infrastructure requirements and financing structure preferences.
- Hospitals:Integrated delivery networks in the United States consolidate radiation oncology into system-level capital planning. These purchasers demand single-vendor imaging-treatment ecosystems to streamline service contracts and staff training standardization.
- Cancer Clinics:Freestanding facilities prioritize throughput-per-square-foot metrics and extended operating hours. German outpatient radiotherapy centers favor leased equipment arrangements to preserve balance sheet flexibility under EU banking regulations.
- Research Institutes:National laboratories and particle physics facilities developing next-generation beam delivery concepts.
- Academic Centers:Teaching hospitals with residency programs requiring training-specific beam configurations and research data access.
Hospitals command the largest equipment budgets; cancer clinics are expanding most quickly in procedure volume per site.
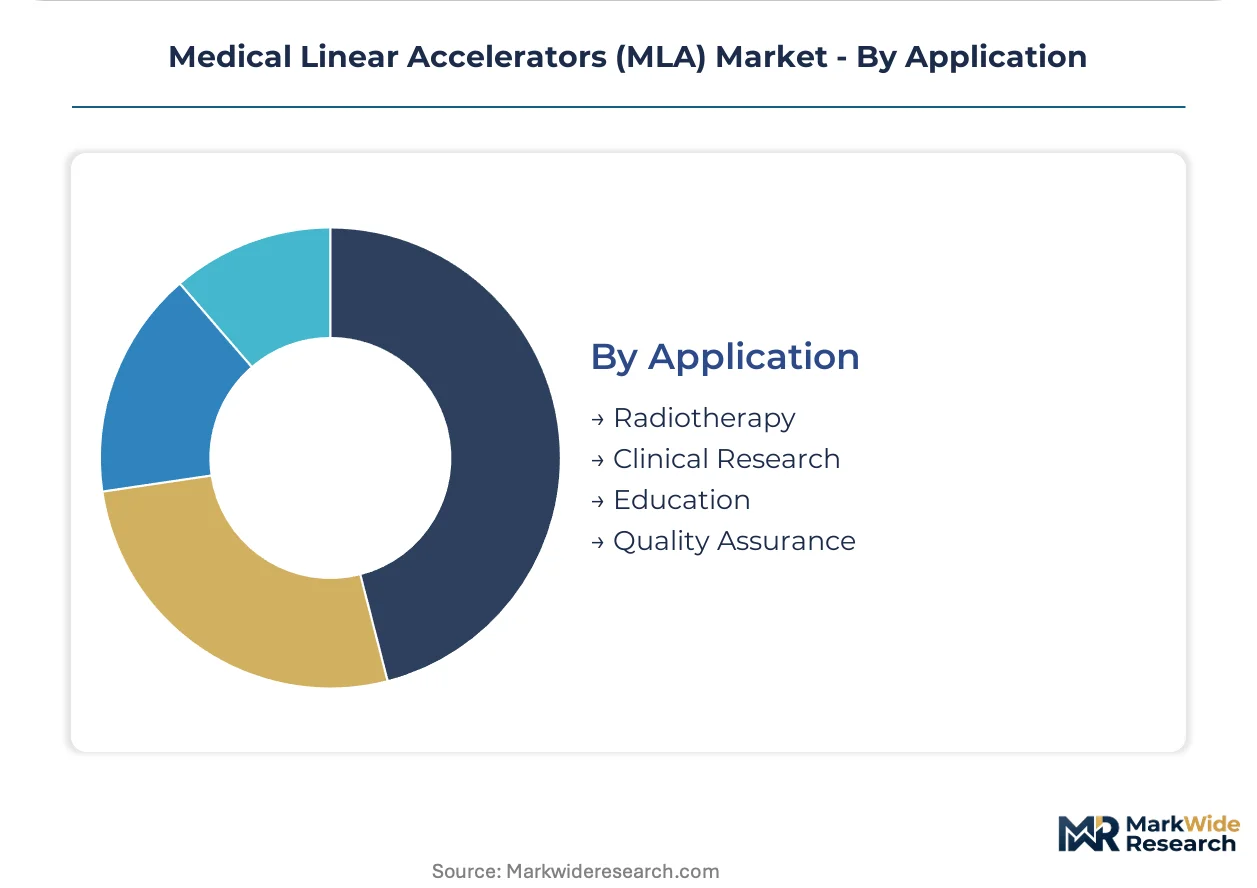
Application:
Volume concentration in therapeutic delivery leaves limited margin contribution from non-clinical use cases.
- Radiotherapy:Curative and palliative tumor treatments constitute the primary revenue driver. Japan's National Health Insurance reimbursement schedules and China's centralized procurement frameworks shape regional equipment specifications.
- Clinical Research:Adaptive therapy trials and dose-escalation studies require specialized beam monitoring and data capture infrastructure. United States NCI-designated cancer centers concentrate demand for research-configurable platforms.
- Education:Medical physics residency programs and radiation therapist training curricula.
- Quality Assurance:Phantom-based dosimetry verification and regulatory compliance testing protocols.
Radiotherapy dominates revenue contribution; clinical research applications are gaining share fastest in academic procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows concentrate in the United States, Germany, and China while export capacity clusters in Sweden, Japan, and the Netherlands. Trade balances reflect domestic manufacturing depth versus specialized component sourcing needs.
United States
FDA 21 CFR 1020.32 compliance costs favor established vendors with dedicated regulatory affairs teams. CMS reimbursement parity for hypofractionated protocols accelerates capital recovery timelines in community oncology networks. The MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor demand for MRI-guided adaptive systems.
Germany
EU MDR Class IIb re-certification demands prospective clinical data collection that extends regulatory timelines. University hospital partnerships with proton therapy specialists concentrate in Heidelberg and Munich. The country's medical physicist training programs face capacity constraints relative to expanding radiotherapy department needs.
China
NMPA streamlined approval pathways for innovative radiation therapy equipment shorten market entry timelines. Government-funded cancer center construction in provincial capitals drives tier-two city penetration. The National Cancer Center in Beijing and Fudan University Shanghai Cancer Center concentrate demand for carbon ion therapy replication.
Japan
PMDA post-market surveillance requirements align with the National Institute of Radiological Sciences licensing model for heavy ion capabilities. METI industrial policy supports domestic accelerator component manufacturing. Chiba and Hyogo prefectures host the primary carbon ion therapy facilities enabling technology export.
India
CDSCO medical device rules impose quality benchmarks that elevate barriers for non-specialized entrants. Government-funded cancer center construction in Lucknow, Jaipur, and Indore creates first-mover advantage for vendors with localized service infrastructure. Tata Memorial Centre in Mumbai anchors clinical training and referral networks.
Medical Linear Accelerators (MLA) Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The vendor base organizes into three tiers: integrated imaging-radiation platforms, standalone accelerator specialists, and regional service-focused distributors. Strategic archetypes include installed-base incumbents leveraging recurring service revenue, proton therapy partnership specialists, and imaging convergence integrators. Dominant competitive moves span single-vendor ecosystem consolidation and predictive maintenance capability deployment.
Within the integrated platform tier, Siemens Healthineers and Hitachi Ltd. exemplify imaging-radiation convergence strategies. Varian Medical Systems and Elekta AB anchor the standalone accelerator specialist archetype with differentiated geographic footprints. Among Asia-Pacific fabricators, Shinva Medical Instrument Co. Ltd. occupies a position reflecting regional service infrastructure localization priorities. Mitsubishi Heavy Industries Ltd. sits within the heavy ion and particle beam specialization segment. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| Siemens Healthineers |
| Hitachi Ltd. |
| Shinva Medical Instrument Co. Ltd. |
| Mitsubishi Heavy Industries Ltd. |
| ViewRay Inc. |
| Brainlab AG |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with embedded spare parts provisions lock in supply access for cancer centers while flattening price volatility across multi-year equipment lifecycles. German university hospitals and United States integrated delivery networks favor these arrangements to secure priority field engineering capacity under EU MDR and FDA compliance timelines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the MLA space. Premium tiers bundle MRI-guided adaptive platforms with predictive maintenance subscriptions, while economy configurations serve Indian tier-two hospitals with stripped-down photon systems. Price differentiation rests on FDA 510(k) clearance tier and installed-base service density. Cost compression in standard-tier IMRT systems is intensifying because Chinese provincial procurement panels enforce centralized bidding protocols. Community oncology networks in the United States exhibit highest price sensitivity; academic proton therapy partnerships show least.
Supply Chain Analysis
Strait of Hormuz transit underwrites molybdenum-99 isotope flows from European research reactors to Asian diagnostic facilities preceding radiation therapy planning. Supply concentrates in Sweden for precision gantry fabrication, Japan for superconducting magnet components, and the Netherlands for aging research reactor isotope production. Raw material dependencies include high-purity copper for RF cavities, niobium-titanium superconducting wire, and specialized tungsten alloy targets. Single-source vulnerability sits with Canadian and Dutch reactor infrastructure approaching end-of-life without replacement capacity. Distribution runs through authorized service distributors with certified medical physicist field teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MLA market reads as a medical physicist scarcity story, where training program throughput constrains equipment utilization rates regardless of capital deployment. This skill gap creates asymmetric returns for vendors who automate treatment planning workflows.
For Market Incumbents: Shield recurring service revenue by embedding predictive maintenance algorithms that reduce customer switching costs. Varian Medical Systems and Elekta AB should deepen backward integration into RF power component manufacturing to offset supply volatility from Swedish and Japanese specialty fabricators. Prioritize FDA pre-submission pathways for AI-contouring software to preempt regulatory bottlenecks as EU MDR clinical evidence demands escalate. For New Entrants and Emerging Players: CDSCO fast-track approval for refurbished digital linac platforms creates white-space entry into Indian tier-two city installations where Tata Memorial Centre referral networks concentrate demand. Carbon ion therapy licensing partnerships with Japan's National Institute of Radiological Sciences offer second penetration vector for Chinese academic medical centers seeking radioresistant tumor capabilities. Lead with leased equipment arrangements to bypass capital budget constraints in German outpatient radiotherapy centers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among installed-base incumbents with captive service infrastructure spanning North American cancer center networks. Long-term viability favors vendors integrating imaging-radiation workflows rather than standalone accelerator specialists facing MRI-guided platform substitution. Monitor CMS reimbursement parity shifts between hypofractionated and conventional protocols as inflection signal for capital equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI Treatment Planning Integration | Automated contouring reduces physicist labor intensity in high-volume community oncology settings. |
| Proton Therapy Partnership | Heidelberg and Munich university hospitals anchor European particle beam infrastructure expansion. |
| MRI-Guided Platform Convergence | MD Anderson and Memorial Sloan Kettering consolidate single-vendor imaging-treatment ecosystems. |
| India Tier-Two Localization | Lucknow and Jaipur government-funded cancer centers demand localized service infrastructure. |
| EU MDR Compliance Investment | Prospective clinical data collection extends regulatory timelines for Class IIb radiation therapy equipment. |
Methodological Framework
A standing panel of radiation oncology department heads, medical physicists, hospital GPO contracts managers, and biomedical engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) premarket notification database, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and NMPA innovative device approval pathways. Bottom-up equipment shipment tracking triangulated against top-down cancer incidence projections and radiotherapy utilization rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning beam generation architecture, treatment delivery protocol, end-user facility type, and regional regulatory cluster. CAGRs were derived from installed base depreciation curves and replacement demand elasticity. Forecast inputs incorporated hypofractionation reimbursement parity shifts and proton therapy infrastructure buildout timelines.
Decision-makers should treat outputs as directional under base assumptions of stable isotope supply and physicist training program throughput; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance requirements and CMS payment policy shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Electron Beam Linear Accelerators Market