
 Chile Radiotherapy Market | 2026-2036
Chile Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Radiotherapy Market Intelligence
Chile is rewriting its radiotherapy access map through public-private oncology partnerships and linear accelerator installations in secondary cities. Varian Medical Systems, Inc. anchors the equipment supply landscape through its installed base of linear accelerators in Santiago and regional hubs. Elekta AB competes with specialized stereotactic body radiation systems that differentiate its portfolio in academic institutes. Accuray Incorporated positions its proton therapy offerings for high-complexity cases in elite cancer treatment centers.
Radiotherapy encompasses the clinical use of ionizing radiation delivered via photon, electron, or particle beams to destroy malignant cells while sparing healthy tissue, with linear accelerators generating X-ray energies between 4 and 25 MeV for deep-seated tumors. Linear accelerators dominate capital expenditure flows due to their versatility across breast, prostate, and lung cancer protocols. External beam radiation leads delivery mode utilization in Chile's hospital network, while stereotactic body radiation represents the fastest-growing modality as precision targeting capabilities expand. Brachytherapy devices occupy a mature niche with stable replacement demand in gynecological and prostate applications.
Chile's Ministry of Health regulates radiotherapy facility licensing through its national oncology program, while the country's nuclear energy commission oversees cobalt-60 source importation and radioactive waste protocols for brachytherapy services. CE-marked equipment standards from European manufacturers shape procurement specifications, and ISO 13485 quality management requirements filter supplier eligibility for public tenders. Stakeholders must monitor reimbursement rate negotiations between Fonasa and private insurers, as these directly determine treatment center willingness to invest in next-generation delivery systems.
Market Dynamics
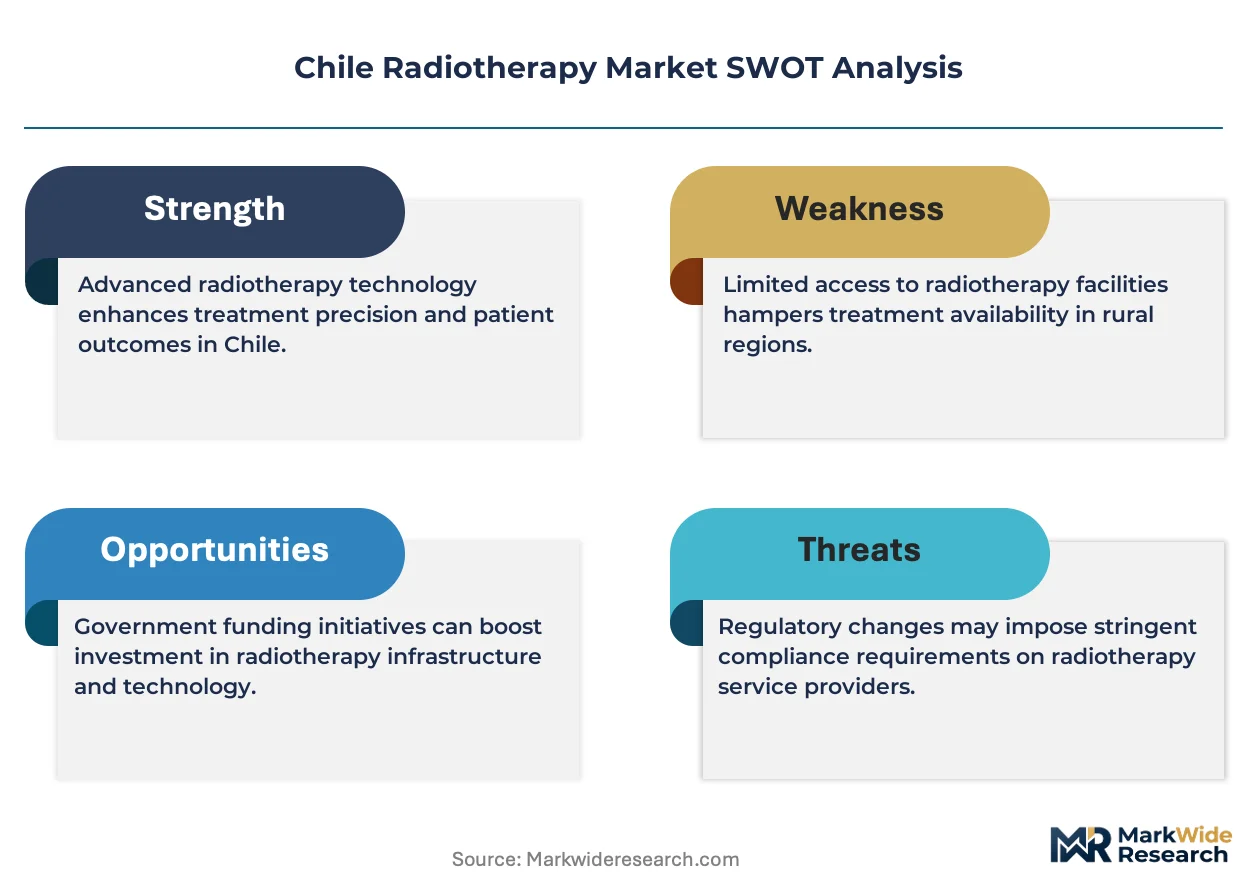
Chile's radiotherapy sector is restructuring around Fonasa reimbursement rate negotiations, which determine whether public hospitals can justify linear accelerator investments against operational cost recovery timelines.
Growth Catalysts
- Metropolitan patient concentration:Santiago's density of insured populations generates predictable treatment volumes that amortize equipment costs faster than peripheral installations.
- Ministry of Health oncology infrastructure program:Public capital allocations for regional cancer centers are accelerating linear accelerator procurement in secondary cities previously dependent on cobalt-60 units.
- SBRT protocol expansion:Stereotactic body radiation therapy's precision targeting is extending curative indications to early-stage lung and prostate cases previously routed to surgery.
Market Restraints
- Linear accelerator supply concentration:Equipment procurement depends on a narrow vendor base with European and North American manufacturing footprints, exposing buyers to currency fluctuation risk and extended lead times.
- Radioactive waste handling costs:Brachytherapy services face escalating disposal fees under Chile's nuclear energy commission protocols, compressing margins on established gynecological procedures.
- Specialized physicist scarcity:Treatment planning and quality assurance functions require professionals with dual competencies in medical physics and radiation safety that domestic training programs produce insufficiently.
Strategic Opportunities
- Antofagasta and Biobío regional expansion:Northern mining corridors and southern industrial zones host underserved populations with rising cancer incidence but minimal radiotherapy access within 300 kilometers.
- Public-private partnership models:Concession structures allowing private operators to manage equipment and staffing within public hospital shells are unlocking capital without direct ministry expenditure.
- Proton therapy anchor installations:Elite Santiago centers can capture complex pediatric and ocular cases from across the Southern Cone where no domestic proton facilities currently operate.
Industry Challenges
- Linear accelerator commissioning timelines:CE-marked equipment acceptance testing and clinical protocol validation extend 12-18 months from delivery to first patient treatment, straining hospital project budgets.
- Interoperability with legacy cobalt-60 bunkers:Shielding specifications and room geometries designed for older isotope units often require complete structural renovation to accommodate modern accelerator footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Radiotherapy Market |
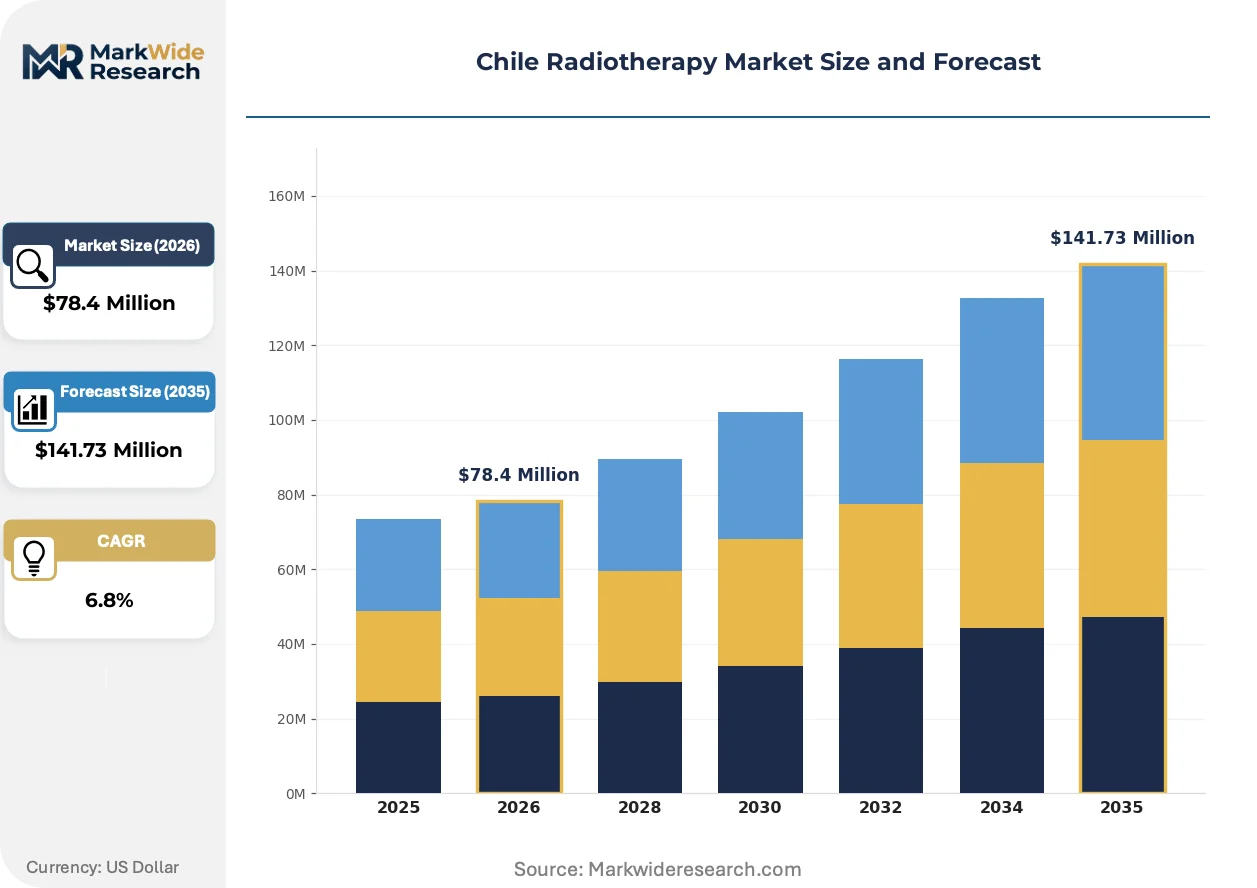
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt Machines, Linear Accelerators, Brachytherapy Devices, Systemic Radiotherapy End User: Hospitals, Cancer Treatment Centers, Academic Institutes, Research Laboratories Delivery Mode: External Beam Radiation, Internal Radiation, Intraoperative Radiation, Stereotactic Body Radiation Application: Breast Cancer, Prostate Cancer, Lung Cancer, Skin Cancer |
| Companies Covered | Varian Medical Systems, Inc., Elekta AB, Accuray Incorporated, Becton, Dickinson and Company, NTP Radioisotopes, Isoray Medical, Ion Beam Applications SA, RaySearch Laboratories AB, Mevion Medical Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Radiotherapy Market Strategic Shifts & Innovations
Artificial intelligence integration and hypofractionation protocols are compressing treatment delivery times while expanding the addressable patient base beyond traditional radiation oncology capacity constraints.
Adaptive radiotherapy planning software is collapsing the gap between simulation and treatment delivery by enabling daily anatomical adjustments based on onboard imaging. Santiago's academic medical centers are piloting these systems for prostate and cervical cases with significant organ motion. The technology is compressing planning workload per fraction while maintaining dose conformity that static plans cannot achieve.
Chile's Ministry of Health has tightened facility licensing requirements through its national oncology program, mandating minimum annual case volumes for external beam authorization. This regulatory compression is forcing low-throughput centers to consolidate or upgrade to multi-energy linear accelerators capable of diverse protocols. Secondary cities with single-machine installations face the steepest compliance pathway.
Hospital procurement committees are unbundling equipment purchases from multi-year service contracts, negotiating separate maintenance agreements with third-party clinical engineering firms. This purchasing behavior shift is disrupting traditional vendor-captive service models and pressuring original equipment manufacturers to compete on parts availability and response time guarantees rather than bundled financing. The trend is most visible in Santiago's municipal hospital network where budget autonomy has expanded.
Chile Radiotherapy Market Segmentation
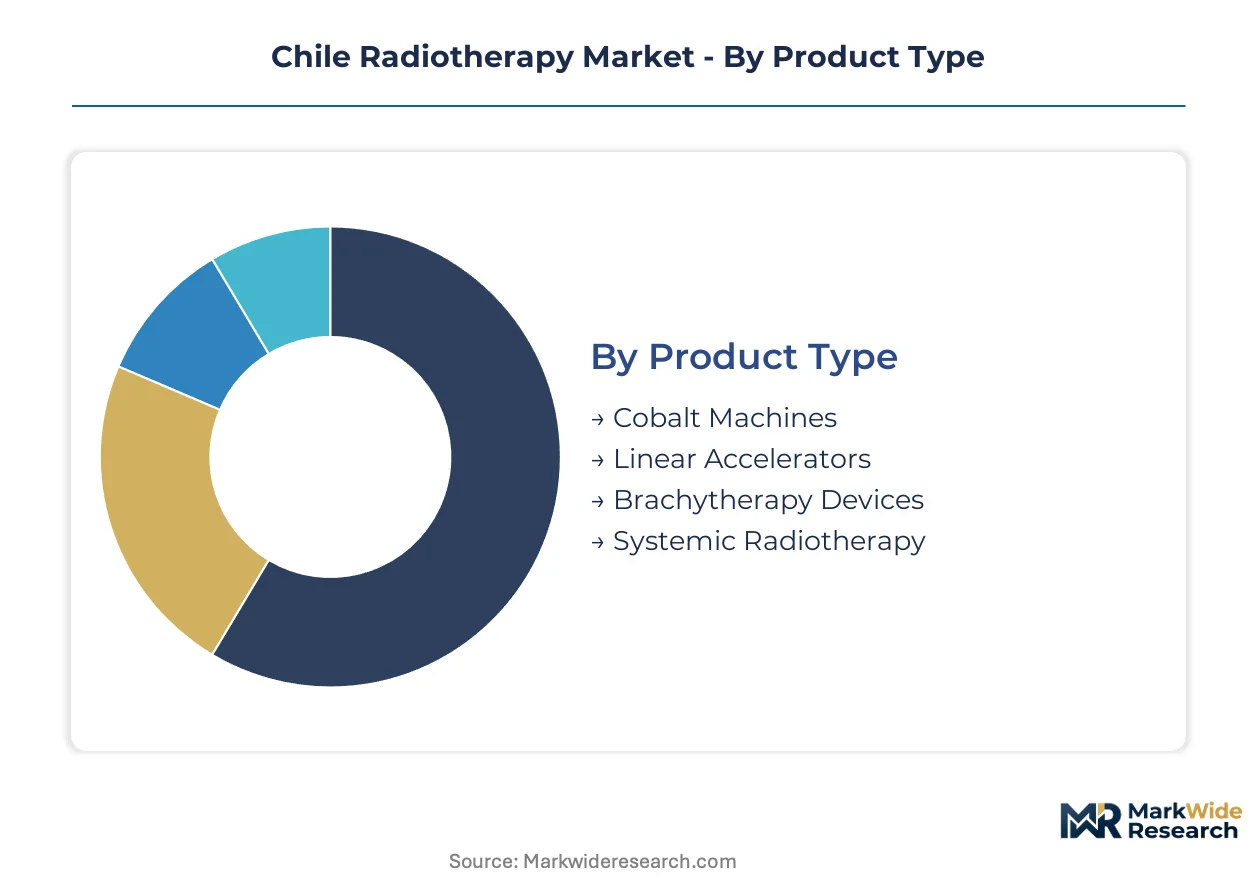
Equipment heterogeneity across Chile's radiotherapy landscape creates divergent service revenue profiles and replacement cycle dynamics. Segmentation reveals how capital intensity, clinical protocol complexity, and reimbursement alignment concentrate demand across distinct product configurations and institutional settings.
Product Type:
After-sales-service intensity varies dramatically across equipment categories, with linear accelerators demanding multi-year maintenance contracts and cobalt machines requiring isotope logistics rather than technical service.
- Linear Accelerators:Multi-energy X-ray systems generating 4-25 MeV beams dominate capital flows across Chile's hospital procurement pipelines. Santiago's public oncology network and regional cancer centers concentrate replacement demand as cobalt-60 units reach end-of-life, with Fonasa reimbursement rates determining payback timelines for Varian and Elekta installations.
- Brachytherapy Devices:Isotope-based internal delivery systems occupy a mature niche with stable replacement cycles in gynecological and prostate applications. Escalating radioactive waste disposal fees under Chile's nuclear energy commission protocols compress margins, limiting new entrant interest despite established clinical demand in metropolitan treatment centers.
- Cobalt Machines:Legacy isotope units face accelerated phase-out as the Ministry of Health's oncology infrastructure program prioritizes linear accelerator modernization in secondary cities.
- Systemic Radiotherapy:Radioisotope pharmaceuticals for metastatic disease management represent the smallest equipment category with minimal domestic manufacturing footprint.
By volume, Linear Accelerators lead. By growth pace, Brachytherapy Devices are expanding most quickly through precision applicator upgrades.
End User:
Institutional purchasing authority shapes procurement patterns, with public hospitals navigating Fonasa rate negotiations while private cancer treatment centers optimize for insured patient throughput.
- Hospitals:General acute-care facilities with radiation oncology departments anchor external beam capacity in Chile's urban centers. Santiago's municipal hospital network and regional public hospitals concentrate linear accelerator installations, though physicist scarcity constrains treatment planning throughput.
- Cancer Treatment Centers:Specialized facilities drive stereotactic body radiation adoption and hypofractionation protocol expansion. These centers capture complex cases from across metropolitan regions, amortizing equipment costs through higher daily patient volumes than general hospital departments.
- Academic Institutes:University-affiliated medical centers pilot adaptive radiotherapy planning software and train the limited domestic supply of medical physicists.
- Research Laboratories:Preclinical radiation biology facilities occupy a peripheral position with minimal commercial equipment demand.
By patient throughput concentration, Hospitals dominate. By technology advancement velocity, Cancer Treatment Centers are gaining share fastest.
Delivery Mode:
Clinical protocol selection determines equipment utilization rates and reimbursement capture, with precision modalities commanding premium positioning despite longer treatment planning cycles.
- External Beam Radiation:Conventional fractionated photon therapy from linear accelerators accounts for the majority of treatment sessions across Chile's hospital network. This modality's versatility across tumor sites maintains its central position in ministry procurement specifications.
- Stereotactic Body Radiation:High-precision ablative dosing with motion management and image guidance represents the steepest expansion trajectory. Santiago's elite centers are extending curative indications to early-stage lung and prostate cases previously routed to surgery, compressing treatment courses from weeks to days.
- Internal Radiation:Brachytherapy catheter-based delivery maintains stable utilization in cervical and prostate protocols with established reimbursement pathways.
- Intraoperative Radiation:Single-fraction electron delivery during surgical resection occupies a narrow niche with limited equipment installations nationwide.
By session volume, External Beam Radiation leads. By protocol expansion rate, Stereotactic Body Radiation is climbing the fastest.
Application:
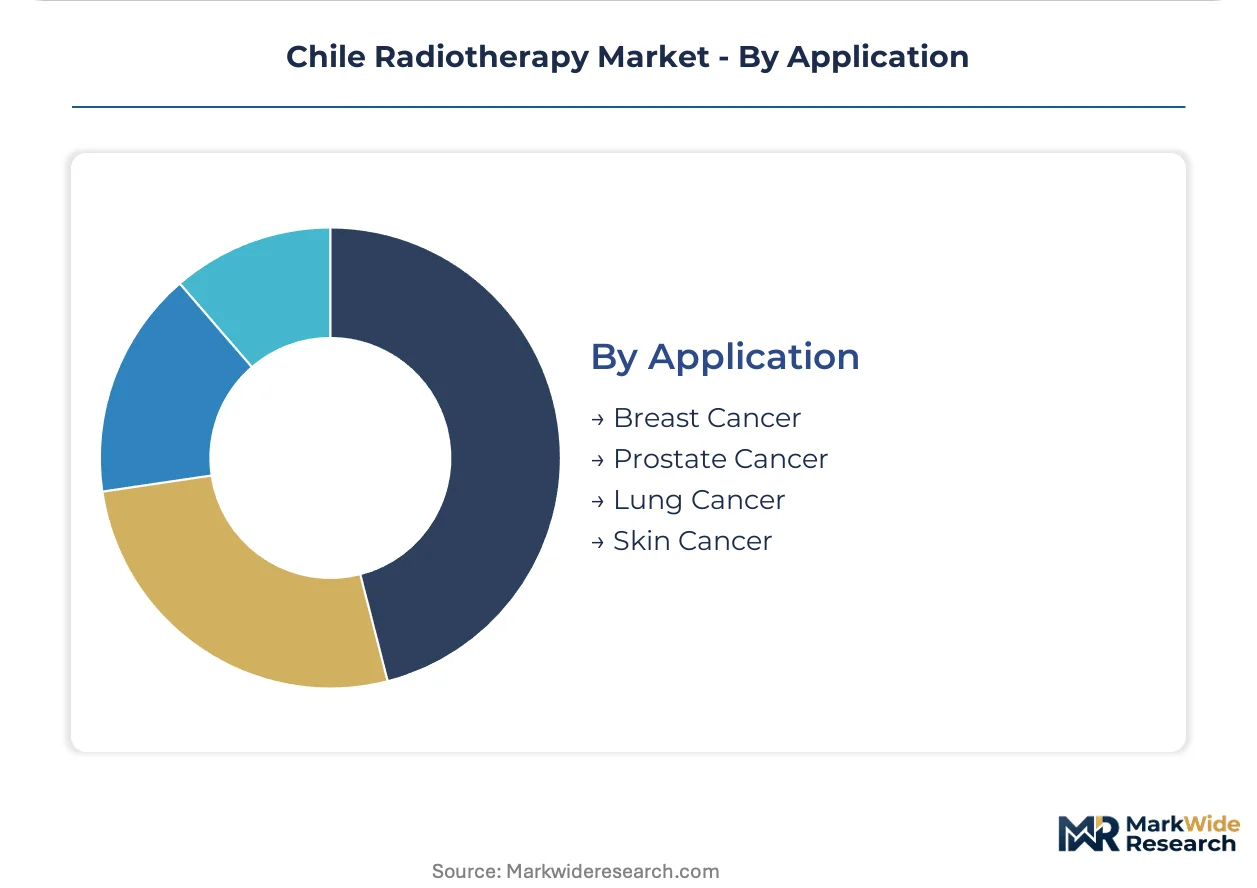
Tumor-specific incidence patterns and screening program coverage determine addressable patient pools, with breast and prostate cancer concentration in insured metropolitan populations driving equipment location decisions.
- Prostate Cancer:High prevalence among Chile's aging male population combines with favorable hypofractionation suitability to drive linear accelerator demand. Santiago's private oncology centers and public hospitals both prioritize prostate protocol capability in equipment specifications.
- Lung Cancer:Rising incidence and stereotactic body radiation eligibility for early-stage cases are reshaping referral patterns. Academic medical centers in the Metropolitan Region are capturing complex thoracic cases requiring motion management and adaptive planning.
- Breast Cancer:National screening program coverage and established adjuvant radiation protocols maintain consistent external beam demand across regional cancer centers.
- Skin Cancer:Superficial lesions and electron therapy applications represent a smaller addressable market with limited dedicated equipment requirements.
By treatment course volume, Breast Cancer leads. By modality shift intensity, Lung Cancer is advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiotherapy utilization patterns diverge sharply across Chile's administrative regions, with metropolitan centers deploying precision modalities while peripheral provinces rely on conventional external beam protocols.
Santiago Metropolitan Region
Fonasa-insured patient density and private oncology center concentration drive linear accelerator throughput rates threefold above national averages. The Ministry of Health's national oncology program mandates minimum case volumes that Santiago facilities exceed routinely. Las Condes and Providencia host the country's densest cluster of stereotactic body radiation capability.
Valparaíso Region
Port-city industrial exposure elevates lung cancer incidence relative to population size, creating demand for motion-managed external beam systems. The regional health service navigates CE-marked equipment procurement under tighter budget constraints than Santiago counterparts. Viña del Mar's municipal hospital anchors radiotherapy access for a catchment of 1.7 million residents.
Biobío Region
Aging industrial infrastructure and delayed screening program penetration concentrate late-stage cancer presentations requiring palliative radiation. The Ministry of Health's regional cancer center initiative targets Concepción for linear accelerator installation to replace legacy cobalt-60 capacity. Local procurement committees face extended commissioning timelines due to physicist recruitment gaps.
Antofagasta Region
Mining corridor demographics skew male and aged, amplifying prostate and lung cancer caseloads against minimal baseline radiotherapy infrastructure. Patients routinely travel 300+ kilometers to Santiago for curative intent treatment, compressing regional survival outcomes. The northern regional health secretariat has prioritized public-private partnership models to attract capital without direct ministry expenditure.
Maule Region
Agricultural economy demographics and dispersed rural settlement patterns complicate patient travel logistics for fractionated treatment courses. Talca's regional hospital maintains single-machine external beam capacity with limited hypofractionation protocol adoption. CE-marked equipment standards and ISO 13485 supplier requirements filter tender participation to established European and North American vendors.
Chile Radiotherapy Market Key Industry Players
Capability concentration sits with the linear accelerator manufacturing tier; scale advantage sits with the service contract and after-sales infrastructure tier. The Chilean radiotherapy equipment landscape structures around three to four dominant original equipment manufacturers with installed base lock-in, while a secondary tier of software and isotope suppliers captures ancillary revenue streams. Two strategic archetypes predominate: full-stack radiation therapy system integrators and specialized precision modality developers. Competitive maneuvering concentrates on multi-year service contract unbundling and third-party clinical engineering partnerships that disrupt traditional vendor-captive models.
Among the full-stack system integrators, Varian Medical Systems, Inc. and Elekta AB occupy positions that exemplify contrasting portfolio strategies—one anchoring installed base breadth across Santiago's hospital network, the other representing specialized stereotactic and adaptive planning capabilities. Accuray Incorporated sits within the precision modality tier, its proton and particle therapy associations positioning it for high-complexity case capture in elite metropolitan centers. These three manufacturers collectively represent the equipment supply landscape's dominant competitive anchors.
| Leading Market Players |
|---|
| Varian Medical Systems, Inc. |
| Elekta AB |
| Accuray Incorporated |
| Becton, Dickinson and Company |
| NTP Radioisotopes |
| Isoray Medical |
| Ion Beam Applications SA |
| RaySearch Laboratories AB |
| Mevion Medical Systems Inc. |
| Others |
Cost & Logistics Intelligence
The Valparaíso-Santiago freight corridor's container logistics costs compress margins on CE-marked linear accelerator imports while amplifying price differentiation between bundled service contracts and unbundled equipment-only procurement. European and North American manufacturing concentration hands original equipment manufacturers substantial pricing power over Chilean hospital procurement committees navigating Fonasa reimbursement constraints.
Pricing Analysis
Long-term service contracts dominate equipment procurement, with multi-year maintenance agreements bundled into capital expenditure flows. Pricing stratifies across premium accelerator tiers with adaptive planning software, standard multi-energy configurations, and economy cobalt-replacement units. Cost compression in the standard tier intensifies as third-party clinical engineering firms unbundle service provision. Public hospitals exhibit highest price sensitivity due to fixed Fonasa rates; private cancer treatment centers absorb premium positioning for insured patient throughput.
Supply Chain Analysis
Upstream magnetron and klystron tube production draws from specialized facilities in Germany, Sweden, and the United States. Linear accelerator gantries, treatment couch assemblies, and multi-leaf collimator systems feed from these concentrated manufacturing nodes. Single-source vulnerability runs through cobalt-60 isotope supply chains governed by Chile's nuclear energy commission import protocols. Distribution runs through authorized distributor networks with clinical engineering certification requirements filtering direct hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's radiotherapy sector is restructuring around artificial intelligence integration and hypofractionation protocols that compress treatment delivery timelines. The Ministry of Health's tightened facility licensing requirements create regulatory inflection favoring capital-rich operators capable of multi-energy accelerator investments.
For Market Incumbents: Build installed base moats through captive service infrastructure and software upgrade pathways. Accelerate replacement cycle capture in secondary cities where cobalt-60 phase-out creates urgent demand. Counter third-party clinical engineering encroachment by guaranteeing parts availability and response time commitments that unbundled competitors cannot match. For New Entrants and Emerging Players: Build out precision modality specialization in stereotactic body radiation and adaptive planning software where Elekta and Accuray have established beachheads. Antofagasta and Biobío regions present the most penetrable geography given minimal baseline radiotherapy infrastructure and active public-private partnership solicitation. Pursue concession-based operational contracts that transfer equipment risk to private operators while capturing patient volume revenue. For Investors and Strategic Acquirers: Third-party clinical engineering specialists with ISO 13485 certification and established hospital relationships represent the most attractive acquisition archetype. Long-term viability hinges on Fonasa reimbursement rate trajectories and Ministry of Health capital allocation continuity. Monitor proton therapy anchor installation announcements in Santiago as signal of high-complexity case capture ambition across the Southern Cone.| Strategic Initiative | Industry Significance |
|---|---|
| Public-Private Partnership Concession | Unlocks linear accelerator deployment in Antofagasta and Biobío without direct ministry capital expenditure. |
| Adaptive Radiotherapy Software Integration | Enables daily anatomical adjustments that differentiate Santiago academic medical centers from regional competitors. |
| Third-Party Service Contract Unbundling | Disrupts vendor-captive maintenance models and pressures original equipment manufacturers on response guarantees. |
| Proton Therapy Anchor Installation | Positions elite metropolitan centers to capture complex pediatric and ocular cases from across the Southern Cone. |
| Physicist Training Program Expansion | Addresses specialized workforce scarcity that constrains treatment planning throughput across regional cancer centers. |
Research Approach
A spread of perspectives from radiation oncologists, hospital procurement committee members, biomedical physicists, and Ministry of Health program administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through Fonasa reimbursement filings, CE marking databases, and Chilean nuclear energy commission import records. Bottom-up equipment installation tracking and top-down health expenditure flows were triangulated against regional cancer incidence projections.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by equipment type, delivery mode, end-user institution, and regional health service jurisdiction. CAGRs derived from historical linear accelerator procurement cycles and anticipated cobalt-60 replacement waves. Forecast inputs incorporated Fonasa rate negotiation trajectories and Ministry of Health oncology infrastructure program capital allocations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by proton therapy specialists or adaptive software platforms would shift outcomes beyond modeled ranges. Cross-checking against hospital procurement database benchmarks and GPO contract disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Equine Operating Tables Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Europe Nuclear Medicine Equipment Market