
 Next Generation Centrifuge Market | 2026-2036
Next Generation Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Centrifuge Market Foresight
ISO 13485 certification for medical device quality management is rotating as the decisive qualification filter for centrifuge suppliers serving clinical diagnostics and blood banking segments. Eppendorf AG leverages its German engineering heritage and deep specialization in benchtop systems for molecular biology workflows. Danaher Corporation sustains competitive density through its life sciences platform strategy, integrating centrifugation with adjacent sample preparation technologies. Thermo Fisher Scientific dominates the North American installed base with extensive field service networks and refrigerated ultracentrifuge portfolios.
Next generation centrifuges employ rotor speeds exceeding 100,000 rpm with precise temperature control between -20°C and +40°C to protect thermolabile samples during separation protocols. Floor-standing units anchor revenue generation in high-throughput bioprocessing facilities where batch volumes and continuous flow demands justify capital-intensive installations. Ultracentrifuge technology captures premium margin pools in academic and pharmaceutical research settings where density gradient separations require extreme gravitational force. Continuous flow systems are extending adoption in industrial biotechnology for harvest clarification, displacing traditional depth filtration in mammalian cell culture downstream processing.
FDA 21 CFR Part 11 electronic records requirements and EU MDR conformity obligations are tightening validation documentation for centrifuges deployed in GMP-regulated environments. The EPA's energy efficiency directives are pressing manufacturers to redesign drive systems and refrigeration circuits for reduced power consumption. Laboratories and biomanufacturers must weigh total cost of ownership against throughput specifications when selecting between refrigerated and non-refrigerated platforms for their specific separation workflows.
Market Dynamics
Bioprocessing infrastructure expansion is concentrating procurement authority among contract development and manufacturing organizations, compressing vendor selection cycles and favoring centrifuge suppliers with integrated service capabilities.
Growth Catalysts
- Cell and gene therapy manufacturing:Viral vector purification workflows require ultracentrifuge systems with precise density gradient capabilities. CDMOs in the United States and Germany are scaling dedicated capacity.
- FDA 21 CFR Part 11:Electronic records and signatures mandates for GMP environments are disqualifying non-compliant equipment from clinical manufacturing sites. Validation documentation has become a primary selection criterion.
- Continuous bioprocessing:Perfusion cell culture systems are generating harvest volumes that exceed batch centrifuge throughput. Facilities are installing continuous flow disc-stack units for real-time clarification.
Market Restraints
- Refrigeration compressor supply:Specialized hermetic compressors for ultracentrifuge cooling circuits concentrate among Japanese and German component suppliers. Lead times have extended to twenty-six weeks.
- EU MDR conformity costs:In vitro diagnostic device reclassification is forcing benchtop centrifuge manufacturers to resubmit technical documentation. Small European OEMs lack resources for notified body engagement.
- Depth filtration substitution:Single-use filtration trains offer lower capital requirements for mammalian cell harvest at scales below two thousand liters. Centrifuge vendors must demonstrate total cost of ownership superiority.
Strategic Opportunities
- India biopharma manufacturing:The country's PLI scheme for active pharmaceutical ingredients is attracting multinational investment in bulk drug production. Local centrifuge assembly partnerships can circumvent import duty structures.
- Carbon fiber rotor materials:Composite engineering enables higher rotational speeds with reduced thermal mass. Integration with IoT vibration monitoring creates predictive maintenance service revenue streams.
- China NMPA harmonization:Mutual recognition agreements with FDA and EMA are accelerating approval timelines for imported analytical equipment. Multinational suppliers can leverage existing validation packages.
Industry Challenges
- Field service engineer scarcity:Ultracentrifuge maintenance requires specialized training in vacuum systems and drive electronics. OEMs compete for technicians with semiconductor equipment service providers.
- Legacy system integration:Biomanufacturing facilities operate mixed fleets of centrifuge generations spanning fifteen to twenty years. Data interoperability between analog-era units and modern LIMS platforms demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Centrifuge Market |
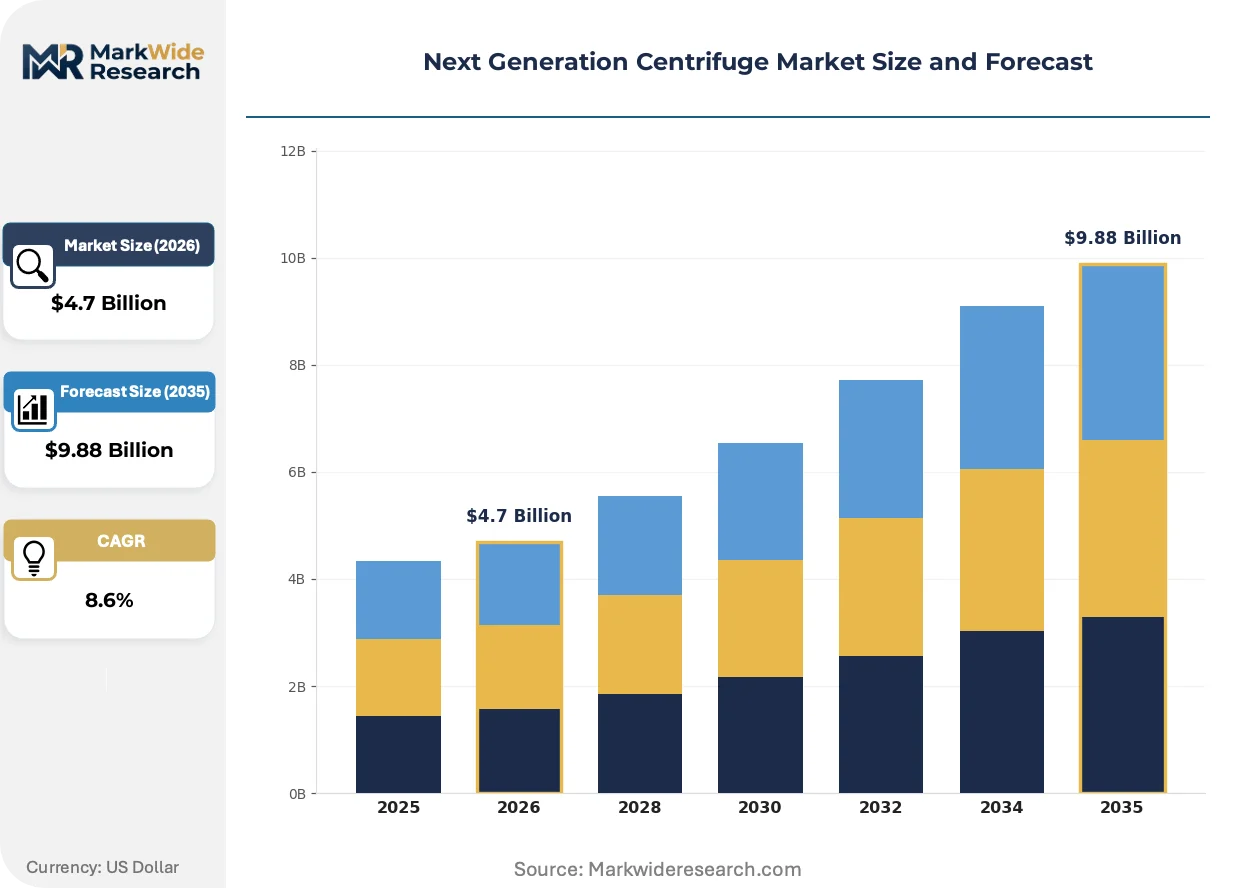
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor-Standing, Benchtop, Mini, High-Speed Technology: Refrigerated, Non-Refrigerated, Ultracentrifuge, Continuous Flow End User: Hospitals, Research Laboratories, Biotechnology Companies, Educational Institutions Application: Cell Separation, Protein Purification, Blood Component Separation, DNA Extraction |
| Companies Covered | FLSmidth A/S, Eppendorf AG, Alfa Laval, Danaher Corporation, Thermo Fisher Scientific Inc, GEA Group Aktiengesellschaft, SPX FLOW, Inc., Flottweg SE, ANDRITZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Centrifuge Market Shifts & Advancements
Centrifuge architecture is fragmenting into modular, application-specific configurations that sacrifice universal flexibility for targeted throughput optimization in high-value bioprocessing workflows.
Microcentrifuge technology is miniaturizing for point-of-care diagnostic applications. Portable units with lithium-ion power systems and touchscreen interfaces are entering emergency medicine and rural health networks in Brazil and Southeast Asia. These devices compress sample preparation from central laboratory workflows to bedside processing, reducing turnaround times for critical care decisions.
REACH restrictions on perfluorinated compounds are forcing refrigeration circuit redesigns across European-manufactured units. Manufacturers are substituting hydrofluoroolefin refrigerants with lower global warming potential, though thermal efficiency penalties require larger condenser surfaces. Premium refrigerated ultracentrifuge models for pharmaceutical R&D are absorbing these engineering costs first.
Service contract unbundling is disrupting traditional centrifuge procurement in North American academic core facilities. Institutions are separating equipment purchase from maintenance agreements, soliciting third-party service providers for routine rotor inspections and drive calibration. This pattern concentrates in budget-constrained public university systems where capital and operating budgets face distinct approval authorities.
Next Generation Centrifuge Market Segmentation
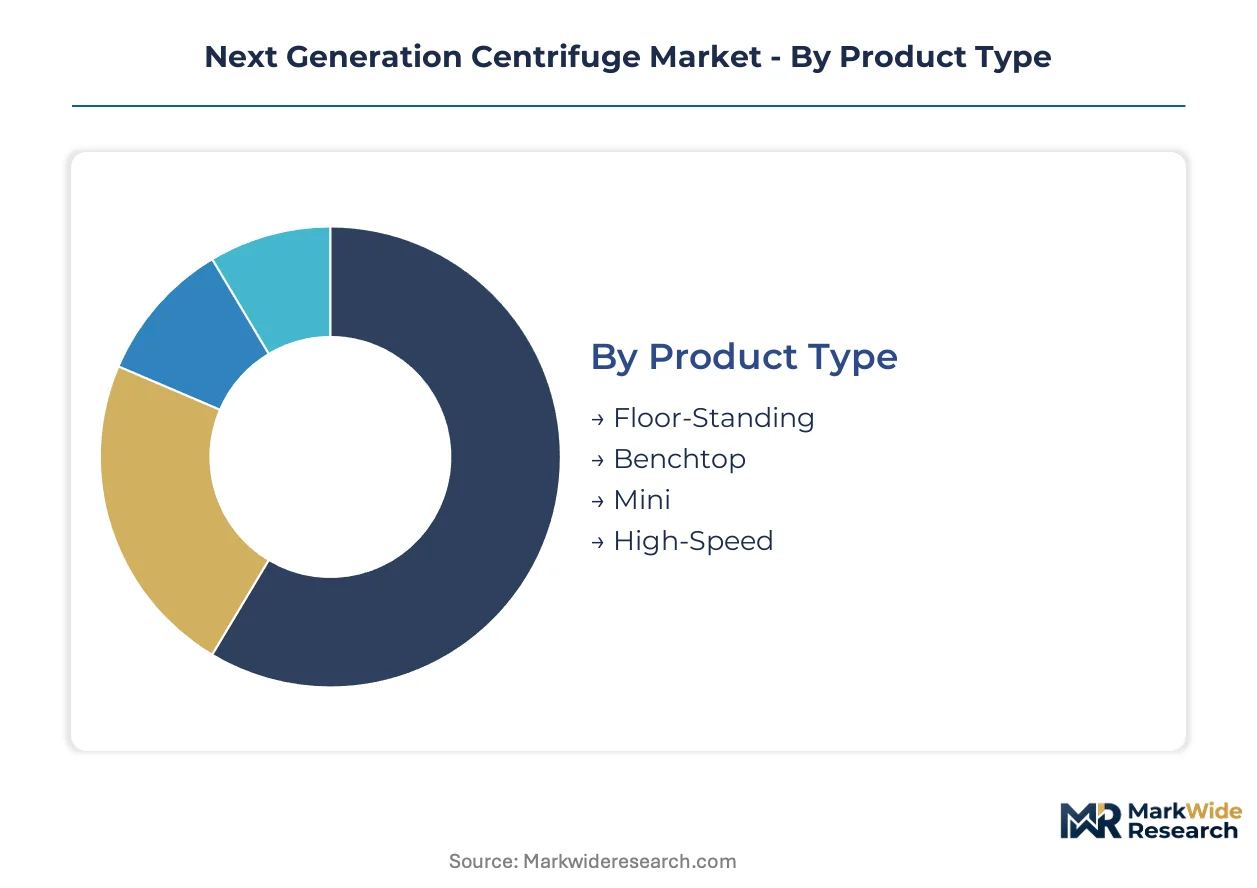
Centrifuge procurement patterns diverge sharply across product configurations and operational environments. Segmentation reveals how capital intensity, regulatory exposure, and workflow specificity shape vendor selection criteria and installed base composition.
Product Type:
Domestic demand concentrates in floor-standing and benchtop units for hospital and academic core facilities, while high-speed exports dominate pharmaceutical CDMO procurement in Germany and China.
- Floor-Standing:These units anchor high-throughput bioprocessing facilities with batch volumes exceeding one thousand liters. Demand concentrates among contract manufacturers in the United States and China where continuous flow integration justifies capital-intensive installations.
- Benchtop:Molecular biology workflows in academic and clinical diagnostics settings drive procurement. German engineering standards and ISO 13485 certification filter supplier qualification for European hospital laboratories.
- Mini:Point-of-care diagnostic applications in Brazil and Southeast Asia favor portable lithium-ion powered units with touchscreen interfaces for emergency medicine deployment.
- High-Speed:Viral vector purification for cell and gene therapy manufacturing requires precise temperature control between -20°C and +40°C. CDMOs in the United States scale dedicated capacity.
Floor-standing units command the established base. The steepest expansion runs through high-speed configurations.
Technology:
Cost tier stratification separates premium refrigerated ultracentrifuge systems from economy non-refrigerated platforms, with margin concentration in GMP-validated equipment.
- Refrigerated:Pharmaceutical R&D and blood banking segments require precise thermal protection for thermolabile samples. REACH restrictions on perfluorinated compounds force hydrofluoroolefin redesigns in European-manufactured units.
- Non-Refrigerated:Routine clinical diagnostics and educational laboratories favor lower total cost of ownership. Budget-constrained public university systems in the United States unbundle service contracts from equipment purchase.
- Ultracentrifuge:Density gradient separations for academic and pharmaceutical research capture premium margin pools. FDA 21 CFR Part 11 electronic records requirements tighten validation documentation for GMP-regulated environments.
- Continuous Flow:Perfusion cell culture harvest volumes exceed batch centrifuge throughput. Industrial biotechnology facilities install disc-stack units for real-time clarification, displacing depth filtration.
Refrigerated technology commands the established base. The steepest expansion runs through continuous flow systems.
End User:
Customer type determines procurement authority concentration, with biotechnology companies accelerating vendor selection cycles and hospitals demanding integrated service capabilities.
- Hospitals:Clinical diagnostics and blood banking workflows require ISO 13485 certified equipment with extensive field service networks. FDA device classification updates reshape compliance requirements for laboratory equipment procurement.
- Research Laboratories:Academic core facilities separate equipment purchase from maintenance agreements, soliciting third-party providers for rotor inspections and drive calibration in budget-constrained public university systems.
- Biotechnology Companies:Cell separation and viral vector purification workflows drive ultracentrifuge procurement. CDMOs compress vendor selection cycles and favor suppliers with integrated service capabilities.
- Educational Institutions:Undergraduate training laboratories prioritize economy non-refrigerated platforms with minimal validation documentation requirements.
Research laboratories command the established base. The steepest expansion runs through biotechnology companies.
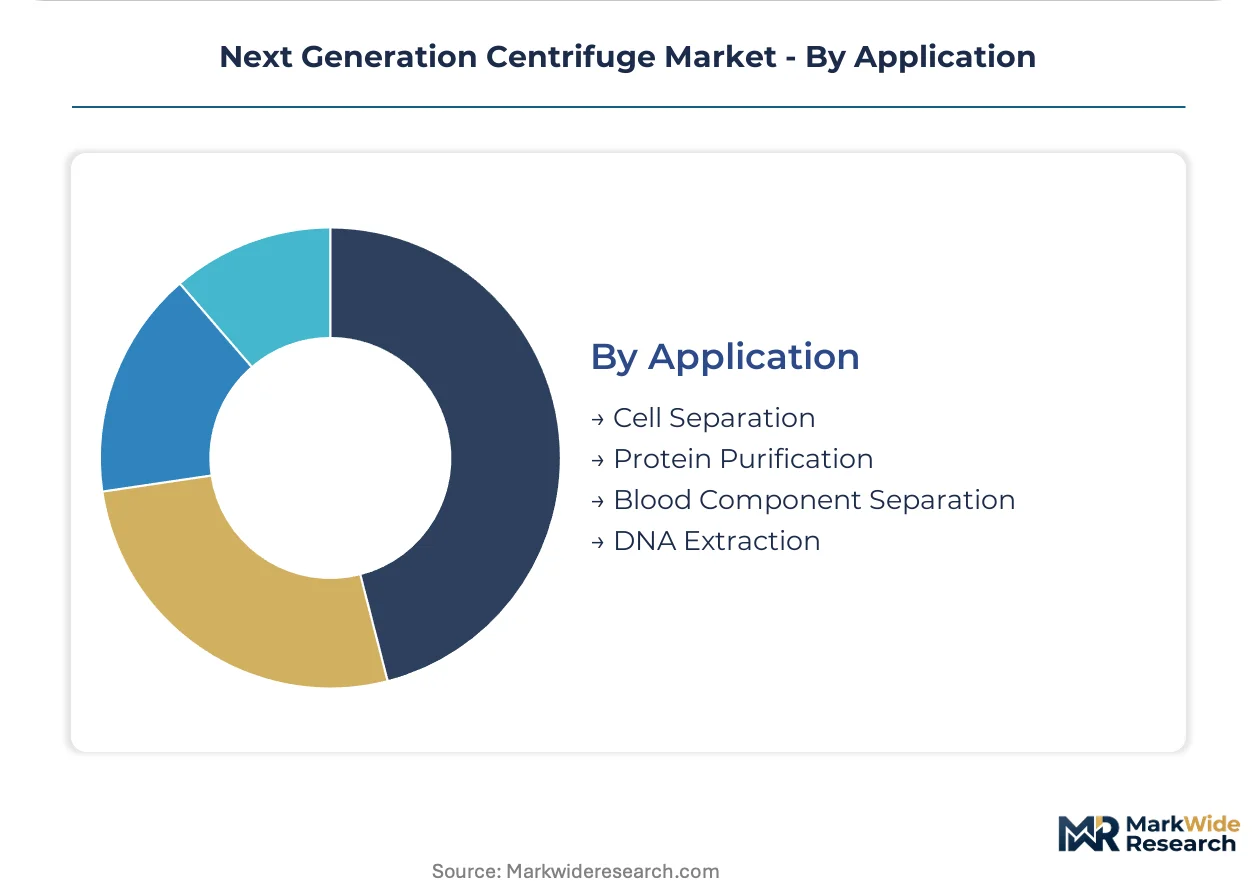
Application:
Volume concentration in cell separation reflects bioprocessing infrastructure expansion, while margin accrues to specialized protein purification workflows with GMP validation requirements.
- Cell Separation:Mammalian cell culture downstream processing and blood component preparation dominate throughput demand. Continuous flow systems extend adoption for harvest clarification in industrial biotechnology.
- Protein Purification:Density gradient ultracentrifugation for biopharmaceutical R&D commands premium pricing. EU MDR conformity obligations tighten validation documentation for GMP-regulated environments.
- Blood Component Separation:Hospital blood banking and clinical diagnostics require refrigerated units with precise temperature control. ISO 13485 certification filters supplier qualification.
- DNA Extraction:Molecular biology workflows in academic and diagnostic settings favor benchtop mini centrifuges with simplified operation protocols.
Cell separation commands the established base. The steepest expansion runs through protein purification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is attracting multinational investment in bulk drug production, creating localized procurement opportunities for centrifuge suppliers. Regulatory harmonization between China's NMPA and Western agencies accelerates equipment validation timelines. Bioprocessing infrastructure clusters in Germany, the United States, and China concentrate demand for high-throughput separation systems.
United States
Cell and gene therapy CDMOs in Massachusetts and North Carolina are scaling dedicated viral vector manufacturing capacity with ultracentrifuge installations. FDA 21 CFR Part 11 electronic records mandates disqualify non-compliant equipment from GMP clinical manufacturing sites. The Greater Boston biotech corridor anchors procurement authority among contract development organizations with compressed vendor selection cycles.
Germany
Pharmaceutical R&D spending in Baden-Württemberg and Bavaria drives premium refrigerated ultracentrifuge demand for density gradient separations. EU MDR conformity obligations force benchtop centrifuge manufacturers to resubmit technical documentation through notified bodies. The Rhine-Main bioprocessing cluster concentrates continuous flow disc-stack installations for mammalian cell culture harvest clarification.
China
NMPA harmonization with FDA and EMA enables multinational suppliers to leverage existing validation packages for imported analytical equipment. The country's dual carbon goals press manufacturers to redesign drive systems for reduced power consumption. Yangtze River Delta biopharma parks in Shanghai and Suzhou expand bioprocessing infrastructure with floor-standing unit procurement.
India
PLI scheme incentives for active pharmaceutical ingredient production attract multinational bulk drug manufacturing investment. CDSCO regulatory pathways for imported laboratory equipment create compliance documentation requirements for centrifuge suppliers. Hyderabad and Ahmedabad pharmaceutical clusters drive localized assembly partnerships to circumvent import duty structures on finished equipment.
Japan
Specialized hermetic compressor supply for ultracentrifuge cooling circuits concentrates among domestic component manufacturers with extended lead times. METI industrial policy supports precision engineering capabilities for carbon fiber rotor material development. Osaka and Tokyo academic research institutes maintain installed bases of high-speed units for protein purification workflows.
Next Generation Centrifuge Market Competitive Landscape
Player mix skews toward diversified life sciences conglomerates with integrated service capabilities and specialized German engineering firms with deep benchtop system expertise. Market structure exhibits tiered consolidation with premium ultracentrifuge segments concentrating among three global platforms and mid-market benchtop categories fragmenting across regional specialists. Dominant strategic archetypes include life sciences platform integrators, precision engineering specialists, and industrial process equipment conglomerates. Competitive moves center on service contract unbundling responses and carbon fiber rotor material integration with IoT monitoring systems.
Within the precision engineering specialist tier, Eppendorf AG exemplifies German heritage positioning in molecular biology workflows. Among diversified life sciences platforms, Danaher Corporation and Thermo Fisher Scientific occupy positions anchoring competitive density through integrated sample preparation technologies and extensive North American field service networks respectively. These three entities represent the strategic archetypes shaping vendor qualification filters for ISO 13485 certification and GMP validation documentation.
| Leading Market Players |
|---|
| FLSmidth A/S |
| Eppendorf AG |
| Alfa Laval |
| Danaher Corporation |
| Thermo Fisher Scientific Inc |
| GEA Group Aktiengesellschaft |
| SPX FLOW, Inc. |
| Flottweg SE |
| ANDRITZ |
| Others |
Supply & Pricing Matrix
Batch volume thresholds at bioprocessing facilities create scale economies that compress unit economics for floor-standing installations while elevating price floors for specialized ultracentrifuge configurations. This capacity-utilization dynamic concentrates supply authority among German and Japanese component specialists while forcing tiered pricing stratification across certification grades.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between premium refrigerated ultracentrifuge systems and economy benchtop units. Three-tier pricing structure across GMP-validated, clinical-grade, and educational platforms segments buyer pools, with biotechnology companies showing lowest price sensitivity due to viral vector manufacturing workflows. Pricing pressure stems from depth filtration substitution in mammalian cell harvest below two thousand liter scales. Public university systems exhibit highest price sensitivity, unbundling service contracts from equipment purchase to optimize capital budget utilization.
Supply Chain Analysis
Strategic stockpiling of hermetic refrigeration compressors dominates procurement behavior given twenty-six week lead times from Japanese and German suppliers. Component manufacturing concentrates in Germany, Japan, and China, with carbon fiber rotor materials drawing from METI-supported precision engineering capabilities. Supply chain risk centers on single-source vulnerability for specialized compressor circuits. Distribution runs through direct OEM channels for GMP-validated equipment and third-party laboratory distributors for benchtop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next generation centrifuge demand follows bioprocessing capital expenditure cycles, with cell and gene therapy manufacturing expansion providing cyclical recovery justification through viral vector purification capacity buildouts.
For Market Incumbents: Compound service revenue through IoT-enabled predictive maintenance platforms integrated with carbon fiber rotor monitoring systems. Deepen backward integration into compressor supply chains to mitigate Japanese supplier lead time volatility. Secure ISO 13485 certification maintenance as EU MDR conformity costs disqualify smaller European OEMs from hospital laboratory procurement.
For New Entrants and Emerging Players: Anchor in India's PLI scheme-driven bulk drug manufacturing clusters through localized assembly partnerships that circumvent import duty structures on finished equipment. Target point-of-care diagnostic applications in Brazil and Southeast Asia with lithium-ion powered mini centrifuge platforms. Pursue CDSCO regulatory pathway expertise as differentiated go-to-market capability for imported laboratory equipment compliance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision engineering specialists with installed base service contract penetration. Five-to-ten year viability favors suppliers with carbon fiber composite capabilities and GMP validation documentation expertise. Monitor NMPA-FDA harmonization progress as inflection indicator for multinational validation package leverage in China biopharma parks.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Rotor Integration | Enables higher rotational speeds with reduced thermal mass for density gradient separations. |
| IoT Predictive Maintenance Platform | Creates recurring service revenue streams through vibration monitoring of vacuum drive systems. |
| India Localized Assembly Partnership | Circumvents PLI scheme import duty structures for bulk drug manufacturing equipment procurement. |
| Continuous Flow Disc-Stack Deployment | Displaces depth filtration in perfusion cell culture harvest clarification workflows. |
| REACH-Compliant Refrigeration Redesign | Substitutes hydrofluoroolefin refrigerants to meet ECHA restrictions on perfluorinated compounds. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance requirements. Conversations with bioprocessing facility engineers, GMP validation specialists, hospital laboratory directors, and CDMO procurement managers informed operational workflow analysis. Secondary sources include FDA 21 CFR Part 11 guidance documents, EU MDR technical documentation requirements, EPA energy efficiency directives, and NMPA harmonization protocols. Bottom-up unit demand modeling triangulates against top-down bioprocessing capacity expansion estimates.
Sensitivity analysis around refrigeration compressor lead times and CDMO capital expenditure cycles shapes the analytical framework across the projection horizon. Segmentation dimensions span product configuration, temperature control technology, end-user procurement authority, and application-specific throughput requirements. CAGRs derive from installed base replacement cycles and bioprocessing infrastructure expansion trajectories. Forecast inputs incorporate viral vector manufacturing capacity buildouts and continuous flow adoption curves in mammalian cell culture downstream processing.
Material uncertainties — regulatory timeline shifts, supply chain disruption severity, substitution technology performance thresholds — sit outside the modeled envelope. Forecasts reflect assumptions regarding CDMO vendor consolidation patterns and REACH refrigerant phase-in schedules. Revision becomes warranted when compressor supplier lead time volatility or NMPA harmonization delays cross thresholds that alter capital equipment procurement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Tanning Units Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Autopsy Saw Market