
 Operating Table Market | 2026-2036
Operating Table Market Size, Share, and Industry Trends Forecast 2026-2036
Operating Table Market Analysis
Market Context
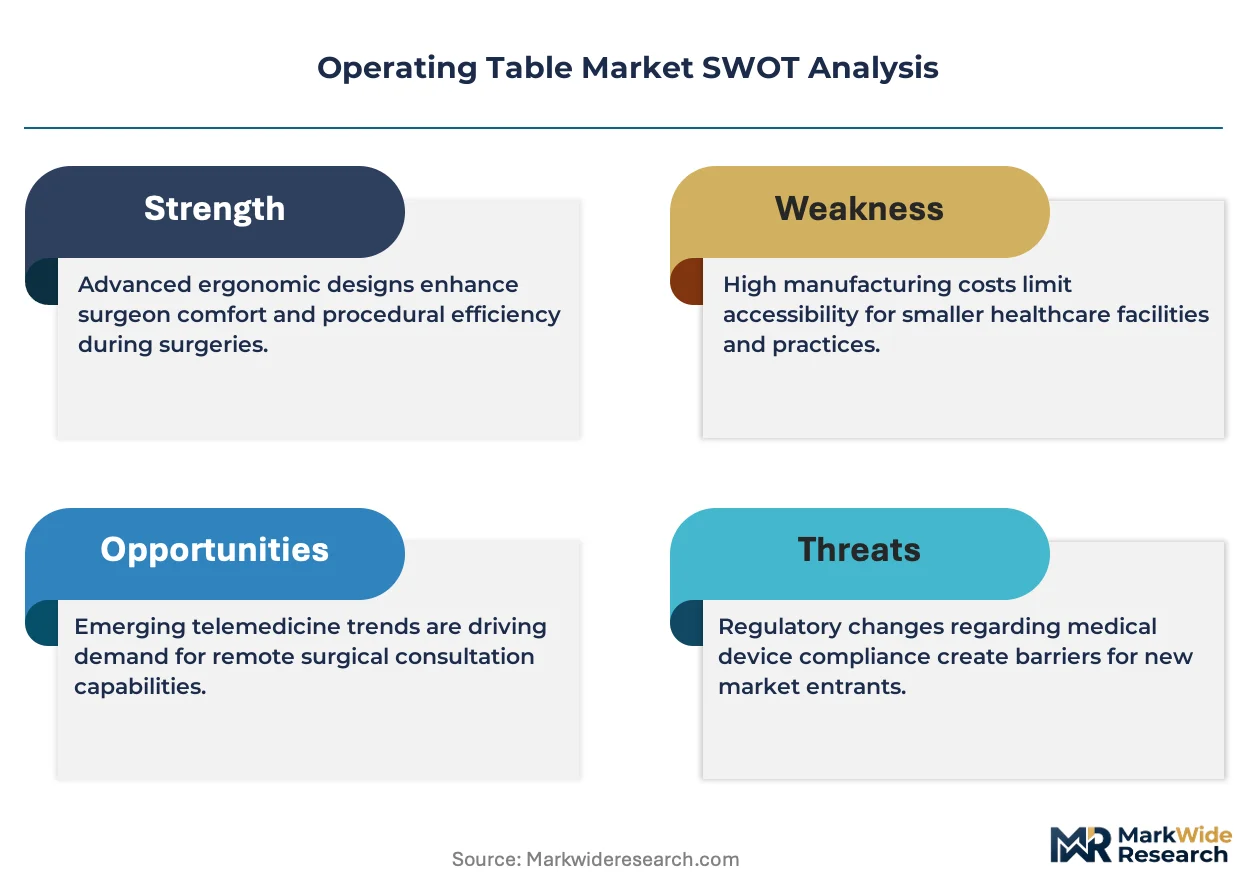
A shortage of certified biomedical technicians is redrawing how hospitals evaluate operating table vendors on service responsiveness and lifecycle support. Stryker leverages its extensive field engineering network to sustain long-term maintenance contracts with large health systems. Getinge anchors its competitive stance through backward integration into sterilization workflows that bundle table systems with perioperative equipment. Mizuho OSI specializes in spine and orthopedic positioning platforms that differentiate its portfolio from general-purpose competitors.
Technical Definition and Structural Segments
An operating table is a height-adjustable, articulating platform engineered to position patients during surgical procedures, typically supporting loads exceeding 225 kg while enabling Trendelenburg, reverse Trendelenburg, and lateral tilt configurations through electromechanical or hydraulic actuation systems. Its primary commercial purpose centers on optimizing surgical access, reducing staff physical strain, and integrating with fluoroscopy and navigation systems. Electric tables command the dominant share of product type revenue due to precision positioning demands in advanced surgical suites, while robotic technology represents the fastest-expanding segment as hospitals adopt integrated surgical ecosystems. General surgery applications generate the largest end-use volume, though orthopedic applications yield higher per-unit pricing due to specialized traction and imaging compatibility requirements.
Regulatory Frame and Outlook
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and market access costs for electromechanical surgical tables. IEC 60601-1 electrical safety standards and ISO 13485 quality management systems govern manufacturing consistency across international supply chains. Stakeholders must monitor how emerging cybersecurity frameworks for connected medical devices reshape validation requirements for network-enabled operating tables.
Market Dynamics
Ambulatory surgical centers are consolidating procurement authority into centralized supply chains, forcing manufacturers to reconfigure distribution networks around multi-site service contracts rather than single-hospital transactions.
Growth Catalysts
- EU MDR Class IIa Certification:Stricter electromechanical safety validation is accelerating replacement cycles for aging hydraulic tables across German and French hospital systems.
- Fluoroscopy Integration:Hybrid operating rooms in the United States are demanding carbon-fiber tabletops that enable real-time imaging without patient repositioning.
- Outpatient Procedure Volume Surge:Japan's aging demographic is expanding same-day surgery capacity, driving orders for compact powered tables with rapid turnover features.
Market Restraints
- Stainless Steel Price Volatility:Surgical-grade 316L stainless input costs fluctuate with nickel markets, compressing margins for mid-tier manufacturers dependent on commodity sourcing.
- Actuator Supply Concentration:Precision electromechanical linear actuators for table positioning concentrate among German and Swiss component suppliers, creating single-source vulnerability.
- Hydraulic Fluid Environmental Restrictions:REACH regulations on synthetic hydraulic fluids are phasing out legacy oil-based systems before electric alternatives achieve cost parity in budget segments.
Strategic Opportunities
- India's PLI Medical Devices Scheme:Domestic manufacturing incentives are opening import substitution pathways for multinational assembly operations targeting South Asian price points.
- AI-Assisted Positioning:Convergence of pressure-mapping sensors with machine learning algorithms enables automated anti-decubitus adjustment protocols in long-duration neurosurgery.
- Direct-to-Ambulatory Distribution:Bypassing traditional dealer networks through manufacturer-owned service hubs captures margin from high-volume ASC chains in Texas and Florida.
Industry Challenges
- Biomedical Technician Shortage:FDA-mandated preventive maintenance schedules exceed available certified field service capacity, extending equipment downtime at rural hospitals.
- Cybersecurity Validation Burden:Network-enabled tables requiring IEC 62304 software lifecycle documentation face 14-18 month clearance timelines that delay product launches.
Report Scope
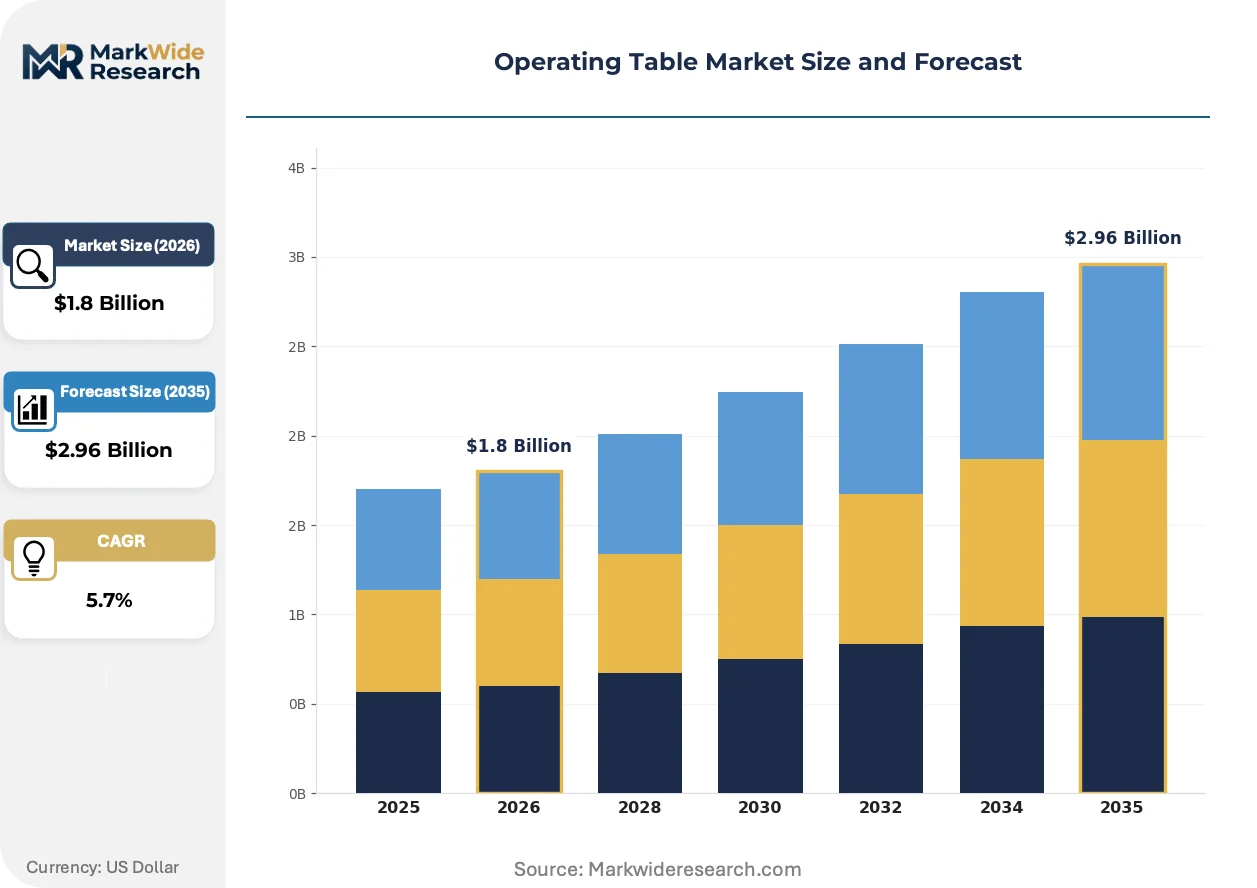
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operating Table Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Hydraulic, Accessories End User: Hospitals, Clinics, Surgical Centers, Ambulatory Care Application: Orthopedic, Cardiovascular, General Surgery, Gynecology Technology: Robotic, Modular, Traditional, Advanced Imaging |
| Companies Covered | Baxter, Skytron, STERIS Healthcare, medifa GmbH, ALVO Medical, Stryker, Mizuho OSI, Merivaara Corp, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operating Table Market Emerging Trajectories
Electromechanical control architectures are displacing hydraulic systems across all but the most price-sensitive procurement tiers, while connectivity requirements are embedding software validation into hardware development cycles.
Integrated pressure-sensing arrays embedded within tabletop surfaces are miniaturizing from discrete sensor nodes to continuous textile-based matrices. Academic medical centers in Massachusetts and California are piloting these systems for real-time tissue perfusion monitoring during cardiac procedures. This capability is compressing the boundary between patient positioning equipment and intraoperative monitoring devices, forcing regulatory reclassification discussions with FDA.
EU MDR's enhanced clinical evidence requirements for electromechanical surgical devices are extending technical file preparation timelines by eight to twelve months. Manufacturers are responding by front-loading post-market surveillance infrastructure before product launch rather than retrofitting compliance frameworks. German notified bodies are experiencing the most severe audit queue congestion, diverting new submissions to Dutch and Swedish conformity assessment organizations.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchase agreements, creating standalone multi-vendor maintenance pools. Third-party clinical engineering firms in Ontario and Michigan are capturing these contracts through specialized actuator refurbishment capabilities. This disintermediation is compressing manufacturer service margins while accelerating parts standardization pressure across competing OEM platforms.
Operating Table Market Segmentation
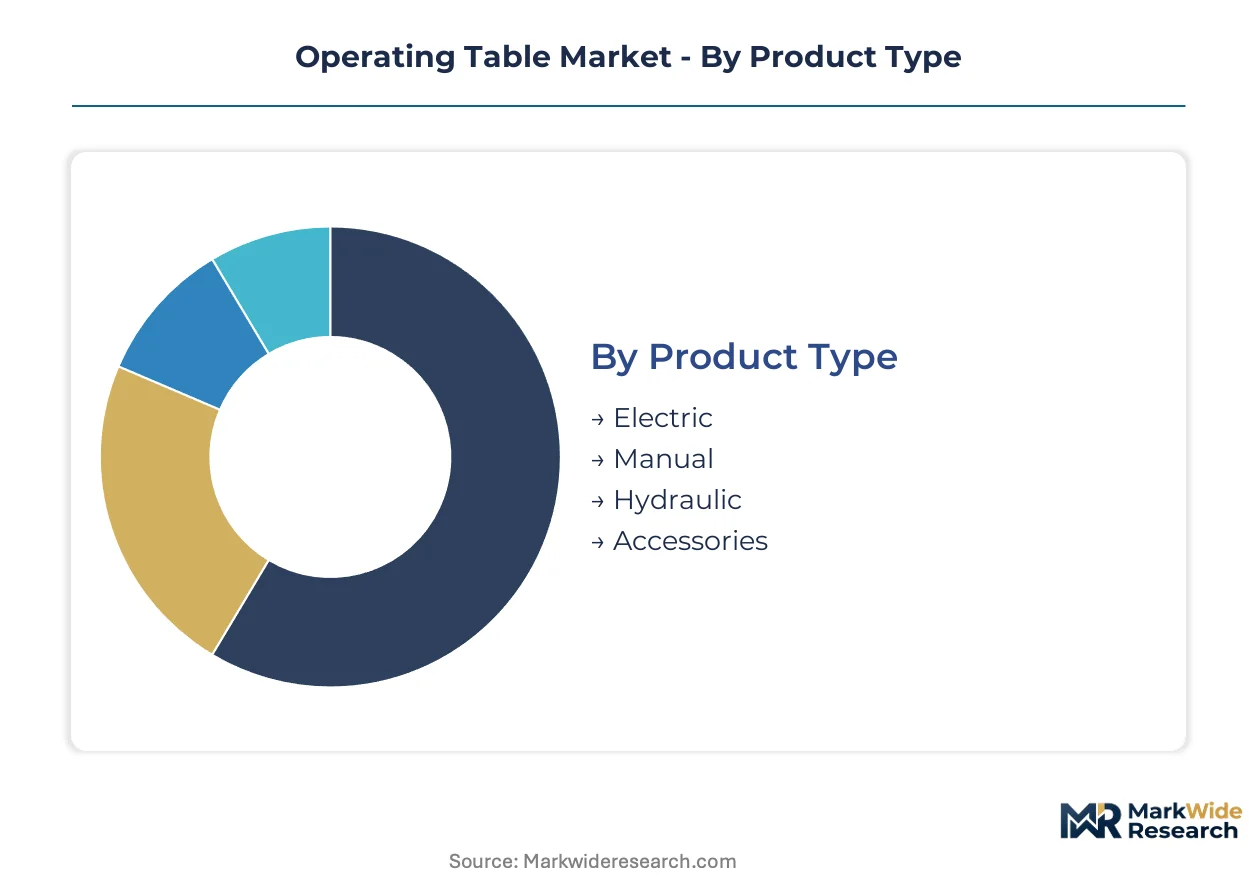
Operating table procurement decisions fragment across multiple technical and clinical dimensions. Electromechanical sophistication, surgical specialty requirements, and facility infrastructure capacity each reshape vendor positioning and pricing power.
Product Type:
Manual tables face the most acute substitution pressure as powered alternatives achieve cost parity in mid-tier budgets, forcing legacy manufacturers to defend position through extreme durability claims and low-maintenance positioning.
- Electric:Electromechanical actuation enables precision Trendelenburg, reverse Trendelenburg, and lateral tilt configurations through sealed motor assemblies. German and French hospital systems are accelerating replacement of hydraulic fleets to meet EU MDR Class IIa validation timelines, prioritizing carbon-fiber tabletops for fluoroscopy compatibility.
- Manual:Mechanical crank or hydraulic pedal systems dominate rural clinics and budget-constrained facilities in South Asia. India's PLI Medical Devices Scheme is drawing multinational assembly operations toward domestic production of entry-level powered units, compressing manual table viability windows.
- Hydraulic:Oil-based actuation systems retain presence in legacy surgical suites with extended depreciation schedules.
- Accessories:Traction frames, arm boards, and head supports extend platform utility across procedure types.
Electric systems retain volume leadership; robotic-ready modular configurations hold the steepest expansion curve.
End User:
Facility infrastructure maturity determines specification tiers, with capital availability and procedure throughput as the primary sorting mechanisms.
- Hospitals:Academic medical centers in Massachusetts and California pilot pressure-sensing textile matrices for cardiac perfusion monitoring, blurring regulatory boundaries between positioning equipment and intraoperative monitoring devices. These institutions demand integrated surgical ecosystems with navigation compatibility.
- Surgical Centers:Texas and Florida ASC chains are consolidating procurement into centralized supply chains, forcing manufacturers to reconfigure distribution around multi-site service contracts. Compact powered tables with rapid turnover features dominate new construction.
- Clinics:Limited procedure volumes favor manual or basic electric configurations with minimal maintenance requirements.
- Ambulatory Care:Same-day discharge protocols prioritize patient transfer efficiency and staff ergonomic safety.
Hospitals command the highest per-unit pricing; surgical centers are gaining share fastest through outpatient volume migration.
Application:
Specialized positioning requirements create margin stratification across surgical disciplines, with imaging compatibility and traction mechanics as the key value drivers.
- Orthopedic:Traction frames, fracture reduction capabilities, and radiolucent tabletops for intraoperative imaging support premium positioning. These systems yield higher per-unit pricing than general-purpose alternatives due to mechanical complexity and durability demands under load stress.
- Cardiovascular:Hybrid operating rooms require carbon-fiber surfaces enabling real-time fluoroscopy without patient repositioning. Academic centers are embedding pressure-mapping arrays for tissue perfusion validation during extended procedures.
- General Surgery:Standard articulation ranges and load ratings satisfy the majority of abdominal and thoracic procedures.
- Gynecology:Lithotomy positioning and stirrup integration address specialty access requirements.
General surgery generates the largest unit volume; orthopedic applications sustain the highest average selling prices.
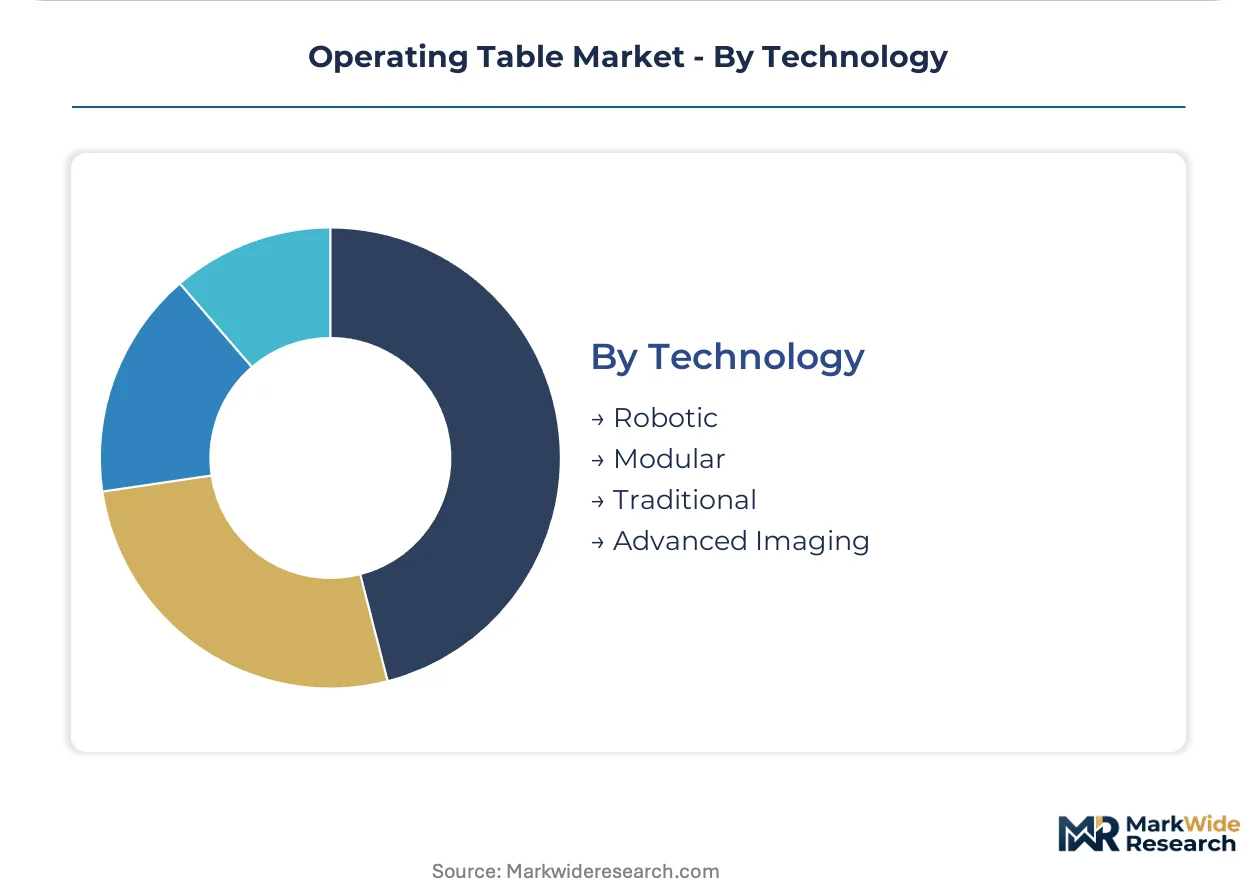
Technology:
Software validation burdens are reshaping competitive entry costs, with network-enabled systems facing extended clearance timelines that favor incumbent engineering resources.
- Robotic:Integrated surgical ecosystems with automated positioning and instrument synchronization represent the fastest-expanding segment as hospitals adopt da Vinci and competing platforms. IEC 62304 software lifecycle documentation requirements impose 14-18 month FDA clearance timelines that delay product launches for new entrants.
- Advanced Imaging:Carbon-fiber tabletops with embedded sensor arrays enable real-time navigation and perfusion monitoring. FDA is evaluating regulatory reclassification discussions as these capabilities compress boundaries between device categories.
- Modular:Configurable subsystems allow platform extension across procedure types without full replacement.
- Traditional:Fixed-configuration systems serve price-sensitive procurement tiers with minimal connectivity requirements.
Traditional configurations retain installed base dominance; robotic integration is climbing the fastest amid surgical ecosystem consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the dominant geography, while EU MDR Class IIa certification timelines and China's NMPA registration requirements reshape competitive positioning across major surgical infrastructure markets.
United States
Hybrid operating rooms in Massachusetts and California drive carbon-fiber tabletop demand for real-time fluoroscopy integration. FDA cybersecurity frameworks for connected medical devices extend validation timelines for network-enabled systems. The Greater Boston academic medical cluster pilots pressure-sensing textile matrices for cardiac perfusion monitoring during extended procedures.
Germany
German hospital systems accelerate replacement of hydraulic fleets to meet EU MDR Class IIa electromechanical safety validation deadlines. REACH regulations on synthetic hydraulic fluids phase out legacy oil-based systems before electric alternatives achieve cost parity. The Baden-Württemberg industrial corridor concentrates precision actuator manufacturing among specialized component suppliers.
China
Domestic health systems modernize aging surgical infrastructure amid expanding tertiary hospital construction in provincial capitals. NMPA registration requirements for Class II medical devices tighten quality management system audits for electromechanical equipment. The Yangtze River Delta manufacturing cluster attracts multinational assembly operations targeting price-optimized powered table production.
Japan
Japan's aging demographic expands same-day surgery capacity, driving procurement of compact powered tables with rapid turnover features. METI industrial policy supports domestic medical device manufacturing through targeted R&D subsidies. The Kanto region around Tokyo concentrates demand from high-throughput academic medical centers upgrading hybrid surgical suites.
India
India's PLI Medical Devices Scheme draws multinational assembly operations toward domestic production of entry-level powered units. CDSCO medical device rules align with international standards for electromechanical safety certification. The Maharashtra-Gujarat industrial corridor hosts emerging manufacturing hubs targeting South Asian price points with localized supply chains.
Operating Table Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around electromechanical platform providers and surgical ecosystem integrators. Tier-one participants compete through captive service networks and backward integration into sterilization workflows, while mid-tier specialists defend position through orthopedic positioning expertise and regional manufacturing scale. Strategic archetypes include full-spectrum surgical ecosystem providers, specialty positioning platform developers, and regional cost-optimized fabricators. Dominant competitive moves encompass multi-site service contract consolidation for ambulatory surgical center chains and front-loaded post-market surveillance infrastructure to compress EU MDR clearance timelines.
Among the integrated leaders, Stryker leverages extensive field engineering networks to sustain long-term maintenance contracts with large health systems, while Getinge anchors its stance through backward integration into sterilization workflows that bundle table systems with perioperative equipment. Within the specialty positioning tier, Mizuho OSI occupies a position exemplifying focused orthopedic and spine platform differentiation from general-purpose competitors.
| Leading Market Players |
|---|
| Baxter |
| Skytron |
| STERIS Healthcare |
| medifa GmbH |
| ALVO Medical |
| Stryker |
| Mizuho OSI |
| Merivaara Corp |
| Getinge |
| Others |
Supply Flow & Price Mechanics
EU MDR Class IIa certification gates both supplier qualification and price stratification, as notified body audit queues in Germany and the Netherlands delay market entry for uncertified manufacturers while accelerating replacement premiums for validated electromechanical systems. Buyers in France and the United States face extended lead times for carbon-fiber tabletop configurations, compressing negotiation leverage for rural hospitals against integrated service bundling from incumbent vendors.
Pricing Analysis
Geographic price spreads of 40-60 percent separate German hospital system contracts from South Asian clinic procurement, with EU MDR compliance costs and carbon-fiber imaging compatibility as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels sorts academic medical centers, regional hospitals, and budget-constrained facilities into distinct specification bands. Cost compression in the manual and hydraulic tiers is intensifying because India's PLI Medical Devices Scheme draws multinational assembly toward domestic production of entry-level powered alternatives. Ambulatory surgical centers in Texas and Florida exhibit the highest price sensitivity due to centralized procurement authority, while Massachusetts academic clusters prioritize imaging integration over unit cost.
Supply Chain Analysis
Inventory buffers for precision electromechanical linear actuators stretch to 16-20 weeks as German and Swiss component suppliers concentrate production of sealed motor assemblies for table positioning systems. Manufacturing draws from stainless steel 316L feedstock, carbon-fiber composite tabletops, and specialized hydraulic fluid formulations now restricted under REACH regulations. Single-source vulnerability in actuator supply creates procurement risk for mid-tier manufacturers lacking dual-qualified component vendors. Distribution runs through manufacturer-owned service hubs for ASC chains and traditional dealer networks for independent hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric table architectures face substitution pressure from robotic-integrated surgical ecosystems as hospitals consolidate around da Vinci and competing platforms, forcing legacy electromechanical vendors to defend installed base through service contract captivity and modular upgrade pathways.
For Market Incumbents: Compound field engineering network density to lock in multi-site maintenance contracts with ASC chains, while accelerating backward integration into sterilization workflows that bundle table systems with perioperative equipment. The robotic ecosystem threat demands preemptive software companion development for navigation compatibility. EU MDR post-market surveillance infrastructure is the priority lever for compressing clearance timelines against audit queue congestion. For New Entrants and Emerging Players: Lead with India's PLI Medical Devices Scheme to establish domestic assembly operations targeting South Asian price points, bypassing tariff exposure on fully-imported systems. The most penetrable white space sits in compact powered tables for Japan's expanding same-day surgery capacity, where rapid turnover features and ergonomic transfer design address aging demographic demand. A direct-to-ambulatory distribution model through manufacturer-owned service hubs captures margin from high-volume ASC procurement consolidation. For Investors and Strategic Acquirers: EU MDR Class IIa implementation reshapes the acquisition landscape toward targets with front-loaded clinical evidence packages and notified body relationships already established. Long-term viability over the next decade hinges on software validation capabilities for network-enabled systems facing IEC 62304 documentation burdens. Watch for FDA cybersecurity framework finalization as the signal indicating which portfolio companies possess compliant development infrastructure versus stranded legacy architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Front-loaded post-market surveillance infrastructure compresses German notified body audit queue delays. |
| Hospital System Partnership | Multi-site service contracts with Texas and Florida ASC chains capture procurement consolidation margin. |
| Software Companion Development | Navigation compatibility modules defend electromechanical base against robotic ecosystem substitution. |
| Backward Integration into Sterilization | Perioperative equipment bundling replicates Getinge's workflow-anchored competitive positioning. |
| Geographic Manufacturing Footprint | India PLI assembly operations unlock South Asian price points with localized stainless steel sourcing. |
Methodological Framework
The analysis maps electromechanical, hydraulic, manual, and robotic-ready table configurations, each validated through biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and ASC supply chain executives. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical file databases, hospital procurement records, and customs trade data for surgical-grade stainless steel and carbon-fiber composite inputs. Bottom-up unit demand modeling triangulated against top-down surgical procedure volume projections.
Consistency checks validated volume and value outputs against independent benchmarks from surgical infrastructure investment tracking and medical device registration databases across the projection horizon. Segmentation dimensions modeled include product type sophistication, end-user facility tier, application specialty requirements, and regional regulatory cluster. CAGRs derived from procedure volume elasticity, replacement cycle compression from EU MDR deadlines, and technology substitution curves for robotic integration. Forecast inputs incorporated fluoroscopy adoption rates in hybrid operating rooms and ASC construction permits in high-growth states.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR audit capacity expansion, stable nickel pricing for stainless steel feedstock, or continued outpatient volume migration would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline execution and component supply continuity. Cybersecurity validation burden escalation or biomedical technician shortage deepening represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Cath Lab Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Hospital-at-Home Equipment Rental Market