
 Medical X-Ray Generators Market | 2026-2036
Medical X-Ray Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Medical X-Ray Generators Market Intelligence
East Asian high-voltage component manufacturing is rebalancing as regional producers scale capacity for medical-grade power electronics. Siemens Healthineers leverages its integrated imaging platform to anchor premium digital radiography installations across European hospital networks. Spellman High Voltage Electronics Corporation specializes in custom high-voltage power supplies for OEM imaging equipment, sustaining its position through deep R&D partnerships. DRGEM Corporation competes aggressively on cost-engineered fixed generators for mid-tier diagnostic centers in emerging markets.
Medical x-ray generators are precision power conversion systems that transform line voltage into stabilized high-voltage DC outputs, typically ranging from 40 kV to 150 kV, to drive x-ray tubes for diagnostic imaging. These units incorporate high-frequency inverter circuits, filament transformers, and microprocessor-controlled feedback loops to ensure precise dose delivery and image consistency across clinical procedures. Digital radiography technology leads product segmentation due to superior workflow efficiency and lower per-exposure operational costs compared to analog alternatives. Portable generator demand is accelerating fastest among ambulatory surgical centers and mobile screening programs where equipment mobility directly expands patient access. Fixed installations still dominate hospital radiology departments where throughput volume justifies permanent infrastructure investment.
FDA 21 CFR Part 1020 governs x-ray system performance standards including beam quality and exposure reproducibility in the United States, while IEC 60601-1-3 and IEC 60601-2-54 establish international safety and dose documentation requirements for radiographic and fluoroscopic equipment. MDR compliance in Europe now demands enhanced clinical evidence and post-market surveillance for generator components classified as Class IIa or higher medical devices. Stakeholders must monitor evolving AI-integrated imaging workflows that will reshape generator interface requirements and procurement criteria as radiology departments prioritize seamless connectivity over standalone hardware specifications.
Market Dynamics
High-frequency inverter architectures are displacing conventional line-frequency transformer designs as FDA 21 CFR Part 1020 and IEC 60601-1-3 dose optimization mandates harden. This technical transition concentrates procurement power among hospital networks capable of absorbing capital-intensive digital radiography upgrades.
Growth Catalysts
- MDR Compliance Deadlines:European Class IIa device reclassification is forcing generator component upgrades across installed bases, creating replacement pull through 2028.
- China Hospital Expansion:Provincial healthcare infrastructure programs in Sichuan and Guangdong are funding fixed generator installations for tier-two diagnostic centers.
- Mobile Screening Programs:Portable generator demand from rural health initiatives in India and Brazil is accelerating equipment procurement cycles.
Market Restraints
- High-Voltage Component Concentration:Specialized capacitor and semiconductor sourcing depends on East Asian foundry capacity, exposing OEMs to supply disruption.
- Extended IEC 60601-2-54 Certification Timelines:Revised dose documentation requirements are stretching product approval cycles by eight to fourteen months.
- Refurbished System Competition:Secondary market digital radiography systems from decommissioned hospital networks are capturing mid-tier diagnostic center budgets.
Strategic Opportunities
- AI-Integrated Workflow Interfaces:Generator connectivity protocols that interface with radiology AI platforms are creating differentiation in premium hospital procurement.
- Ambulatory Surgical Center Penetration:United States outpatient facility expansion is opening demand for compact, high-frequency portable units.
- German Energy Efficiency Incentives:Federal hospital modernization funds are prioritizing low-consumption high-frequency architectures over legacy transformer designs.
Industry Challenges
- Power Electronics Talent Scarcity:Medical-grade high-voltage engineering expertise concentrates among a narrow cohort of specialized designers in Germany and Japan.
- Legacy Analog System Integration:Hybrid environments requiring generator compatibility with aging film-based equipment complicate hospital upgrade planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical X-Ray Generators Market |
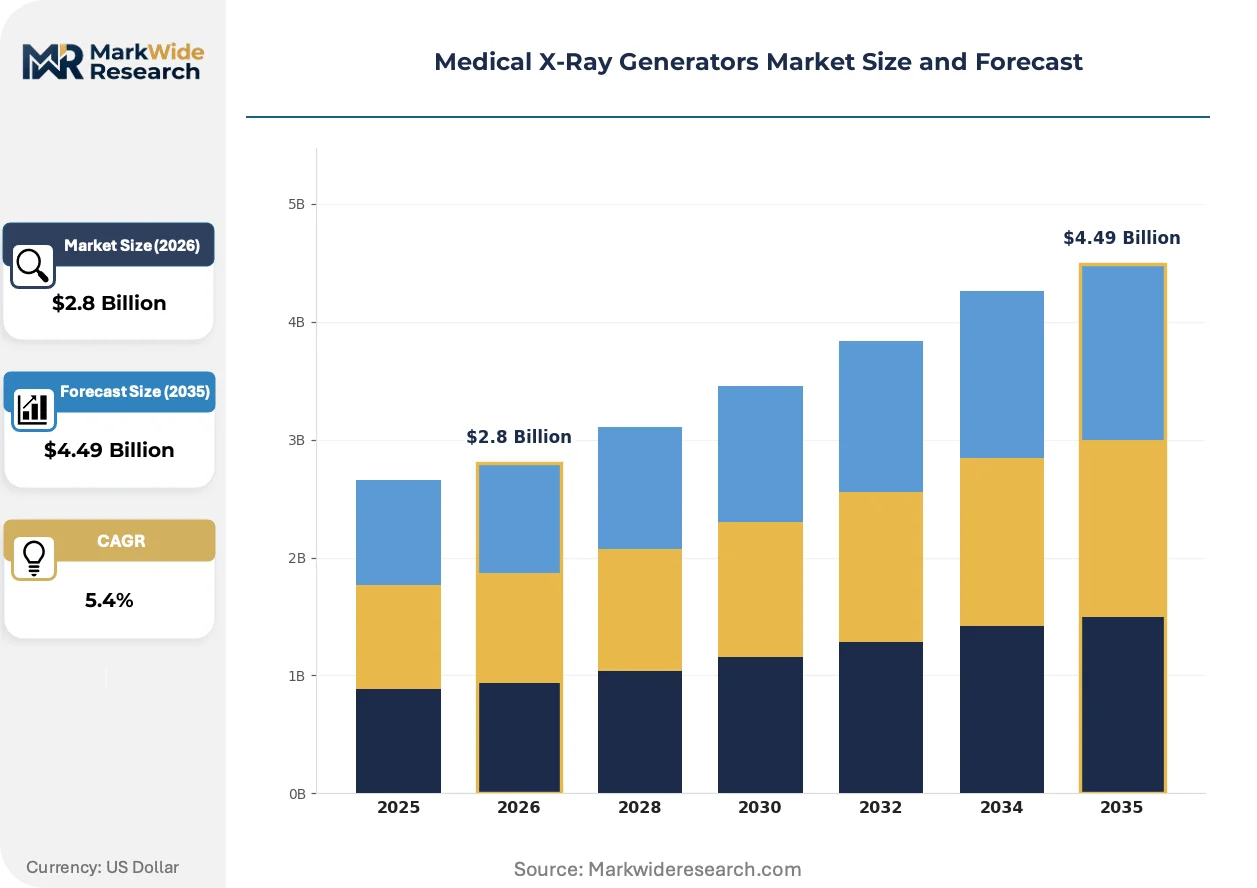
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Digital, Analog End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Conventional, Computed Radiography, Digital Radiography, Fluoroscopy Application: Orthopedics, Oncology, Dentistry, Cardiovascular |
| Companies Covered | Spellman High Voltage Electronics Corporation, Siemens Healthineers, Communications & Power Industries LLC, DRGEM Corporation, Innomed Medical Zrt., DMS Group LLC, ECORAY, Josef Betschart AG, Poskom Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical X-Ray Generators Market Strategic Shifts & Innovations
Digital radiography workflows are compressing exposure times and demanding generator architectures capable of sub-millisecond pulse precision. This technical pressure is redrawing competitive boundaries between integrated imaging platform vendors and specialized power supply manufacturers.
Solid-state high-voltage switching using silicon carbide semiconductors is decentralizing generator thermal management and enabling compact portable form factors. Mobile screening operators in India and Brazil are adopting these units for rapid deployment. The technology is decentralizing service models away from centralized hospital engineering departments toward distributed field technician networks.
MDR post-market surveillance requirements are mandating real-time dose traceability from generator to PACS archive. European notified bodies are rejecting legacy analog documentation systems. Radiology departments in Germany, France, and Italy are prioritizing generators with embedded data logging to satisfy clinical evidence demands.
Hospital procurement committees are unbundling generator purchases from full-system radiography contracts, creating direct OEM negotiation channels. Independent service organizations are capturing maintenance contracts previously held by integrated platform vendors. This pattern is most visible in United States academic medical centers and German hospital networks with dedicated biomedical engineering divisions.
Medical X-Ray Generators Market Segmentation
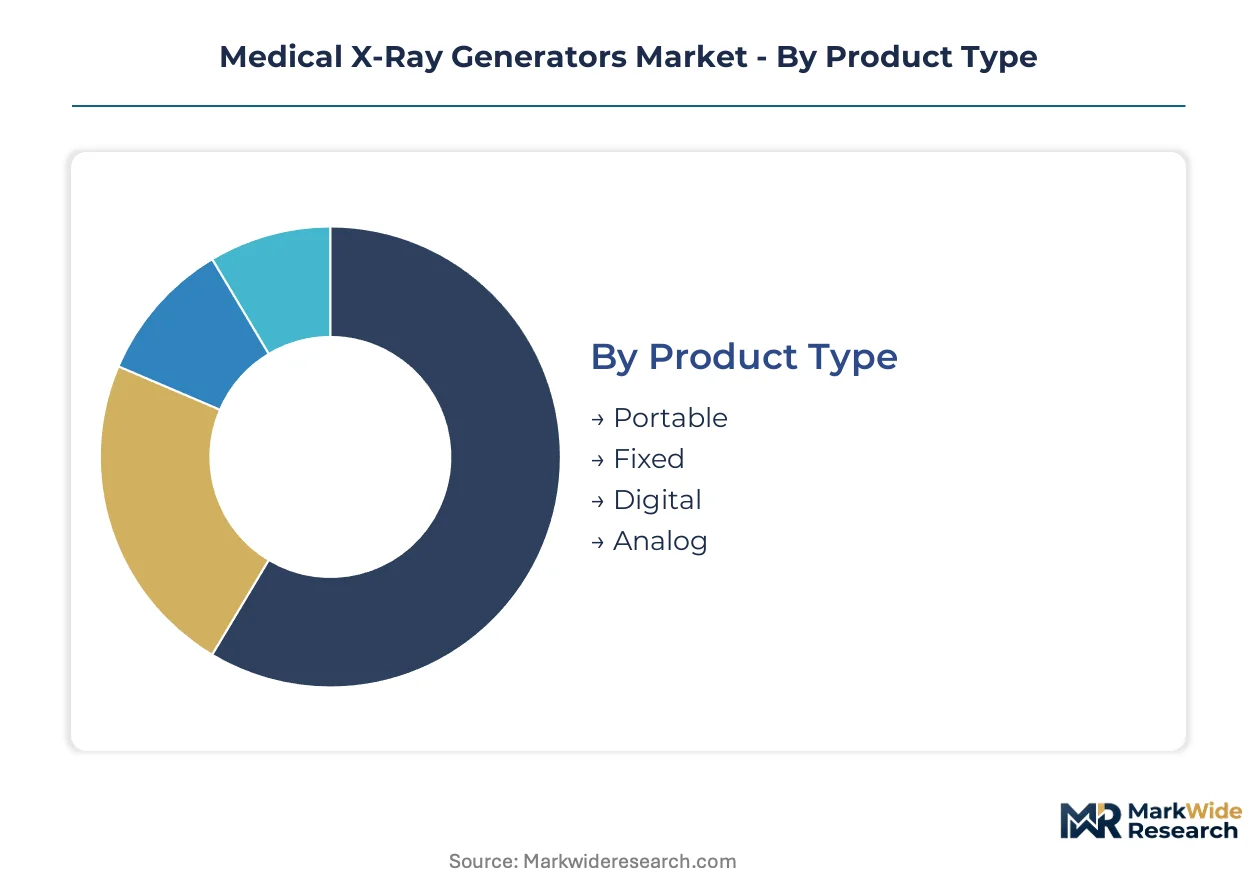
Segmentation in medical x-ray generators reveals how capital allocation, regulatory compliance, and clinical workflow requirements split procurement decisions across healthcare networks. Hospital engineering departments weigh permanent infrastructure against mobile flexibility when matching generator specifications to imaging volumes.
Product Type:
Capital-intensity varies sharply across product configurations, with fixed installations demanding substantial electrical infrastructure and shielding investments while portable units trade upfront cost against service complexity.
- Fixed:Stationary high-frequency generators integrate with permanent radiography suites, requiring dedicated three-phase power feeds and lead-lined vault construction. German hospital networks prioritize these units for high-throughput departments where Siemens Healthineers anchors integrated platform contracts. Capital recovery depends on procedure volume thresholds that tier-two diagnostic centers in China struggle to justify.
- Digital:Solid-state switching architectures with embedded dose logging satisfy MDR post-market surveillance mandates across European installations. United States academic medical centers unbundle these generators from full-system contracts to negotiate directly with OEM power supply specialists. Workflow integration with PACS archives drives procurement criteria more than standalone hardware specifications.
- Portable:Compact high-frequency units with battery-backed inverters enable deployment to ambulatory surgical centers and mobile screening programs. Demand concentrates in rural health initiatives across India and Brazil where equipment mobility expands patient access beyond fixed infrastructure.
- Analog:Line-frequency transformer designs persist in hybrid environments requiring compatibility with aging film-based equipment. Refurbished systems from decommissioned hospital networks capture budget-constrained mid-tier diagnostic centers.
Fixed generators absorb the bulk of installed capacity; portable units are expanding most quickly through mobile screening procurement.
End User:
Procurement authority concentrates differently across customer types, with hospital networks leveraging scale for integrated platform contracts while independent diagnostic centers prioritize cost-engineered component sourcing.
- Hospitals:Radiology departments with dedicated biomedical engineering divisions unbundle generator purchases to capture maintenance contract flexibility. German hospital networks and United States academic medical centers lead this pattern, negotiating directly with Spellman High Voltage Electronics for custom power supply configurations. Throughput volume justifies permanent infrastructure investment and premium high-frequency architectures.
- Diagnostic Centers:Mid-tier facilities in emerging markets face capital constraints that DRGEM Corporation targets with cost-engineered fixed generators. Tier-two centers in Sichuan and Guangdong provinces access provincial healthcare infrastructure funding for digital radiography upgrades. These customers prioritize equipment cost against service network density.
- Clinics:Outpatient facilities in the United States ambulatory surgical center expansion favor compact portable units with rapid deployment capability. Procurement committees prioritize workflow efficiency over maximum imaging specifications.
- Research Institutions:Specialized imaging protocols demand custom high-voltage power supplies with extended kV ranges and pulse precision beyond standard clinical configurations. Deep R&D partnerships with specialized manufacturers sustain this niche demand.
Hospitals command the largest share of generator procurement value; diagnostic centers in emerging markets are climbing the fastest as infrastructure funding expands.
Technology:
Regulatory mandates on dose optimization and documentation are accelerating displacement of legacy architectures, with high-frequency inverter designs capturing procurement preference despite higher upfront capital requirements.
- Digital Radiography:Sub-millisecond pulse precision and embedded data logging satisfy FDA 21 CFR Part 1020 exposure reproducibility standards and MDR clinical evidence requirements. Siemens Healthineers leverages its integrated imaging platform to anchor premium installations across European hospital networks. Solid-state silicon carbide switching enables thermal management improvements that decentralize service models.
- Fluoroscopy:Continuous x-ray output capabilities for interventional procedures demand specialized high-voltage stability and extended duty cycles. IEC 60601-2-54 certification timelines stretch product approval cycles for manufacturers targeting this segment.
- Computed Radiography:Phosphor plate-based imaging workflows persist in budget-constrained environments transitioning from analog film. Hybrid procurement patterns emerge where generators must interface with both legacy and digital detector systems.
- Conventional:Line-frequency transformer designs face obsolescence pressure from tightening IEC 60601-1-3 dose optimization mandates. Refurbishment and secondary market activity concentrates in regions with extended legacy equipment replacement cycles.
Digital Radiography holds the dominant installed base; Fluoroscopy is gaining share fastest through interventional cardiology and oncology procedure expansion.
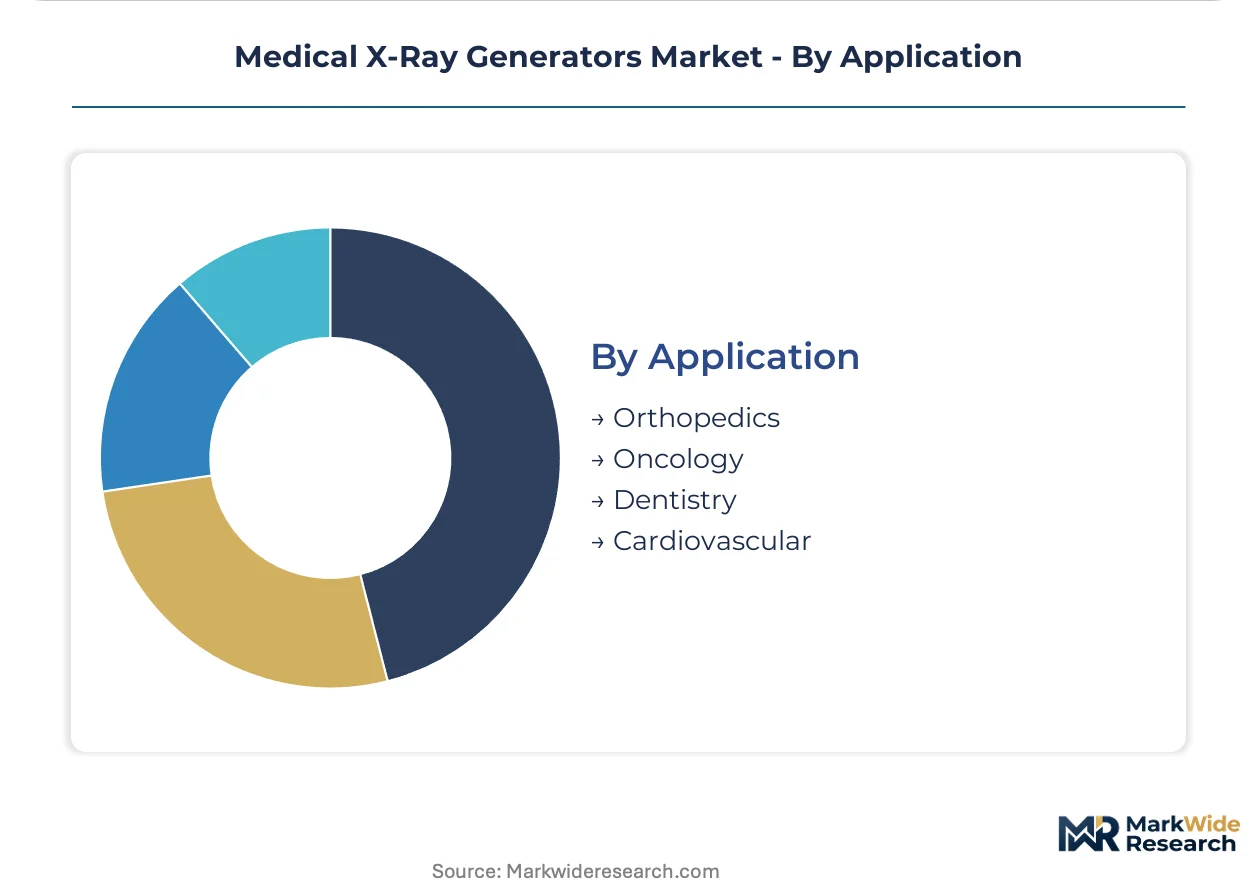
Application:
Clinical imaging requirements dictate generator specification priorities, with orthopedic and cardiovascular applications driving divergent technical demands on kV range stability and exposure timing precision.
- Orthopedics:Weight-bearing extremity imaging and long-length spine studies require precise kV modulation across broad anatomical ranges. Digital radiography generators with automated exposure control dominate hospital radiology department procurement for this high-volume application.
- Cardiovascular:Interventional fluoroscopy demands continuous output stability and rapid kV switching for cardiac catheterization procedures. High-frequency inverter architectures with advanced thermal management capture premium procurement in specialized cardiac centers.
- Oncology:Image-guided radiation therapy and staging protocols require integration with linear accelerator and CT simulation workflows. Generator connectivity protocols that interface with radiology AI platforms create differentiation in comprehensive cancer center procurement.
- Dentistry:Intraoral and panoramic imaging operates at lower kV ranges with compact form factor constraints. Cost-engineered fixed generators from regional manufacturers compete aggressively in this high-unit-volume, lower-price-point segment.
Orthopedics accounts for the greatest generator deployment volume; Cardiovascular is expanding most steeply through interventional procedure growth and specialized center investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian capacitor and semiconductor foundry capacity anchors generator manufacturing geography, while procurement concentrates in healthcare networks with capital-intensive modernization cycles.
United States
FDA 21 CFR Part 1020 dose optimization mandates accelerate hospital procurement of high-frequency inverter architectures. Ambulatory surgical center expansion drives portable generator demand across outpatient networks. Boston and Minneapolis biomedical engineering clusters concentrate service technician training for distributed field support models.
Germany
Federal hospital modernization funds prioritize energy-efficient high-frequency generators over legacy transformer designs. MDR Class IIa device reclassification forces component upgrades across installed bases through 2028. Bavarian and Baden-Württemberg hospital networks unbundle generator purchases to negotiate directly with specialized OEM power supply manufacturers.
China
Provincial healthcare infrastructure programs in Sichuan and Guangdong fund fixed generator installations for tier-two diagnostic centers. NMPA medical device registration timelines compress for domestic manufacturers with established quality management systems. Shanghai and Shenzhen electronics manufacturing clusters scale capacity for medical-grade high-voltage power electronics.
India
Rural health initiatives accelerate portable generator procurement for mobile screening programs expanding patient access beyond fixed infrastructure. CDSCO medical device rules harmonization streamlines import pathways for high-frequency architectures. Bangalore and Hyderabad diagnostic center networks prioritize cost-engineered equipment against constrained capital budgets.
Brazil
ANVISA medical device registration requirements extend certification timelines for imported high-voltage components. Mobile screening operators adopt silicon carbide switching units for rapid deployment to underserved regions. São Paulo and Rio de Janeiro hospital procurement committees evaluate refurbished digital radiography systems against premium new equipment.
Medical X-Ray Generators Market Key Industry Players
Global majors compete with regional champions across integrated imaging platforms versus specialized power supply manufacturing. Siemens Healthineers anchors premium hospital network contracts through bundled radiography system offerings. Three strategic archetypes dominate: integrated imaging platform vendors, specialized high-voltage power supply OEMs, and cost-engineered fixed generator manufacturers. Dominant competitive moves include unbundling generator purchases from full-system contracts and capturing independent service organization maintenance agreements previously held by integrated vendors.
Among specialized high-voltage power supply manufacturers, Spellman High Voltage Electronics Corporation exemplifies the deep R&D partnership archetype, while DRGEM Corporation occupies a position within cost-engineered fixed generator production for emerging market diagnostic centers. Siemens Healthineers represents the integrated platform vendor tier, anchoring premium installations through bundled radiography system contracts across European and North American hospital networks. These three company types illustrate how procurement committee unbundling and direct OEM negotiation channels reshape competitive positioning.
| Leading Market Players |
|---|
| Spellman High Voltage Electronics Corporation |
| Siemens Healthineers |
| Communications & Power Industries LLC |
| DRGEM Corporation |
| Innomed Medical Zrt. |
| DMS Group LLC |
| ECORAY |
| Josef Betschart AG |
| Poskom Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Backward integration into high-voltage component manufacturing anchors both supply security and pricing power for leading OEMs, as East Asian foundry capacity constraints force hospital procurement committees toward premium-tier suppliers with captive semiconductor sourcing. This structural positioning separates integrated imaging platform vendors from specialized power supply manufacturers competing on unbundled generator contracts.
Pricing Analysis
Warranty and service bundling separates premium procurement from cost-engineered alternatives, with Siemens Healthineers anchoring integrated platform contracts through multi-year maintenance agreements while DRGEM Corporation competes on unbundled hardware pricing for emerging market diagnostic centers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 21 CFR Part 1020 and MDR Class IIa compliance commanding substantial premiums. Cost compression in mid-tier fixed generators is intensifying because refurbished digital radiography systems from decommissioned hospital networks capture budget-constrained buyers. Tier-two diagnostic centers in Sichuan and Guangdong provinces exhibit highest price sensitivity, whereas German hospital networks with dedicated biomedical engineering divisions prioritize performance specifications over upfront capital outlay.
Supply Chain Analysis
Domestic-content mandates in China's NMPA medical device registration pathway are reshaping sourcing patterns, accelerating Shanghai and Shenzhen manufacturing clusters toward medical-grade high-voltage power electronics capacity. East Asian capacitor and semiconductor production draws from Taiwan, South Korea, and Japan, with specialized silicon carbide switching components resting on single-source vulnerability from concentrated foundry output. Distribution runs through integrated imaging platform vendors for premium hospital networks, while independent service organizations capture aftermarket service contracts previously held by bundled suppliers. Tariff exposure on imported high-voltage components stretches ANVISA registration timelines for Brazilian mobile screening operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical x-ray generator supply is tightening around East Asian high-voltage component foundry capacity, with specialized semiconductor sourcing bottlenecks propping pricing power for manufacturers with backward-integrated supply positions.
For Market Incumbents: Lock in captive supply agreements for silicon carbide semiconductors and high-voltage capacitors before East Asian foundry allocation tightens further. Defend against unbundling pressure from United States academic medical centers and German hospital networks by embedding AI-integrated workflow interfaces that raise switching costs. Prioritize MDR post-market surveillance compliance investments to capture European replacement cycles through 2028. For New Entrants and Emerging Players: Rural health initiative procurement managers in India and Brazil represent the most penetrable buyer archetype, as mobile screening program expansion outpaces established service network coverage. Target compact portable generator segments where equipment mobility commands premium pricing against fixed installation alternatives. Pursue CDSCO and ANVISA regulatory pathway efficiency as a go-to-market angle, compressing import timelines that disadvantage established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized high-voltage power supply manufacturers with deep R&D partnerships and custom configuration capabilities. Five-to-ten-year viability favors OEMs with demonstrated IEC 60601-2-54 certification track records and hospital direct-negotiation relationships. Monitor AI-integrated imaging workflow adoption rates as the inflection signal for generator interface requirement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | Class IIa device reclassification forces generator upgrades across European installed bases. |
| Silicon Carbide Switching Adoption | Solid-state thermal management enables compact portable form factors for mobile screening. |
| AI Workflow Interface Development | Radiology department prioritization of PACS connectivity reshapes procurement criteria. |
| Independent Service Organization Expansion | Maintenance contract unbundling from integrated vendors captures recurring revenue streams. |
| Provincial Hospital Network Partnership | Sichuan and Guangdong infrastructure funding opens tier-two diagnostic center demand. |
Research Approach
Independent corroboration across hospital procurement committee interviews, biomedical engineering director consultations, and GPO contracts manager surveys underwrites the qualitative findings in this study. Primary fieldwork with high-voltage power supply OEM technical directors, radiology department heads, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, IEC standard documentation, NMPA registration databases, and hospital capital expenditure disclosures. Bottom-up generator shipment analysis and top-down healthcare infrastructure spending triangulation anchored segmentation-level estimates.
Rate-of-change decomposition across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from procedure volume growth, replacement cycle timing, and capital expenditure elasticity modeling. Forecast inputs incorporated provincial healthcare infrastructure program announcements, ambulatory surgical center expansion trajectories, and mobile screening deployment schedules.
Revisions become necessary when East Asian semiconductor foundry capacity allocation shifts, MDR notified body interpretation changes, or AI-integrated imaging workflow standardization accelerates beyond modeled adoption curves. Forecasts reflect documented assumptions regarding regulatory timeline stability and hospital capital budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Birthing Beds Market