
 Patient Lifts Market | 2026-2036
Patient Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Lifts Market Analytics
Hospital procurement channels for patient lifts is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialized durable medical equipment distributors. Arjo controls premium ceiling lift installations across Nordic health systems. Stryker leverages its bed-integrated lift portfolio to anchor acute care contracts. Invacare Corporation competes through home care channel specialization and Medicare reimbursement navigation.
Patient lifts are motorized or manually operated transfer devices designed to move individuals with limited mobility between surfaces, typically employing hydraulic pistons, electric actuators, or overhead track systems with rated load capacities from 300 to 600 pounds. Their primary commercial purpose is reducing caregiver injury incidence while enabling safe patient handling in clinical and residential settings. Electric lifts lead revenue contribution due to higher unit pricing and institutional preference, while smart lift technology with integrated scale and position sensors represents the fastest-expanding margin pool. Ceiling lifts dominate retrofit-intensive skilled nursing facilities where spatial optimization governs capital planning.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for patient lift manufacturers. OSHA safe patient handling standards and ISO 10535 sling testing protocols further constrain design choices and supplier qualification. Stakeholders must monitor reimbursement code revisions and emerging smart lift interoperability standards as decisive variables for portfolio allocation and geographic prioritization.
Market Dynamics
Home care agencies are consolidating equipment procurement around aging-in-place mandates while FDA and EU MDR sling integrity requirements compress product development cycles for manufacturers.
Growth Catalysts
- OSHA Safe Patient Handling Standards:US acute care facilities face mandated injury reduction targets, forcing capital allocation toward motorized transfer equipment with documented load-bearing verification.
- Japan's Post-Acute Care Infrastructure:METI-funded facility modernization programs prioritize ceiling lift retrofits in skilled nursing environments where spatial constraints dominate capital planning.
- Smart Sensor Integration:Position tracking and integrated scale systems enable real-time patient weight monitoring, reducing manual documentation burden in bariatric care workflows.
Market Restraints
- Steel and Aluminum Input Volatility:Load-bearing frame fabrication depends on commodity metals whose price swings compress margin predictability for hydraulic and electric lift manufacturers.
- EU MDR Technical Documentation Burden:Sling classification as Class I medical devices extends conformity assessment timelines, delaying market access for iterative product improvements.
- Manual Lift Substitution in Price-Sensitive Segments:Hydraulic patient lifts retain cost advantage in emerging markets where labor arbitrage outweighs caregiver injury liability exposure.
Strategic Opportunities
- German Ambulatory Care Expansion:Outpatient rehabilitation facility construction under statutory health insurance reform creates demand for portable electric lifts with rapid deployment capability.
- Telehealth-Integrated Remote Monitoring:Convergence of lift usage data with electronic health records enables predictive maintenance contracts and outcome-based reimbursement navigation.
- Direct-to-Consumer Channel Development:Medicare Advantage supplemental benefit expansion allows bypass of traditional durable medical equipment distributors for residential ceiling lift installations.
Industry Challenges
- Biomechanical Engineer Talent Scarcity:Safe patient handling protocol design requires specialized ergonomics expertise that outpaces vocational training program output in key manufacturing regions.
- Legacy Bed System Interoperability:Integration of standalone lift units with proprietary Stryker and Hillrom bed control architectures demands costly adapter development and certification retesting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Lifts Market |
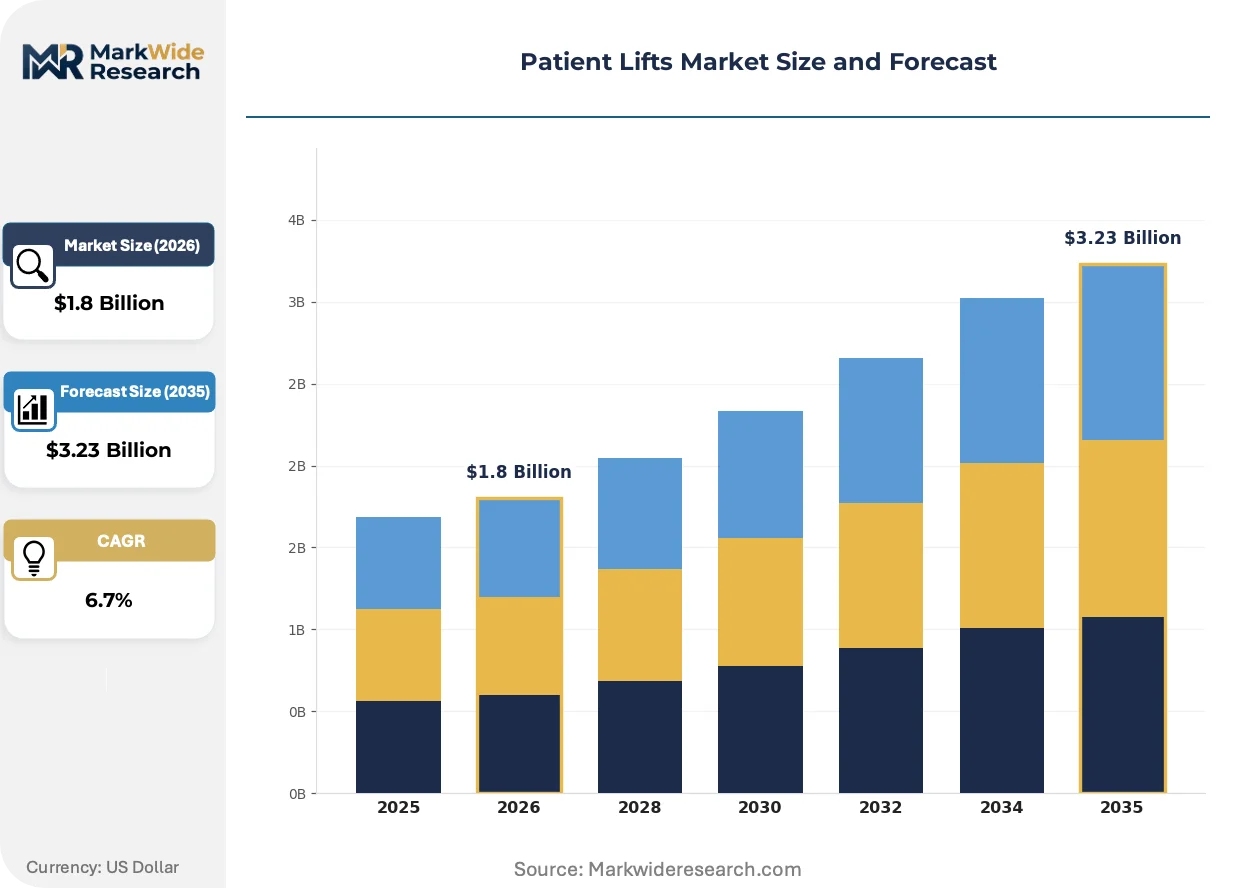
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Lifts, Electric Lifts, Ceiling Lifts, Sit-to-Stand Lifts End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Technology: Manual, Automatic, Smart Lifts, Modular Systems Weight Capacity: 300 lbs, 400 lbs, 600 lbs, Others |
| Companies Covered | GF Health Products, Hill-Rom (Baxter), Invacare Corporation, Etac AB, Handicare, Arjo, Joerns Healthcare, Drive DeVilbiss Healthcare, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Lifts Market Evolving Landscape
Sensor-enabled lift systems are compressing the service model from equipment sale to continuous monitoring subscription, while regulatory documentation requirements reshape R&D resource allocation across manufacturing footprints.
Lithium-ion battery packs with integrated charge-state telemetry are rendering obsolete tethered electric lifts that require proximity to wall outlets. Skilled nursing facilities in Germany and Japan are deploying these units at replacement cycle acceleration, enabling room-to-room mobility without infrastructure modification. The technology is rendering obsolete the spatial planning constraints that previously governed fixed lift placement decisions.
EU MDR Article 10 technical documentation obligations now mandate clinical evaluation reports for sling accessories previously exempt under the Medical Devices Directive. Manufacturers must maintain post-market surveillance systems with periodic safety update reports, extending product manager workload per SKU. Sling suppliers with legacy ISO 10535 certifications face the steepest compliance adaptation costs.
Group purchasing organization leverage is eroding as health systems consolidate direct manufacturer relationships for ceiling lift fleet standardization. IDN procurement teams in the United States now negotiate enterprise-wide service agreements spanning installation, preventive maintenance, and sling replacement inventory. This concentration is most visible in multi-site post-acute chains seeking uniform training protocols across state-licensed facilities.
Patient Lifts Market Segmentation
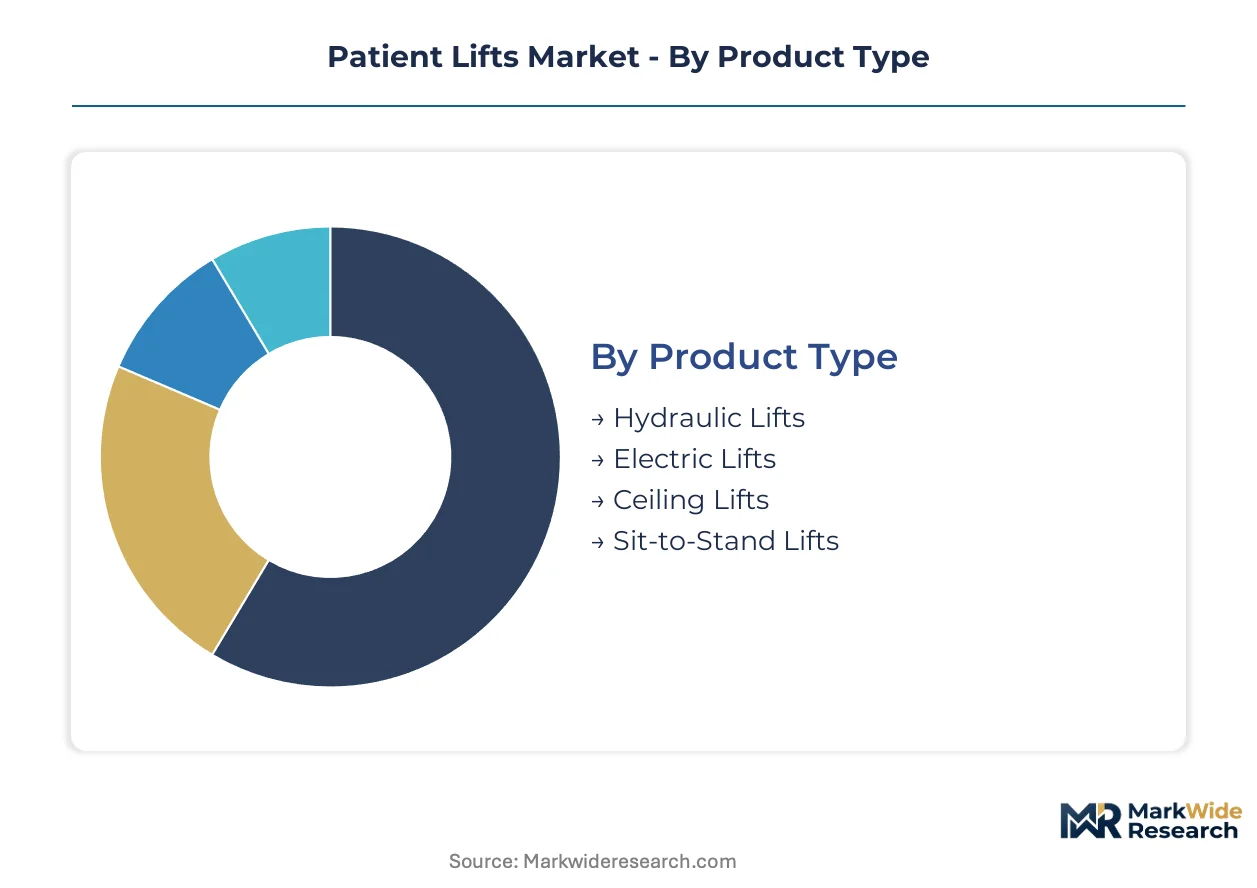
Patient lift manufacturers configure service networks and spare parts logistics differently across product architectures. Segmentation reveals where preventive maintenance contracts concentrate and which installation types demand specialized technical labor pools.
Product Type:
After-sales-service intensity varies sharply across lift architectures, with ceiling-mounted systems requiring structural engineering validation and electric units demanding battery replacement programs.
- Electric Lifts:Motorized base units with rechargeable power systems dominate institutional procurement channels. Hospital systems in the United States specify these for bariatric wards where load-bearing verification exceeds 450 pounds.
- Ceiling Lifts:Overhead track installations optimize spatial constraints in retrofit-intensive skilled nursing facilities. METI-funded modernization programs in Japan accelerate replacement cycles for tethered systems.
- Hydraulic Lifts:Manual pump mechanisms retain cost advantage in price-sensitive procurement environments.
- Sit-to-Stand Lifts:Ambulatory support devices target rehabilitation workflows with partial weight-bearing protocols.
Electric lifts hold the largest share; momentum sits with ceiling lift retrofits.
End User:
Channel economics diverge between capital-intensive facility installations and residential reimbursement navigation.
- Hospitals:Acute care systems negotiate enterprise-wide fleet standardization with embedded preventive maintenance. OSHA safe patient handling mandates force capital allocation toward motorized transfer equipment.
- Home Care:Aging-in-place policy expansion drives direct-to-consumer channel development. Medicare Advantage supplemental benefits now cover residential ceiling lift installations.
- Nursing Homes:Multi-site post-acute chains seek uniform training protocols across state-licensed facilities.
- Rehabilitation Centers:Outpatient construction under German statutory health insurance reform creates demand for portable deployment.
Hospitals command the highest service contract values; home care is expanding most quickly.
Technology:
Sensor integration is compressing equipment margins into continuous monitoring subscriptions.
- Smart Lifts:Position tracking and integrated scale systems enable real-time patient weight monitoring. Bariatric care workflows in the United States reduce manual documentation burden through automated data capture.
- Automatic Lifts:Programmable height and angle settings standardize transfer protocols across caregiver shifts.
- Manual Lifts:Basic mechanical operation persists where labor arbitrage outweighs injury liability exposure.
- Modular Systems:Interchangeable sling and frame configurations accommodate diverse patient mobility profiles.
Smart lifts claim the steepest expansion trajectory; automatic systems anchor volume.
Weight Capacity:
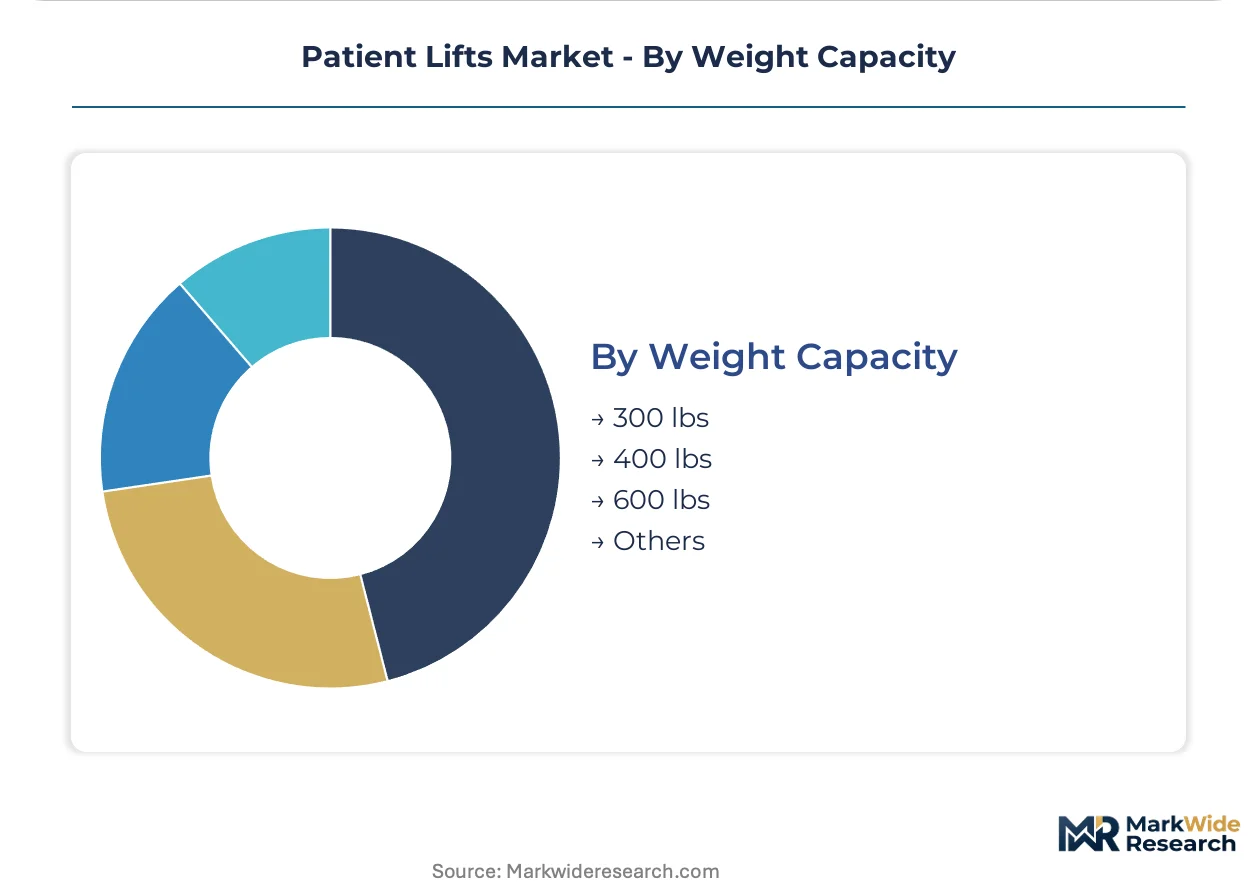
Frame fabrication specifications determine steel and aluminum input exposure for manufacturers.
- 600 lbs:Reinforced structural engineering addresses bariatric patient populations. FDA 510(k) clearance requirements elevate documentation burden for load-bearing verification protocols.
- 400 lbs:Standard institutional specification balances versatility against capital cost.
- 300 lbs:Residential and ambulatory applications prioritize maneuverability over maximum rating.
- Others:Pediatric and specialty configurations serve niche clinical requirements.
600-pound capacity commands premium pricing; 400-pound specification drives unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium ceiling lift installations in Sweden command pricing multiples unavailable to equivalent specifications in India, where hydraulic manual systems dominate procurement channels. This asymmetry reflects divergent regulatory enforcement intensity and reimbursement infrastructure maturity rather than manufacturing cost differentials alone.
United States
OSHA safe patient handling mandates force capital allocation toward motorized transfer equipment in acute care systems. FDA 510(k) clearance requirements elevate documentation burden for load-bearing verification protocols. Hospital procurement in Texas and Florida concentrates around enterprise-wide fleet standardization with embedded preventive maintenance contracts.
Germany
Outpatient rehabilitation facility construction under statutory health insurance reform creates demand for portable electric lifts. EU MDR technical documentation obligations extend conformity assessment timelines for sling accessories. Industrial clusters in North Rhine-Westphalia and Bavaria host specialized durable medical equipment distributors serving ambulatory care expansion.
Japan
METI-funded facility modernization programs prioritize ceiling lift retrofits in spatially constrained skilled nursing environments. JIS standards govern structural engineering validation for overhead track installations. The Kanto region around Tokyo anchors procurement volume for lithium-ion battery systems enabling room-to-room mobility.
United Kingdom
NHS capital planning frameworks emphasize injury reduction targets in acute trusts, directing spend toward electric base units. MHRA post-market surveillance requirements align with EU MDR transition timelines for sling suppliers. Procurement concentration in Greater London and the Midlands favors direct manufacturer relationships over traditional group purchasing organization channels.
Australia
Aged care quality standards mandate safe patient handling equipment in residential facilities, accelerating replacement cycles for legacy manual systems. TGA medical device regulations classify patient lifts according to risk-based conformity assessment pathways. New South Wales and Victoria lead state-level procurement for bariatric-rated installations in metropolitan hospital networks.
Patient Lifts Market Competitive Landscape
Premium-system integrators and home-care channel specialists split the market along reimbursement-navigation capability versus acute-care contract scale. Hospital procurement consolidation favors players with embedded preventive maintenance infrastructure and enterprise-wide training protocol standardization. Two strategic archetypes dominate: ceiling-lift installation specialists with structural engineering partnerships, and portable-equipment fabricators with Medicare reimbursement expertise. Competitive moves concentrate on direct manufacturer contract displacement of group purchasing organization intermediaries, and lithium-ion battery platform standardization across product generations.
Within the premium-system tier, Arjo and Stryker occupy positions defined by acute-care contract anchoring and bed-integrated lift portfolio extension. Invacare Corporation exemplifies the home-care specialization archetype, navigating Medicare reimbursement complexity for residential channel penetration. These three entities represent distinct strategic postures: Nordic health system integration, US hospital capital equipment bundling, and durable medical equipment distributor relationship management.
| Leading Market Players |
|---|
| GF Health Products |
| Hill-Rom (Baxter) |
| Invacare Corporation |
| Etac AB |
| Handicare |
| Arjo |
| Joerns Healthcare |
| Drive DeVilbiss Healthcare |
| Stryker |
| Others |
Value Network & Pricing Analysis
Trans-Pacific freight corridors from Shanghai to Los Angeles govern landed cost differentials for steel-framed electric lift assemblies, compressing margin buffers for manufacturers sourcing aluminum extrusions from China while enabling premium pricing power for Nordic producers with captive European supply bases.
Pricing Analysis
Configured-to-order ceiling lift installations with structural engineering validation command 40-60% premiums over standard electric base units. Pricing stratifies across premium, standard, and economy tiers based on load-bearing certification grade and after-sales service bundling. Cost compression in the hydraulic segment intensifies as Indian and Southeast Asian manufacturers exploit labor arbitrage. Home care agencies exhibit highest price sensitivity due to Medicare reimbursement caps, while IDN procurement teams prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for aluminum frame fabricators and lithium-ion battery pack assemblers. Manufacturing concentration centers on China, Germany, and the United States for motorized lift assemblies, with sling textile production anchored in Turkey and Vietnam. Steel and aluminum commodity volatility feeds directly into margin unpredictability. Distribution runs through specialized durable medical equipment distributors and direct manufacturer contracts with consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient lift economics are shifting from equipment transaction to platform subscription as smart sensor integration creates continuous data revenue streams and bed-lift interoperability becomes the decisive procurement criterion.
For Market Incumbents: Pre-empt disintermediation by group purchasing organizations through enterprise-wide service agreements spanning installation, preventive maintenance, and sling replacement inventory. Deepen structural engineering partnerships for ceiling lift retrofit expertise. Invest in lithium-ion battery platform standardization to accelerate replacement cycle capture in Japan and Germany.
For New Entrants and Emerging Players: Pursue direct-to-consumer channel development under Medicare Advantage supplemental benefit expansion, bypassing traditional durable medical equipment distributors. Target residential ceiling lift installations in Florida and Texas where aging-in-place policy traction is strongest. Lead with telehealth-integrated remote monitoring capabilities to differentiate from legacy equipment fabricators.
For Investors and Strategic Acquirers: Home-care channel specialists with Medicare reimbursement navigation expertise represent the most defensible acquisition archetype against acute-care contract consolidation. Monitor FDA 510(k) clearance velocity and EU MDR technical documentation completion rates as inflection indicators for portfolio company R&D efficiency and market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Platform Development | Position tracking and integrated scale systems enable subscription revenue from bariatric care workflows. |
| Ceiling Lift Retrofit Specialization | Structural engineering partnerships unlock METI-funded modernization programs in Japanese skilled nursing facilities. |
| Lithium-Ion Battery Standardization | Room-to-room mobility without infrastructure modification accelerates replacement cycles in German and Japanese markets. |
| Direct-to-Consumer Channel Buildout | Medicare Advantage supplemental benefit expansion enables bypass of traditional durable medical equipment distributors. |
| EU MDR Compliance Infrastructure | Clinical evaluation reports and post-market surveillance systems secure sling accessory market access under Article 10 obligations. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and home care agency procurement directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation repositories. Bottom-up unit economics triangulated against top-down market sizing across product architectures and end-use segments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning lift type, weight capacity tier, end-use facility, and technology integration level. CAGRs derived from installed base replacement cycles, regulatory mandate compliance deadlines, and reimbursement code expansion trajectories. Forecast inputs incorporated OSHA safe patient handling enforcement intensity and METI facility modernization funding allocations.
Sensitivities concentrate around steel and aluminum commodity volatility, EU MDR conformity assessment timeline extensions, and Medicare reimbursement code revisions for residential installations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market