
 Intensive Care Unit (ICU) Equipment Market | 2026-2036
Intensive Care Unit (ICU) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Intensive Care Unit (ICU) Equipment Market Analysis
Emergency departments are recalibrating their capital equipment priorities toward integrated monitoring and rapid-response platforms. Baxter leverages its renal care and critical care portfolio to anchor positions in multi-organ support systems across North American hospital networks. Fresenius sustains manufacturing scale in infusion and fluid management technologies that serve high-acuity settings. Philips differentiates through digital telemetry architectures that bridge bedside and centralized monitoring workflows.
Intensive Care Unit equipment encompasses life-support apparatus, physiological monitoring systems, and therapeutic delivery devices engineered to maintain organ function in critically ill patients, typically operating within precision tolerances of ±2% for infusion rates and pressure-controlled ventilation parameters. Ventilators and monitoring systems command the largest installed base and replacement revenue pools, with modular architectures gaining preference as hospitals seek flexible capacity expansion without full system overhauls. Digital technology platforms now dominate new procurement specifications, displacing analog interfaces as connectivity standards and remote-access protocols become baseline requirements.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation impose escalating clinical evidence requirements that extend development timelines and favor established manufacturers with regulatory infrastructure. The EPA's energy-efficiency standards for hospital equipment additionally shape ventilator and monitor design specifications, particularly for thermal management and standby power consumption. Stakeholders must weigh the capital efficiency of modular upgrade paths against the operational risks of fragmented device ecosystems as procurement cycles compress and interoperability mandates tighten.
Market Dynamics
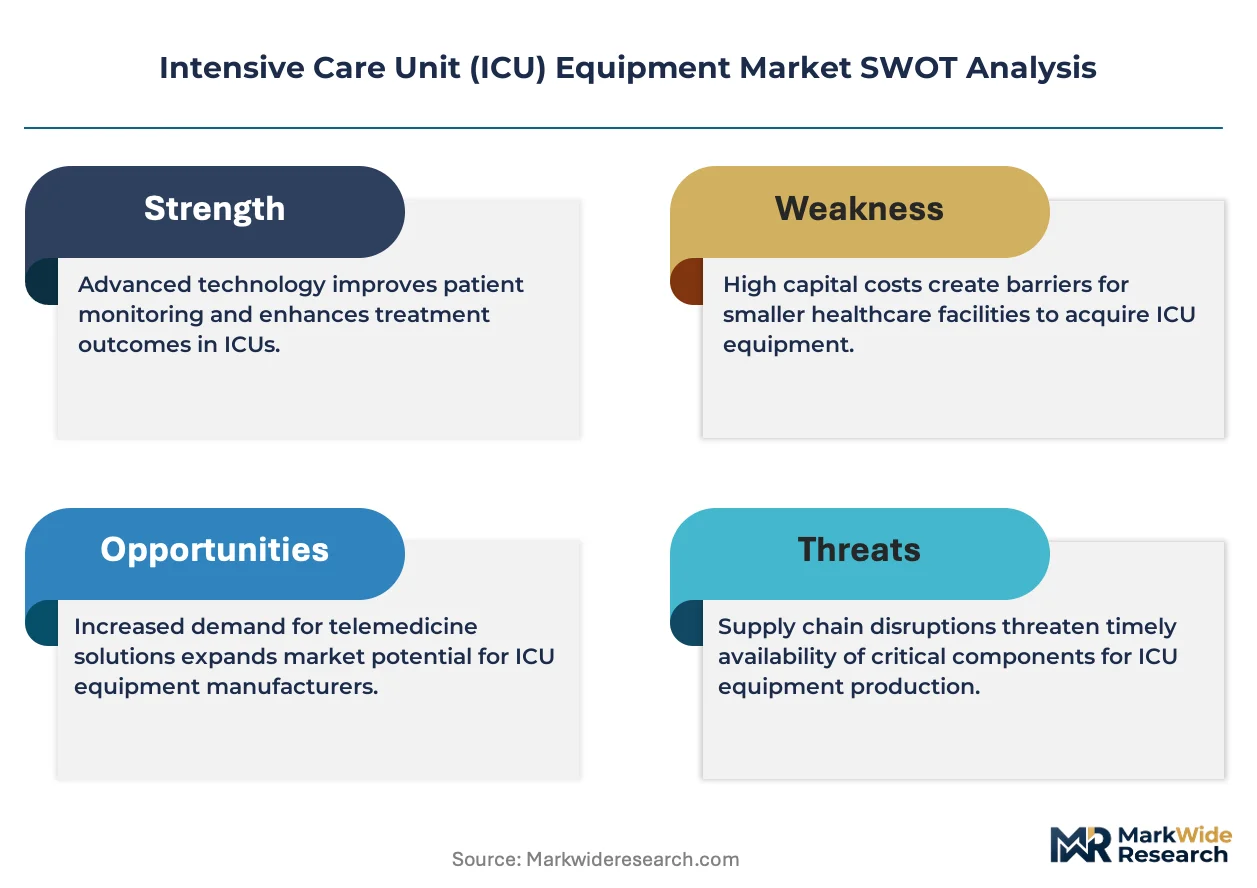
The ICU equipment sector faces structural pressure from modular system architectures that fragment purchasing authority across hospital IT, biomedical engineering, and critical care departments. This distributed decision-making is compressing replacement cycles while elevating interoperability requirements.
Growth Catalysts
- FDA 510(k) pathway streamlining:The premarket notification framework for Class II devices accelerates clearance timelines for iterative monitoring technologies, enabling faster feature deployment in pulse oximetry and capnography systems.
- Academic medical centers:These institutions drive demand for research-grade physiological data capture, mandating equipment with expanded sampling rates and open API architectures for clinical trial integration.
- Edge computing integration:On-device analytics for arrhythmia detection and sepsis risk scoring reduce latency in alarm generation, supporting decentralized ICU staffing models.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate fabrication of application-specific integrated circuits for ventilator motor controllers, creating vulnerability in pneumatic system production.
- EU MDR clinical evidence escalation:The Medical Device Regulation's expanded requirements for post-market surveillance and periodic safety update reports extend recertification timelines for legacy monitoring platforms.
- Reusable sensor substitution:Single-use pulse oximeter probes face displacement from sterilizable alternatives in sustainability-focused procurement, threatening consumables revenue pools.
Strategic Opportunities
- India's hospital infrastructure expansion:The country's PLI scheme for medical devices attracts domestic manufacturing investment, creating localized supply advantages for ventilator and infusion pump assembly.
- Remote ICU command centers:Tele-critical care platforms enable specialist labor arbitrage across hospital networks, opening subscription-based monitoring service models beyond equipment sales.
- AI Act compliance differentiation:Early alignment with the EU's risk-based AI governance framework positions manufacturers for preferential procurement in European hospital systems adopting algorithmic decision-support tools.
Industry Challenges
- Biomedical engineering talent scarcity:Hospitals face recruitment gaps for technicians capable of servicing hybrid pneumatic-digital ventilator architectures, extending equipment downtime during failure events.
- Legacy system integration complexity:Proprietary communication protocols in installed monitoring networks obstruct seamless data aggregation with new telemetry platforms, forcing middleware expenditures.
- EPA energy certification timelines:Extended validation periods for standby power efficiency standards delay product launches and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensive Care Unit (ICU) Equipment Market |
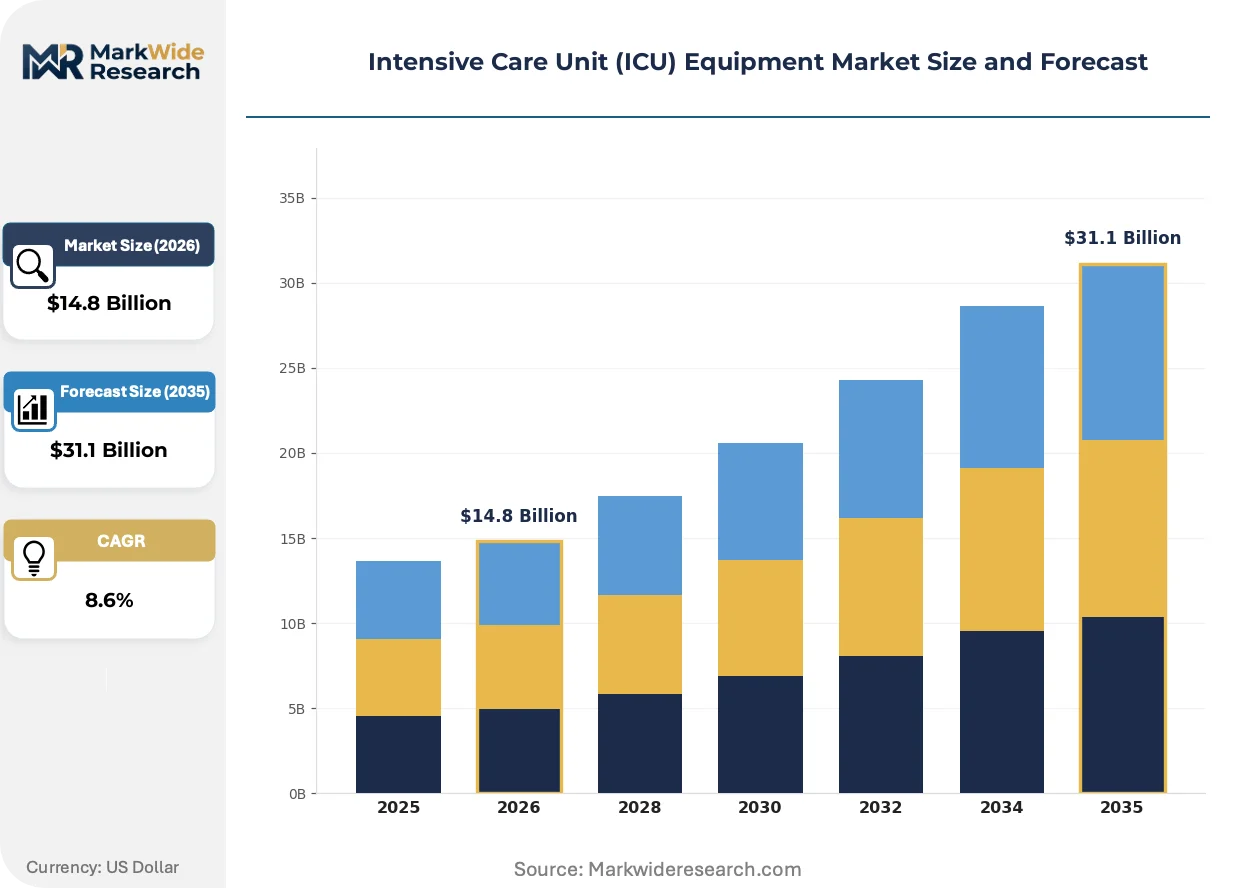
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Monitoring Systems, Infusion Pumps, Defibrillators Technology: Digital, Portable, Modular, Analog End User: Hospitals, Specialized Clinics, Emergency Departments, Rehabilitation Centers Application: Cardiac Care, Respiratory Support, Neurological Monitoring, Postoperative Recovery |
| Companies Covered | Baxter, Fresenius, GE Healthcare, Nihon Kohden, BD, Philips, Dragerwerk, Mindray, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensive Care Unit (ICU) Equipment Market Emerging Trajectories
Digital telemetry architectures are fragmenting the traditional bedside monitor category, with sensor miniaturization and wireless protocols enabling continuous monitoring outside physical ICU boundaries. This technological dispersion is redrawing competitive boundaries between device manufacturers and enterprise software vendors.
Disposable multi-parameter patches integrating ECG, respiratory rate, and temperature sensing are rewriting patient mobility protocols in step-down units. Post-acute facilities adopt these platforms to maintain surveillance during patient transport and early mobilization. The technology is compressing the addressable market for traditional multi-lead cable systems while expanding monitoring into previously uneconomical care settings.
REACH regulation amendments on substance restrictions in electrical equipment are forcing material substitutions in cable insulation and circuit board laminates. Manufacturers reformulate ventilator internal wiring harnesses to maintain compliance with evolving substance thresholds. German hospital procurement associations now embed full material disclosure requirements in tender specifications, favoring suppliers with established green chemistry documentation systems.
Consolidated purchasing through regional health system networks is displacing individual hospital capital committees as the primary equipment acquisition channel. Integrated delivery networks in the United States negotiate enterprise-wide telemetry contracts spanning dozens of facilities, extracting volume discounts that independent hospitals cannot match. This concentration is most visible in the southeastern states, where large nonprofit systems have absorbed community hospitals and standardized device fleets across acquired campuses.
Intensive Care Unit (ICU) Equipment Market Segmentation
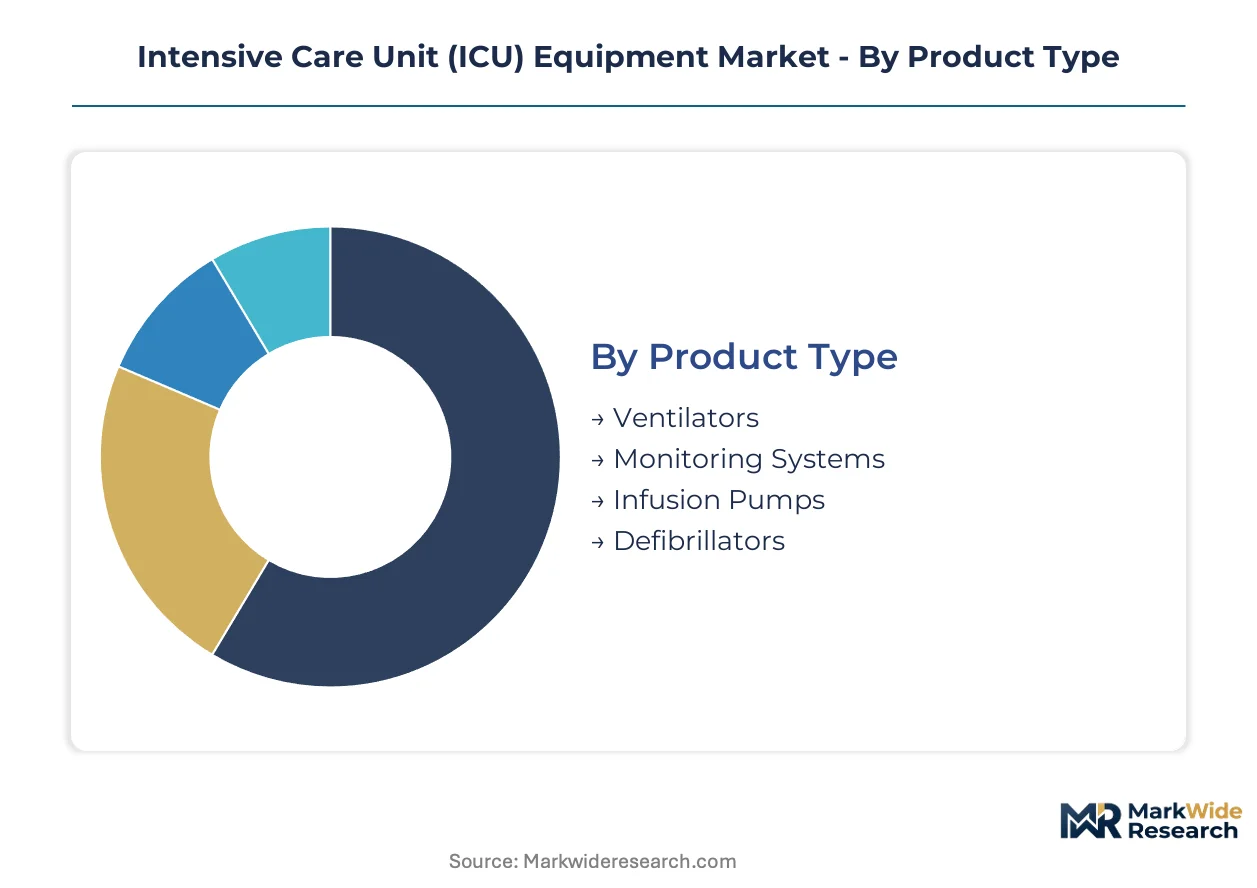
ICU equipment purchasing fragments across clinical workflows, forcing manufacturers to align specifications with divergent technical requirements. Hospital procurement committees now weight interoperability and upgrade pathways alongside device performance metrics.
Product Type:
Ventilators and monitoring systems anchor revenue concentration at the premium tier, while infusion pumps and defibrillators operate on volume-driven replacement cycles.
- Ventilators:Precision pneumatic systems deliver pressure-controlled and volume-controlled ventilation with tidal accuracy within ±10 mL. Demand clusters in academic medical centers performing multi-organ support protocols, where FDA 510(k) clearances for high-frequency oscillation modes command procurement priority.
- Monitoring Systems:Multi-parameter platforms integrate ECG, SpO2, invasive pressure, and temperature sensing through centralized telemetry architectures. Hospital networks in the United States specify open API compatibility for enterprise data aggregation, displacing standalone bedside units.
- Infusion Pumps:Syringe and volumetric pumps maintain medication delivery accuracy within ±2% across critical care and anesthesia workflows. Modular pump configurations allow channel expansion without controller replacement.
- Defibrillators:Biphasic waveform devices with automated external and manual modes serve rapid response teams. Biphasic energy protocols reduce myocardial damage compared to monophasic alternatives.
Today's leader: Ventilators. Tomorrow's challenger: Monitoring Systems.
Technology:
Digital architectures dominate new procurement specifications, while portable and modular formats address capacity flexibility demands.
- Digital:Network-connected platforms enable centralized alarm management and predictive analytics through edge computing integration. Hospital IT departments mandate HL7 FHIR compliance for seamless EHR integration.
- Modular:Component-based designs allow incremental capability expansion—adding hemodynamic monitoring modules to base telemetry platforms without full system replacement. This architecture appeals to capital-constrained community hospitals.
- Portable:Battery-powered ventilators and monitors support intra-hospital transport and emergency department surge capacity. Lightweight construction trades feature depth for mobility.
- Analog:Legacy interfaces persist in resource-limited settings where network infrastructure remains underdeveloped. Replacement cycles accelerate as connectivity mandates tighten.
Digital platforms command current procurement preference. Modular systems are climbing the fastest as hospitals seek capital efficiency.
End User:
Hospital systems concentrate purchasing authority, while specialized clinics and emergency departments fragment decision-making across clinical and operational stakeholders.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts spanning ICU, step-down, and perioperative units. Standardization across acquired campuses reduces training and maintenance complexity.
- Emergency Departments:Rapid-response specifications prioritize device startup speed and intuitive interfaces for rotating clinical staff. Space constraints favor compact multi-parameter platforms.
- Specialized Clinics:Cardiac and neurological focused facilities demand research-grade data sampling rates for clinical trial participation. Premium pricing tolerance reflects specialized reimbursement.
- Rehabilitation Centers:Post-acute settings adopt portable monitoring for patient mobilization protocols. Lower acuity requirements permit simplified feature sets.
Hospitals control today's volume. Emergency Departments represent the fastest-expanding procurement channel.
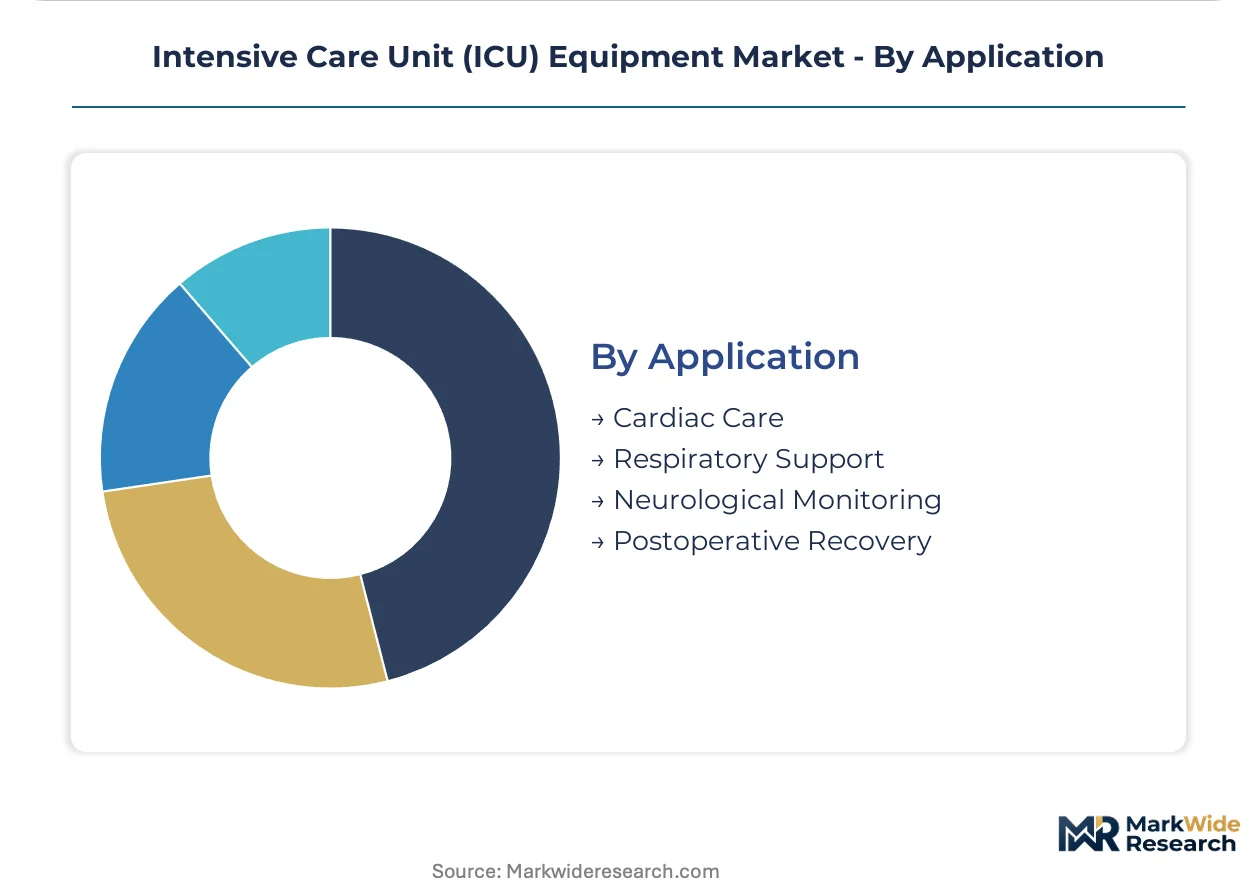
Application:
Cardiac and respiratory applications anchor installed base density, while neurological monitoring and postoperative recovery drive emerging specification requirements.
- Respiratory Support:Mechanical ventilation and non-invasive respiratory assistance address acute respiratory distress syndrome and post-surgical weaning. Precision gas blending and closed-loop oxygen control satisfy critical care protocols.
- Cardiac Care:Hemodynamic monitoring, intra-aortic balloon pumps, and temporary pacemakers support acute coronary syndrome and post-cardiac surgery recovery. Continuous cardiac output measurement integrates with fluid management algorithms.
- Neurological Monitoring:Intracranial pressure sensors and continuous EEG platforms detect secondary brain injury in trauma and stroke patients. Data-intensive requirements strain legacy telemetry bandwidth.
- Postoperative Recovery:Enhanced recovery after surgery protocols demand continuous surveillance during early mobilization. Disposable patch sensors enable monitoring outside traditional ICU boundaries.
Respiratory Support leads current deployment. Neurological Monitoring is gaining share fastest as neurocritical care specialization expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors the global ICU equipment manufacturing cluster, with the United States commanding the largest procurement volume through integrated delivery networks and academic medical center procurement programs.
United States
Hospital network consolidation and ICU bed expansion programs drive equipment replacement cycles at a sustained pace. The FDA's 510(k) premarket notification framework shapes clearance timelines for Class II monitoring devices. Minneapolis and Boston house concentrated R&D operations for multi-parameter telemetry platforms serving North American health systems.
Germany
Precise engineering standards and hospital procurement association standardization create premium-tier demand for ventilator and monitoring systems. The EU Medical Device Regulation imposes escalating clinical evidence requirements that extend recertification timelines. The Baden-Württemberg industrial corridor hosts specialized pneumatic component fabrication for critical care ventilation equipment.
China
Domestic hospital infrastructure expansion and import substitution policies accelerate local manufacturing capacity buildout. The National Medical Products Administration enforces registration requirements for Class II and Class III devices that parallel FDA stringency. The Yangtze River Delta cluster concentrates ventilator motor controller and sensor module production for regional supply chains.
India
Public hospital modernization and medical device manufacturing incentives reshape procurement patterns toward domestically assembled equipment. The Production Linked Incentive scheme for medical devices attracts capital investment in ventilator and infusion pump assembly operations. Maharashtra and Karnataka host emerging manufacturing zones targeting price-competitive critical care equipment for South Asian markets.
Japan
Aging demographics and hospital digitization mandates sustain demand for integrated monitoring architectures with predictive analytics capabilities. The Pharmaceuticals and Medical Devices Agency maintains rigorous quality management system inspections for manufacturing facilities. The Kansai region retains specialized production capacity for high-precision physiological sensors serving domestic and export markets.
Intensive Care Unit (ICU) Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bridge hardware expertise with digital health platform capabilities. The vendor base concentrates around diversified medical technology conglomerates with established regulatory infrastructure and specialized critical care equipment pure-plays. Three archetypes define competitive positioning: integrated life sciences conglomerates with multi-organ support portfolios, precision monitoring specialists with telemetry-centric architectures, and regional scale manufacturers serving price-sensitive procurement channels. M&A activity and technology licensing agreements represent the primary vectors for capability expansion and geographic penetration.
Within the diversified conglomerate tier, Baxter and Fresenius occupy positions anchored by renal care and fluid management portfolios that extend into multi-organ critical care support. Philips represents the digital telemetry archetype, with enterprise monitoring architectures that bridge bedside and centralized command workflows. Mindray exemplifies the regional scale manufacturer model, with cost-optimized production configurations targeting emerging market hospital procurement programs. These three anchors illustrate how competitive positioning fragments across regulatory sophistication, software integration depth, and manufacturing cost structure rather than converging on a single optimal configuration.
| Leading Market Players |
|---|
| Baxter |
| Fresenius |
| GE Healthcare |
| Nihon Kohden |
| BD |
| Philips |
| Dragerwerk |
| Mindray |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
REACH substance restriction amendments in electrical equipment gate qualified supply access and premium-tier pricing power for ICU device manufacturers, forcing reformulation of cable insulation and circuit board laminates while German hospital procurement associations embed full material disclosure requirements in tender specifications.
Pricing Analysis
Distributor margins for multi-parameter telemetry platforms compress as integrated delivery networks negotiate enterprise-wide contracts spanning dozens of facilities. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, brand premium, and after-sales service bundling. Cost compression in the standard tier intensifies because Mindray and domestic Chinese manufacturers expand price-competitive ventilator assembly. Emergency departments demonstrate highest price sensitivity due to capital budget constraints, while academic medical centers show lowest sensitivity given research-grade reimbursement tolerance.
Supply Chain Analysis
FDA 510(k) and EU MDR certification requirements gate component sourcing, with only qualified suppliers meeting clinical evidence and quality management system standards. Taiwan, China, and Germany concentrate fabrication of application-specific integrated circuits for ventilator motor controllers, precision pneumatic components, and physiological sensors. Raw material dependencies span semiconductor wafers, medical-grade polymers, and rare earth elements for sensor magnetics. Single-source vulnerability in Taiwan-based foundries threatens pneumatic system production continuity. Distribution runs through regional health system networks and group purchasing organizations rather than independent hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost differentials between India's PLI-subsidized medical device zones and German precision engineering corridors create geographic-arbitrage opportunities for ventilator and infusion pump assembly operations.
For Market Incumbents: Deploy backward integration into semiconductor sourcing to mitigate Taiwan foundry concentration risk threatening ventilator motor controller supply. Consolidate service networks across acquired hospital campuses to reduce biomedical engineering talent scarcity downtime. Counter disposable multi-parameter patch substitution threats with modular upgrade pathways for installed telemetry platforms. For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for price-competitive ventilator and infusion pump assembly targeting South Asian public hospital modernization programs. Focus white-space capture on rehabilitation center portable monitoring where simplified feature sets reduce regulatory burden. Pursue tele-critical care platform partnerships as subscription-based service entry points beyond capital equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for telemetry-centric monitoring specialists because hospital network standardization mandates create acquisition synergies across enterprise contract consolidation. Target mid-cap manufacturers with established FDA 510(k) clearance infrastructure and open API architectures. Watch for AI Act compliance differentiation signaling preferential procurement positioning in European hospital systems adopting algorithmic decision-support tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance timelines for iterative pulse oximetry and capnography monitoring technologies enable faster feature deployment. |
| CE Marking Pathway Investment | EU MDR clinical evidence escalation demands extended post-market surveillance infrastructure favoring established regulatory players. |
| Hospital System Partnership | Enterprise-wide telemetry contracts with integrated delivery networks extract volume discounts that independent hospitals cannot match. |
| Software Companion Development | HL7 FHIR-compliant edge computing analytics for arrhythmia detection support decentralized ICU staffing models and alarm management. |
| Reimbursement Strategy Alignment | Enhanced recovery after surgery protocol adoption drives continuous surveillance demand during early patient mobilization phases. |
Methodological Framework
Multiple input streams — hospital procurement database analysis, GPO contract review, CMS Medicare equipment utilization data, and FDA 510(k) clearance filings — were reconciled through bottom-up and top-down triangulation. Primary interviews with critical care clinicians, hospital purchasing committee directors, biomedical engineering managers, and GPO contracts specialists were validated against secondary sources including SEC 10-K disclosures from listed medical device manufacturers, EU MDR recertification timelines, and Indian PLI scheme beneficiary announcements.
Historical shipment volumes were cross-referenced against panel input from ventilator and monitoring system manufacturers to derive expansion rates across the projection horizon. Segmentation modeling incorporated product type, technology architecture, end-user facility category, and clinical application workflow. CAGRs were calculated from reconciled baseline and terminal value estimates incorporating ICU bed expansion program announcements, semiconductor supply concentration risk adjustments, and regulatory timeline impacts.
Revisions become necessary when FDA 510(k) pathway streamlining accelerates or delays, EU MDR clinical evidence requirements escalate further, or Taiwan semiconductor foundry capacity constraints materialize. A model refresh is warranted upon material change in integrated delivery network consolidation pace or AI Act compliance procurement mandates in European hospital systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Operating Light Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Cath Lab Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Water Bath Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Medical Equipment Leasing Market