
 Electric Bed Market | 2026-2036
Electric Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bed Market Intelligence
Chinese manufacturers of electric bed components is recalibrating capacity allocation toward motor and actuator modules. Stryker leverages its integrated hospital systems footprint to sustain recurring service revenue across North American acute care networks. Hill-Rom Services Inc. anchors premium positioning through specialized bariatric and critical care configurations. LINET competes aggressively on total cost of ownership in European public tender environments.
An electric bed integrates motorized actuators, control electronics, and adjustable frame architecture to enable automated positioning of the sleep surface for therapeutic, diagnostic, or comfort purposes. Units typically incorporate linear actuators rated for loads exceeding 250 kg, with power consumption ranging from 50W to 150W depending on simultaneous motor operation, and communicate through CAN bus or wireless protocols to nursing station dashboards. Hospital beds occupy the largest revenue pool given replacement cycles tied to accreditation standards and infection control protocols, while home care represents the fastest-expanding end user channel as reimbursement frameworks shift toward outpatient recovery. App control mechanisms command margin premiums over wired alternatives by enabling remote patient monitoring integration and predictive maintenance alerts.
The FDA 510(k) pathway governs electric hospital bed clearance in the United States, while the EU MDR imposes stricter clinical evidence requirements on Class IIa and IIb patient positioning devices. Japan's PMDA maintains distinct electromagnetic compatibility testing protocols that create separate certification burdens for manufacturers seeking access. Stakeholders must monitor how reimbursement rate negotiations between hospital purchasing coalitions and equipment vendors reshape specification requirements for future procurement cycles.
Market Dynamics
The electric bed market is being restructured by the EU Medical Device Regulation (MDR) framework, which is forcing hospital procurement departments to replace legacy semi-electric units with fully motorized ICU configurations ahead of compliance deadlines.
Growth Catalysts
- Aging demographics:Japan's super-aged population is expanding home care reimbursement for motorized adjustable frames through METI-administered long-term care insurance tiers.
- EU MDR compliance mandates:German hospital purchasing coalitions are accelerating replacement cycles for patient positioning devices to meet Class IIb clinical evidence requirements.
- App-control integration:Bluetooth-enabled remote monitoring modules are penetrating residential care facilities, enabling predictive maintenance alerts and reducing emergency service calls.
Market Restraints
- Actuator supply concentration:Linear motor production clusters in Zhejiang Province create single-source vulnerability for European bed assemblers.
- Electromagnetic compatibility testing:Japan's PMDA maintains distinct EMC protocols that duplicate certification costs for manufacturers seeking access.
- Steel and aluminum input volatility:Frame fabrication depends on commodity metals exposed to energy-driven price swings.
Strategic Opportunities
- Underpenetrated home care segments:India's tier-2 cities present whitespace for affordable electric bed rental models tied to CDSCO-registered distributors.
- Reimbursement framework expansion:The US IRA provisions for home-based recovery are extending durable medical equipment coverage to motorized sleep surfaces.
- Convergence of sensor arrays:Pressure-mapping textiles combined with CAN bus architectures enable automated repositioning for pressure ulcer prevention.
Industry Challenges
- Firmware validation timelines:FDA 510(k) submissions for software-controlled positioning algorithms face extended review queues.
- Integration complexity with legacy nurse call systems:Wired communication protocols in existing hospital infrastructure resist wireless retrofit without gateway hardware.
- Field service technician scarcity:Electromechanical troubleshooting skills lag behind installed base expansion in rural acute care networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bed Market |
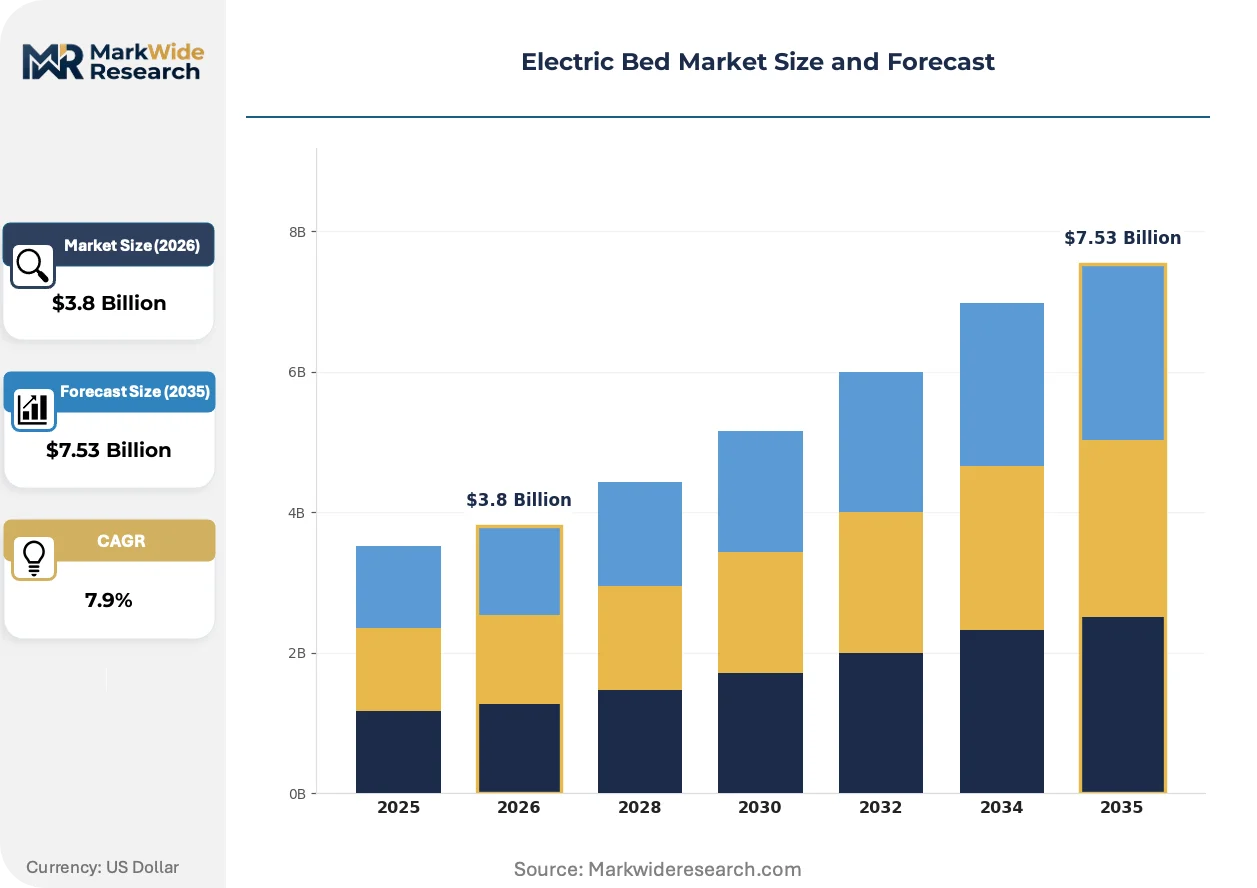
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Bed Frames, Hospital Beds, Luxury Beds, Electric Recliners End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Functionality: Massage Function, Heating Function, Raised Head, Lowered Foot Control Mechanism: Remote Control, App Control, Wired Control, Voice Control |
| Companies Covered | Hill-Rom Services Inc., Stryker, Arjo, Malvestio Spa, LINET, Medline Industries Inc., PARAMOUNT BED CO. LTD., Gendron Inc., Invacare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bed Market Strategic Shifts & Innovations
Motorized bed architectures are converging with digital health infrastructure, compressing the boundary between furniture and clinical monitoring equipment while reshaping vendor revenue models toward subscription-based maintenance.
Brushless DC actuator systems with integrated position feedback are unifying motion control and telemetry in single modules. Hospital engineering departments in the United States are specifying these units for new ICU construction. This unification is collapsing the supplier tier structure by eliminating separate controller board vendors.
The EU MDR's post-market surveillance requirements are extending clinical evidence obligations to patient positioning devices previously exempt under the Medical Device Directive. Manufacturers must now maintain systematic registries for adverse events. Class IIb bed configurations face the steepest documentation burden, compressing margins for mid-tier European assemblers.
Acute care purchasing coalitions are consolidating specification authority into centralized procurement offices, displacing individual hospital autonomy. Group purchasing organizations now mandate interoperability with electronic health record systems. This concentration is most advanced in North American integrated delivery networks, where standardization clauses override individual facility preferences.
Electric Bed Market Segmentation
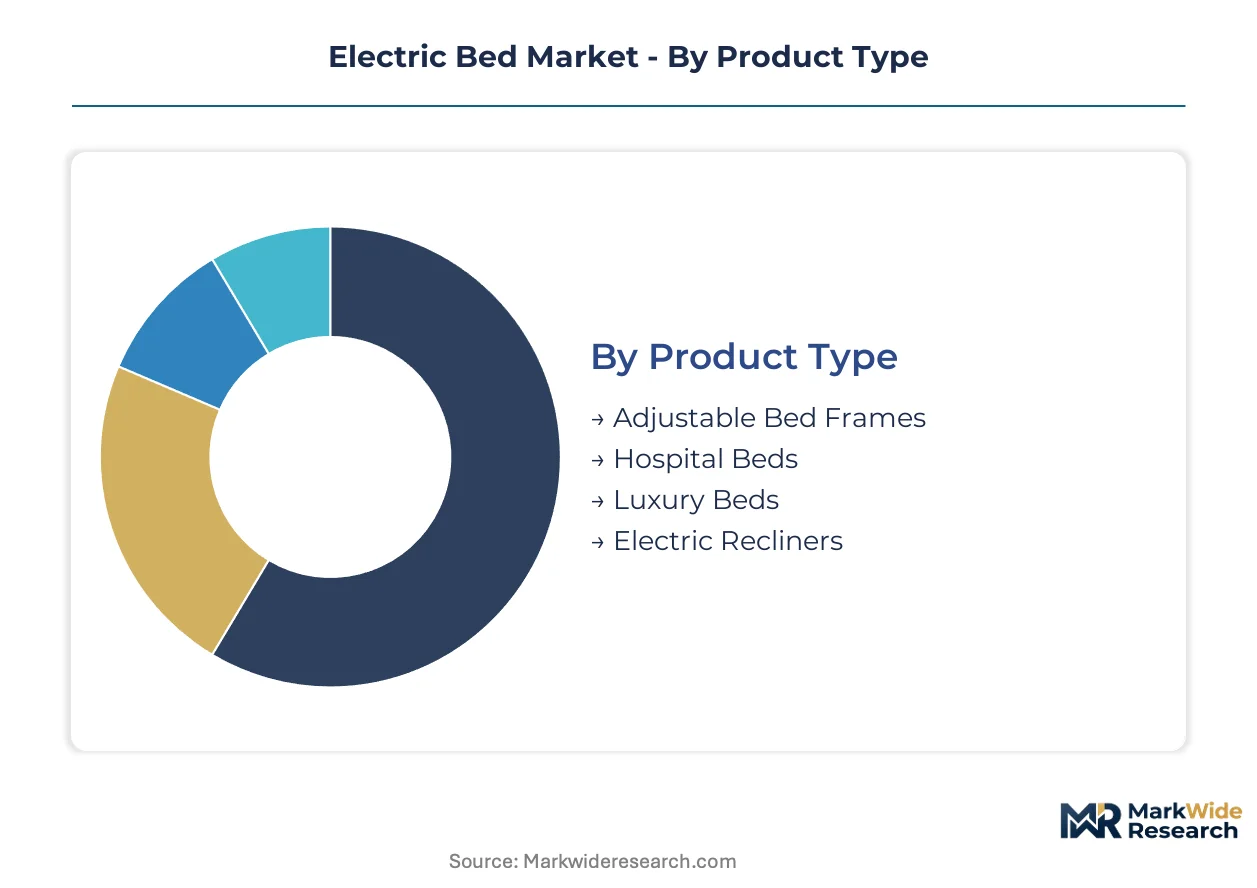
Electric bed segmentation reveals divergent engineering priorities across care environments. Hospital procurement emphasizes actuator reliability and infection-resistant surfaces, while residential buyers prioritize connectivity integration and aesthetic integration with home furnishings.
Product Type:
Motor configuration and load-bearing architecture distinguish commercial viability across sleep surface categories.
- Adjustable Bed Frames:Modular actuator systems rated for 250-350 kg dynamic loads enable independent head and foot articulation. Demand concentrates in German and Japanese home care markets where METI and statutory health insurance funds reimburse motorized positioning for pressure ulcer prevention.
- Hospital Beds:Fully electric ICU configurations integrate CAN bus telemetry, battery backup systems, and radiolucent deck panels for intra-bed imaging. German hospital purchasing coalitions are accelerating replacement cycles ahead of EU MDR Class IIb compliance deadlines.
- Luxury Beds:Upholstered residential units with whisper-rated motors below 40 dB target premium aging-in-place renovations.
- Electric Recliners:Single-motor lift mechanisms serve bariatric and mobility-limited users in outpatient rehabilitation settings.
Mature deployment sits with Hospital Beds. Newer deployment is concentrated in Adjustable Bed Frames.
End User:
Reimbursement eligibility and procurement authority reshape specification requirements across care settings.
- Hospitals:Acute care networks specify beds with integrated scale systems, siderail egress sensors, and nurse call interoperability. North American integrated delivery networks are consolidating purchasing authority through centralized procurement offices that mandate EHR connectivity.
- Home Care:Bluetooth-enabled adjustable frames with predictive maintenance alerts are climbing the fastest as US IRA provisions extend durable medical equipment coverage to motorized sleep surfaces.
- Nursing Homes:Semi-electric configurations dominate Medicaid-funded facilities constrained by capital expenditure limits.
- Rehabilitation Centers:Bariatric-rated frames with Trendelenburg positioning support post-surgical recovery protocols.
Established procurement patterns persist in Hospitals. Emerging deployment is accelerating in Home Care.
Functionality:
Therapeutic feature integration commands margin premiums based on clinical validation and energy consumption profiles.
- Raised Head:Anti-reflux and respiratory positioning drives specification in cardiac and pulmonary wards. Japanese super-aged population expansion through METI-administered long-term care insurance tiers is expanding reimbursement for this configuration.
- Lowered Foot:Edema management and venous return optimization targets post-operative recovery protocols in European public tender environments.
- Massage Function:Percussion motor modules with programmable intensity cycles serve luxury residential and wellness facility segments.
- Heating Function:Low-voltage warming elements integrate into pressure-mapping textiles for thermoregulatory support in home care.
Clinical-grade deployment centers on Raised Head. Consumer-oriented feature expansion is concentrated in Massage Function.
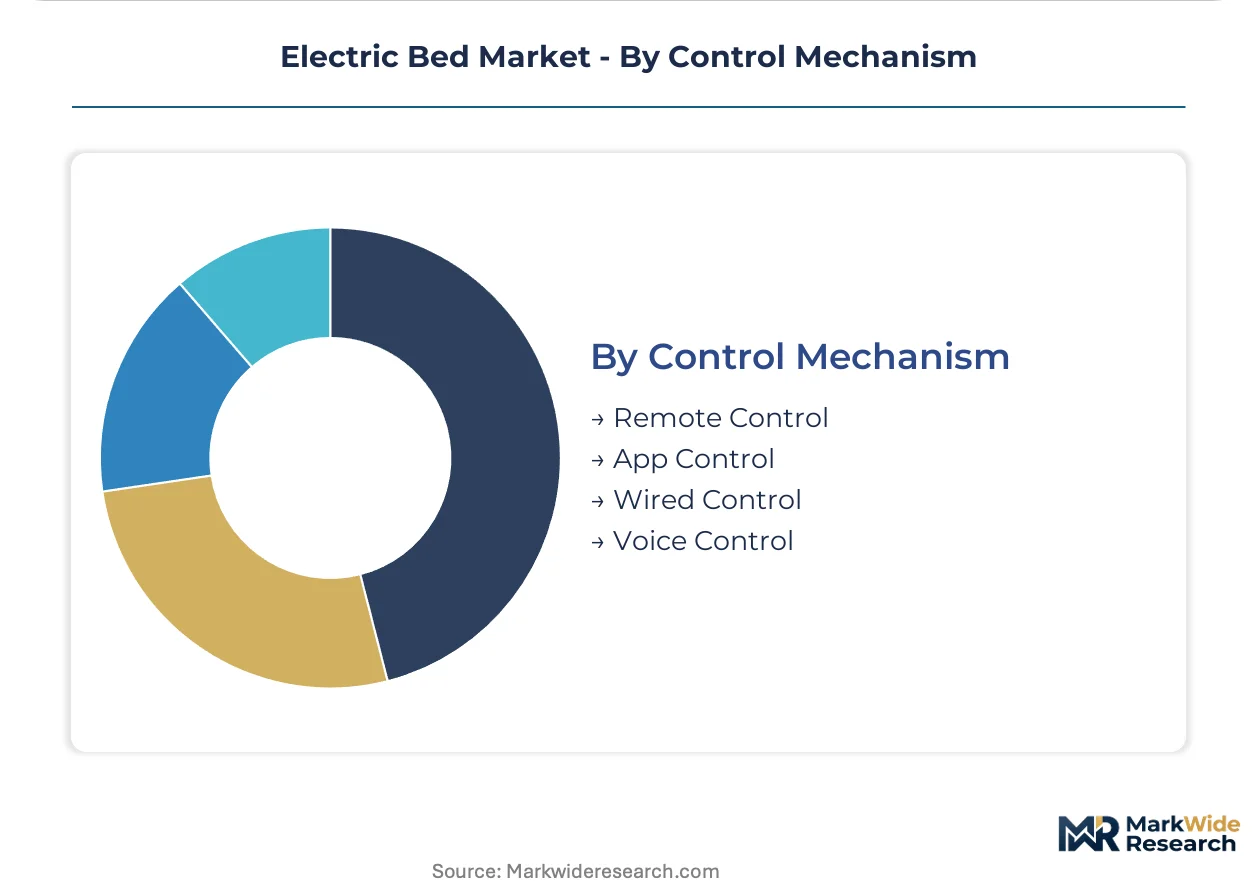
Control Mechanism:
Interface architecture determines integration depth with digital health infrastructure and maintenance cost structures.
- App Control:Bluetooth and Wi-Fi modules enable remote patient monitoring, caregiver alerts, and over-the-air firmware updates. Chinese manufacturers are scaling production of app-controlled frames for domestic aging-in-place demand.
- Remote Control:Handheld infrared or RF transmitters remain standard in Medicaid-funded nursing homes with limited IT infrastructure.
- Wired Control:Pendant cables with strain relief connectors serve high-availability ICU environments where wireless interference risks are unacceptable.
- Voice Control:Natural language interfaces integrated with smart home ecosystems target independent living residential segments.
Installed base concentration remains with Remote Control. Capability expansion is advancing in App Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province's linear motor production clusters anchor actuator supply for electric bed assemblers worldwide. German hospital purchasing coalitions and Japanese long-term care insurers are reshaping demand specifications across their respective markets.
United States
Integrated delivery networks in North America are consolidating procurement authority into centralized offices that mandate EHR connectivity for new ICU bed purchases. FDA 510(k) clearance pathways govern electric hospital bed approvals, with extended review queues for software-controlled positioning algorithms. Acute care networks in the Midwest and Southeast specify beds with integrated scale systems and nurse call interoperability.
Germany
Hospital purchasing coalitions are accelerating replacement cycles for patient positioning devices ahead of EU MDR Class IIb compliance deadlines. The EU Medical Device Regulation imposes stricter clinical evidence requirements on fully motorized ICU configurations. Manufacturing and engineering competencies concentrate in Baden-Württemberg and North Rhine-Westphalia, where component suppliers serve pan-European bed assemblers.
China
Domestic manufacturers are scaling production of app-controlled adjustable frames for aging-in-place home care demand. NMPA registration requirements apply to electric beds marketed as medical devices, though many residential units fall outside this scope. Production gravity concentrates in Zhejiang Province, where linear motor and actuator module capacity serves both export and domestic markets.
Japan
METI-administered long-term care insurance tiers are expanding reimbursement for motorized adjustable frames among the super-aged population. PMDA maintains distinct electromagnetic compatibility testing protocols that create separate certification burdens for manufacturers seeking market access. Demand concentrates in Kanto and Kansai regions, where urban aging demographics drive residential care facility investment.
India
Tier-2 cities present whitespace for affordable electric bed rental models tied to CDSCO-registered distributors. The country's national pharmaceutical regulator oversees medical device registration, though enforcement varies across states. Industrial activity clusters in Maharashtra and Gujarat, where domestic fabricators assemble frames for price-sensitive healthcare infrastructure.
Electric Bed Market Key Industry Players
Global majors compete with regional champions across certification depth and service network reach. The vendor base stratifies into three tiers: integrated hospital systems providers, specialized bariatric and critical care configurators, and regional cost-optimized assemblers. Dominant competitive moves include backward integration into motor and actuator production, and strategic partnerships with group purchasing organizations to secure recurring service contracts.
Within the integrated systems tier, Stryker and Hill-Rom Services Inc. occupy positions defined by recurring service revenue across acute care networks. Among European specialists, LINET exemplifies total cost of ownership positioning in public tender environments. PARAMOUNT BED CO. LTD. represents the Asia-Pacific regional champion archetype, anchoring domestic production scale for aging-in-place demand.
| Leading Market Players |
|---|
| Hill-Rom Services Inc. |
| Stryker |
| Arjo |
| Malvestio Spa |
| LINET |
| Medline Industries Inc. |
| PARAMOUNT BED CO. LTD. |
| Gendron Inc. |
| Invacare Corporation |
| Others |
Cost & Logistics Intelligence
Steel and aluminum commodity benchmarks cascade through electric bed manufacturing into three distinct pricing tiers, with frame fabrication costs directly tethered to energy-driven metal volatility and motor module sourcing geography.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium hospital system vendors from unbundled component assemblers, with service contracts commanding sustained margin premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU MDR Class IIb and FDA 510(k) pathways. Pricing pressure stems from Chinese manufacturers scaling app-controlled residential units, compressing mid-tier margins. Medicaid-funded nursing homes exhibit acute price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for linear actuators are reshaping procurement protocols among German hospital purchasing coalitions and North American acute care networks. Production gravity centers on Zhejiang Province for motor modules, Baden-Württemberg for precision engineering, and Maharashtra for frame fabrication. Supply chains draw from cold-rolled steel, rare-earth magnets, and medical-grade polymers. Single-source vulnerability in Zhejiang linear motor clusters presents structural concentration risk. Distribution runs through CDSCO-registered distributors in India, GPO contracts in the United States, and public tender authorities in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric bed market is consolidating around regulatory compliance depth and service network density, with EU MDR documentation burdens forcing mid-tier European assemblers toward exit or acquisition.
For Market Incumbents: Acquire field service technician capabilities in rural acute care networks to close the widening gap between installed base expansion and electromechanical troubleshooting capacity. Backward integration into brushless DC actuator production collapses supplier tiers and captures telemetry unification margins. Defend against Chinese manufacturers scaling app-controlled residential units by embedding predictive maintenance algorithms into hospital system contracts. For New Entrants and Emerging Players: Capture tier-2 Indian cities through affordable rental models tied to CDSCO-registered distributor networks, where capital expenditure constraints limit outright purchase penetration. Target home care reimbursement expansion under US IRA provisions as the most penetrable reimbursement frontier. Pursue white-label partnerships with domestic fabricators in Maharashtra and Gujarat to bypass upfront manufacturing fixed costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European assemblers facing EU MDR Class IIb documentation compression in Germany and surrounding markets, where clinical evidence obligations exceed retained earnings capacity. Five-to-ten year viability hinges on software-controlled positioning algorithm differentiation and EHR interoperability certification. Monitor FDA 510(k) review queue duration as the critical inflection signal for firmware-dependent valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Class IIb clinical evidence registries satisfy German hospital purchasing coalition mandates ahead of deadlines. |
| Actuator Module Backward Integration | In-house brushless DC production eliminates separate controller board vendors and unifies telemetry architectures. |
| App Control Platform Development | Bluetooth-enabled remote monitoring penetrates residential care facilities and reduces emergency service dispatch frequency. |
| Field Service Network Expansion | Electromechanical technician density in rural acute care networks lags behind installed base growth rates. |
| Hospital System Partnership | Integrated delivery network standardization clauses override individual facility preferences and lock in recurring revenue. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contract repositories, and CMS durable medical equipment coverage filings underwrites the qualitative findings in this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and aftermarket service heads combined with secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and METI long-term care insurance tier schedules. Bottom-up demand modeling across product configurations triangulates against top-down market sizing through the analysis window.
Comparable-period anchoring to historical replacement cycles and reimbursement framework shifts structured the forecast methodology across the projection horizon. Segmentation dimensions span motor configuration, end-user care setting, therapeutic functionality, and control mechanism interface. CAGRs derive from regression analysis against aging demographic trajectories, regulatory compliance deadlines, and reimbursement expansion schedules. Forecast inputs incorporate EU MDR implementation timelines, US IRA home care provisions, and Japanese METI insurance tier adjustments.
The model holds under stable reimbursement rates and regulatory enforcement continuity; deviation in hospital purchasing coalition negotiation outcomes or NMPA registration pathway changes would shift volume assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Global Capnography Equipment Market