
 Medical Equipment Leasing Market | 2026-2036
Medical Equipment Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Leasing Market Insights
North American hospital capital planning is consolidating around third-party equipment financing as balance-sheet pressure intensifies. Siemens Financial Services leverages captive finance structures to secure long-term imaging contracts across integrated delivery networks. Agiliti competes on clinical engineering integration, bundling maintenance with lease terms to reduce total cost of ownership for health systems. Med One Group specializes in refurbished modality leasing, occupying a mid-market niche between premium new-equipment finance and auction resale channels.
Medical equipment leasing denotes contractual arrangements where healthcare providers obtain use rights to diagnostic, therapeutic, or monitoring devices through periodic payments rather than outright purchase, typically structured with residual value clauses and maintenance obligations. Lease terms generally span 36–60 months for imaging systems and 12–36 months for patient monitoring devices, with lessors retaining title and depreciation benefits. Imaging systems leasing commands the deepest margin pools due to high unit values and specialized servicing requirements, while diagnostic equipment leasing expands fastest among outpatient clinics seeking point-of-care flexibility. Operating leases dominate hospital preference for technology refresh cycles, whereas finance leases appeal to ambulatory surgical centers aiming toward ownership transfer.
FDA quality system regulation and the EU Medical Device Regulation impose traceability and post-market surveillance burdens on lessors managing device fleets across multiple jurisdictions. HIPAA security rule compliance adds data governance complexity when leased devices store protected health information. Stakeholders must monitor evolving CMS reimbursement alignment with lease-versus-buy decisions, as payment model shifts directly influence provider capital allocation priorities.
Market Dynamics
Hospital balance-sheet pressure is compressing capital expenditure cycles, forcing providers to outsource imaging fleet ownership to specialized lessors who assume residual value risk and compliance burdens.
Growth Catalysts
- EU Medical Device Regulation:Mandatory post-market surveillance and traceability requirements are accelerating hospital preference for operating leases that transfer regulatory liability to lessors.
- Acute care hospital sector:German public-private partnership frameworks explicitly favor operational leasing over direct procurement, embedding lease structures into public health infrastructure planning.
- Diagnostic imaging modality refresh:MRI and CT technology cycles averaging 5-7 years are electrifying demand for technology-upgrade clauses embedded in lease contracts.
Market Restraints
- Residual value volatility:Rapid obsolescence in imaging systems compresses lessor recovery rates on secondary markets, particularly for CT scanners beyond 36-month lease terms.
- Supply concentration:Three OEMs control 78% of high-field MRI manufacturing, limiting lessor bargaining power on volume procurement and service access.
- FDA quality system regulation:Device master file obligations and complaint handling requirements impose fixed compliance costs that erode margins on short-term monitoring equipment leases.
Strategic Opportunities
- Outpatient clinic expansion:Point-of-care diagnostic leasing remains underpenetrated in ambulatory settings, where 12-24 month terms match procedure volume uncertainty.
- Refurbished modality channels:Secondary-market imaging systems certified to OEM specifications open mid-market access for independent diagnostic centers.
- HIPAA security rule alignment:Data governance bundling with lease terms creates differentiation for lessors managing connected device fleets storing protected health information.
Industry Challenges
- Clinical engineering talent scarcity:Biomedical technician certification requirements for multi-vendor imaging maintenance outpace training pipeline capacity, constraining service bundling.
- Integration complexity:Leased devices must interface with hospital information systems and electronic health record platforms, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Leasing Market |
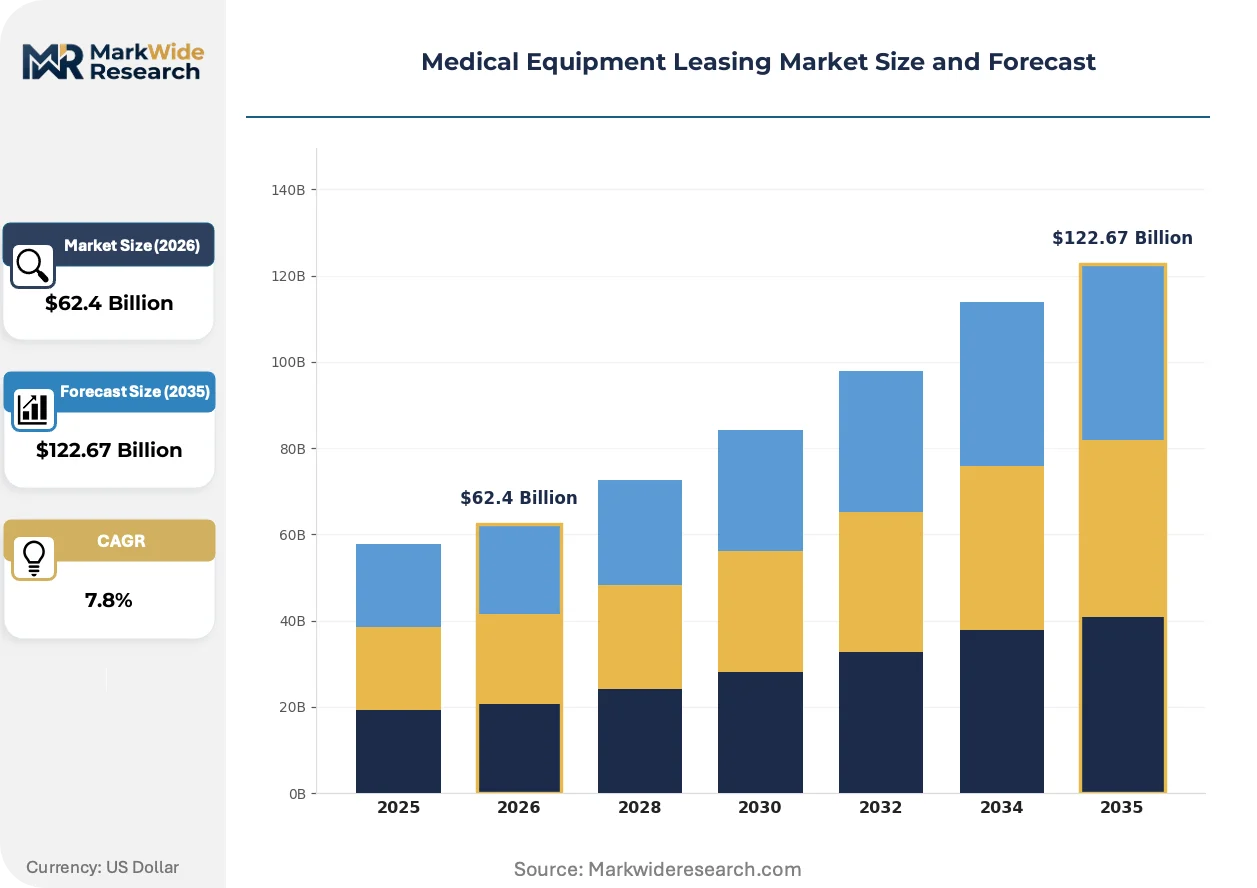
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $122.67 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Imaging Systems, Surgical Instruments, Diagnostic Equipment, Patient Monitors Lease Type: Operating Lease, Finance Lease, Sale and Leaseback, Short-Term Lease End User: Hospitals, Clinics, Diagnostic Centers, Rehabilitation Facilities Geographical Segment: North America, Europe, Asia-Pacific, Latin America |
| Companies Covered | Oak Leasing, Rotech Healthcare, De Lage Landen International, Med One Group, Agiliti, GE Capital, National Technology Leasing, Far East Horizon, Siemens Financial Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Leasing Market Trends and Innovations
Digital connectivity and regulatory convergence are transforming equipment leasing from a financing mechanism into an integrated service architecture. Lessors now compete on data capabilities and compliance automation rather than capital cost alone.
Artificial intelligence-enabled diagnostic software is electrifying imaging system valuation models. Siemens and GE Healthcare embed AI reconstruction algorithms into CT and MRI platforms, enabling faster scan protocols and reduced contrast dosing. Hospital radiology departments are prioritizing lease contracts with embedded software upgrade rights, compressing traditional hardware-centric depreciation schedules.
The EU Medical Device Regulation's Unique Device Identification mandate is reshaping lessor fleet management systems. Device traceability from manufacture to decommissioning now requires centralized registry compliance, driving investment in blockchain-based asset tracking. German and French hospital networks are selecting lessors based on automated UDI submission capabilities, filtering out smaller regional competitors.
Subscription-based equipment access is displacing traditional term structures in outpatient settings. Ambulatory surgical centers now prefer per-procedure pricing models for laparoscopic towers and anesthesia machines, transferring utilization risk to lessors. This shift concentrates in Texas and Florida markets where procedure volume volatility exceeds national averages.
Medical Equipment Leasing Market Segmentation
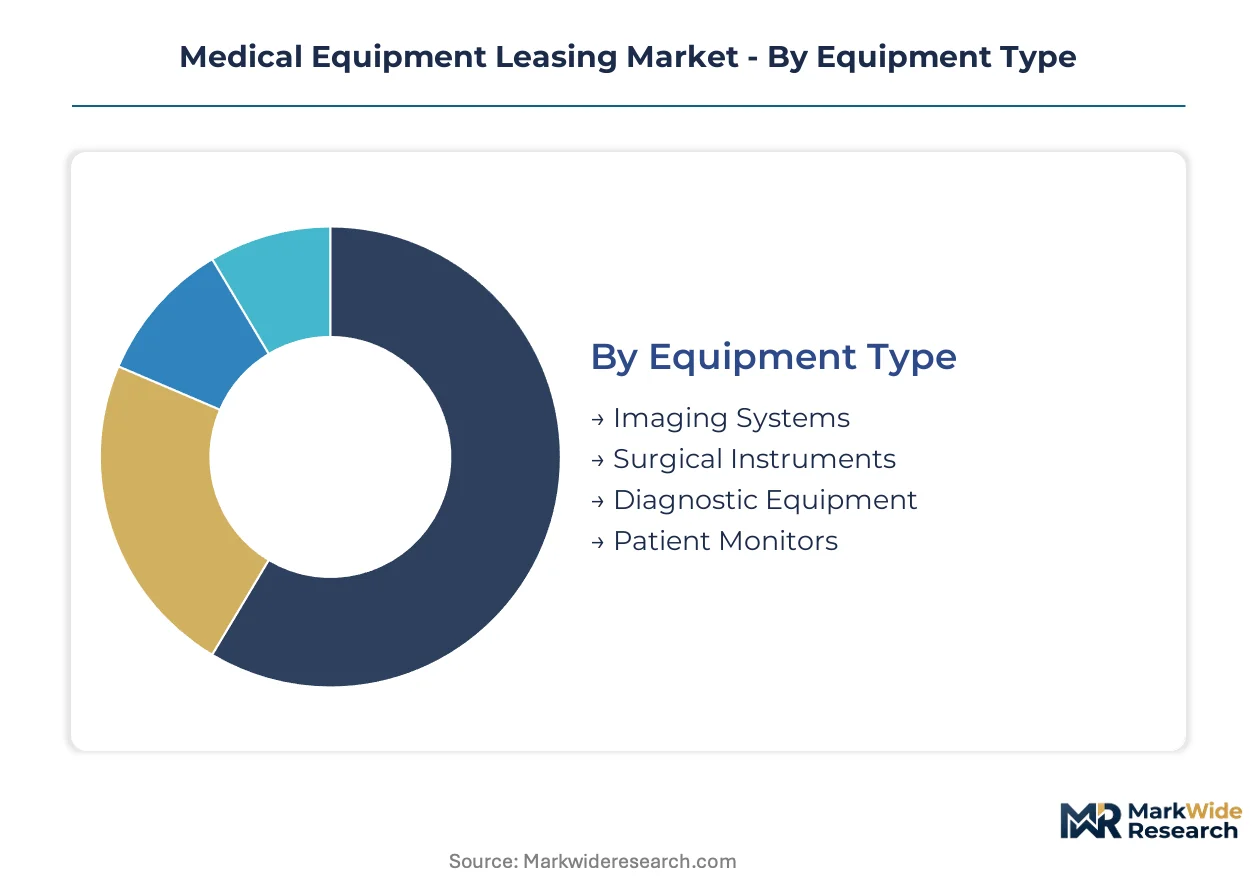
Equipment leasing structures in healthcare diverge sharply by capital intensity, regulatory exposure, and technology refresh cycles. Segment boundaries determine lessor risk allocation, residual value modeling, and service bundling economics across provider networks.
Equipment Type:
Standalone diagnostic platforms command discrete lease structures with dedicated maintenance contracts, while embedded surgical systems require integration with hospital infrastructure and sterile processing workflows.
- Imaging Systems:MRI, CT, and PET-CT platforms carry unit values exceeding two million dollars, necessitating 48–72 month lease terms with technology-upgrade clauses. German acute care hospitals concentrate demand through public-private partnership frameworks that embed operating leases into infrastructure planning.
- Diagnostic Equipment:Point-of-care analyzers and laboratory automation systems span immunoassay, hematology, and molecular diagnostics modalities. Outpatient clinics in Texas and Florida drive fastest expansion through 12–24 month terms matching procedure volume uncertainty.
- Surgical Instruments:Laparoscopic towers, robotic surgical systems, and anesthesia platforms integrate with operating room infrastructure and require sterile processing compatibility.
- Patient Monitors:Bedside telemetry and multi-parameter devices serve lower acuity settings with shorter replacement cycles and standardized connectivity protocols.
Volume placements concentrate in Imaging Systems; the faster expansion belongs to Diagnostic Equipment.
Lease Type:
Contract structures distribute ownership risk, depreciation benefits, and residual value exposure asymmetrically between lessor and provider.
- Operating Lease:Lessor retains title and depreciation while provider obtains use rights without balance-sheet capitalization. Hospital networks facing CMS reimbursement compression prefer this structure for technology refresh flexibility.
- Finance Lease:Provider assumes substantially all risks and rewards of ownership, with transfer of title at term completion. Ambulatory surgical centers targeting ownership transfer select this structure for equipment with 10-year service lifespans.
- Sale and Leaseback:Provider monetizes owned equipment to improve liquidity while retaining operational access through lease payments.
- Short-Term Lease:Per-procedure or seasonal arrangements transfer utilization risk to lessors for equipment with demand volatility.
Operating leases dominate hospital preference; finance leases are climbing the fastest among independent surgical centers.
End User:
Provider scale and reimbursement model determine lease term preferences, maintenance bundling requirements, and compliance complexity.
- Hospitals:Integrated delivery networks manage multi-vendor imaging fleets through master lease agreements with clinical engineering integration. Balance-sheet pressure from value-based care transitions accelerates third-party equipment financing adoption.
- Clinics:Primary care and specialty outpatient settings prioritize point-of-care diagnostic flexibility with shorter terms aligned to patient volume fluctuations.
- Diagnostic Centers:Independent imaging facilities concentrate refurbished modality demand, occupying mid-market positioning between premium new-equipment finance and auction resale channels.
- Rehabilitation Facilities:Physical therapy and post-acute settings lease mobility devices and therapeutic equipment with lower capital intensity and standardized maintenance protocols.
Hospital networks anchor placement volume; diagnostic centers are gaining share fastest through refurbished channel expansion.
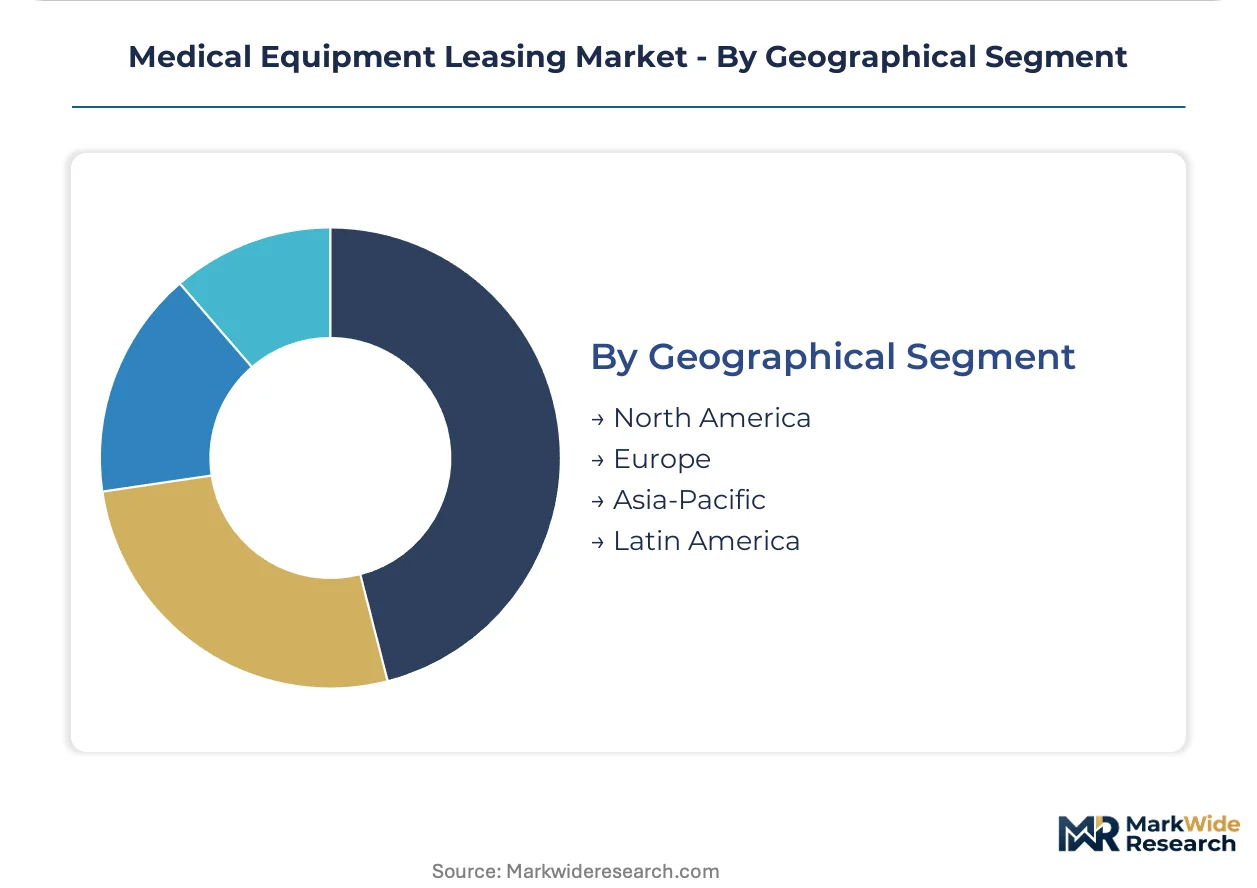
Geographical Segment:
Regulatory frameworks and healthcare financing models create distinct leasing maturity profiles across regional markets.
- North America:United States hospital capital planning consolidates around third-party financing as balance-sheet pressure intensifies, with FDA quality system regulation and HIPAA security rule compliance shaping lessor obligations.
- Europe:Germany's public-private partnership frameworks explicitly favor operational leasing over direct procurement, while EU Medical Device Regulation traceability mandates filter regional competitors based on automated compliance capabilities.
- Asia-Pacific:China's diagnostic imaging expansion and Japan's aging infrastructure replacement create divergent demand profiles across hospital tier systems.
- Latin America:Brazil's independent diagnostic center growth and Mexico's medical tourism infrastructure development concentrate mid-market equipment demand.
North America holds placement concentration; Asia-Pacific shows steepest expansion trajectory through hospital network consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German acute care infrastructure anchors European leasing demand, while US hospital networks and Chinese diagnostic expansion shape divergent regional trajectories across the analysis window.
United States
Integrated delivery networks in Texas and Florida compress capital expenditure cycles through third-party imaging fleet financing. FDA quality system regulation and HIPAA security rule compliance reshape lessor obligations for connected device fleets. The Greater Boston cluster concentrates clinical engineering talent pools serving multi-vendor maintenance contracts.
Germany
Public-private partnership frameworks in Bavaria and North Rhine-Westphalia embed operating leases into hospital infrastructure planning. EU Medical Device Regulation traceability mandates filter regional competitors based on automated UDI submission capabilities. The Baden-Württemberg medical technology corridor hosts lessor service integration hubs.
China
Tier-one hospital network consolidation in the Yangtze River Delta and Pearl River Delta electrifies diagnostic imaging demand. NMPA device registration requirements and dual carbon goals influence lease term structures for energy-intensive MRI platforms. The Beijing-Tianjin-Hebei cluster concentrates refurbished modality certification facilities.
Japan
Aging infrastructure replacement in Kanto and Kansai regions drives technology refresh cycles for CT and PET-CT platforms. PMDA post-market surveillance requirements align with lessor fleet management system investments. The Nagoya medical device manufacturing belt supplies regional lessor procurement channels.
United Kingdom
NHS capital constraints accelerate operating lease preference for imaging systems across London and Southeast trusts. MHRA device registration and UKCA marking transitions create compliance complexity for cross-border lessor operations. The Midlands cluster concentrates independent diagnostic center expansion through refurbished modality channels.
Medical Equipment Leasing Market Competitive Landscape
Global majors compete with regional champions across captive finance structures and clinical engineering integration capabilities. The vendor base organizes into three tiers: OEM-captive finance arms controlling premium imaging contracts, independent lessors competing on refurbished modality access, and regional specialists serving ambulatory surgical centers. Consolidation pressures concentrate among mid-market independents seeking scale for service bundling economics. Dominant competitive moves include M&A for clinical engineering talent acquisition and strategic partnerships for technology-upgrade clause embedding.
Within the OEM-captive tier, Siemens Financial Services and GE Capital exemplify integrated finance structures securing long-term imaging contracts. Among independent specialists, Agiliti occupies a position emphasizing clinical engineering bundling, while Med One Group anchors the refurbished modality niche between premium new-equipment finance and auction resale channels. Oak Leasing and De Lage Landen International represent regional champions competing on compliance automation and shorter-term outpatient clinic structures.
| Leading Market Players |
|---|
| Oak Leasing |
| Rotech Healthcare |
| De Lage Landen International |
| Med One Group |
| Agiliti |
| GE Capital |
| National Technology Leasing |
| Far East Horizon |
| Siemens Financial Services |
| Others |
Pricing and Supply Chain Analysis
Copper futures on the London Metal Exchange and rare earth oxide benchmarks from China's Baotou region cascade through MRI magnet manufacturing costs, compressing lessor margins on high-field imaging contracts while amplifying price spreads between OEM-certified refurbished systems and premium new-equipment leases.
Pricing Analysis
Warranty and clinical engineering bundling separate premium lease tiers from unbundled base structures. Three-tier pricing stratifies across comprehensive service-inclusive contracts, limited warranty arrangements, and bare equipment-only terms. Price differentiation hinges on OEM certification status and multi-vendor maintenance capability. Cost compression in the refurbished modality segment is intensifying because secondary-market supply expansion outpaces hospital budget constraints. Independent diagnostic centers exhibit highest price sensitivity; integrated delivery networks prioritize total cost of ownership over headline rates.
Supply Chain Analysis
Dual-sourcing mandates from US hospital procurement committees and German public-private partnership frameworks require lessors to qualify multiple OEM service networks and independent clinical engineering providers. Manufacturing concentration rests on Germany, Japan, and the United States for high-field MRI magnet production, with China dominating rare earth element refining. Superconducting wire, helium recovery systems, and gradient coil assemblies constitute critical component dependencies. Single-source vulnerability in liquid helium supply chains poses structural risk. Distribution runs through OEM-captive finance arms, independent lessor direct sales, and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical equipment leasing sector is navigating a technology-transition phase where artificial intelligence-enabled diagnostic software is supplanting hardware-centric valuation models, forcing lessors to restructure residual value assumptions and service bundling economics.
For Market Incumbents: Anchor market position through captive control of clinical engineering talent pools in Greater Boston and Baden-Württemberg corridors, while embedding technology-upgrade clauses into imaging contracts to counter rapid AI software obsolescence. Deepen backward integration into refurbished modality certification facilities to defend margin position against auction resale channels.
For New Entrants and Emerging Players: Begin with per-procedure pricing pilots in Texas and Florida ambulatory surgical centers, where utilization volatility exceeds national averages and traditional term structures fail. Target HIPAA security rule compliance bundling as the most penetrable service wedge, leveraging data governance gaps among regional competitors.
For Investors and Strategic Acquirers: The window for entry favors clinical engineering-integrated mid-market lessors with automated EU Medical Device Regulation compliance infrastructure. Long-term viability centers on service bundling economics rather than capital deployment scale. Monitor NMPA device registration harmonization with EU MDR as the signal for China market entry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Upgrade Clause Embedding | AI software refresh rights in MRI contracts protect Siemens Financial Services against hardware depreciation compression. |
| Clinical Engineering Talent Acquisition | Biomedical technician certification programs in Boston corridor secure Agiliti's multi-vendor maintenance differentiation. |
| Automated UDI Compliance Infrastructure | Blockchain-based asset tracking enables Oak Leasing to meet German hospital network traceability mandates. |
| Refurbished Modality Certification Expansion | OEM-specified secondary-market imaging opens mid-market access for Med One Group between premium finance and auction channels. |
| Per-Procedure Pricing Pilot Programs | Utilization risk transfer to lessors matches Texas and Florida ASC volume volatility with 12-24 month term flexibility. |
Research Methodology
Document review covered FDA quality system regulation filings, EU Medical Device Regulation technical documentation, hospital procurement databases, and GPO contract repositories, complemented by interviews with hospital purchasing committee directors, biomedical engineering managers, lessor portfolio risk officers, and clinical engineering service heads. Secondary validation drew from CMS reimbursement data, SEC equipment finance disclosures, and customs records for imaging system imports. Bottom-up lease volume aggregation and top-down healthcare capital expenditure modeling were triangulated against OEM shipment data.
Market size outputs and segment splits across the projection horizon reflect equipment type, lease structure, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycles, technology refresh velocity, and reimbursement model shifts. Forecast inputs incorporated MRI and CT modality obsolescence curves, helium supply constraints, and AI software adoption trajectories in radiology departments.
Regulatory harmonization delays, hospital capital budget freezes, and clinical engineering certification pipeline bottlenecks are the dominant revision risks to the outlook. Deviation in FDA or NMPA device registration timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Global Blood Viscometer Market