
 Medical Fluid Bags Market | 2026-2036
Medical Fluid Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Fluid Bags Market Analysis
Modular IV bag configurations with integrated ports and closed-system transfer devices is shifting procurement criteria toward bundled solutions that reduce contamination risk. Baxter International Inc. leverages its vertically integrated polymer compounding capabilities to control raw material quality. B. Braun Melsungen AG sustains manufacturing scale across European and Asian production networks. Fresenius Kabi AG anchors its position through specialization in parenteral nutrition-compatible bag formulations.
Medical fluid bags are sterile, flexible containers fabricated from polyvinyl chloride, polypropylene, or ethylene vinyl acetate, designed for the aseptic storage and administration of intravenous solutions, blood components, or drainage collection with typical capacities ranging from 50 mL to 4,000 mL and compliance to USP Class VI biocompatibility standards. IV bags occupy the largest revenue pool due to universal utilization across acute care settings, while blood bags command premium pricing tied to specialized anticoagulant coatings and cold-chain integrity requirements. Dialysis bags represent the fastest-expanding application segment as home-based peritoneal dialysis protocols gain clinical traction.
The FDA enforces 21 CFR Part 820 quality system regulations for medical device manufacturing, while ISO 10993 governs biological evaluation of bag polymers in contact with bodily fluids; the EU MDR imposes stricter clinical evidence requirements for Class IIa fluid containers, elevating compliance costs for market access. The EPA regulates phthalate plasticizer emissions from PVC production facilities, pressuring manufacturers toward non-DEHP material transitions. Stakeholders must monitor evolving biocompatibility standards and polymer substitution timelines to align R&D pipelines with regulatory trajectories.
Market Dynamics
The transition from DEHP-plasticized PVC to non-phthalate polymers is compressing incumbent material supply chains while elevating biocompatibility certification costs for bag manufacturers serving FDA and EU MDR jurisdictions.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter Class IIa device requirements are accelerating bag manufacturer consolidation, favoring firms with in-house toxicology testing infrastructure.
- Home-based peritoneal dialysis protocols:Nephrology departments in tertiary hospitals are expanding ambulatory dialysis programs, multiplying demand for 2,000-4,000 mL drainage bags with integrated sterile connectors.
- Closed-system transfer device adoption:Oncology pharmacies are mandating needle-free bag-to-bag transfer systems to reduce hazardous drug exposure, pulling demand toward integrated port configurations.
Market Restraints
- Ethylene vinyl acetate resin supply concentration:Specialty polymer production clusters in Germany and Japan create single-source vulnerability for non-PVC bag manufacturers.
- ISO 10993-18 chemical characterization costs:Extractables and leachables testing for novel polymer formulations extends product development timelines by 18-24 months.
- Glass bottle substitution in premium parenteral nutrition:High-barrier glass containers retain preference for lipid emulsion storage, capping polymer bag penetration in neonatal intensive care.
Strategic Opportunities
- Indian tertiary hospital expansion:CDSCO's streamlined medical device registration pathway is opening procurement contracts for 500+ bed facilities in Maharashtra and Karnataka.
- RFID-enabled bag tracking:Convergence of polymer extrusion with printed electronics enables unit-level cold-chain verification for blood component logistics.
- Japan's home healthcare subsidy expansion:METI reimbursement adjustments for peritoneal dialysis supplies are creating direct-to-patient distribution channels bypassing hospital purchasing.
Industry Challenges
- Polymer compounding technician scarcity:Specialized expertise in medical-grade PVC and TPE formulation is concentrating among aging workforces in Ohio and Bavaria.
- Cleanroom capacity expansion timelines:ISO 14644 Class 7 certification for new extrusion lines requires 14-18 month validation cycles, constraining volume response to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Fluid Bags Market |
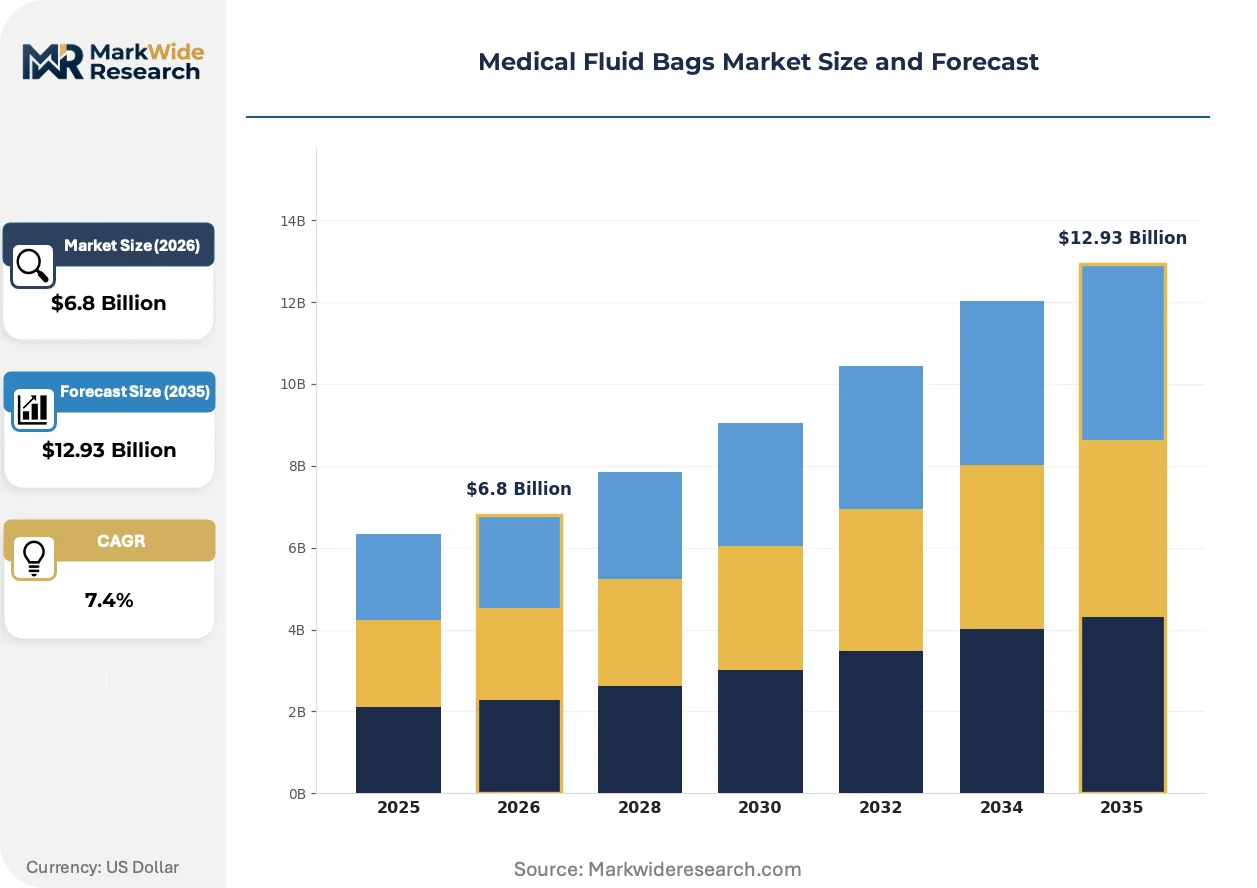
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Bags, Blood Bags, Urine Bags, Dialysis Bags Material: Polyvinyl Chloride, Polypropylene, Silicone, Ethylene Vinyl Acetate Application: Intravenous Therapy, Blood Transfusion, Urinary Catheterization, Dialysis End User: Hospitals, Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Fresenius Kabi AG, ICU Medical Inc., Terumo Corporation, Sippex IV Bag Solutions, Otsuka Pharmaceutical Co., Ltd., SSY Group Limited, Renolit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Fluid Bags Market Emerging Trajectories
Material science advances and regulatory chemistry requirements are converging to redefine polymer selection criteria, with downstream consequences for manufacturing equipment, supplier relationships, and end-user training protocols.
Multilayer coextrusion films incorporating cyclic olefin polymer barrier layers are absorbing the functional requirements previously met by DEHP-plasticized PVC in blood storage applications. Blood banks in the United States are validating these formulations for 42-day red cell storage. The technology is absorbing market share from conventional PVC while forcing resin suppliers to expand cyclic olefin polymer capacity.
REACH Annex XVII restrictions on phthalate plasticizers are compelling European manufacturers to eliminate DEHP from neonatal and maternity ward fluid bags by 2025. The regulation is triggering reformulation investments across polypropylene and TPE alternatives. French and German hospitals are now specifying non-DEHP materials in procurement tenders, compressing PVC bag volumes in Western Europe.
Consolidated purchasing by United States hospital networks is unbundling fluid bag procurement from traditional distributor bundles. Integrated delivery networks in Texas and Florida are negotiating direct manufacturer contracts for standardized bag configurations. This behavioral shift is most visible in multi-hospital systems exceeding 50 facilities, where procurement departments are centralizing specification authority.
Medical Fluid Bags Market Segmentation
Medical fluid bag procurement decisions cascade through multiple technical dimensions, from polymer biocompatibility specifications to end-use sterility requirements. Each segmentation axis carries distinct regulatory footprints and margin structures that reshape competitive positioning across manufacturer portfolios.
Product Type:
Replacement cycles vary sharply across fluid containment categories, with acute care settings driving shorter upgrade intervals for high-turnover disposables versus capital-intensive blood storage systems.
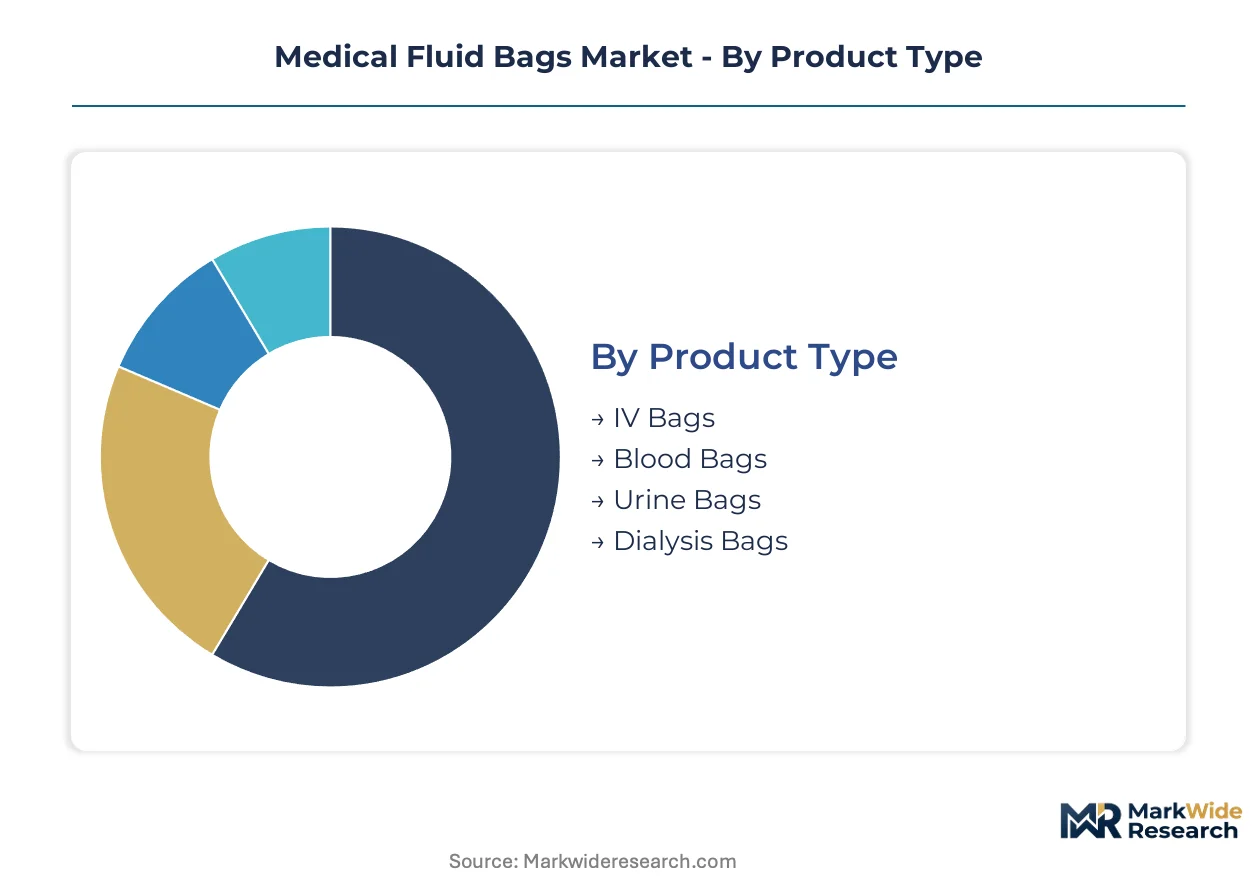
- IV Bags:Flexible polymeric containers ranging from 50 mL to 1,000 mL for parenteral solution delivery, fabricated from DEHP-free PVC or polypropylene multilayer films. Demand concentrates in United States tertiary hospitals where surgical throughput sustains bulk purchasing agreements; closed-system transfer device integration is compressing supplier margins while elevating technical qualification barriers.
- Blood Bags:Specialized anticoagulant-coated containers with cold-chain integrity specifications for 42-day red cell storage, incorporating cyclic olefin polymer barrier layers. United States blood banks are validating non-PVC formulations, with FDA biocompatibility testing timelines extending procurement decisions by 18-24 months.
- Urine Bags:Drainage collection systems with anti-reflux valves and graduated volume markings, typically 2,000 mL capacity.
- Dialysis Bags:Peritoneal dialysis drainage containers, 2,000-4,000 mL with sterile connectors.
IV bags sit at the top of the volume ranking, with dialysis bags climbing the fastest.
Material:
Cost tiers stratify sharply between commodity PVC compounds and specialty thermoplastic elastomers, with regulatory chemistry mandates forcing accelerated substitution timelines.
- Polyvinyl Chloride:DEHP-plasticized formulations face REACH Annex XVII phaseouts in Europe by 2025, compelling reformulation investments. German and French hospital tenders now specify non-phthalate alternatives, compressing incumbent volumes.
- Polypropylene:High-clarity random copolymers with gamma sterilization compatibility for parenteral nutrition applications. Japanese manufacturers are expanding compounding capacity for multilayer coextrusion films.
- Silicone:Platinum-cured elastomers for extended-dwelling urinary catheterization systems.
- Ethylene Vinyl Acetate:Specialty resin production clusters in Germany and Japan create supply vulnerability for non-PVC bag manufacturers.
Polyvinyl chloride retains the dominant volume position, though polypropylene is gaining share fastest as DEHP substitution accelerates.
Application:
Customer workflow integration determines specification authority, with pharmacy departments controlling oncology fluid protocols versus nursing units driving urinary drainage procurement.
- Intravenous Therapy:Universal acute care utilization spanning hydration, medication delivery, and electrolyte replacement. United States integrated delivery networks exceeding 50 facilities are centralizing procurement specifications, unbundling bags from distributor bundles.
- Blood Transfusion:Specialized handling protocols with temperature monitoring and irradiation requirements.
- Urinary Catheterization:Intermittent and indwelling catheter drainage systems for post-operative and long-term care settings.
- Dialysis:Home-based peritoneal dialysis protocols are multiplying demand for larger-capacity drainage bags with integrated sterile connectors; Japan's METI reimbursement adjustments are creating direct-to-patient distribution channels.
Intravenous therapy commands the highest procedure volume, with dialysis application expanding most quickly.
End User:
Procurement sophistication varies across facility types, with hospital networks leveraging scale economics versus home care channels requiring patient-training infrastructure.
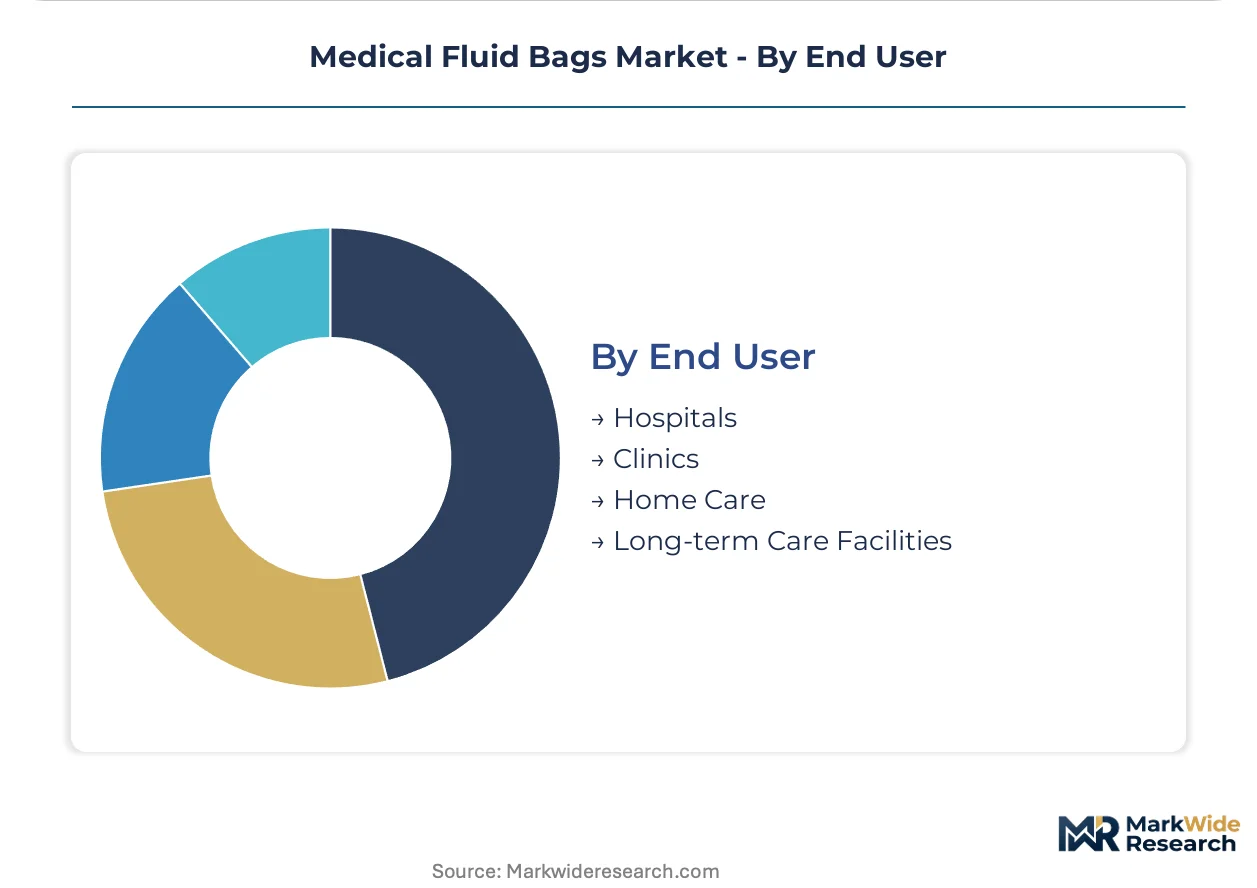
- Hospitals:500+ bed tertiary facilities in Maharashtra and Karnataka are opening procurement contracts through CDSCO's streamlined registration pathway. Cleanroom capacity expansion timelines of 14-18 months constrain volume response to demand spikes.
- Clinics:Outpatient infusion centers with standardized bag configurations.
- Home Care:Direct-to-patient distribution channels bypassing hospital purchasing in Japan's subsidy-expanded peritoneal dialysis market.
- Long-term Care Facilities:Extended-dwelling catheterization systems with cost-optimized specifications.
Hospitals dominate procurement volume, with home care climbing the fastest as reimbursement shifts enable direct distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical fluid bag industry traces its modern origins to post-war polymer chemistry advances in Germany and the United States, where PVC compounding for sterile containers first achieved commercial scale. Tertiary hospital networks and specialized polymer production clusters now concentrate demand and supply across five distinct national markets.
United States
Aging demographics and chronic disease prevalence sustain high utilization rates across 500+ bed integrated delivery networks in Texas and Florida. FDA's 21 CFR Part 820 quality system regulations govern manufacturing compliance, while the EPA regulates phthalate plasticizer emissions from PVC production facilities. Ohio's polymer compounding corridor hosts specialized technician expertise for medical-grade PVC and TPE formulation.
Germany
REACH Annex XVII restrictions on phthalate plasticizers are compelling manufacturers to eliminate DEHP from neonatal and maternity ward fluid bags by 2025. ECHA chemical safety assessments drive reformulation investments across polypropylene and TPE alternatives. Bavaria's resin production clusters concentrate specialty ethylene vinyl acetate supply for non-PVC bag manufacturers.
Japan
METI reimbursement adjustments for peritoneal dialysis supplies are creating direct-to-patient distribution channels that bypass hospital purchasing. PMDA biocompatibility standards align with ISO 10993 for polymer evaluation. Nagoya's medical device manufacturing belt is expanding cleanroom capacity for multilayer coextrusion film production.
India
CDSCO's streamlined medical device registration pathway is opening procurement contracts for 500+ bed facilities in Maharashtra and Karnataka. Rising surgical volumes in tertiary hospitals are expanding demand for intravenous fluid containment systems. Mumbai-Pune pharmaceutical corridor is attracting contract manufacturing investments for export-oriented bag production.
France
French hospital tenders now specify non-DEHP materials, compressing PVC bag volumes in Western Europe. ANSM medical device vigilance requirements enforce post-market surveillance for fluid container safety. Lyon-Grenoble polymer research cluster is advancing cyclic olefin polymer barrier layer validation for blood storage applications.
Medical Fluid Bags Market Vendor Landscape
The competitive structure tilts toward vertically integrated polymer specialists with captive compounding capabilities. Three to five multinational conglomerates with diversified medical device portfolios dominate volume positions, while mid-scale regional fabricators compete on customization and local regulatory navigation. Two strategic archetypes prevail: integrated polymer-to-bag manufacturers controlling raw material quality, and formulation specialists concentrating on parenteral nutrition-compatible designs. Capacity expansion and strategic partnerships represent the dominant competitive moves, with ISO 14644 Class 7 cleanroom certification timelines constraining rapid volume response.
Among diversified healthcare conglomerates, Baxter International Inc., B. Braun Melsungen AG, and Fresenius Kabi AG occupy positions exemplifying distinct strategic vectors. Baxter International Inc. represents the integrated polymer compounding archetype with upstream control over raw material quality. B. Braun Melsungen AG exemplifies manufacturing scale distributed across European and Asian production networks. Fresenius Kabi AG anchors the formulation specialization tier through focus on parenteral nutrition-compatible bag designs. These three entities collectively illustrate how competitive positioning derives from material science depth, geographic manufacturing footprint, and clinical application focus.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| ICU Medical Inc. |
| Terumo Corporation |
| Sippex IV Bag Solutions |
| Otsuka Pharmaceutical Co., Ltd. |
| SSY Group Limited |
| Renolit Group |
| Others |
Supply Flow & Price Mechanics
Ethylene vinyl acetate resin costs cascade through medical fluid bag manufacturing, with specialty polymer pricing in Germany and Japan setting tier boundaries that separate premium multilayer coextrusion films from standard PVC formulations downstream.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between bag manufacturers and hospital integrated delivery networks, with price differentiation resting on biocompatibility certification tier and volume scale commitments. Three-tier pricing structure across premium cyclic olefin polymer barrier layers, standard DEHP-free PVC, and economy-grade polypropylene separates blood storage applications from routine hydration therapy. Margins are tightening due to ISO 10993-18 extractables testing cost absorption. Oncology pharmacies exhibit lowest price sensitivity given hazardous drug handling mandates, while long-term care facilities drive hardest volume negotiations.
Supply Chain Analysis
Freight costs for temperature-sensitive polymer resins have elevated landed costs for European and Asian manufacturers serving North American hospital networks. Raw material production clusters in Germany, Japan, and the United States supply medical-grade PVC, polypropylene, and ethylene vinyl acetate to compounding facilities. Single-source vulnerability concentrates in Bavaria's ethylene vinyl acetate plants and Ohio's specialized technician workforce. Distribution runs through regional medical device distributors with GPO contract administration, though direct manufacturer agreements are proliferating among multi-facility systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
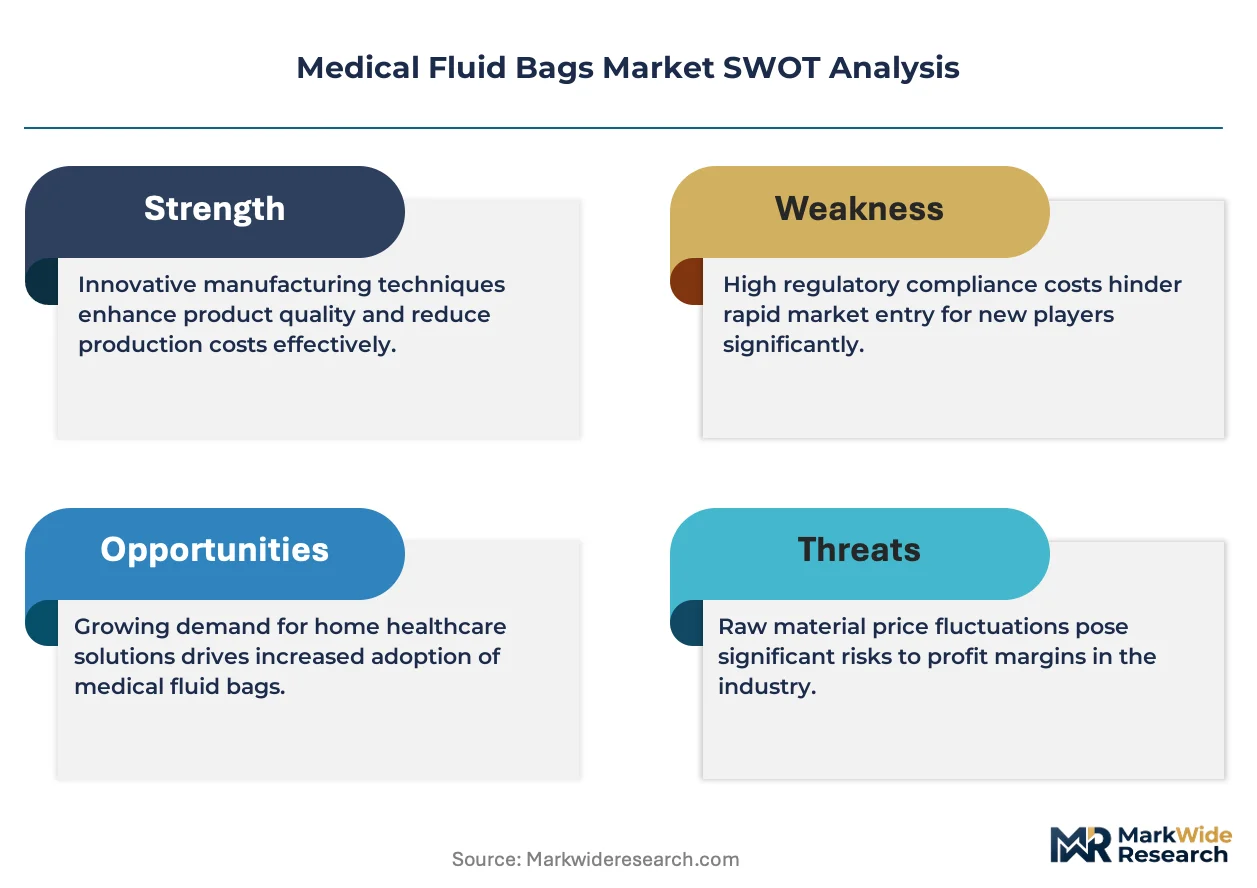
This market offers margin expansion through DEHP substitution-driven premium material shifts, as REACH Annex XVII compliance costs compress commodity PVC volumes while elevating pricing power for validated non-phthalate alternatives.
For Market Incumbents: Anchor market position through captive polymer compounding capacity in Ohio or Bavaria to secure raw material quality control against emerging Asian contract manufacturers. Accelerate ISO 14644 Class 7 cleanroom certification timelines to outpace demand spikes from Indian tertiary hospital expansion. Defend against formulation specialists by integrating closed-system transfer device engineering in-house.
For New Entrants and Emerging Players: Enter via CDSCO's streamlined registration pathway for Maharashtra and Karnataka 500+ bed facilities, where incumbent distributor relationships remain underdeveloped. Target home care peritoneal dialysis segments in Japan's METI-subsidized direct-to-patient channels. Lead with RFID-enabled cold-chain tracking as differentiated value proposition against commodity bag suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 10993 toxicology testing infrastructure concentrates among aging technical workforces in Ohio and Bavaria. Five-to-ten year viability favors targets with validated non-PVC formulations and hospital GPO contract tenure. Monitor FDA biocompatibility testing queue lengths as inflection signal for procurement decision delays benefiting incumbents with approved alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Non-DEHP Material Transition | REACH Annex XVII compliance secures European hospital procurement eligibility against PVC incumbents. |
| Cleanroom Capacity Expansion | ISO 14644 Class 7 certification enables volume response to Indian tertiary hospital demand spikes. |
| Closed-System Transfer Device Integration | Oncology pharmacy mandates for hazardous drug handling elevate technical qualification barriers. |
| RFID-Enabled Cold-Chain Tracking | Blood bank validation requirements for 42-day red cell storage create premium pricing tier. |
| Direct-to-Patient Distribution | Japan's METI reimbursement adjustments bypass hospital purchasing for peritoneal dialysis supplies. |
Methodological Framework
Multiple input streams — primary interviews with polymer compounding technicians, hospital procurement managers, and GPO contracts administrators, plus secondary validation through FDA 510(k) filings, CDSCO registration databases, and ECHA chemical safety assessments — were reconciled through bottom-up and top-down triangulation. Conversations with biomedical engineers and nephrology department heads informed clinical workflow integration assumptions. Trade data from German and Japanese resin suppliers anchored material cost modeling.
Data-stream reconciliation across product type, material formulation, application workflow, and end-user facility tier generated volume and value outputs across the projection horizon. CAGRs derived from surgical throughput trends, dialysis protocol adoption curves, and regulatory substitution timelines. Hospital bed expansion data from Maharashtra and Karnataka, plus METI reimbursement schedule adjustments, fed geographic demand disaggregation.
Inputs from polymer suppliers and hospital purchasing committees were available through the study window; gaps in real-time DEHP phaseout compliance rates introduce uncertainty bands around European volume forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Tanning Units Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Indirect Calorimeter Market