
 Healthcare Digital Signage Market | 2026-2036
Healthcare Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Digital Signage Market Analytics
4K and medical-grade color calibration specification tiers are rotating upward as hospital procurement committees prioritize diagnostic-adjacent accuracy over consumer-grade brightness metrics. Samsung Electronics Co., Ltd. leverages its semiconductor foundry scale to captive-supply display driver ICs for healthcare panels. LG Electronics anchors North American hospital networks through direct integration with nurse call and EMR platforms. Koninklijke Philips N.V. differentiates via patient monitoring ecosystem tie-ins that bundle signage with bedside devices.
Healthcare digital signage denotes networked visual display systems engineered for clinical environments with antimicrobial surface treatments, IEC 60601-1 electromagnetic compatibility certification, and 24/7 operational duty cycles designed to deliver patient information, staff alerts, and pharmaceutical messaging. LED Displays command the largest product type position due to falling per-lumen costs and thin-form-factor retrofit compatibility with aging hospital infrastructure. Cloud-based Solutions represent the fastest-expanding technology segment as IT departments centralize content governance across distributed clinic footprints. Wayfinding applications concentrate margin pools through software licensing models that recur annually per deployed screen.
FDA cybersecurity guidance and HIPAA privacy rules compel manufacturers to embed encrypted data transmission and access audit trails, effectively raising engineering barriers for non-specialized entrants. The EU MDR and GDPR frameworks impose parallel conformity requirements for European hospital deployments, favoring vendors with dual-continent certification capabilities. Stakeholders must monitor whether CMS reimbursement policy shifts will codify digital patient engagement as quality metrics, thereby accelerating replacement cycles for non-compliant legacy installations.
Market Dynamics
Hospital consolidation across multi-state health systems is concentrating procurement authority into centralized IT committees that mandate IEC 60601-1 certification and encrypted data transmission as baseline vendor qualifications.
Growth Catalysts
- HIPAA Privacy Rule Enforcement:The Department of Health and Human Services is intensifying audit frequency for patient-facing digital systems, compelling hospitals to replace consumer-grade displays with hardened healthcare-grade alternatives that embed access audit trails.
- LED Cost Compression:Falling per-lumen manufacturing expenses are enabling thin-form-factor retrofit installations within aging hospital infrastructure without structural ceiling modifications.
- Cloud Content Governance:Health system IT departments are centralizing digital signage management across distributed clinic footprints, reducing per-site administrative overhead and enabling real-time emergency messaging deployment.
Market Restraints
- Semiconductor Supply Concentration:Display driver IC fabrication concentrates in East Asian foundries, exposing procurement timelines to geopolitical disruption and foundry allocation priorities.
- Antimicrobial Coating Input Costs:Silver-ion and copper-alloy surface treatments face raw material price volatility that compresses margin on mid-tier product lines.
- Legacy Infrastructure Interoperability:Nurse call and EMR platforms from the 2010s lack API standardization, forcing costly middleware development for seamless signage integration.
Strategic Opportunities
- EU MDR Certification Arbitrage:Vendors holding dual FDA and EU MDR conformity credentials can capture replacement cycles as European hospitals modernize patient engagement infrastructure under stricter electromagnetic compatibility mandates.
- Wayfinding Software Licensing:Annual recurring revenue models per deployed screen are concentrating margin pools away from hardware commoditization toward proprietary navigation algorithms and indoor positioning integration.
- Bedside Device Convergence:Patient monitoring ecosystem bundling—combining signage with vital signs displays and infusion pump interfaces—creates stickier hospital relationships and longer contract durations.
Industry Challenges
- IEC 60601-1 Certification Timeline:Third-party electromagnetic compatibility testing and FDA 510(k) documentation requirements extend product launch cycles by 14-18 months, compressing technology refresh windows.
- Cybersecurity Engineering Talent Scarcity:Embedded systems architects with healthcare data encryption expertise command premium compensation, constraining mid-tier vendor R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Digital Signage Market |
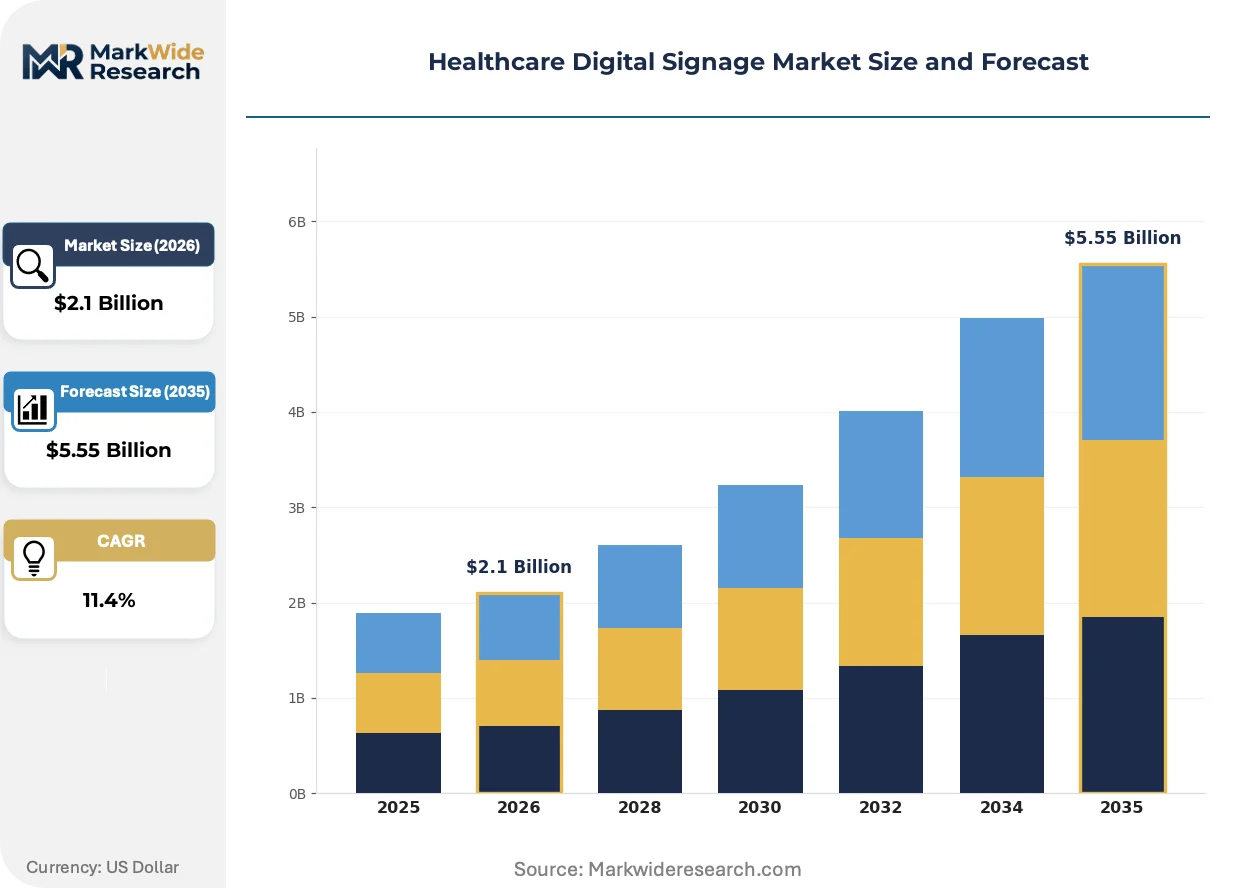
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Displays, LED Displays, Projectors, Digital Billboards Application: Waiting Area, Patient Education, Wayfinding, Internal Communication Technology: Interactive Touchscreen, Wireless Connectivity, Cloud-based Solutions, Content Management Systems End User: Hospitals, Clinics, Medical Centers, Pharmacies |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, Panasonic Holdings Corporation, Koninklijke Philips N.V., Sharp Corporation, Daktronics, Inc., Sony Corporation, Barco, STRATACACHE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Digital Signage Market Evolving Landscape
Medical-grade color calibration is displacing consumer brightness metrics as the primary procurement specification, while cloud-native content management and AI-driven personalization engines reshape competitive differentiation.
MicroLED backlighting technology is displacing conventional edge-lit LED arrays in diagnostic-adjacent applications. Radiology departments and surgical planning units are adopting these panels for DICOM-compliant grayscale accuracy. This displacement is compressing the addressable market for conventional commercial displays in high-acuity clinical zones.
FDA cybersecurity guidance issued under Section 524B of the FD&C Act now mandates premarket submission of software bill of materials and vulnerability management plans for networked medical devices. Manufacturers must embed encrypted transmission protocols and automated patch deployment infrastructure. Small regional integrators lacking dedicated compliance teams are exiting the hospital segment rather than absorbing engineering overhead.
Health system procurement committees are consolidating technology vendor relationships into enterprise framework agreements that span digital signage, patient televisions, and bedside tablets. Single-source contracting is displacing fragmented point solutions purchased by individual departments. This concentration is most visible in United States multi-hospital networks where CIOs report directly to system-level executives rather than facility administrators.
Healthcare Digital Signage Market Segmentation
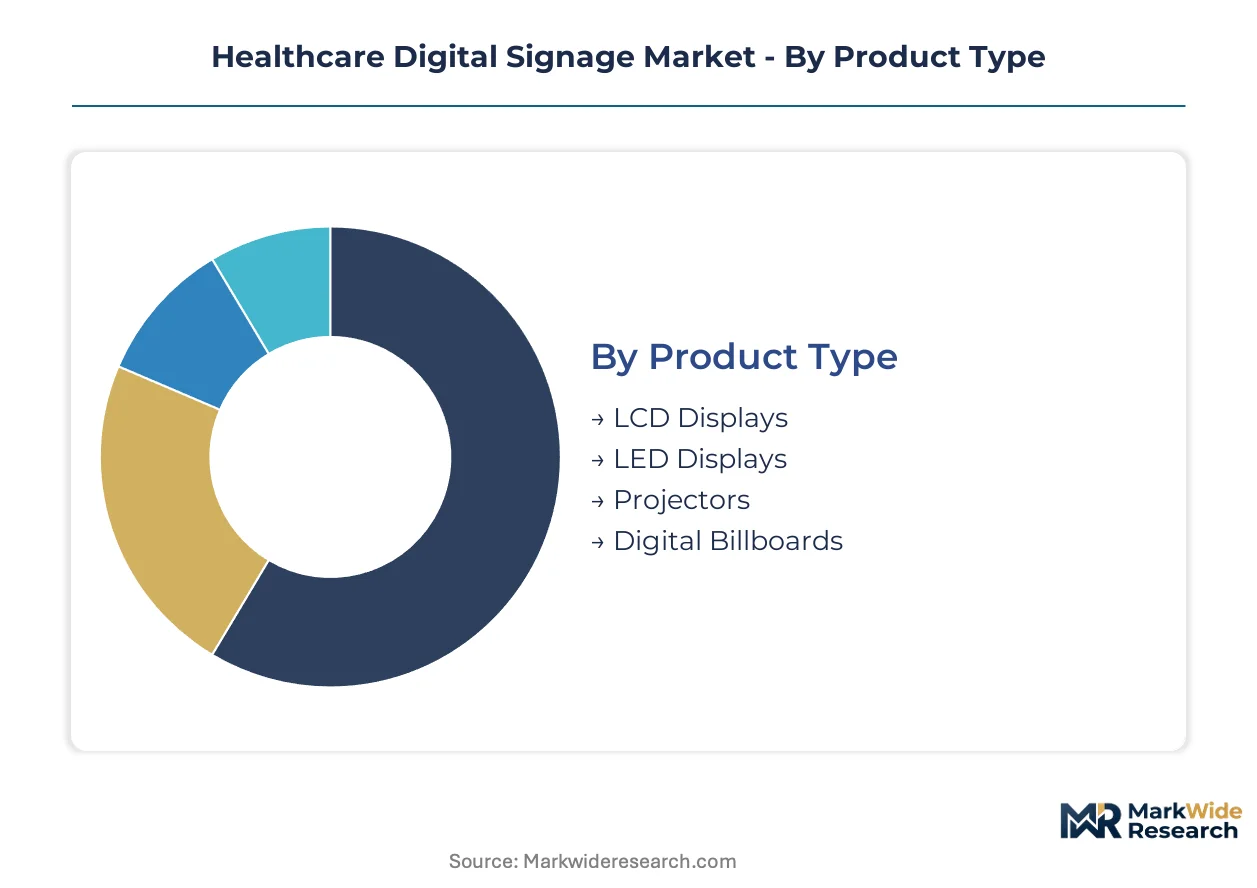
Healthcare digital signage procurement committees evaluate products across four intersecting dimensions: display hardware specifications, clinical use case requirements, infrastructure integration capabilities, and facility scale. Segmentation clarity enables vendors to align certification investments with addressable demand pools and margin profiles.
Product Type:
LED Displays face intensifying substitution pressure from MicroLED backlighting arrays in diagnostic-adjacent zones, while LCD Displays confront margin compression from commoditized consumer panel imports.
- LED Displays:Thin-form-factor solid-state illumination enables retrofit installation within aging ceiling infrastructure without structural modification. Demand concentrates in United States multi-hospital networks where falling per-lumen manufacturing costs support fleet-wide standardization across distributed clinic footprints.
- LCD Displays:Liquid crystal panels with antimicrobial surface treatments and IEC 60601-1 electromagnetic compatibility certification serve budget-constrained departmental deployments. Procurement timelines shorten through established supply chains, though diagnostic accuracy limitations restrict placement to non-clinical zones.
- Projectors:Short-throw laser projection systems occupy temporary installation niches for conference and training facilities where permanent display mounting proves impractical.
- Digital Billboards:Large-format exterior-facing installations deliver pharmaceutical messaging and emergency broadcast capabilities at hospital campus entry points.
LED Displays retain volume leadership; Cloud-based Solutions within Technology holds the steepest expansion curve.
Application:
Procurement authority concentrates in IT committees that prioritize operational efficiency gains over departmental preference, reshaping budget allocation across use cases.
- Wayfinding:Proprietary navigation algorithms and indoor positioning integration command annual recurring software licensing fees per deployed screen. United States health systems with multi-state footprints centralize content governance to reduce per-site administrative overhead and enable real-time emergency messaging deployment.
- Patient Education:HIPAA-compliant content delivery systems embed access audit trails and encrypted transmission protocols mandated by Department of Health and Human Services audit intensification.
- Waiting Area:General information displays with consumer-grade brightness specifications face replacement pressure from hardened healthcare-grade alternatives.
- Internal Communication:Staff alert systems integrate with nurse call platforms through middleware development where 2010s-era EMR installations lack API standardization.
Wayfinding captures margin concentration through software licensing; Patient Education climbs the fastest on regulatory compliance replacement cycles.
Technology:
Engineering talent scarcity constrains vendor R&D bandwidth across encryption-intensive technology tiers, favoring incumbents with dedicated compliance teams.
- Cloud-based Solutions:Centralized content governance architectures reduce distributed clinic administrative burden while enabling instantaneous emergency broadcast deployment. Health system IT departments in United States multi-hospital networks mandate these platforms for enterprise framework agreements spanning signage, patient televisions, and bedside tablets.
- Interactive Touchscreen:Antimicrobial glass surfaces with capacitive response layers serve patient check-in and wayfinding interfaces in high-touch clinical environments.
- Wireless Connectivity:Encrypted transmission protocols comply with FDA cybersecurity guidance under Section 524B of the FD&C Act requiring software bill of materials submission.
- Content Management Systems:Legacy on-premise installations face displacement as procurement committees consolidate vendor relationships into single-source contracting structures.
Cloud-based Solutions gain share fastest on IT centralization trends; Interactive Touchscreen maintains deployment density in patient-facing zones.
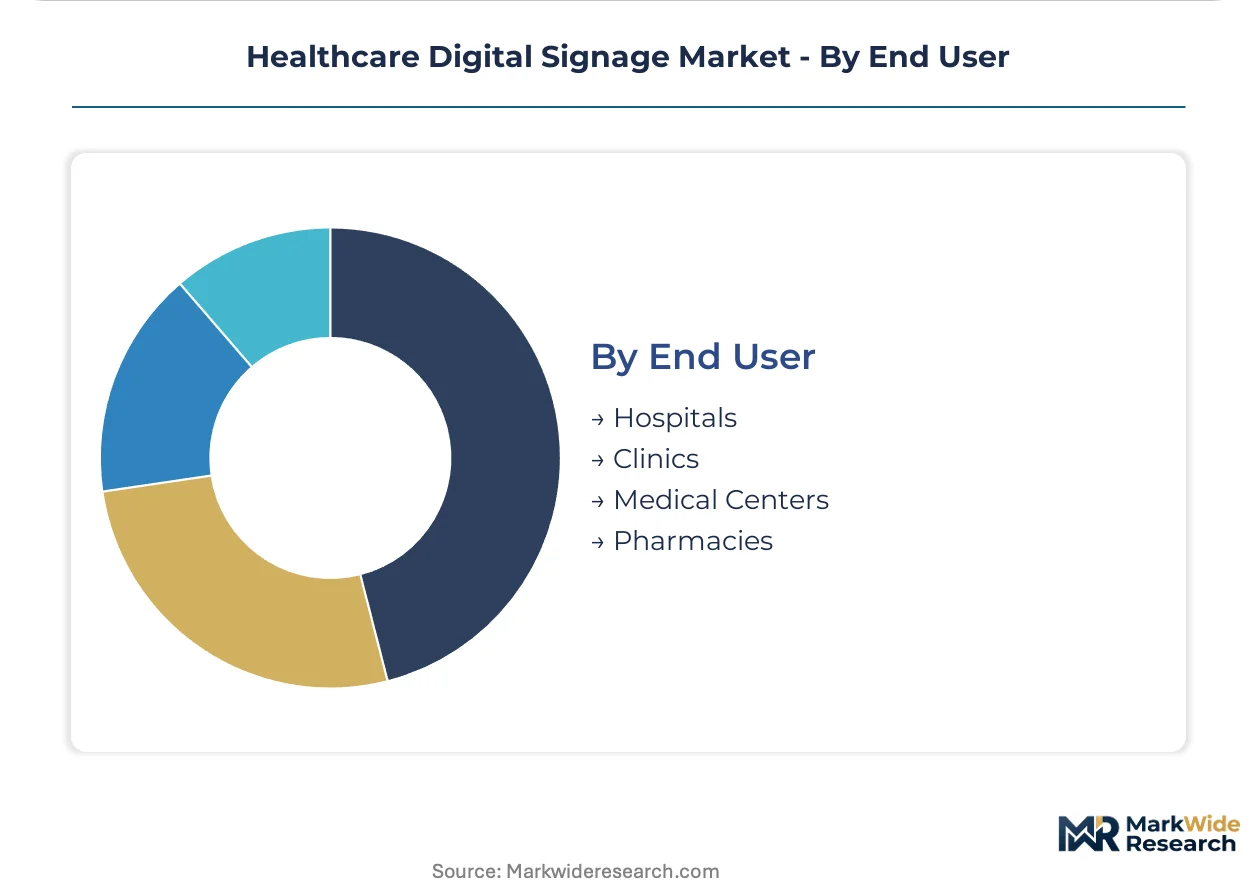
End User:
Facility scale determines procurement committee composition and certification stringency, with hospital networks imposing baseline qualifications that filter mid-tier vendors.
- Hospitals:Large health systems consolidate technology procurement across multi-state networks through centralized IT committees mandating IEC 60601-1 certification and encrypted data transmission as baseline vendor qualifications. FDA 510(k) documentation requirements extend product launch cycles by 14-18 months.
- Clinics:Distributed outpatient footprints prioritize cloud-native management platforms that reduce per-site administrative overhead.
- Medical Centers:Specialty surgical and diagnostic facilities drive MicroLED adoption for DICOM-compliant grayscale accuracy in radiology and surgical planning units.
- Pharmacies:Retail health locations deploy consumer-grade displays for promotional messaging with limited regulatory exposure.
Hospitals anchor procurement volume concentration; Medical Centers exhibit the steepest technology specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established display manufacturing clusters in East Asia supplying healthcare-grade panels to hospital networks in North America and Western Europe. Trade flows concentrate high-value IEC 60601-1 certified products through specialized medical device distribution channels rather than consumer electronics retail.
United States
Multi-state health system consolidation drives centralized procurement of hardened display networks with HIPAA-compliant encryption. FDA cybersecurity guidance under Section 524B of the FD&C Act mandates software bill of materials submission for networked patient-facing devices. Texas Medical Center in Houston anchors deployment density with enterprise framework agreements spanning signage, patient televisions, and bedside tablets.
Germany
University hospital networks in Baden-Württemberg and Bavaria prioritize EU MDR-certified displays with electromagnetic compatibility documentation. The EU Medical Device Regulation imposes parallel conformity requirements that favor vendors with dual-continent certification capabilities. Berlin-Brandenburg health clusters drive MicroLED specification escalation for diagnostic-adjacent radiology applications.
Japan
Aging hospital infrastructure retrofit demand concentrates procurement of thin-form-factor LED panels without structural ceiling modifications. METI guidelines on medical device cybersecurity influence procurement committee qualification standards. Kansai region hospital networks, centered on Osaka, lead cloud-native content governance adoption for distributed clinic management.
China
Domestic display foundry scale enables captive supply of healthcare-grade panels with antimicrobial surface treatments. NMPA medical device registration requirements and GB standards for electromagnetic compatibility shape vendor qualification barriers. Yangtze River Delta hospital clusters in Shanghai and Jiangsu province drive fleet-wide standardization across provincial health system networks.
United Kingdom
NHS England technology procurement frameworks mandate encrypted data transmission and access audit trails for patient-facing digital systems. GDPR compliance requirements intersect with NHS Digital cybersecurity standards for networked clinical devices. London and Southeast England acute trusts concentrate replacement cycles for legacy consumer-grade waiting area displays.
Healthcare Digital Signage Market Competitive Landscape
Concentration sits with diversified electronics conglomerates possessing captive semiconductor fabrication and dedicated healthcare compliance teams. The vendor base stratifies across three tiers: integrated display manufacturers with foundry-scale component supply, specialized medical device vendors with bedside ecosystem bundling capabilities, and regional systems integrators retreating from hospital segments due to engineering overhead. Dominant competitive moves include enterprise framework agreements spanning multiple product categories and backward integration into display driver IC supply.
Within the integrated electronics tier, Samsung Electronics Co., Ltd., LG Electronics, and Koninklijke Philips N.V. exemplify archetypes diverging on strategic emphasis. Samsung leverages semiconductor foundry scale for captive component supply. LG anchors North American networks through platform integration positioning. Philips occupies a position emphasizing patient monitoring ecosystem convergence that bundles signage with bedside devices.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Panasonic Holdings Corporation |
| Koninklijke Philips N.V. |
| Sharp Corporation |
| Daktronics, Inc. |
| Sony Corporation |
| Barco |
| STRATACACHE |
| Others |
Value Network & Pricing Analysis
Foundry-scale semiconductor fabrication in Taiwan and South Korea establishes minimum efficient scale thresholds that compress margin structures for mid-tier display vendors while elevating price floors for healthcare-grade certification tiers. This concentration simultaneously concentrates procurement leverage among integrated electronics conglomerates and fragments pricing power for regional systems integrators lacking captive component supply.
Pricing Analysis
Hospital procurement committees anchor healthcare-grade display pricing through enterprise framework agreements that span signage, patient televisions, and bedside tablets. Three-tier pricing structure across premium diagnostic-adjacent, standard clinical-grade, and economy non-clinical tiers reflects IEC 60601-1 certification investment and antimicrobial surface treatment costs. Pricing pressure stems from LED cost compression in consumer panel imports that force mid-tier vendors toward unprofitable specification matching. Small clinic networks exhibit highest price sensitivity; multi-state health systems with consolidated IT authority command volume discounts through single-source contracting.
Supply Chain Analysis
Taiwan and South Korea anchor display driver IC fabrication, while China dominates LED backlighting module assembly and antimicrobial coating application. Raw material dependencies center on silver-ion surface treatments, copper-alloy substrates, and specialized medical-grade glass. Single-source vulnerability concentrates in East Asian foundry allocation priorities exposed to geopolitical disruption. Distribution runs through specialized medical device channels rather than consumer electronics retail, with GPO contracts and direct health system procurement displacing traditional VAR networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where IEC 60601-1 certification timelines and FDA 510(k) documentation requirements create switching costs that protect incumbent positions. Network effects concentrate in cloud-native content governance platforms where centralized IT management deepens platform stickiness across distributed clinic footprints.
For Market Incumbents: Compound defensive positioning through backward integration into display driver IC supply and accelerated EU MDR certification to capture European hospital modernization cycles. Threat exposure runs from MicroLED substitution in diagnostic-adjacent zones and emerging cloud-native entrants with AI personalization engines. Prioritize bedside device ecosystem bundling that lengthens contract durations and raises replacement switching costs.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for software-only content management platforms offer lower engineering barriers than hardware certification. White-space targets concentrate in clinic outpatient networks with cloud-native management needs and pharmacy retail health locations with limited regulatory exposure. Go-to-market positioning should emphasize middleware interoperability with legacy 2010s-era EMR installations lacking API standardization.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized medical device vendors with bedside ecosystem bundling capabilities over pure-play display manufacturers facing hardware commoditization. Long-term viability hinges on recurring software licensing models in wayfinding and patient education applications. Acquisition target archetype: regional systems integrators with established hospital relationships but lacking compliance engineering bandwidth. Signal to monitor: CMS reimbursement policy shifts codifying digital patient engagement as quality metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market entry for software-defined signage platforms under Section 524B cybersecurity guidance. |
| EU MDR Certification Investment | Unlocks European hospital procurement frameworks requiring electromagnetic compatibility documentation under stricter mandates. |
| Hospital System Partnership | Secures enterprise framework agreements spanning multi-state networks with consolidated IT authority. |
| Bedside Device Ecosystem Bundling | Creates stickier relationships through convergence of signage with patient monitoring and infusion pump interfaces. |
| Cloud-Native Content Platform | Captures recurring revenue through centralized governance reducing per-site administrative overhead. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital CIOs, biomedical engineers, GPO contracts managers, and healthcare IT procurement leads; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR conformity documentation. Bottom-up triangulation across installed base estimates and top-down cross-checks against health system technology expenditure patterns anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning display hardware specifications, clinical use case requirements, infrastructure integration capabilities, and facility scale tiers. CAGRs derived from technology adoption curve analysis and replacement cycle dynamics tied to regulatory compliance mandates. Forecast inputs incorporated LED cost compression trajectories and cloud content governance penetration rates across multi-hospital network consolidation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained HIPAA enforcement intensity and stable East Asian semiconductor supply; material deviation in either would warrant model refresh. Specific risk factors include foundry allocation disruption from geopolitical events and CMS reimbursement policy shifts that could accelerate or decelerate replacement cycles. Recalibration cycles align with material shifts in FDA cybersecurity guidance and health system consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Digital Patient Engagement Solutions Market