
 South Africa Bariatric Surgery Market | 2026-2036
South Africa Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Bariatric Surgery Market Analytics
Minimally invasive laparoscopic platforms is reshaping operative workflows across South African bariatric centers, reducing recovery timelines and expanding candidacy pools. Johnson & Johnson leverages its broad surgical stapling portfolio to anchor supply relationships with major private hospital groups. Medtronic PLC competes through integrated energy devices and sustained training investments for township-adjacent facilities. Intuitive Surgical Inc positions its robotic systems in premium-tier academic centers, differentiating on precision metrics for complex revisional cases.
Bariatric surgery encompasses restrictive and malabsorptive procedures modifying gastrointestinal anatomy to achieve sustained weight reduction, typically requiring specialized stapling devices with titanium-alloy cartridges and calibrated anvil pressures of approximately 3.5 to 4.0 mm. The primary commercial purpose centers on treating morbid obesity and comorbid metabolic disease when conservative management fails. Sleeve gastrectomy dominates procedure type volumes due to simpler technical execution and lower complication profiles versus Roux-en-Y gastric bypass. Robotic surgery technology captures premium pricing tiers while laparoscopic surgery sustains mainstream volume throughput across public and private settings. Surgical staplers concentrate margin pools given disposable consumption patterns and vendor lock-in dynamics.
The Health Professions Council of South Africa governs surgeon credentialing and facility licensing, directly constraining market entry and procedure volume ceilings. Council for Medical Schemes reimbursement determinations shape patient affordability and private-sector investment incentives for new program launches. ISO 13485 and South African Health Products Regulatory Authority device registration requirements impose quality system burdens on imported instrument portfolios. Stakeholders must monitor evolving medical scheme tariff negotiations and public-private partnership frameworks for provincial hospital outsourcing.
Market Dynamics
Private hospital chains in Johannesburg and Cape Town are expanding metabolic surgery units as obesity-related diabetes burdens climb, reshaping capacity deployment and surgeon labor markets across Gauteng and Western Cape provinces.
Growth Catalysts
- Minimally invasive laparoscopic platforms:These systems reduce recovery timelines and expand candidacy pools for bariatric procedures across South African centers.
- Council for Medical Schemes reimbursement pathways:Evolving tariff determinations shape patient affordability and incentivize private-sector investment in new program launches.
- Specialist surgeon density in insured patient pools:Concentration of qualified practitioners in Gauteng and Western Cape provinces drives procedure volume accessibility.
Market Restraints
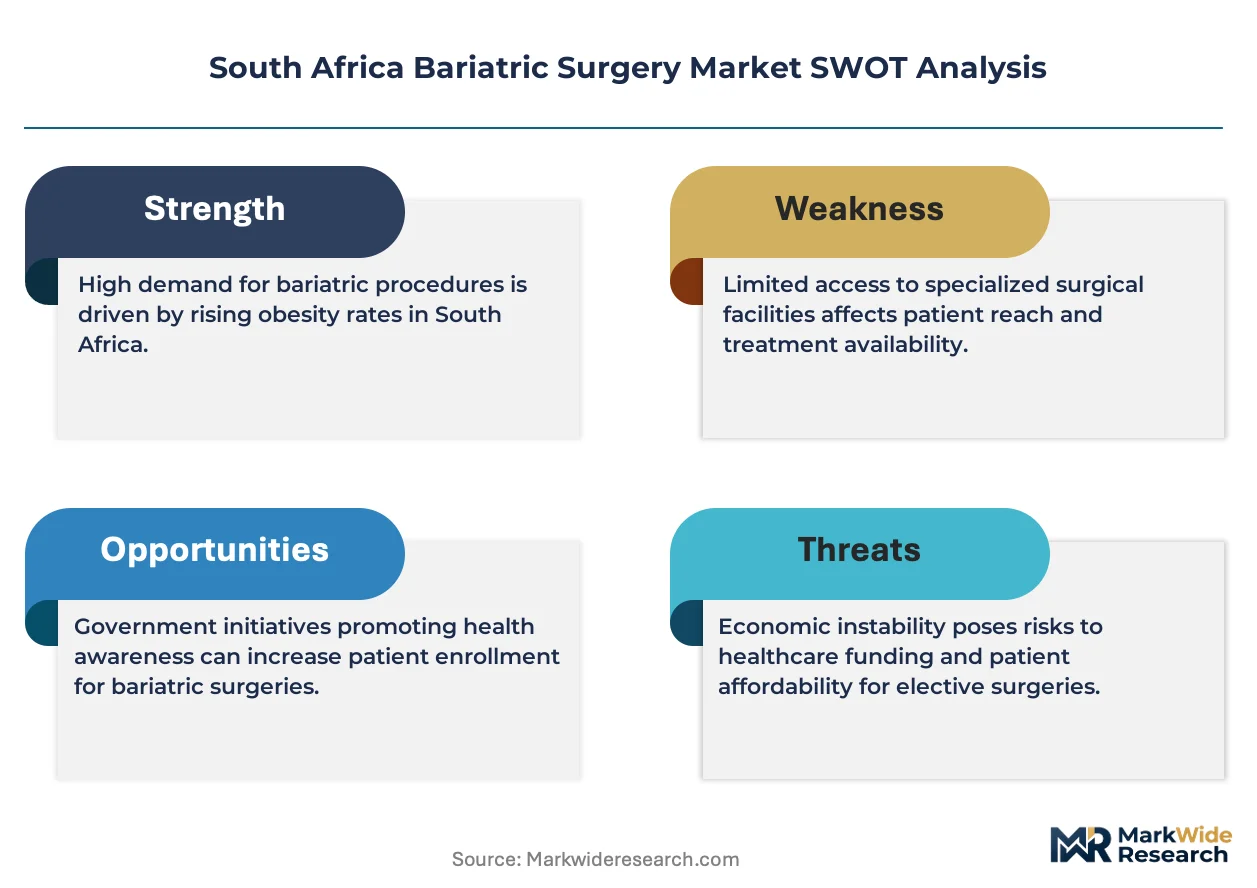
- Titanium-alloy cartridge supply concentration:Dependence on imported surgical stapling consumables exposes facilities to currency volatility and shipping delays.
- Health Professions Council of South Africa credentialing bottlenecks:Stringent facility licensing and surgeon certification requirements constrain market entry and volume ceilings.
- Public hospital resource limitations:Provincial outsourcing frameworks remain underdeveloped, restricting access for uninsured populations.
Strategic Opportunities
- Township-adjacent facility networks:Underserved peri-urban corridors around Johannesburg and Cape Town present expansion targets for tiered service models.
- Robotic-assisted revisional surgery:Complex case differentiation at academic medical centers commands premium positioning and training revenue streams.
- Public-private partnership frameworks:Provincial hospital outsourcing agreements could unlock volume growth in state-funded care segments.
Industry Challenges
- Specialized bariatric nursing workforce scarcity:Post-operative care protocols require trained staff that remain concentrated in major metropolitan private hospitals.
- ISO 13485 quality system compliance timelines:Device registration through the South African Health Products Regulatory Authority imposes lengthy validation burdens on imported instrument portfolios.
- Legacy electronic health record integration:Metabolic surgery tracking requirements clash with existing hospital information system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Bariatric Surgery Market |
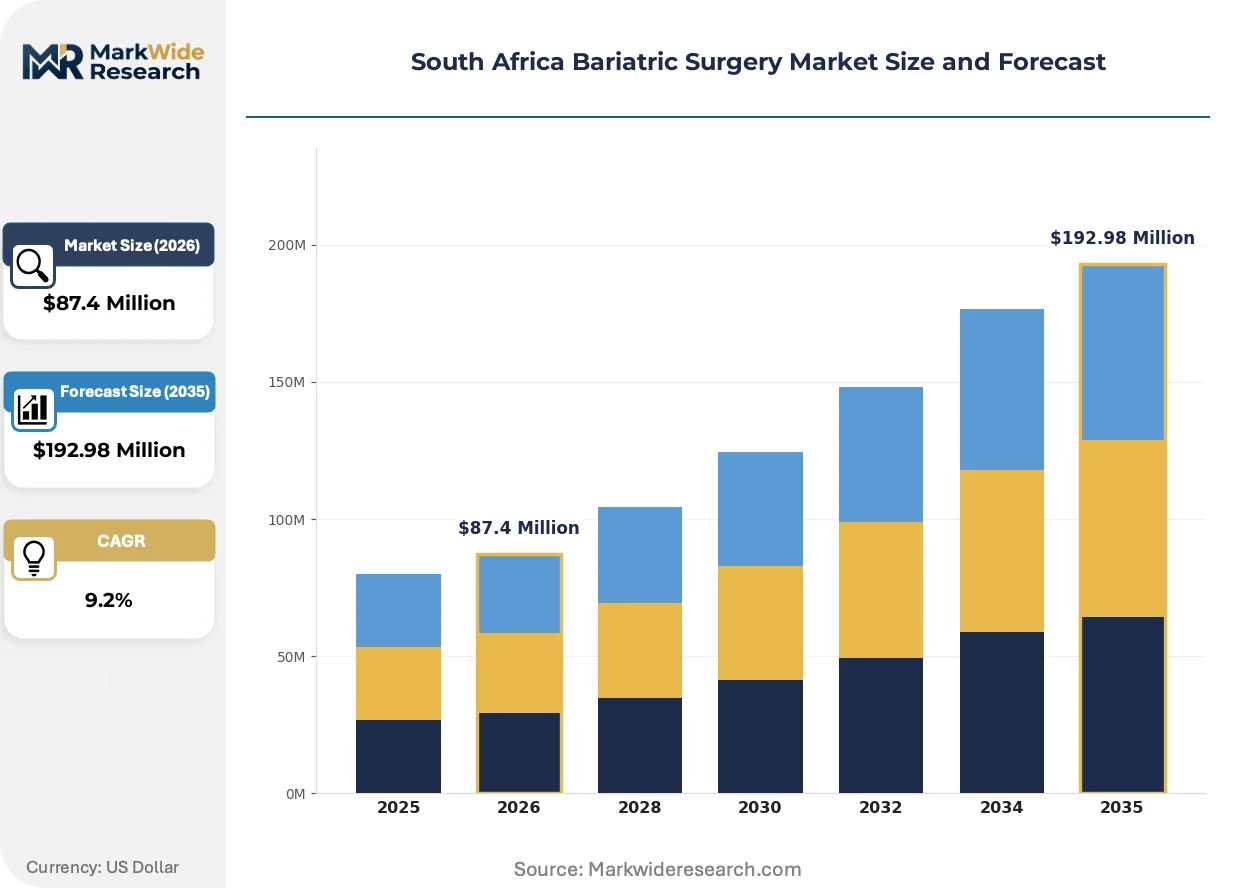
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $192.98 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Roux-en-Y Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Private Practices Product Type: Surgical Staplers, Adjustable Bands, Gastric Pouches, Laparoscopic Instruments Technology: Robotic Surgery, Laparoscopic Surgery, Endoscopic Techniques, Conventional Surgery |
| Companies Covered | Apollo Endosurgery Inc, Aspire Bariatrics, B Braun Melsungen AG, ConMed Corporation, Intuitive Surgical Inc, Johnson & Johnson, Medtronic PLC, Olympus Corporation, The Cooper Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Bariatric Surgery Market Evolving Landscape
Operative workflows across South African bariatric centers are being reconfigured by platform technologies and reimbursement evolution, compressing traditional service delivery models and redrawing competitive boundaries between private hospital groups.
Single-incision laparoscopic surgery platforms are gaining traction in Cape Town academic centers for sleeve gastrectomy procedures. Premium-tier hospitals are adopting these systems to differentiate on cosmetic outcomes and reduce post-operative pain scores. Conventional multi-port laparoscopic instrumentation is rendering obsolete in these settings as patient preference data drives capital allocation decisions.
The Council for Medical Schemes is revising tariff structures for metabolic surgery to incorporate bundled payment elements. This policy shift pressures facilities to standardize episode-of-care costs and document long-term outcomes. Private hospital groups in Gauteng are responding by consolidating pre-operative assessment and post-operative monitoring into integrated service lines.
Patients are demanding comprehensive metabolic management rather than isolated surgical intervention. This behavioral pivot disrupts traditional fee-for-service relationships between surgeons and medical schemes. Western Cape facilities are most visibly adapting by embedding dietetic and endocrinology services within bariatric units, creating recurring revenue streams beyond the index procedure.
South Africa Bariatric Surgery Market Segmentation
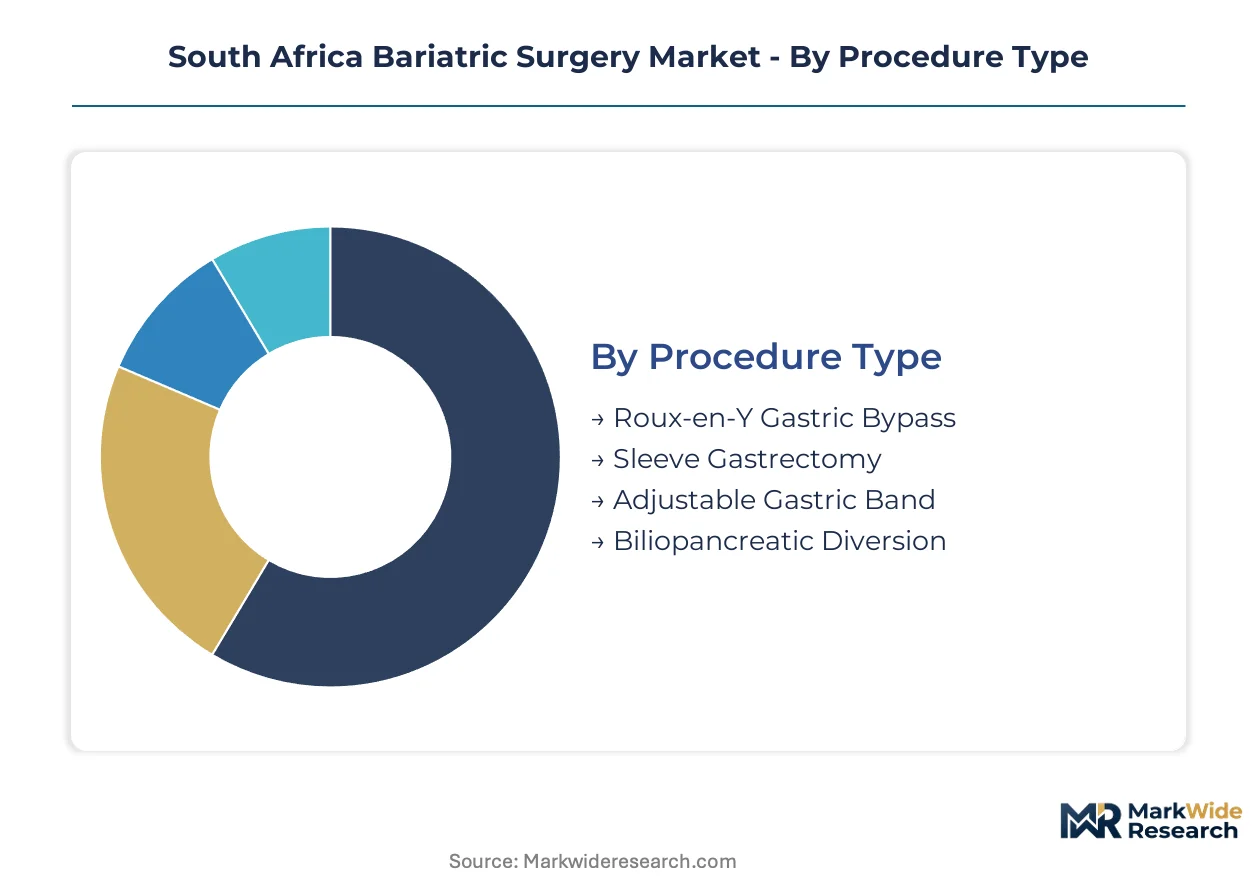
South Africa's bariatric surgery market segments along procedural, technological, and facility dimensions that determine reimbursement pathways, capital deployment, and patient access. Understanding these divisions clarifies where private hospital groups concentrate expansion investments and which device categories command recurring consumable revenue.
Procedure Type:
After-sales service intensity varies sharply across procedures, with revisional cases demanding sustained follow-up protocols and staple-line surveillance programs.
- Sleeve Gastrectomy:Partial gastric resection creates a tubular stomach remnant using linear staplers with 3.5 mm titanium-alloy cartridges. Demand concentrates in Johannesburg private hospital chains where insured patient pools and specialist surgeon density overlap, driven by simpler technical execution and lower complication profiles that reduce readmission penalties.
- Roux-en-Y Gastric Bypass:Malabsorptive reconstruction requires gastrojejunostomy and enteroenterostomy anastomoses with precise staple-line integrity. Western Cape academic centers handle complex cases, constrained by Health Professions Council of South Africa credentialing bottlenecks that limit qualified practitioner supply.
- Adjustable Gastric Band:Restrictive silicone device with subcutaneous port access for saline adjustment. Port maintenance and band deflation services create recurring outpatient revenue streams.
- Biliopancreatic Diversion:Aggressive malabsorptive procedure with duodenal switch variation reserved for super-obese patients. Limited to high-volume metabolic surgery units with intensive nutritional monitoring capabilities.
By volume, Sleeve Gastrectomy leads. By growth pace, Robotic-assisted Roux-en-Y Gastric Bypass is expanding most quickly in premium-tier facilities.
End User:
Cost tier stratification separates metropolitan private hospitals from township-adjacent facilities, with capital intensity determining which technologies each tier can deploy.
- Hospitals:Full-service inpatient facilities with ICU backup and 24-hour specialist coverage. Gauteng and Western Cape private hospital groups anchor metabolic surgery unit expansion, capturing bundled payment structures from Council for Medical Schemes revisions.
- Ambulatory Surgical Centers:Same-day discharge protocols for low-complexity sleeve gastrectomy in selected patients. Cape Town centers are piloting enhanced recovery pathways to reduce length-of-stay costs.
- Specialty Clinics:Focused bariatric units with embedded dietetic and endocrinology services. Johannesburg clinics are consolidating pre-operative assessment and long-term monitoring into integrated service lines.
- Private Practices:Surgeon-owned facilities with limited procedure throughput. Constrained by ISO 13485 device registration burdens and nursing workforce scarcity for post-operative care protocols.
By patient volume, Hospitals dominate. By margin per case, Ambulatory Surgical Centers are gaining share fastest through reduced overhead structures.
Product Type:
Supply concentration for titanium-alloy consumables creates vendor lock-in dynamics that shape procurement negotiations across facility tiers.
- Surgical Staplers:Disposable linear and circular staplers with calibrated anvil pressures. Johannesburg private hospital chains concentrate demand, exposed to currency volatility on imported cartridges.
- Adjustable Bands:Silicone devices with subcutaneous access ports. Port revision and replacement procedures sustain aftermarket revenue.
- Gastric Pouches:Pre-formed or hand-sewn stomach reconstructions. Academic centers prefer custom tailoring for complex revisional anatomy.
- Laparoscopic Instruments:Graspers, dissectors, and energy devices for minimally invasive access. Township-adjacent facilities prioritize reusable instrumentation to reduce per-case supply costs.
By revenue concentration, Surgical Staplers lead. By technology substitution risk, Laparoscopic Instruments face displacement from single-incision platforms.
Technology:
Volume throughput separates mainstream laparoscopic deployment from premium robotic positioning, with reimbursement parity still evolving under Council for Medical Schemes tariff structures.
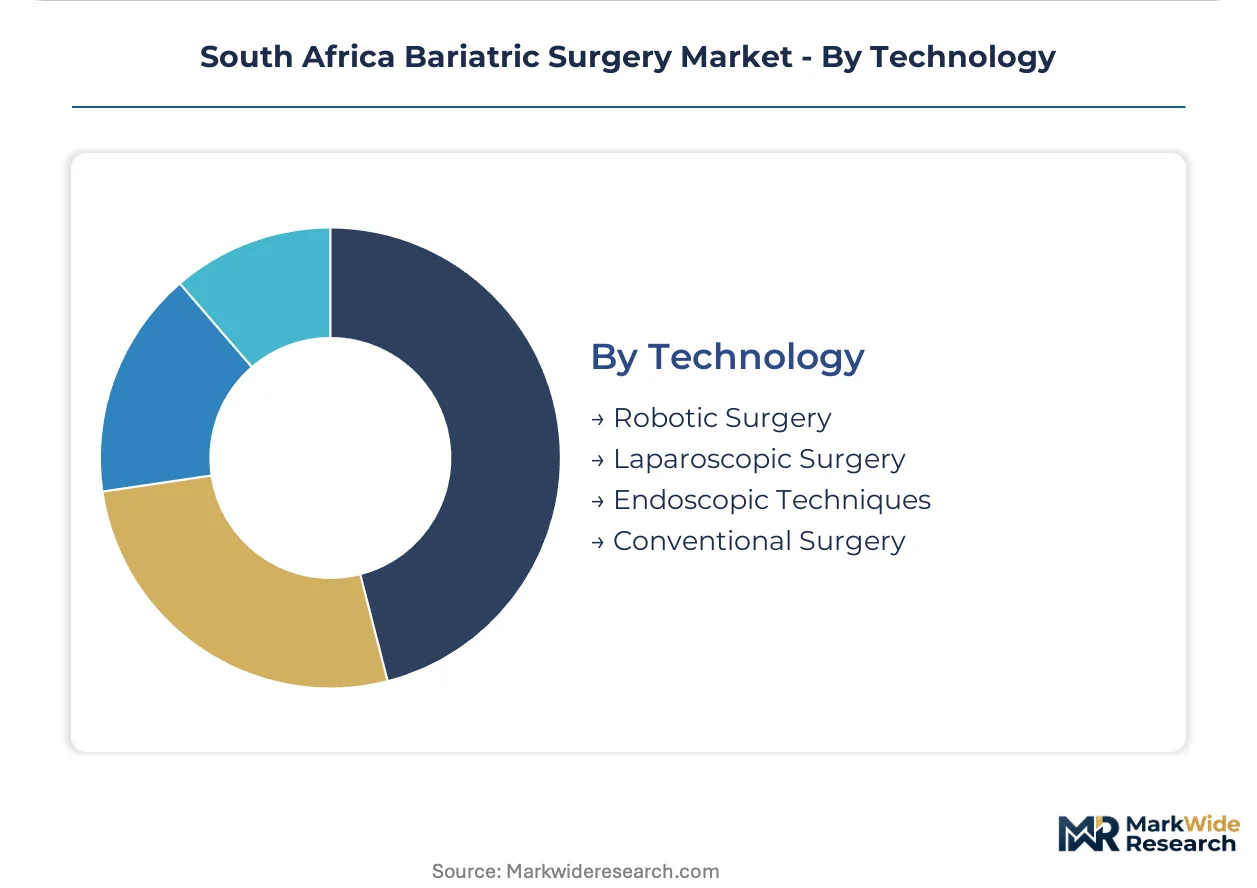
- Laparoscopic Surgery:Multi-port and single-incision platforms with standardized instrumentation. Sustains mainstream procedure volumes across public and private settings in Gauteng and Western Cape.
- Robotic Surgery:Da Vinci systems for precision suturing in complex revisional cases. Cape Town academic centers command premium positioning and training revenue streams.
- Endoscopic Techniques:Transoral approaches for primary and revisional interventions without abdominal wall breach. Emerging applications for band removal and fistula management.
- Conventional Surgery:Open abdominal access reserved for conversion scenarios and resource-constrained public hospitals. Declining share as minimally invasive platforms expand candidacy pools.
By procedure count, Laparoscopic Surgery leads. By capital investment growth, Robotic Surgery shows the steepest expansion trajectory in premium-tier private hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa imports surgical stapling consumables and robotic platforms from German and US manufacturers, with Johannesburg and Cape Town serving as the primary distribution nodes for Southern African healthcare networks.
Gauteng Province
Private hospital chains in Johannesburg are expanding metabolic surgery units as obesity-related diabetes burdens climb. The Health Professions Council of South Africa governs surgeon credentialing and facility licensing, directly constraining market entry. Specialist surgeon density concentrates in Sandton and Pretoria, where insured patient pools overlap with premium-tier academic medical centers.
Western Cape Province
Cape Town academic centers handle complex revisional cases using robotic-assisted platforms. The Council for Medical Schemes is revising tariff structures to incorporate bundled payment elements for metabolic surgery. Single-incision laparoscopic surgery platforms are gaining traction in these facilities for sleeve gastrectomy procedures.
KwaZulu-Natal Province
Durban private hospitals are piloting enhanced recovery pathways to reduce length-of-stay costs for ambulatory bariatric cases. The South African Health Products Regulatory Authority imposes ISO 13485 quality system burdens on imported instrument portfolios. Device registration timelines delay technology deployment in this coastal corridor.
Eastern Cape Province
Port Elizabeth and East London facilities face specialized bariatric nursing workforce scarcity that limits post-operative care protocols. Provincial outsourcing frameworks remain underdeveloped, restricting access for uninsured populations. Township-adjacent peri-urban corridors present expansion targets for tiered service models.
South Africa Bariatric Surgery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's bariatric surgery market. The vendor base fragments across multinational device manufacturers, regional distributors, and local service integrators. Three archetypes dominate: diversified surgical conglomerates with broad stapling portfolios, precision robotics specialists targeting academic centers, and endoscopic platform innovators. Capacity expansion in Johannesburg and Cape Town metabolic surgery units, alongside strategic partnerships for township-adjacent facility networks, represent the dominant competitive moves.
Among US-based surgical technology developers, Johnson & Johnson and Medtronic PLC occupy positions anchoring supply relationships with major private hospital groups. Intuitive Surgical Inc exemplifies the premium robotics tier, with its systems positioned in academic centers for complex revisional cases. These three entities represent the primary competitive anchors shaping procurement dynamics and technology adoption trajectories across Gauteng and Western Cape provinces.
| Leading Market Players |
|---|
| Apollo Endosurgery Inc |
| Aspire Bariatrics |
| B Braun Melsungen AG |
| ConMed Corporation |
| Intuitive Surgical Inc |
| Johnson & Johnson |
| Medtronic PLC |
| Olympus Corporation |
| The Cooper Companies |
| Others |
Value Network & Pricing Analysis
Titanium-alloy cartridge import dependency determines both pricing tier spreads and supply chain shape across South African bariatric centers, with currency volatility compressing margins on disposable consumables while forcing tiered procurement strategies between premium robotic-equipped hospitals and cost-conscious township-adjacent facilities.
Pricing Analysis
Robotic-assisted platforms command three-tier pricing structure across premium, standard, and economy levels versus conventional laparoscopic systems. Price differentiation hinges on after-sales service bundling and ISO 13485 certification tier of imported stapling devices. Pricing pressure stems from Council for Medical Schemes tariff compression under bundled payment pilots. Uninsured patient segments exhibit highest price sensitivity, driving demand for reusable instrumentation in peri-urban corridors.
Supply Chain Analysis
US export-control restrictions on precision surgical robotics limit technology flows into South African academic centers. Manufacturing concentrates in Germany, the United States, and Switzerland for stapling platforms and energy devices. Raw material dependencies center on titanium-alloy sheet, medical-grade silicone, and precision-machined anvil components. Single-source vulnerability runs through Johnson & Johnson's dominant cartridge supply position. Distribution feeds through Johannesburg and Cape Town hub-and-spoke networks serving Gauteng and Western Cape private hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's bariatric surgery market reads as a service-attach opportunity where long-term metabolic management programs and staple-line surveillance contracts expand faster than capital equipment sales, embedding recurring revenue into episode-of-care relationships.
For Market Incumbents: Entrench supply relationships with major private hospital groups through captive training academy investments and exclusive cartridge servicing contracts. Consolidate procurement leverage against emerging single-incision platform vendors by deepening backward integration into regional distribution infrastructure. Counter robotic-assisted substitution threats by embedding laparoscopic platforms in township-adjacent facility expansion pipelines. For New Entrants and Emerging Players: Eastern Cape peri-urban corridors around Port Elizabeth present the most penetrable geographic white-space, with specialized bariatric nursing workforce scarcity currently blocking incumbent expansion. Target ambulatory surgical center partnerships for low-complexity sleeve gastrectomy protocols, bypassing capital-intensive hospital infrastructure requirements. Pursue public-private partnership frameworks as the primary go-to-market angle for state-funded volume access. For Investors and Strategic Acquirers: Council for Medical Schemes bundled payment tariff revisions reshape the acquisition landscape by rewarding integrated metabolic surgery service lines over standalone device suppliers. Five-to-ten year viability favors platform-agnostic service integrators with embedded dietetic and endocrinology capabilities. Monitor Health Professions Council of South Africa credentialing queue lengths as the critical inflection signal for surgeon supply expansion and volume ceiling relaxation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures preferred vendor status with Johannesburg and Cape Town private hospital chains under bundled payment structures. |
| Reimbursement Strategy | Aligns device portfolio with Council for Medical Schemes tariff revisions to unlock patient affordability expansion. |
| Software Companion Development | Enables remote staple-line surveillance and metabolic outcome tracking for recurring service revenue attachment. |
| CE Marking Pathway | Facilitates South African Health Products Regulatory Authority device registration through harmonized quality system documentation. |
| Training Academy Investment | Builds surgeon loyalty and consumable lock-in through Health Professions Council of South Africa-accredited credentialing programs. |
Research Methodology
A standing panel of bariatric surgeons, hospital procurement managers, biomedical engineers, and Council for Medical Schemes tariff negotiators provided ongoing calibration across primary fieldwork phases. Secondary validation drew from South African Health Products Regulatory Authority device registration databases, hospital procurement contract disclosures, and Health Professions Council of South Africa credentialing records. Bottom-up procedure volume estimates triangulated against top-down private hospital group capacity expansion announcements.
Scenario-bracketing framed demand projections across the analysis window, modeling procedure type, technology platform, facility tier, and patient insurance status as core segmentation dimensions. CAGRs derived from surgeon supply growth trajectories and medical scheme coverage expansion rates. Forecast inputs incorporated Council for Medical Schemes tariff negotiation timelines and ISO 13485 compliance burden estimates for imported instrument portfolios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by robotic platform specialists or public-private partnership integrators would shift outcomes. Material shifts in Council for Medical Schemes bundled payment adoption rates or Health Professions Council of South Africa credentialing reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market