
 Pathology Laboratories Market | 2026-2036
Pathology Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Pathology Laboratories Market Intelligence
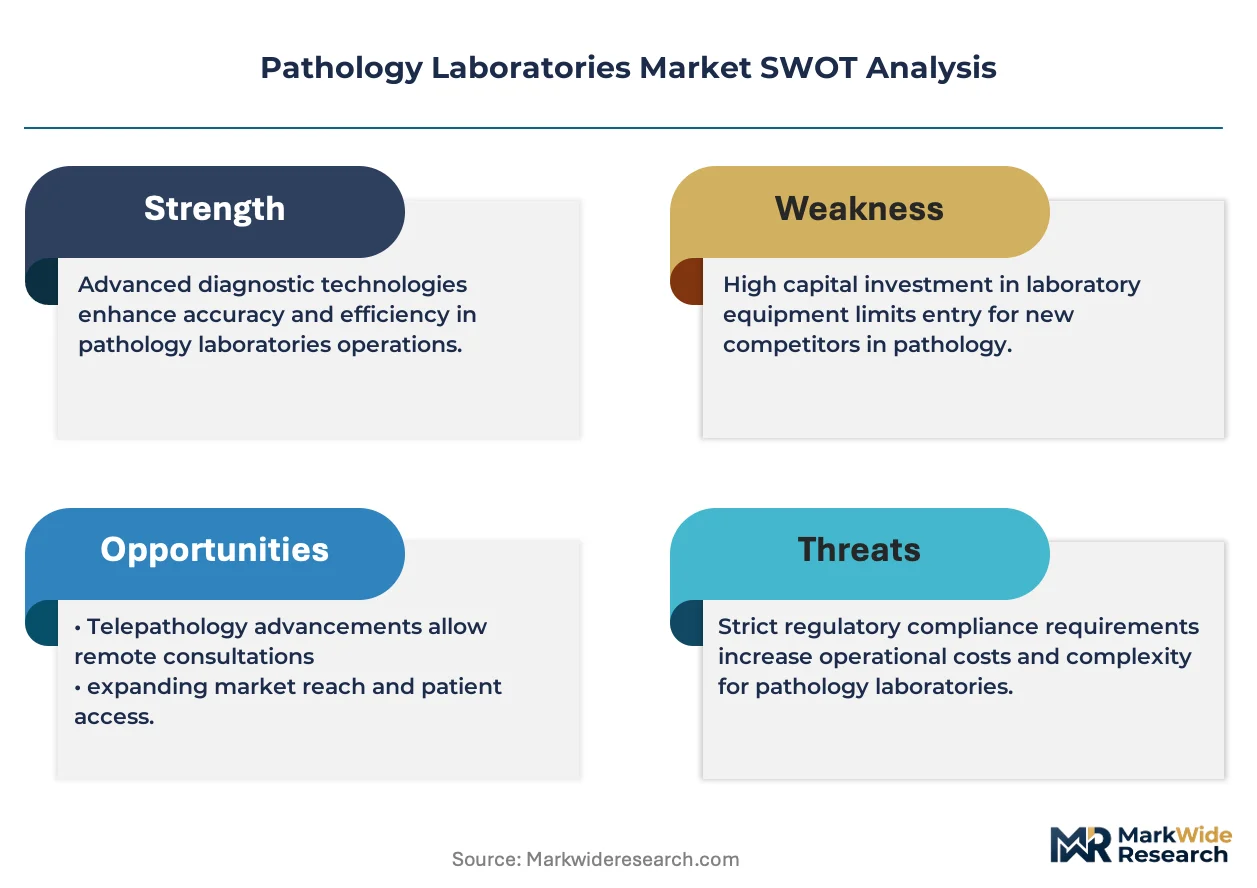
Multi-source contracting for advanced molecular diagnostics is shifting how hospital systems manage pathology capacity. Quest Diagnostics leverages its national logistics network to sustain reference lab dominance. Laboratory Corporation of America anchors high-volume clinical testing through integrated payer relationships. Siemens Healthineers competes on imaging-to-pathology workflow convergence.
Pathology laboratories perform tissue analysis, cellular examination, and biomarker detection using reagents, instruments, and software platforms to support disease diagnosis and treatment selection. Histopathology and molecular diagnostics segments lead revenue contribution, with immunohistochemistry commanding premium pricing due to antibody specificity requirements. Cancer diagnosis applications drive fastest volume expansion as precision oncology protocols expand biomarker testing panels across hospital networks.
FDA laboratory-developed test oversight and CLIA quality standards shape capital deployment and validation timelines for new assay introductions. CAP accreditation requirements and state-level laboratory licensing frameworks add compliance layers that influence regional market entry decisions. Stakeholders must monitor evolving reimbursement policies for next-generation sequencing-based cancer panels to align service expansion with sustainable revenue capture.
Market Dynamics
Hospital systems are consolidating pathology outsourcing contracts while the FDA modernizes laboratory-developed test oversight, forcing capital reallocation toward compliance infrastructure and specialized molecular testing partnerships.
Growth Catalysts
- Precision oncology protocols:Cancer centers are expanding biomarker testing panels to guide targeted therapy selection, driving volume through molecular diagnostics suites.
- CLIA quality standards:Federal laboratory certification requirements are elevating operational benchmarks and filtering subscale competitors from high-complexity testing markets.
- United States:Advanced healthcare infrastructure and high diagnostic procedure volume concentrate demand for automated histopathology workflows.
Market Restraints
- Antibody specificity costs:Immunohistochemistry reagents require premium-grade monoclonal antibodies, compressing margins on routine cancer panels.
- Reimbursement uncertainty:CMS and private payers are recalibrating coverage policies for next-generation sequencing-based cancer diagnostics, delaying service line investments.
- Validation timelines:CAP accreditation and state laboratory licensing frameworks extend new assay introduction cycles by 12-18 months.
Strategic Opportunities
- Digital pathology convergence:Whole-slide imaging paired with artificial intelligence is integrating into diagnostic workflows, creating remote interpretation capabilities.
- India:CDSCO regulatory streamlining and rising cancer incidence are opening reference lab partnerships with tertiary hospital networks.
- Liquid biopsy expansion:Circulating tumor DNA testing is penetrating early cancer screening protocols, displacing tissue-based sampling in monitoring applications.
Industry Challenges
- Pathologist workforce constraints:Fellowship-trained subspecialists in molecular genomics remain scarce relative to testing volume growth.
- Legacy LIS integration:Laboratory information systems from the 2010s require costly middleware to connect with modern digital pathology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathology Laboratories Market |
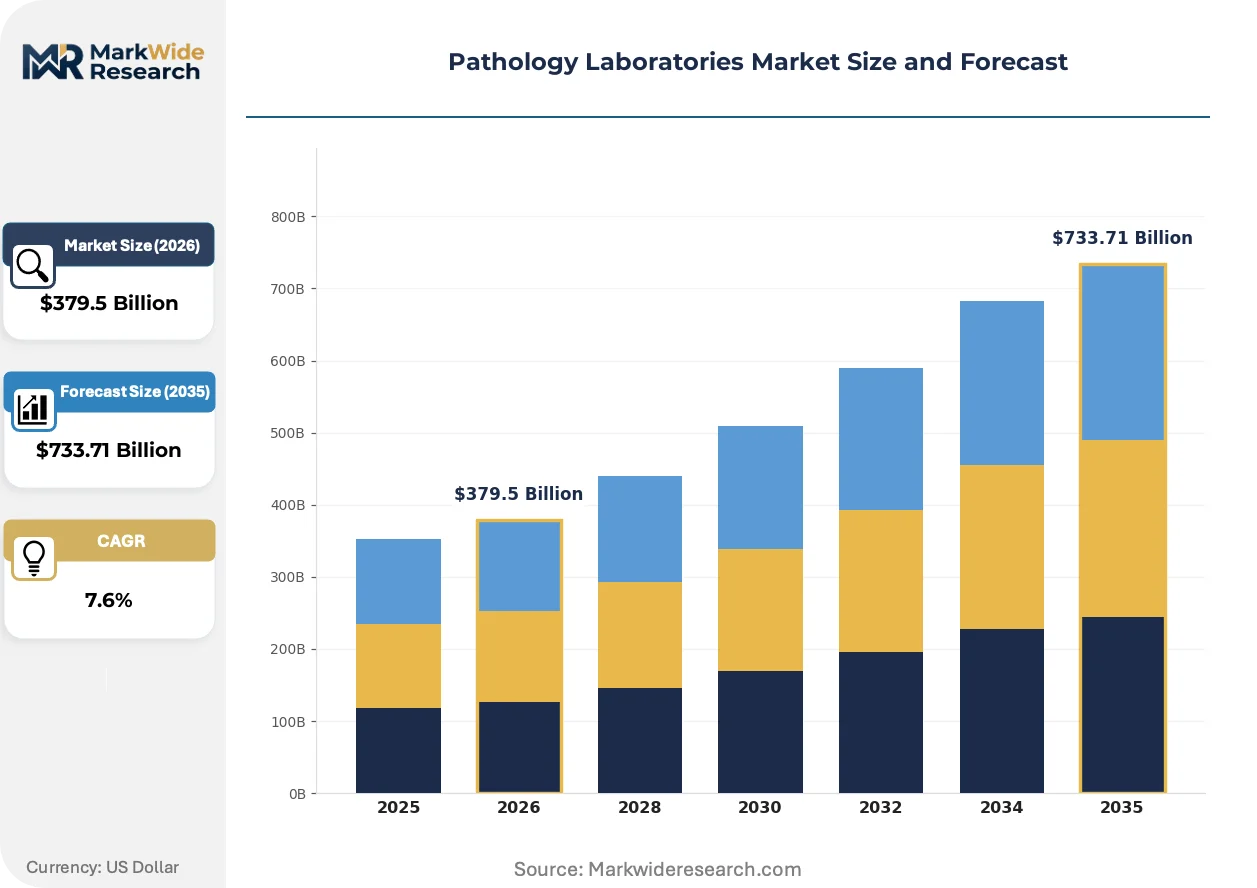
| Market Size in 2026 | $379.5 Billion |
| Market Size in 2035 | $733.71 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Application: Cancer Diagnosis, Infectious Diseases, Genetic Testing, Hematology Technology: Histopathology, Cytopathology, Molecular Diagnostics, Immunohistochemistry |
| Companies Covered | Quest Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Agilent Technologies, Abbott Laboratories, Danaher Corporation, Laboratory Corporation of America, QIAGEN, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathology Laboratories Market Strategic Shifts & Innovations
Workflow automation and computational pathology are compressing diagnostic turnaround times while regulatory modernization reshapes competitive entry requirements. Three developments are restructuring how laboratories capture value.
Multiplex immunofluorescence platforms are integrating into academic medical center workflows, enabling simultaneous detection of eight or more protein markers from single tissue sections. Pathology departments at NCI-designated cancer centers are adopting these systems to support immuno-oncology clinical trials. The technology is integrating biomarker quantification with spatial mapping, consolidating what previously required multiple serial staining runs.
EU In Vitro Diagnostic Regulation (IVDR) reclassification rules are elevating clinical evidence requirements for laboratory-developed tests marketed across European member states. Manufacturers must now submit technical documentation and performance studies to notified bodies for moderate-risk devices previously self-certified. Germany and France are witnessing delayed product registrations as laboratories await CE mark transitions for companion diagnostic assays.
Hospital procurement departments are consolidating vendor contracts for anatomic pathology services, shifting from fee-per-test arrangements to multi-year managed service agreements. Integrated delivery networks in Texas and Florida are bundling histology, immunohistochemistry, and molecular testing under single-source contracts with reference laboratories. This concentration is compressing margins for independent pathology groups while favoring operators with national logistics networks.
Pathology Laboratories Market Segmentation
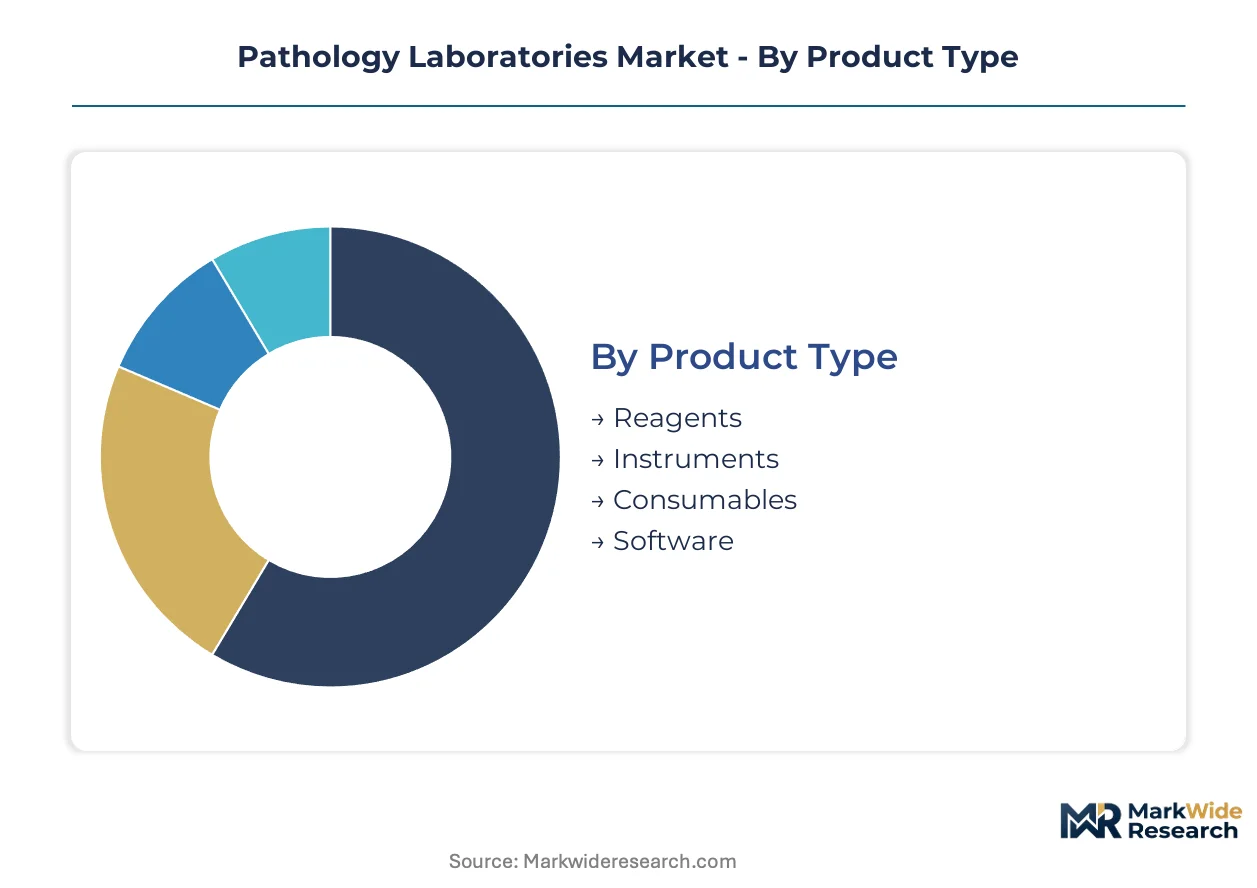
Segmentation in pathology laboratories reveals how technology specialization, end-user purchasing power, and application urgency reshape procurement patterns. Understanding these divides exposes where margin pools concentrate and where commoditization pressures intensify.
Product Type:
Technology specifications determine replacement cycles and vendor lock-in intensity across the four product categories.
- Reagents:Biochemical formulations including fixatives, stains, and assay-specific detection chemistries constitute recurring revenue streams with 60-90 day consumption cycles. Academic medical centers in the United States drive demand for multiplex-compatible reagent kits as precision oncology protocols expand biomarker panel complexity.
- Instruments:Automated stainers, tissue processors, and slide scanners anchor capital budgets with 5-7 year depreciation schedules. Hospital systems concentrate procurement in integrated analyzer platforms that consolidate histology and molecular preparation workflows to reduce bench space requirements and technician training overhead.
- Consumables:Microtome blades, cassettes, and cover slips represent high-volume, low-margin categories where group purchasing organizations extract price concessions through consolidated contracting.
- Software:Laboratory information systems and digital pathology viewers command premium pricing when integrated with artificial intelligence-assisted diagnostic modules.
Mature deployment sits with Reagents. Newer deployment is concentrated in Software.
End User:
Purchasing authority and test volume scale create distinct service models across the four customer types.
- Hospitals:In-house laboratories at tertiary and community hospitals process 40-60% of anatomic pathology specimens domestically, retaining high-margin molecular testing while outsourcing routine histology. Integrated delivery networks in Texas and Florida are consolidating multi-year managed service agreements that bundle histology, immunohistochemistry, and molecular diagnostics under single-source contracts.
- Diagnostic Centers:Independent reference laboratories capture overflow volume from hospital systems and direct-to-consumer testing demand, competing on turnaround time and specialized assay menus.
- Research Laboratories:NCI-designated cancer centers and pharmaceutical development sites drive adoption of multiplex immunofluorescence platforms for clinical trial biomarker quantification.
- Clinics:Physician office laboratories perform limited CLIA-waived testing, referring complex cases to hospital or reference lab partners.
Volume concentration favors Hospitals. Fastest capability expansion is occurring in Diagnostic Centers.
Application:
Disease prevalence and reimbursement certainty segment addressable market opportunity across clinical use cases.
- Cancer Diagnosis:Tissue-based oncology testing commands premium pricing due to therapy-selection stakes, with next-generation sequencing panels and companion diagnostic assays representing the steepest expansion trajectory as precision medicine protocols penetrate community oncology practices.
- Infectious Diseases:Molecular detection of pathogens including SARS-CoV-2, tuberculosis, and antimicrobial resistance markers sustained elevated demand through pandemic response infrastructure investments.
- Genetic Testing:Hereditary cancer panels and pharmacogenomic assays face reimbursement compression as CMS recalibrates coverage policies for germline sequencing.
- Hematology:Bone marrow morphology and flow cytometry for leukemia classification remain core competencies of academic medical center laboratories.
Established revenue sits with Hematology. Steepest volume climb is occurring in Cancer Diagnosis.
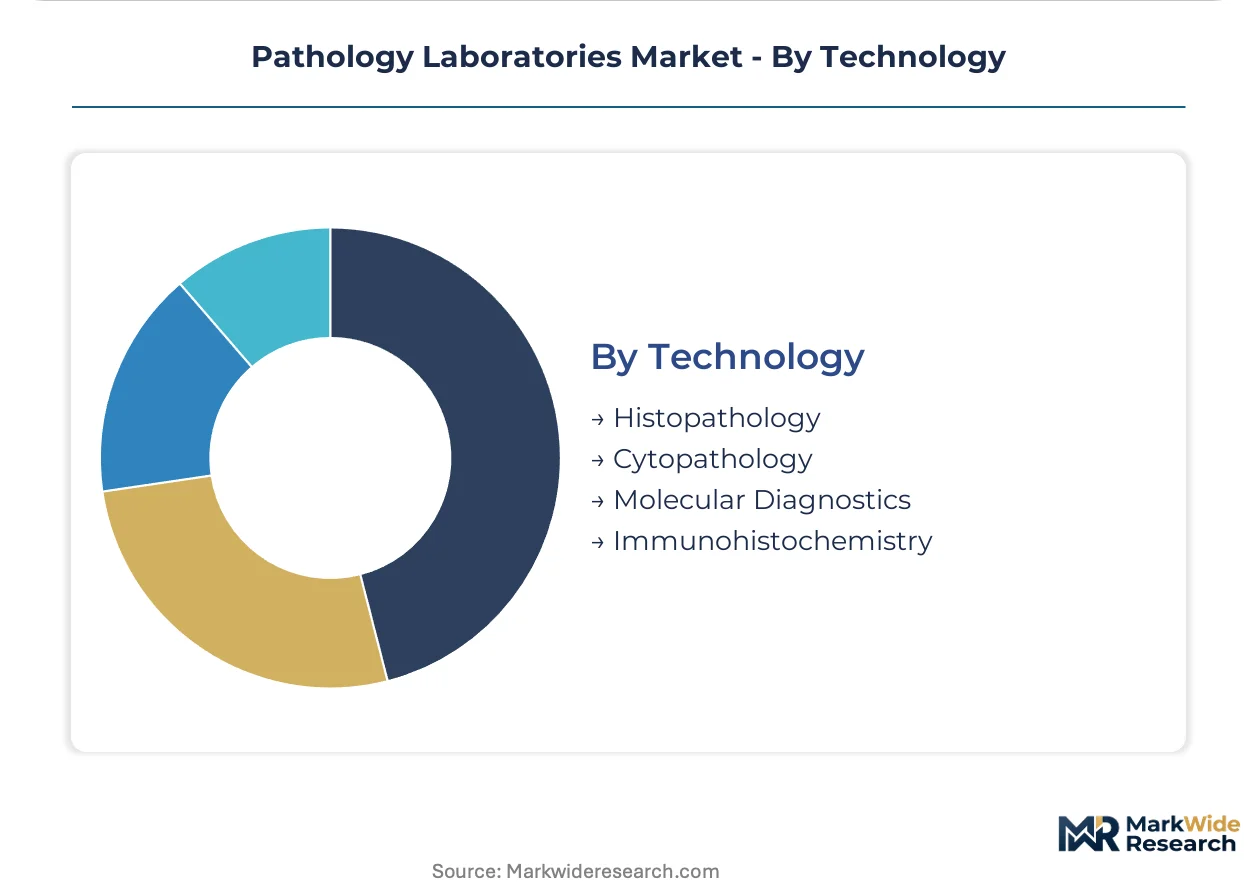
Technology:
Methodological sophistication and regulatory classification stratify competitive entry barriers across diagnostic approaches.
- Histopathology:Conventional tissue processing and H&E staining constitutes the procedural foundation for cancer diagnosis, with workflow automation compressing turnaround times from days to hours at high-volume centers.
- Cytopathology:Cervical cancer screening through Pap smear cytology faces volume decline from HPV primary screening adoption, redirecting cytotechnologist capacity toward fine needle aspiration evaluation.
- Molecular Diagnostics:PCR, FISH, and next-generation sequencing platforms enable biomarker detection at nucleic acid resolution, requiring CLIA high-complexity certification and specialized interpretation expertise that constrains workforce supply.
- Immunohistochemistry:Antibody-based protein detection on tissue sections supports diagnostic classification and therapy target identification, with premium-grade monoclonal antibody specificity requirements compressing margins on routine cancer panels.
Standardized deployment sits with Histopathology. Capability investment is concentrating in Molecular Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reagent manufacturing clusters in Massachusetts and North Carolina anchor supply-side capacity for molecular diagnostic consumables. Hospital consolidation and reference laboratory outsourcing patterns vary sharply across national healthcare systems.
United States
Precision oncology protocols at NCI-designated cancer centers drive demand for multiplex immunofluorescence platforms. FDA modernization of laboratory-developed test oversight is extending validation timelines for companion diagnostic assays. The Boston-Cambridge corridor concentrates biopharma pathology partnerships, while Texas integrated delivery networks consolidate managed service agreements.
Germany
Academic medical centers in Baden-Württemberg anchor histopathology automation adoption across university hospital networks. EU In Vitro Diagnostic Regulation reclassification rules are elevating clinical evidence requirements for moderate-risk devices. The Rhine-Main cluster around Frankfurt sustains reference laboratory capacity serving central European overflow testing.
India
Rising cancer incidence in metropolitan areas is opening reference laboratory partnerships with tertiary hospital networks. CDSCO regulatory streamlining is reducing product registration timelines for imported diagnostic instruments. Maharashtra's Mumbai-Pune corridor concentrates private diagnostic chains expanding molecular testing menus.
Japan
Aging demographics and universal health coverage sustain high per-capita diagnostic procedure volume. PMDA harmonization with FDA standards is accelerating approval pathways for companion diagnostic assays. The Kanto region around Tokyo anchors automated histopathology deployment at national cancer center hospitals.
United Kingdom
NHS pathology network consolidation is centralizing specialized molecular testing at regional hub laboratories. MHRA post-Brexit regulatory autonomy is recalibrating CE mark recognition timelines for IVD devices. The Greater Manchester cluster exemplifies integrated laboratory service delivery across acute hospital trusts.
Pathology Laboratories Market Key Industry Players
Strategic partnerships dominate the current landscape as hospital systems seek outsourced capacity for specialized molecular testing. The vendor base stratifies across three tiers: multinational reference laboratory networks, integrated diagnostic instrument manufacturers, and regional pathology service providers. Two strategic archetypes predominate: national logistics operators capturing volume through managed service agreements, and technology-integrated platforms converging imaging with pathology workflows. M&A activity and compliance infrastructure investments represent the dominant competitive moves reshaping market position.
Among reference laboratory specialists, Quest Diagnostics and Laboratory Corporation of America occupy positions as archetypal national logistics operators. Siemens Healthineers and Thermo Fisher Scientific exemplify the instrument-integrated platform archetype. Danaher Corporation sits within the precision diagnostics tier through its life sciences portfolio. F. Hoffmann-La Roche and Abbott Laboratories represent the pharmaceutical-diagnostic convergence model. These six entities collectively illustrate the competitive segmentation without exhaustively mapping market share.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Abbott Laboratories |
| Danaher Corporation |
| Laboratory Corporation of America |
| QIAGEN |
| F. Hoffmann-La Roche |
| Others |
Cost & Logistics Intelligence
Outsourced molecular testing partnerships anchor supply positioning for hospital systems while simultaneously constraining pricing power for independent pathology groups. This captive sourcing arrangement concentrates volume with national reference laboratory networks that leverage integrated logistics to extract multi-year managed service agreements from integrated delivery networks.
Pricing Analysis
Service bundling separates instrument placement and reagent supply from standalone assay pricing, with maintenance contracts and validation support included in premium-tier arrangements. Three-tier pricing structure across premium, standard, and economy levels tracks CLIA certification complexity and antibody specificity grade. Cost compression in routine immunohistochemistry panels intensifies as group purchasing organizations consolidate consumable contracts. Community hospital laboratories exhibit highest price sensitivity due to constrained capital budgets, while NCI-designated cancer centers prioritize assay breadth over unit cost.
Supply Chain Analysis
Monoclonal antibody production rests on Massachusetts and North Carolina biomanufacturing clusters, with specialized reagent formulation concentrated in Germany and Japan. Tissue processing consumables draw from Chinese molded plastics suppliers and German precision metalworking for microtome components. Single-source vulnerability persists for multiplex immunofluorescence detection chemistries subject to FDA import alerts. Distribution runs through regional medical distributors serving hospital procurement departments, with direct-to-laboratory channels gaining share for high-turnover reagent categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary antibody development and digital pathology software stacks has become the decisive competitive lever, with incumbents racing to control upstream reagent specificity and downstream interpretation workflows.
For Market Incumbents: Acquire molecular genomics interpretation platforms to anchor companion diagnostic assay pipelines against emerging AI-enabled pathology startups. Consolidate reference laboratory footprint in Texas and Florida integrated delivery networks before contract renewal cycles complete. Defensive capacity addition in Maharashtra and São Paulo offsets regulatory streamlining advantages for regional challengers. For New Entrants and Emerging Players: Capture liquid biopsy monitoring applications where tissue-based incumbents lack circulating tumor DNA expertise, penetrating community oncology practices with lower-complexity CLIA-waived assays. White-space concentration in India's tertiary hospital partnerships offers fastest regulatory pathway for imported instrument platforms. Go-to-market positioning through CDSCO-registered distributor networks reduces direct compliance overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diagnostic instrument manufacturers seeking software-enabled service revenue. Five-to-ten-year viability favors precision oncology assay developers with FDA breakthrough device designation momentum. Acquisition target archetype: mid-cap reference laboratories with captive payer contracts in concentrated geographies. Watch FDA laboratory-developed test oversight rulemaking as inflection trigger for compliance infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | Federal certification barriers filter subscale competitors from molecular diagnostics revenue pools. |
| Multiplex Assay Panel Expansion | Simultaneous biomarker detection commands premium pricing from precision oncology protocols. |
| Digital Pathology Platform Integration | Whole-slide imaging with AI modules creates remote interpretation capabilities for hospital networks. |
| Managed Service Agreement Consolidation | Multi-year contracts with Texas integrated delivery networks lock out independent pathology groups. |
| Companion Diagnostic Co-Development | Pharmaceutical partnerships anchor reimbursement pathways for next-generation sequencing panels. |
Research Approach
Document review covered FDA 510(k) filings, CMS Medicare reimbursement databases, and CAP accreditation records, complemented by interviews with pathology laboratory directors, hospital procurement managers, diagnostic instrument R&D heads, and molecular assay validation specialists. Secondary sources included CLIA certification registries, GPO contract disclosure databases, and EU IVDR technical documentation repositories. Bottom-up test volume modeling triangulated against top-down healthcare expenditure flows.
Historical adoption curves for immunohistochemistry automation cross-referenced against panel input from reference laboratory executives and cancer center medical directors. Segmentation dimensions spanned technology type, end-user purchasing authority, application urgency, and regional regulatory cluster. CAGRs derived from slope-intercept fitting across the projection horizon, with sensitivity analysis around FDA oversight timeline scenarios and CMS coverage determination patterns for next-generation sequencing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA laboratory-developed test final rule implementation and private payer prior authorization automation. Assumptions reflect current reimbursement paradigms and CLIA enforcement intensity. A small set of named triggers—CMS national coverage determination for liquid biopsy screening, EU IVDR notified body capacity constraints, and pathologist fellowship graduation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Pathology Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
LIMS Market