
 Cervical Implants Market | 2026-2036
Cervical Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Implants Market Analysis
Aftermarket service revenue is rewriting margin capture across the cervical implant value chain. NuVasive leverages its lateral single-position surgery ecosystem to sustain recurring instrument servicing contracts. Medtronic anchors its position through deep integration of navigation and intraoperative monitoring with cervical hardware.
Cervical implants are medical devices designed for spinal stabilization and motion preservation, typically constructed from titanium alloys, polyetheretherketone, or porous tantalum with surface modifications to promote osseointegration. These devices restore disc height, decompress neural elements, and stabilize vertebral segments following degenerative disease or trauma. Cervical discs command premium pricing due to motion-preservation functionality and complex biomechanical testing requirements, while interbody cages compete on material science differentiation with porous titanium and 3D-printed architectures. Minimally invasive surgery delivery modes are expanding fastest as robotic platforms reduce approach-related morbidity and enable outpatient migration.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation impose stringent biocompatibility, mechanical fatigue, and clinical evidence requirements that filter market participants by capital intensity. Japan's PMDA maintains distinct approval pathways for novel materials, creating staggered launch timelines across major jurisdictions. Stakeholders must monitor reimbursement parity between fusion and motion-preservation technologies as ambulatory site-of-service shifts accelerate.
Market Dynamics
The migration of cervical fusion and disc replacement procedures from inpatient hospitals to ambulatory surgical centers is restructuring capital deployment and reimbursement dynamics across the implant value chain. This site-of-service shift compresses procedure economics while demanding instrumentation portability and sterilization workflow redesign from manufacturers.
Growth Catalysts
- Aging demographics:Expanding Medicare-eligible populations in the United States, Germany, and Japan are generating surgical volume for degenerative cervical spine conditions requiring stabilization or motion-preservation interventions.
- MDR compliance acceleration:The EU Medical Device Regulation's enhanced clinical evidence requirements are filtering out marginal competitors and consolidating market share among capital-intensive manufacturers with robust quality management systems.
- Robotic platform integration:Minimally invasive surgical systems are reducing approach-related morbidity and enabling same-day discharge protocols that expand addressable procedure volume beyond traditional hospital settings.
Market Restraints
- Titanium alloy supply concentration:Aerospace and defense procurement priorities in the United States and Russia are constraining spot market availability of medical-grade titanium alloys, elevating raw material cost volatility for implant manufacturers.
- Reimbursement parity gaps:CMS and private payor coverage policies in the United States maintain differential payment rates for cervical fusion versus artificial disc replacement, distorting physician adoption of motion-preservation technologies.
- Biologics substitution:Orthobiologic adjuncts including demineralized bone matrix and synthetic bone graft substitutes are capturing incremental fusion procedure value, compressing hardware-only pricing power.
Strategic Opportunities
- India's surgical infrastructure buildout:Government hospital modernization programs and private healthcare investment in tier-2 cities are creating first-mover advantages for implant manufacturers establishing localized distribution and surgeon training capabilities.
- 3D-printed porous titanium architectures:Additive manufacturing enables patient-specific interbody cage geometries with optimized elastic modulus matching and enhanced osseointegration surfaces that command premium positioning.
- Japan's PMDA novel material pathway:Accelerated approval tracks for innovative surface coatings and PEEK-carbon composite constructs offer regulatory arbitrage for manufacturers with differentiated material science portfolios.
Industry Challenges
- Surgeon training bandwidth:Minimally invasive lateral and posterior cervical approaches require specialized cadaveric lab curricula and proctored case volumes that strain medical education department resources at mid-tier device firms.
- EU MDR technical documentation:Legacy implant products face costly clinical data gap assessments and notified body recertification timelines that threaten commercial continuity for portfolios with aging 93/42/EEC approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Implants Market |
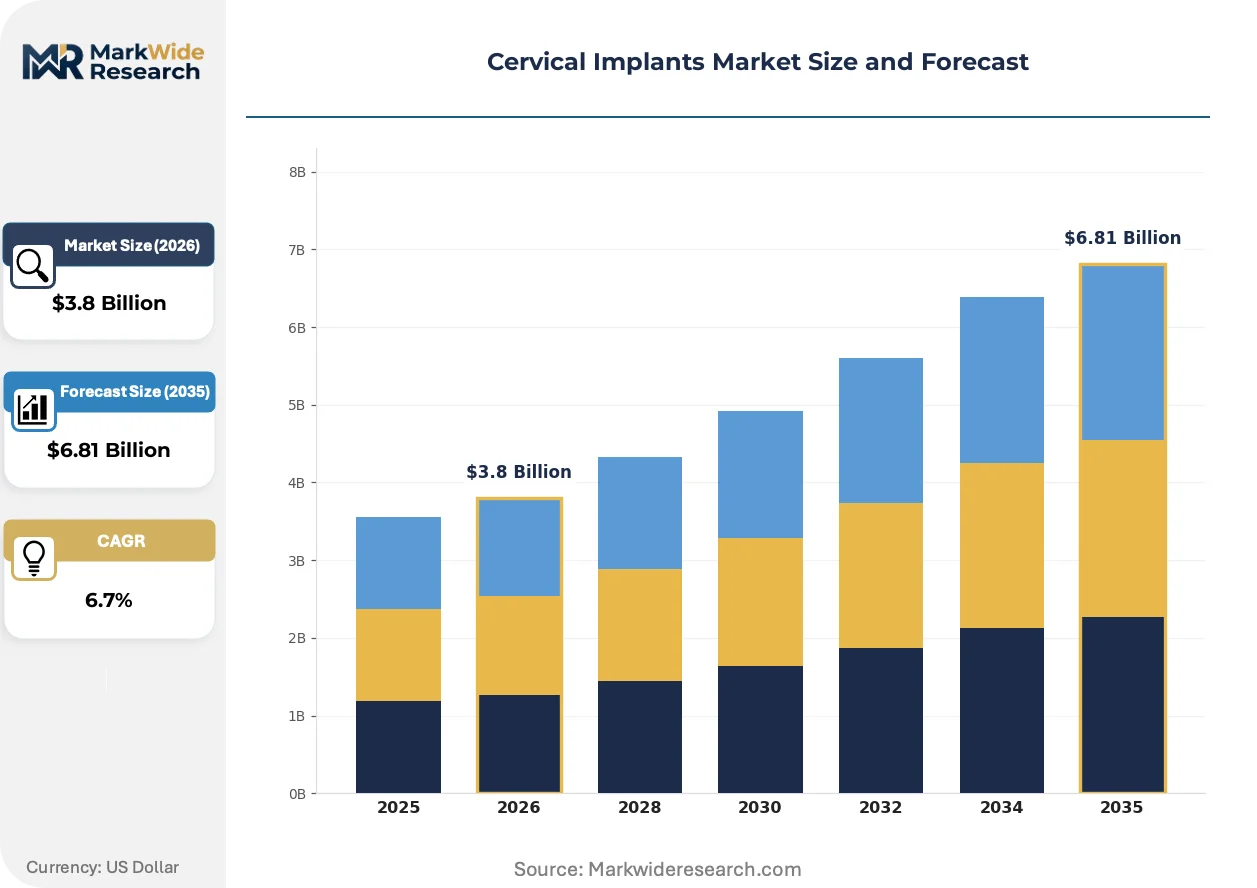
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cervical Discs, Cervical Plates, Interbody Cages, Spinal Rods End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Material: Metal, Polymer, Composite, Biologic Delivery Mode: Open Surgery, Minimally Invasive Surgery, Robotic-Assisted Surgery, Outpatient Procedures |
| Companies Covered | NuVasive, Zimmer Biomet, Medtronic, B. Braun Melsungen AG, Alphatec Spine, Johnson & Johnson (DePuy Synthes), Globus Medical, Orthofix International, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Implants Market Emerging Trajectories
Digital surgical planning and intraoperative navigation are virtualizing traditional freehand implant placement workflows, compressing learning curves while elevating precision requirements for hardware design. These converging capabilities are reshaping competitive differentiation beyond static implant mechanics.
Patient-specific 3D-printed titanium interbody cages with architected porosity gradients are virtualizing conventional machined solid-body geometries. Ambulatory surgical centers and high-volume hospital systems are adopting these constructs to reduce subsidence rates and accelerate fusion timelines. This technology is virtualizing the economic model for revision surgery prevention, shifting value capture toward upfront premium pricing justified by reduced downstream complication costs.
The EU Medical Device Regulation's post-market surveillance requirements and EUDAMED database integration are mandating systematic implant tracking and adverse event reporting across the product lifecycle. Manufacturers must restructure quality management systems to accommodate real-world performance monitoring. Small and mid-cap implant firms with limited regulatory affairs infrastructure face disproportionate compliance burdens relative to diversified orthopedic conglomerates.
Hospital procurement committees are consolidating vendor contracts and bundling cervical hardware with spinal navigation and neuromonitoring services. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that displace fragmented multi-vendor purchasing. This concentration is most visible in Texas and Florida health systems where ambulatory spine joint ventures are capturing migration of commercial payer cases from traditional hospital outpatient departments.
Cervical Implants Market Segmentation
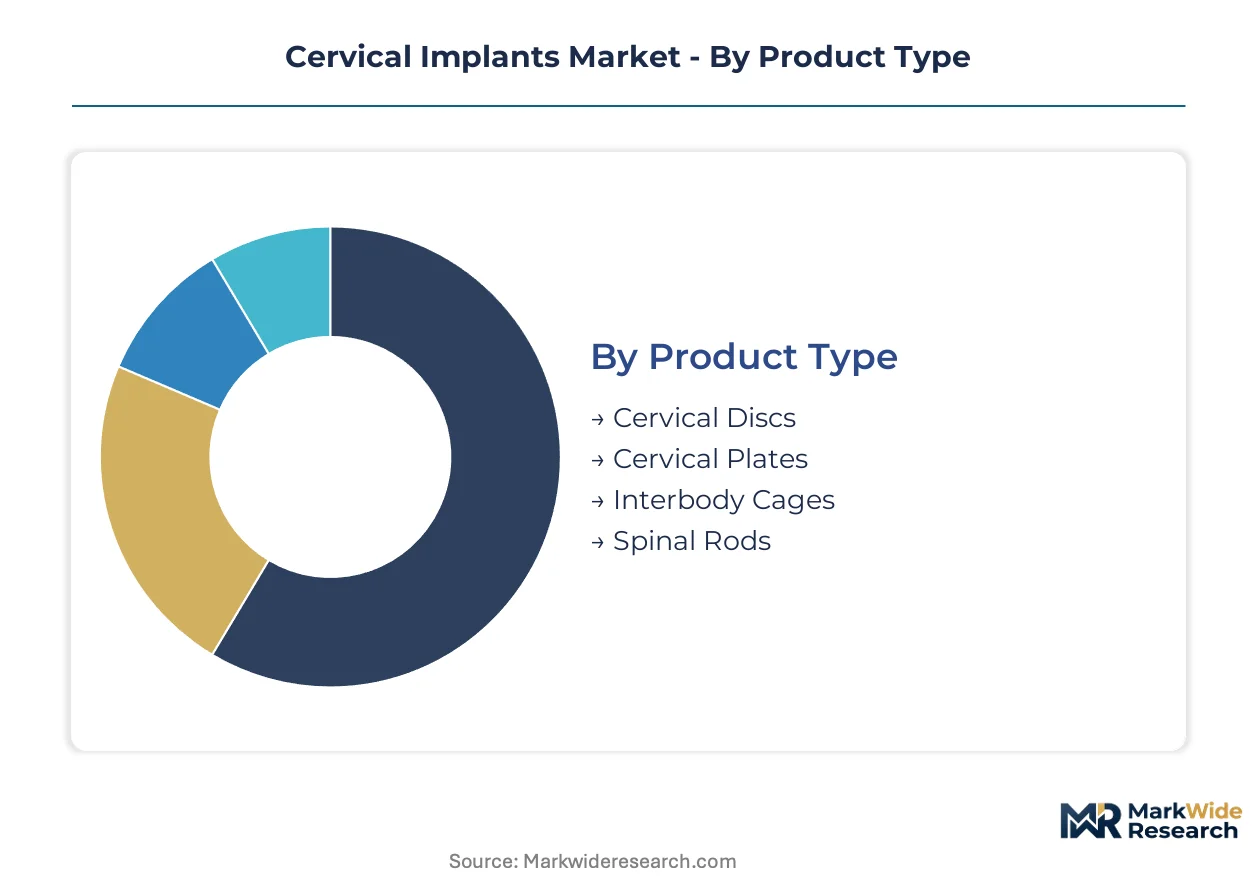
Segmentation in cervical implants determines both procurement economics and after-sales service intensity. Product complexity, surgical setting, and material science differentiation create distinct margin profiles and recurring revenue opportunities across categories.
Product Type:
After-sales service intensity varies sharply by implant category, with motion-preservation devices demanding specialized instrument maintenance and surgeon recertification programs.
- Cervical Discs:These articulating bearings replicate physiologic motion through metal-on-polymer or metal-on-metal interfaces. Demand concentrates in ambulatory surgical centers across the United States and Germany, where commercial payor reimbursement parity supports premium positioning for motion-preservation over fusion alternatives.
- Cervical Plates:Anterior screw-plate constructs stabilize multilevel fusions through titanium alloy or cobalt-chrome designs. Japanese hospitals and German orthopedic centers drive procurement volume, constrained by MDR clinical evidence requirements that filter out marginal suppliers lacking robust mechanical fatigue testing data.
- Interbody Cages:PEEK and porous titanium spacers restore disc height with osteoconductive surface modifications.
- Spinal Rods:Posterior stabilization systems anchor lateral mass and pedicle screw constructs.
By volume, Interbody Cages leads. By growth pace, Cervical Discs is climbing the fastest.
End User:
Site-of-service economics reshape capital deployment patterns, with outpatient migration compressing hardware pricing while expanding addressable procedure volume.
- Hospitals:Inpatient facilities maintain dominance for complex multilevel revisions and trauma cases requiring extended monitoring. Academic medical centers in the United States and Japan anchor procurement of navigation-integrated systems.
- Ambulatory Surgical Centers:These settings capture migration of single-level fusions and disc replacements, enabled by robotic platforms and enhanced recovery protocols. Texas and Florida health systems are consolidating vendor contracts around bundled navigation and neuromonitoring services.
- Specialty Clinics:Focused spine centers concentrate high-volume surgeons and drive rapid adoption of patient-specific 3D-printed constructs.
- Rehabilitation Centers:Post-acute facilities influence implant selection through outcomes data feedback to referring surgeons.
By procedure count, Hospitals dominates. By expansion trajectory, Ambulatory Surgical Centers is gaining share fastest.
Material:
Raw material cost volatility and osseointegration performance create tiered pricing architectures across implant substrates.
- Metal:Titanium alloys and cobalt-chrome dominate load-bearing applications with established fatigue resistance. Aerospace procurement competition in the United States and Russia constrains medical-grade titanium spot availability, elevating input cost uncertainty.
- Polymer:PEEK and PEEK-carbon composites offer radiolucency and elastic modulus matching to native bone. Japan's PMDA maintains distinct approval pathways for novel polymer formulations.
- Composite:Hybrid constructs combine metallic strength with polymeric flexibility.
- Biologic:Demineralized bone matrix and synthetic graft substitutes capture incremental fusion procedure value.
By implant volume, Metal leads. By technology differentiation, Composite is expanding most quickly.
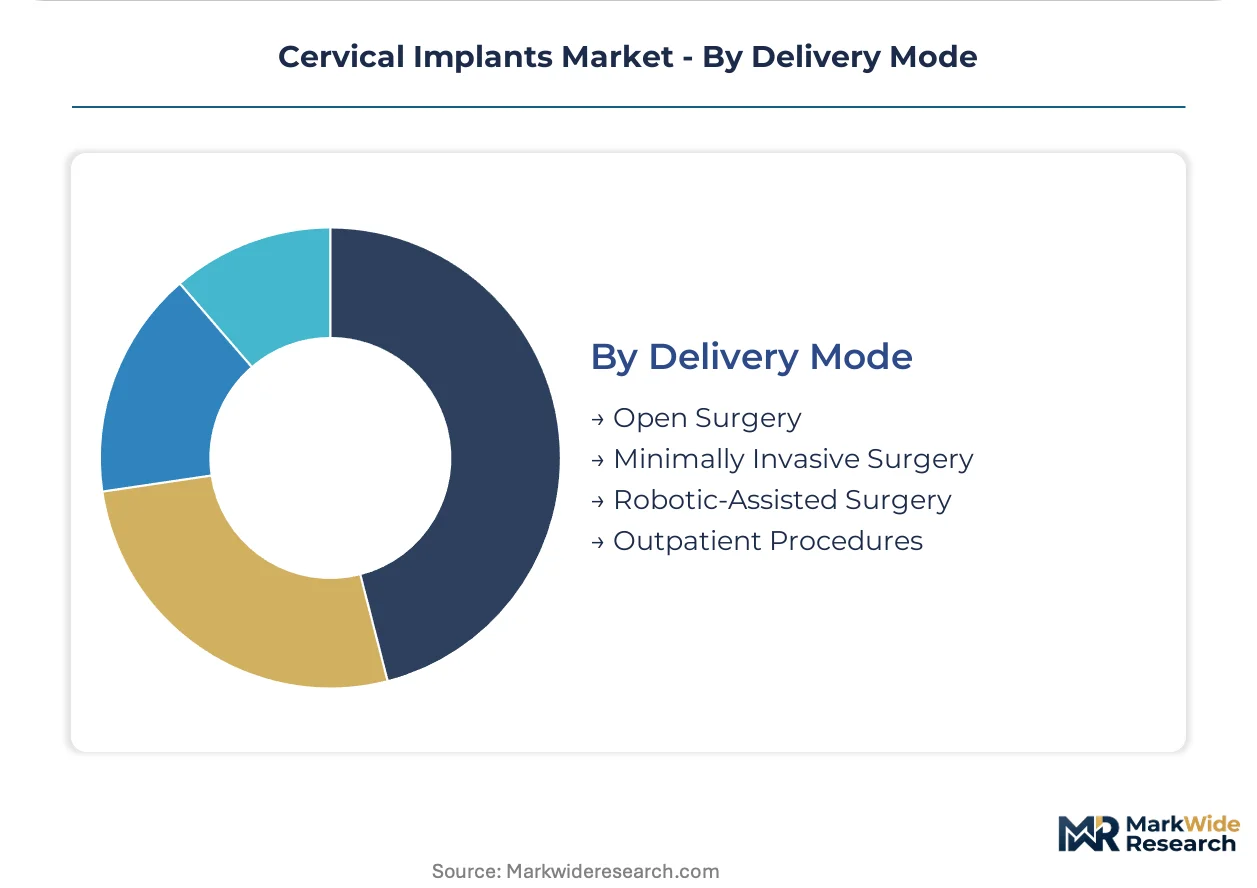
Delivery Mode:
Surgical approach selection determines instrumentation portability requirements and sterilization workflow complexity for manufacturers.
- Open Surgery:Traditional anterior and posterior approaches remain standard for complex deformity and trauma cases. German and Japanese training programs maintain cadaveric lab curricula emphasizing open technique mastery.
- Minimally Invasive Surgery:Lateral and posterior tubular approaches reduce approach-related morbidity and enable same-day discharge. United States ambulatory joint ventures are capturing commercial payer case migration through MIS protocols.
- Robotic-Assisted Surgery:Navigation platforms compress learning curves and elevate precision requirements for hardware design. Integrated delivery networks negotiate multi-year sole-source agreements bundling robotic systems with implant contracts.
- Outpatient Procedures:Same-day discharge protocols demand portable instrumentation and streamlined sterilization workflows.
By current procedure volume, Open Surgery leads. By adoption velocity, Robotic-Assisted Surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States surgeons favor motion-preservation disc replacements in ambulatory settings, while German and Japanese clinicians maintain stronger preference for multilevel fusion constructs. This consumption-mix differential shapes regulatory investment and product launch sequencing across major jurisdictions.
United States
Medicare-eligible population expansion and commercial payor reimbursement parity for artificial disc replacement drive procedural volume. The FDA's 510(k) premarket notification framework filters entrants through biocompatibility and mechanical fatigue requirements. Texas and Florida health systems consolidate vendor contracts around bundled navigation and neuromonitoring services.
Germany
German orthopedic centers anchor procurement of anterior cervical plate systems and navigation-integrated platforms. The EU Medical Device Regulation imposes enhanced clinical evidence requirements that filter marginal suppliers lacking robust quality management systems. The Rhine-Ruhr metropolitan region concentrates high-volume spine centers adopting patient-specific 3D-printed constructs.
Japan
Aging demographics and degenerative disc disease prevalence generate surgical demand for stabilization and motion-preservation interventions. Japan's PMDA maintains distinct approval pathways for novel materials including PEEK-carbon composites, creating staggered launch timelines. The Kanto region around Tokyo anchors academic medical center procurement of navigation-integrated systems.
India
Government hospital modernization programs and private healthcare investment in tier-2 cities create first-mover opportunities for implant manufacturers. The Central Drugs Standard Control Organization regulates medical device imports and domestic manufacturing under the Medical Device Rules framework. Maharashtra and Karnataka states concentrate private hospital infrastructure buildout and surgeon training capabilities.
United Kingdom
NHS procurement frameworks and integrated care systems reshape vendor selection criteria toward value-based outcomes. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, diverging from EU MDR timelines. London and the Southeast concentrate private spine centers driving adoption of minimally invasive surgical protocols.
Cervical Implants Market Vendor Landscape
Capability concentration sits with diversified orthopedic conglomerates possessing integrated navigation and neuromonitoring portfolios; scale advantage sits with mid-tier specialists leveraging lateral single-position surgery ecosystems. The market structure tiers across capital-intensive manufacturers with robust regulatory affairs infrastructure and regional players with limited MDR compliance bandwidth. Three archetypes dominate: diversified medical technology conglomerates, spine-focused device specialists, and emerging additive manufacturing innovators. Competitive moves center on multi-year sole-source agreements with integrated delivery networks and backward integration into patient-specific 3D-printed titanium architectures.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson (DePuy Synthes) exemplify the integrated-systems archetype through deep hardware-software bundling. NuVasive and Globus Medical occupy positions within the spine-specialist tier, with NuVasive representing the lateral-approach ecosystem model and Globus Medical exemplifying robotic-platform integration strategies. Zimmer Biomet and Stryker sit within the orthopedic conglomerate tier, leveraging broad trauma and joint reconstruction portfolios to cross-sell cervical hardware.
| Leading Market Players |
|---|
| NuVasive |
| Zimmer Biomet |
| Medtronic |
| B. Braun Melsungen AG |
| Alphatec Spine |
| Johnson & Johnson (DePuy Synthes) |
| Globus Medical |
| Orthofix International |
| Stryker |
| Others |
Supply Flow & Price Mechanics
The Trans-Pacific maritime corridor from Shanghai to Los Angeles feeds medical-grade titanium alloy spot markets where aerospace procurement competition elevates raw material cost volatility, compressing margins for implant manufacturers while amplifying price differentiation between capital-intensive conglomerates and mid-tier specialists lacking long-term offtake security.
Pricing Analysis
Long-term offtake agreements anchor procurement economics for diversified orthopedic conglomerates, while spot market exposure punishes smaller manufacturers. Three-tier pricing structure across premium motion-preservation discs, standard interbody cages, and economy-grade anterior plates reflects FDA 510(k) clearance tier and bundled navigation service intensity. Cost compression in standard cages is intensifying because biologics substitution captures incremental fusion procedure value. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with bundled navigation contracts show lowest.
Supply Chain Analysis
United States export controls on advanced manufacturing technologies constrain additive manufacturing equipment flows to medical device producers in China and Russia, fragmenting 3D-printed titanium cage production networks. Supply concentrates in the United States for medical-grade titanium alloys, Germany for precision machining equipment, and Switzerland for surface coating technologies. Raw material dependencies include titanium sponge from Japan, PEEK polymer from the United Kingdom, and cobalt-chrome feedstock from South Africa. Single-source vulnerability in electron beam melting equipment threatens patient-specific implant scalability. Distribution runs through specialized orthopedic distributors and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cervical implant manufacturers face substitution defense imperatives as orthobiologic adjuncts capture incremental fusion procedure value, eroding hardware-only pricing power and forcing portfolio restructuring toward integrated biologics-hardware bundles.
For Market Incumbents: Insulate core fusion hardware margins through backward integration into demineralized bone matrix and synthetic graft substitutes, neutralizing biologics substitution threats. Deepen captive supply of medical-grade titanium alloys through long-term offtake agreements with Japanese sponge producers, reducing spot market exposure. Anchor hospital system loyalty by bundling cervical hardware with navigation and neuromonitoring services under multi-year sole-source contracts. For New Entrants and Emerging Players: Tier-2 cities in Maharashtra and Karnataka states represent the most penetrable entry point for first-mover manufacturers establishing localized distribution and surgeon training capabilities ahead of infrastructure saturation. Patient-specific 3D-printed titanium interbody cages with architected porosity gradients offer regulatory arbitrage through Japan's PMDA novel material pathway, bypassing congested FDA 510(k) queues. Pursue direct-to-hospital contracting models bypassing established distributor networks. For Investors and Strategic Acquirers: Additive manufacturing innovators with proprietary electron beam melting workflows and patient-specific design software represent the highest-conviction acquisition archetype for portfolio differentiation. Long-term viability hinges on regulatory compliance bandwidth under EU MDR post-market surveillance requirements and EUDAMED database integration. Monitor CMS reimbursement parity decisions between cervical fusion and artificial disc replacement as inflection indicator for motion-preservation technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Overhaul | Legacy implant portfolios face costly clinical data gap assessments and notified body recertification timelines under enhanced evidence requirements. |
| Robotic Platform Integration | Navigation-integrated cervical systems compress learning curves and elevate precision requirements, enabling same-day discharge protocols. |
| Patient-Specific 3D-Printed Cage Development | Additive manufacturing with architected porosity gradients commands premium positioning through optimized elastic modulus matching. |
| Biologics-Hardware Bundle Structuring | Integrated delivery networks negotiate multi-year contracts combining demineralized bone matrix with interbody cage systems. |
| India Distribution Infrastructure Buildout | Government hospital modernization programs in tier-2 cities create first-mover advantages for localized surgeon training capabilities. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement contract filings preceded structured interviews with spine surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads at diversified orthopedic conglomerates and mid-tier device specialists. Secondary validation drew from CMS Medicare reimbursement data, Japanese PMDA approval records, and customs trade statistics for medical-grade titanium alloy flows. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across the analysis window.
Assumptions held reimbursement parity between cervical fusion and artificial disc replacement constant at current CMS levels, while varying ambulatory surgical center case migration velocity and robotic platform adoption curves across sensitivity scenarios. Segmentation dimensions modeled include product type complexity, end-user site-of-service economics, material science differentiation tiers, and delivery mode surgical approach intensity. CAGRs derived from regression-based trending of procedure volumes against demographic projections and technology diffusion patterns, with titanium alloy cost volatility and MDR compliance timelines as key forecast inputs.
Practitioners should monitor FDA artificial disc replacement coverage determinations, EU MDR recertification bottlenecks, and aerospace titanium procurement cycles for early signals of forecast deviation. Material shifts in CMS reimbursement parity or novel biologics substitution rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Powered Mattress System Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Organ Preservation Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
India Medical Devices Market
Medical Devices
Pericardial Patches Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Breast Lesion Localization Device Market