
 Frozen Tissues Samples Market | 2026-2036
Frozen Tissues Samples Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Tissues Samples Market Foresight
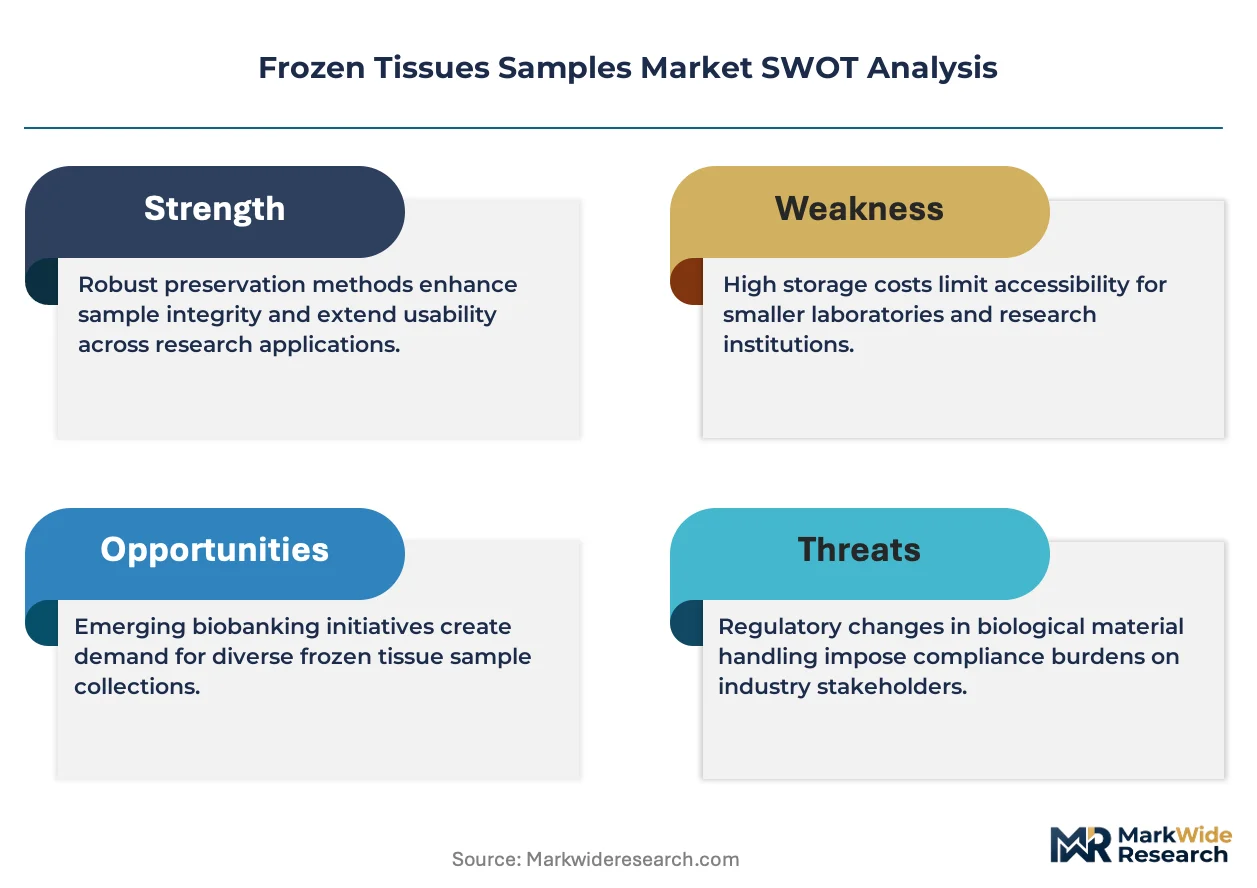
Clinical-grade specimen certification is collapsing the gap between research-use and diagnostic-use frozen tissues. OriGene Technologies leverages its geographic dominance in North American biobanking to sustain premium positioning. Precision for Medicine anchors its competitive stance through deep vertical integration into specimen logistics and analytics services. REPROCELL differentiates via specialized expertise in induced pluripotent stem cell-derived frozen tissue products.
Frozen tissues samples are biological specimens preserved at ultra-low temperatures, typically below minus 130 degrees Celsius, to maintain cellular morphology, nucleic acid integrity, and protein stability for downstream molecular analysis. Their primary commercial purpose centers on enabling reproducible genomic, proteomic, and histopathological studies across drug discovery and precision medicine workflows. Cryopreserved specimens command the largest volume share among product types, while formalin-fixed frozen alternatives are gaining traction where simultaneous morphology and molecular profiling prove essential. Diagnostic research applications occupy the most mature margin pool, though pharmaceutical development segments exhibit the fastest structural expansion as sponsors internalize biobank capabilities.
The FDA governs human tissue collection under 21 CFR Part 1271, while the EMA's tissue and cell directive shapes European quality benchmarks; ISO 20387 provides international biobanking standards that increasingly determine market access for cross-border specimen commerce. These frameworks compel facilities to invest in controlled-rate freezing infrastructure and chain-of-custody documentation systems. Stakeholders must monitor evolving harmonization between FDA quality expectations and emerging WHO biobank guidelines to anticipate compliance cost trajectories.
Market Dynamics
FDA's updated 21 CFR Part 1271 guidance on human tissue quality standards is compressing collection and storage protocols across the biobanking sector, forcing facilities to upgrade controlled-rate freezing infrastructure and chain-of-custody documentation systems to maintain market access.
Growth Catalysts
- Pharmaceutical pipeline expansion:Drug sponsors are internalizing biobank capabilities to accelerate biomarker validation for precision medicine programs.
- ISO 20387 adoption:International biobanking standards are enabling cross-border specimen commerce and harmonizing quality benchmarks across jurisdictions.
- Cryopreservation technology maturation:Ultra-low temperature storage below minus 130 degrees Celsius now preserves nucleic acid integrity for reproducible genomic analysis.
Market Restraints
- Liquid nitrogen supply volatility:Cryogenic coolant costs fluctuate with energy markets, squeezing facility operating margins.
- Controlled-rate freezer capex concentration:Equipment procurement concentrates among three specialized manufacturers, creating supplier lock-in risk.
- EMA tissue directive compliance burden:European quality benchmarks require redundant documentation systems that duplicate FDA protocols without mutual recognition.
Strategic Opportunities
- Formalin-fixed frozen alternatives:Simultaneous morphology and molecular profiling capabilities open diagnostic pathology workflows previously closed to cryopreserved specimens.
- Induced pluripotent stem cell derivatives:iPSC-derived frozen tissue products address donor scarcity in rare disease research applications.
- India biobank infrastructure buildout:CDSCO regulatory alignment with international standards creates export-capable collection hubs for pharmaceutical contract research.
Industry Challenges
- Cold chain custody documentation:Facilities struggle to deploy integrated informatics platforms that reconcile temperature logging with specimen provenance tracking.
- Clinical-grade certification timelines:Diagnostic-use frozen tissue qualification extends research-use validation cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Tissues Samples Market |
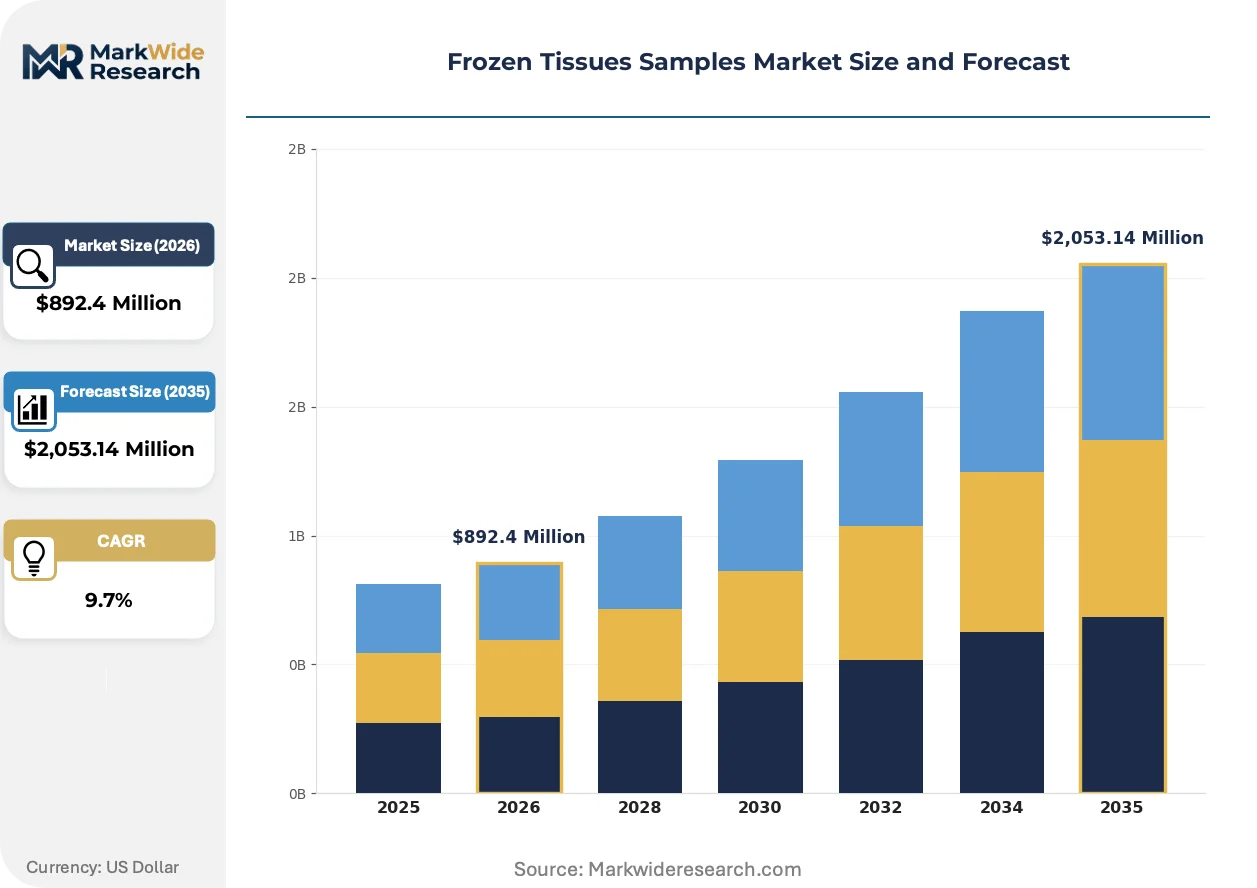
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,053.14 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Frozen, Cryopreserved, Formalin-Fixed Frozen, Embedding Frozen Application: Diagnostic Research, Pharmaceutical Development, Genetic Analysis, Disease Modeling End User: Biotechnology Firms, Academic Institutions, Contract Research Organizations, Pathology Labs Storage Method: Liquid Nitrogen, Mechanical Freezers, Cryogenic Vials, Controlled Rate Freezers |
| Companies Covered | Precision for Medicine, ProteoGenex, Bay Biosciences, ZenBio, OriGene Technologies, BioChain Institute, Audubon Bioscience, REPROCELL, US Biolab Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Tissues Samples Market Shifts & Advancements
Automation and digitization are restructuring how frozen tissues move from collection through molecular analysis, with three developments commanding strategic attention from biobank operators and specimen buyers.
Automated liquid handling systems for nucleic acid extraction from cryopreserved specimens are miniaturizing sample processing workflows. Academic medical centers and contract research organizations are adopting these platforms at accelerating pace. This compression of manual touchpoints is reducing contamination risk while enabling higher-throughput biomarker screening.
REACH chemicals regulation in Europe is restricting cryoprotectant formulations containing dimethyl sulfoxide alternatives with higher environmental toxicity profiles. Biobank facilities must reformulate storage media or source compliant substitutes. Pharmaceutical sponsors with pan-European specimen networks face the steepest reformulation costs.
Buyers are consolidating vendor relationships around vertically integrated specimen logistics and analytics providers. Large pharmaceutical developers are displacing fragmented supplier networks with single-source contracts covering collection, cryopreservation, and downstream molecular profiling. This concentration is most visible in United States markets where major biobanks and CRO clusters operate in geographic proximity.
Frozen Tissues Samples Market Segmentation
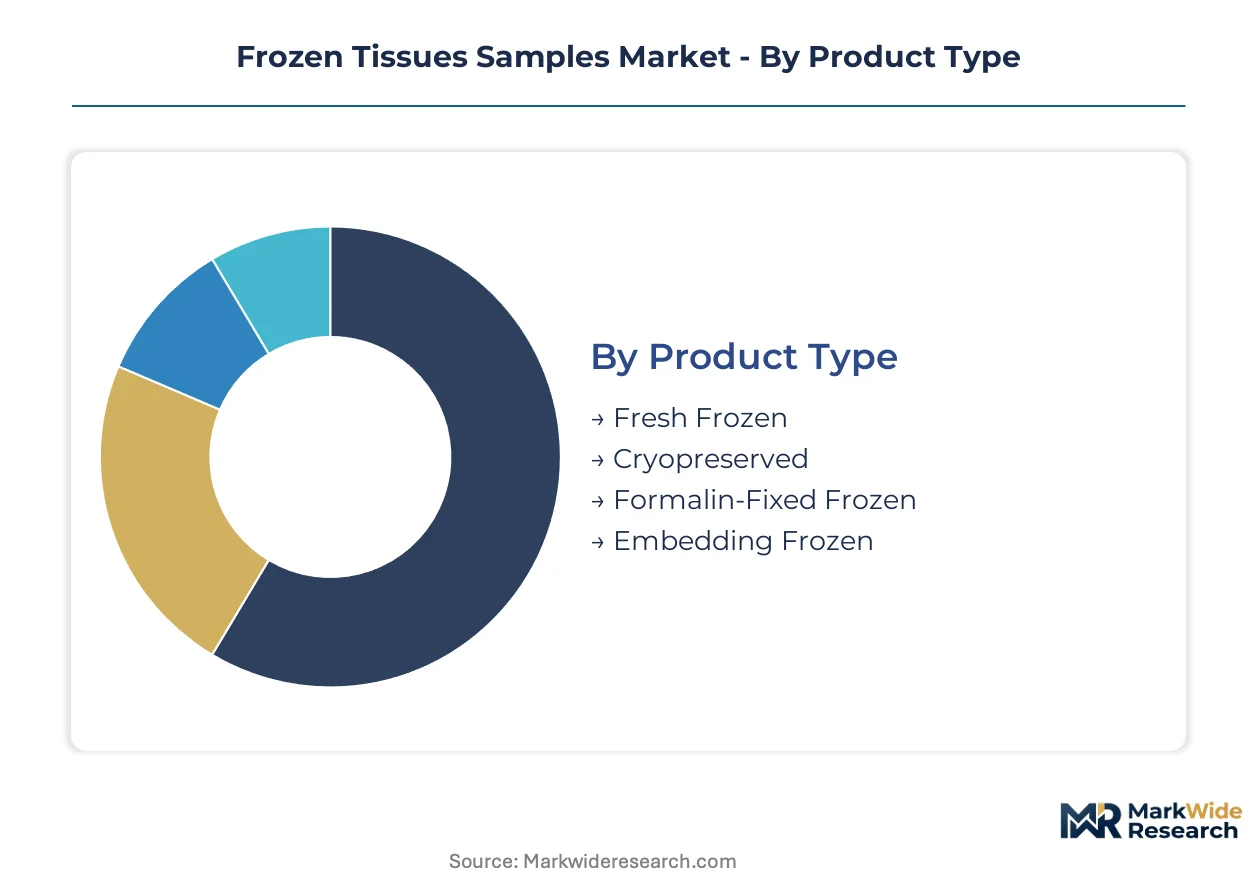
Frozen tissue specimens flow through distinct commercial channels based on preservation chemistry and downstream analytical requirements. Segmentation reveals where procurement concentrates among biopharma sponsors versus diagnostic developers.
Product Type:
Cryopreserved and fresh frozen specimens dominate pharmaceutical procurement channels, while formalin-fixed alternatives route through diagnostic pathology networks.
- Cryopreserved:Ultra-low temperature preservation below minus 130 degrees Celsius maintains nucleic acid integrity for genomic and proteomic workflows. Pharmaceutical sponsors in the United States source these specimens through vertically integrated biobank contracts for biomarker validation programs. Demand concentrates where reproducible molecular analysis is non-negotiable.
- Fresh Frozen:Rapid freezing without cryoprotectant preserves native protein conformation for immunohistochemistry applications. Academic medical centers and pathology labs in research-intensive clusters favor this format for immediate histological assessment. Supply constraints limit scale for commercial drug development.
- Formalin-Fixed Frozen:Dual-preservation approach enabling simultaneous morphology and molecular profiling from single specimens.
- Embedding Frozen:Tissue blocks frozen in optimal cutting temperature compound for sectioning precision.
Cryopreserved specimens dominate installed base. Fresh frozen is where expansion concentrates for precision medicine workflows.
Application:
Cost tiering separates mature diagnostic research from capital-intensive pharmaceutical development segments.
- Pharmaceutical Development:Sponsors internalize biobank capabilities to accelerate target validation and companion diagnostic co-development. FDA's 21 CFR Part 1271 quality standards tighten specimen qualification timelines, extending research-use validation cycles by 18-24 months for diagnostic-grade certification.
- Diagnostic Research:Clinical-grade specimen certification collapses the gap between research-use and diagnostic-use frozen tissues. Pathology labs and reference laboratories in the United States represent the most mature margin pool, with established reimbursement pathways for molecular diagnostic assays.
- Genetic Analysis:Genomic profiling applications spanning hereditary disease screening and pharmacogenomics.
- Disease Modeling:Rare disease research leveraging induced pluripotent stem cell-derived frozen tissue products.
Diagnostic research commands revenue concentration. Pharmaceutical development is climbing the fastest as sponsors build captive biobank infrastructure.
End User:
Customer type determines procurement sophistication, from standardized catalog purchases to bespoke collection contracts.
- Biotechnology Firms:Mid-stage biotech sponsors in Boston and San Diego clusters drive demand for prospectively collected specimens with rich clinical annotation. These buyers consolidate vendor relationships around single-source contracts covering collection, cryopreservation, and downstream molecular profiling.
- Contract Research Organizations:CROs in the United States act as intermediaries managing multi-site specimen logistics for pharmaceutical sponsors. Their procurement emphasizes chain-of-custody documentation and temperature logging integration.
- Academic Institutions:University medical centers with NIH-funded biorepositories.
- Pathology Labs:Hospital-based and commercial reference laboratories processing routine diagnostic specimens.
Biotechnology firms dominate premium segment procurement. Contract research organizations are gaining share fastest as sponsor outsourcing deepens.
Storage Method:
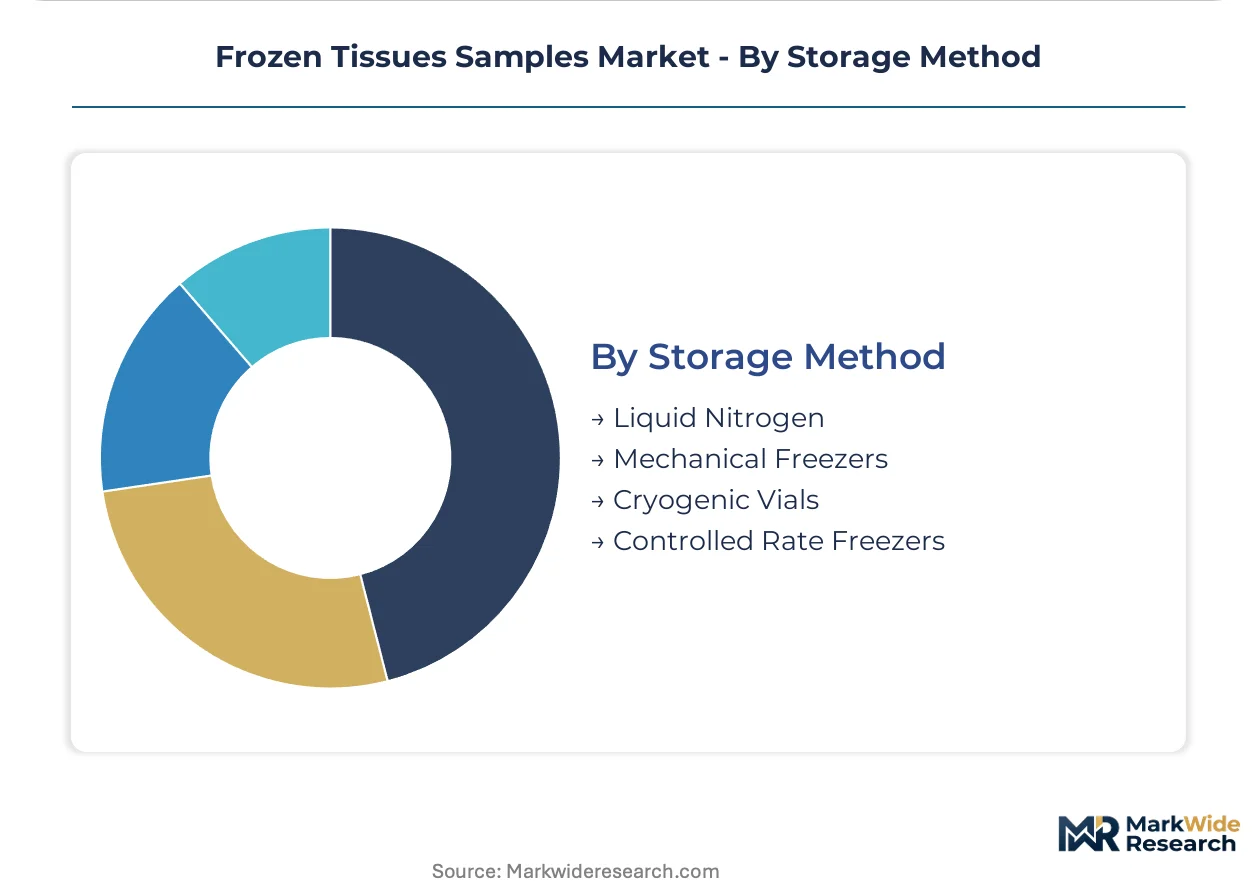
Supply concentration among three controlled-rate freezer manufacturers creates equipment lock-in risk across facility networks.
- Liquid Nitrogen:Vapor-phase storage at minus 150 to minus 196 degrees Celsius represents the gold standard for long-term nucleic acid preservation. Energy market volatility squeezes operating margins as cryogenic coolant costs fluctuate.
- Controlled Rate Freezers:Programmable freezing profiles prevent ice crystal formation during cryopreservation. FDA quality expectations and ISO 20387 biobanking standards compel facilities to invest in this infrastructure for cross-border specimen commerce.
- Mechanical Freezers:Minus 80 degree Celsius units for short-term holding and working specimen banks.
- Cryogenic Vials:Container standardization for specimen aliquoting and barcode tracking.
Liquid nitrogen dominates long-term preservation infrastructure. Controlled rate freezers represent the steepest expansion trajectory as quality standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor countries with harmonized biobanking standards and proximity to pharmaceutical R&D clusters. The United States maintains a structural surplus in high-annotation specimens, while Germany and Japan rely on controlled import channels for rare disease research materials.
United States
FDA's 21 CFR Part 1271 quality standards and NIH-funded biorepositories drive specimen certification demand. The country's national pharmaceutical regulator enforces chain-of-custody documentation for cross-state commerce. Boston and San Diego clusters anchor biotechnology firm procurement of prospectively collected tissues with rich clinical annotation.
Germany
EMA tissue directive compliance and REACH chemicals regulation reshape cryoprotectant formulation requirements. The country's national pharmaceutical regulator mandates redundant documentation systems that parallel FDA protocols. Heidelberg and Munich medical centers concentrate academic biobank infrastructure for pan-European specimen distribution.
Japan
PMDA quality benchmarks and METI biobank standardization initiatives accelerate ISO 20387 adoption. The country's national pharmaceutical regulator aligns domestic protocols with international commerce requirements. Tokyo and Osaka clusters host induced pluripotent stem cell-derived tissue specialists serving Asia-Pacific pharmaceutical sponsors.
India
CDSCO regulatory alignment with international standards and pharmaceutical contract research expansion create export-capable collection hubs. The country's national pharmaceutical regulator streamlines specimen export licensing for biotech sponsors. Hyderabad and Bangalore clusters concentrate CRO-managed multi-site specimen logistics infrastructure.
United Kingdom
MHRA post-Brexit quality framework and NHS biobank network integration sustain specimen commerce capabilities. The country's national pharmaceutical regulator maintains equivalence recognition with FDA and EMA standards. London and Cambridge clusters anchor diagnostic research applications with established molecular assay reimbursement pathways.
Frozen Tissues Samples Market Competitive Landscape
Concentration sits with vertically integrated specimen logistics providers and specialized cryopreservation technology developers. The vendor base stratifies across three tiers: multinational biobank operators with captive analytics capabilities, regional collection specialists with deep clinical site relationships, and niche technology providers focused on iPSC-derived alternatives. Strategic moves center on backward integration into collection site networks and technology licensing partnerships for automated processing platforms.
Among North American biobank operators, OriGene Technologies and Precision for Medicine exemplify the vertically integrated archetype with end-to-end specimen logistics and analytics services. REPROCELL occupies a distinct position within the iPSC-derived tissue specialization tier. These three anchors represent contrasting competitive vectors: geographic dominance through biobank density, deep vertical integration into specimen logistics, and differentiated expertise in stem cell-derived products.
| Leading Market Players |
|---|
| Precision for Medicine |
| ProteoGenex |
| Bay Biosciences |
| ZenBio |
| OriGene Technologies |
| BioChain Institute |
| Audubon Bioscience |
| REPROCELL |
| US Biolab Corporation |
| Others |
Supply & Pricing Matrix
FDA's 21 CFR Part 1271 quality standards gate both supply qualification and price differentiation simultaneously, compelling facilities to invest in controlled-rate freezing infrastructure before accessing premium diagnostic-grade specimen contracts. Pharmaceutical sponsors absorb these certification costs through long-term offtake agreements, while smaller research buyers face tiered access based on annotation depth and chain-of-custody documentation completeness.
Pricing Analysis
Pharmaceutical development sponsors anchor pricing stratification across premium, standard, and economy tiers, with clinical-grade certification and ISO 20387 compliance serving as the primary price differentiation drivers. Cost compression in the economy tier is intensifying because liquid nitrogen supply volatility squeezes facility operating margins. Academic medical centers exhibit the highest price sensitivity due to constrained NIH funding cycles, while biotechnology firms in Boston and San Diego clusters demonstrate lowest sensitivity when prospectively collected specimens carry rich clinical annotation.
Supply Chain Analysis
Just-in-time specimen logistics dominate pharmaceutical sponsor procurement, though strategic stockpiling of rare disease materials persists among induced pluripotent stem cell specialists in Japan. Supply concentrates in the United States, Germany, and Japan, with cryogenic coolant production and controlled-rate freezer manufacturing drawing from specialized industrial gas suppliers and precision equipment fabricators. Single-source vulnerability in liquid nitrogen infrastructure represents the dominant supply chain risk. Distribution runs through vertically integrated biobank operators with captive analytics capabilities rather than fragmented collection site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen tissues samples sit within early-cycle expansion as pharmaceutical pipelines internalize biobank capabilities for precision medicine biomarker validation, with ISO 20387 adoption accelerating cross-border specimen commerce penetration.
For Market Incumbents: Shield market position by deepening backward integration into collection site networks before emerging iPSC-derived tissue specialists capture rare disease research contracts. Prioritize certification investment for FDA diagnostic-grade qualification to extend research-use validation cycles into 18-24 month competitive moats. Control channel access through single-source logistics contracts covering cryopreservation and downstream molecular profiling.
For New Entrants and Emerging Players: Differentiate on induced pluripotent stem cell-derived tissue specialization where donor scarcity creates white-space opportunity in rare disease research applications. Target India biobank infrastructure buildout as CDSCO regulatory alignment with international standards creates export-capable collection hubs for pharmaceutical contract research. Pursue technology licensing partnerships for automated liquid handling platforms as the go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-rate freezer infrastructure as FDA quality expectations tighten, favoring scaled operators with existing equipment networks. Long-term viability centers on vertically integrated specimen logistics providers with captive analytics capabilities rather than regional collection specialists. Watch for REACH chemicals regulation compliance costs as the inflection indicator signaling which European facilities can sustain pan-continental specimen networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Certification Investment | FDA 21 CFR Part 1271 compliance extends research-use validation cycles into diagnostic-grade qualification timelines. |
| Backward Integration into Collection Sites | Captive supply of prospectively annotated specimens secures premium positioning against fragmented regional competitors. |
| iPSC-Derived Product Line Expansion | REPROCELL's specialization vector demonstrates addressable market creation in donor-scarce rare disease applications. |
| Automated Processing Platform Deployment | Miniaturized nucleic acid extraction systems reduce contamination risk while enabling higher-throughput biomarker screening. |
| Pan-European Logistics Network Consolidation | REACH chemicals regulation compliance costs displace smaller facilities unable to reformulate cryoprotectant formulations. |
Research Methodology
Operator-level perspectives from biobank facility directors, pharmaceutical development executives, regulatory affairs leads, and contract research organization procurement managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA 21 CFR Part 1271 guidance documents, EMA tissue directive filings, ISO 20387 biobanking standards, and ClinicalTrials.gov specimen procurement disclosures. Bottom-up facility capacity modeling and top-down pharmaceutical sponsor spending estimates were triangulated to cross-verify volume and value outputs.
Sensitivity analysis framed the forecast construction across cryopreserved, fresh frozen, formalin-fixed frozen, and embedding frozen product types intersecting with pharmaceutical development, diagnostic research, genetic analysis, and disease modeling applications. Modeled dimensions included preservation chemistry, downstream analytical requirements, end-user procurement sophistication, and regional regulatory cluster alignment. CAGRs were derived from facility expansion pipelines and sponsor biobank internalization trends, with liquid nitrogen cost volatility and controlled-rate freezer capex cycles serving as key industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained ISO 20387 harmonization progress and stable cryogenic coolant supply chains would require recalibration. Forecasts reflect assumptions regarding FDA-EMA quality standard convergence and pharmaceutical sponsor willingness to absorb diagnostic-grade certification premiums. Revision becomes warranted when REACH chemicals regulation enforcement crosses thresholds that trigger widespread cryoprotectant reformulation failures or when CDSCO regulatory alignment in India stalls export licensing streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Central Lab Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
LIMS Market
Laboratory Services
Global Virology Specimen Collection Market