
 Global Clinical Reference Laboratory Market | 2026-2036
Global Clinical Reference Laboratory Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Reference Laboratory Market Foresight
The shift from hospital-based in-house testing toward outsourced reference laboratory partnerships is rebalancing procurement patterns across health systems. Quest Diagnostics leverages its national logistics network to sustain specimen volume leadership in routine diagnostics. Mayo Clinic Laboratories anchors its competitive position through subspecialty esoteric testing that differentiates on clinical interpretation depth. Eurofins Scientific competes aggressively in molecular diagnostics through European laboratory density and cross-border accreditation harmonization.
A clinical reference laboratory performs complex diagnostic analyses on patient specimens using standardized methodologies such as mass spectrometry, immunoassays, and next-generation sequencing platforms to support physician decision-making and disease management. These facilities operate at higher testing volumes and technical sophistication than hospital laboratories, enabling economies of scale for esoteric and specialized assays. Molecular diagnostics and genetic testing represent the fastest-expanding service categories as precision medicine protocols expand oncology and rare disease workflows. High-throughput screening technology dominates routine chemistry and hematology processing where automation drives per-test cost efficiency, while next-generation sequencing commands premium positioning in tumor profiling and pharmacogenomic applications.
The FDA enforces Clinical Laboratory Improvement Amendments quality standards that govern test accuracy, personnel qualifications, and proficiency testing across US reference laboratories, directly shaping operational compliance costs and market entry barriers. EMA regulatory frameworks for companion diagnostics and in vitro diagnostic medical devices in Europe create parallel certification requirements that influence cross-border service expansion strategies. Stakeholders must monitor evolving reimbursement policies for laboratory-developed tests and precision diagnostic categories as payers recalibrate coverage criteria for molecular and genetic assay portfolios.
Market Dynamics
Hospital networks across the United States are dismantling in-house diagnostic infrastructure in favor of outsourced reference laboratory partnerships, fundamentally reallocating capital from fixed assets to variable testing contracts.
Growth Catalysts
- Precision medicine protocols:Oncology and rare disease workflows are expanding molecular diagnostics and genetic testing portfolios across clinical networks.
- CLIA quality standards:The FDA's Clinical Laboratory Improvement Amendments create accreditation barriers that favor high-volume reference laboratories over fragmented hospital labs.
- Germany's aging demographics:Centralized laboratory networks serving multiple federal states concentrate demand for high-throughput esoteric testing.
Market Restraints
- Reimbursement compression:Payer recalibration of coverage criteria for laboratory-developed tests squeezes margins on molecular and genetic assay portfolios.
- Cross-border accreditation friction:EMA frameworks for companion diagnostics and in vitro diagnostic medical devices create parallel certification requirements that slow European expansion.
- Next-generation sequencing capital intensity:Tumor profiling and pharmacogenomic platforms require substantial upfront investment with extended utilization ramp periods.
Strategic Opportunities
- India's diagnostic infrastructure gaps:CDSCO regulatory pathways for in vitro diagnostics remain underdeveloped relative to testing demand from tier-2 and tier-3 cities.
- Mass spectrometry-immunoassay convergence:Hybrid analytical platforms enable simultaneous quantitative and qualitative biomarker detection in single workflows.
- Direct-to-physician digital channels:Electronic health record integration and portal-based test ordering bypass traditional hospital procurement committees.
Industry Challenges
- Specialized personnel scarcity:CLIA-mandated qualifications for high-complexity testing directors limit operational scaling in competitive labor markets.
- Legacy laboratory information system integration:Hospital IT architectures require costly middleware development to connect with reference laboratory data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Reference Laboratory Market |
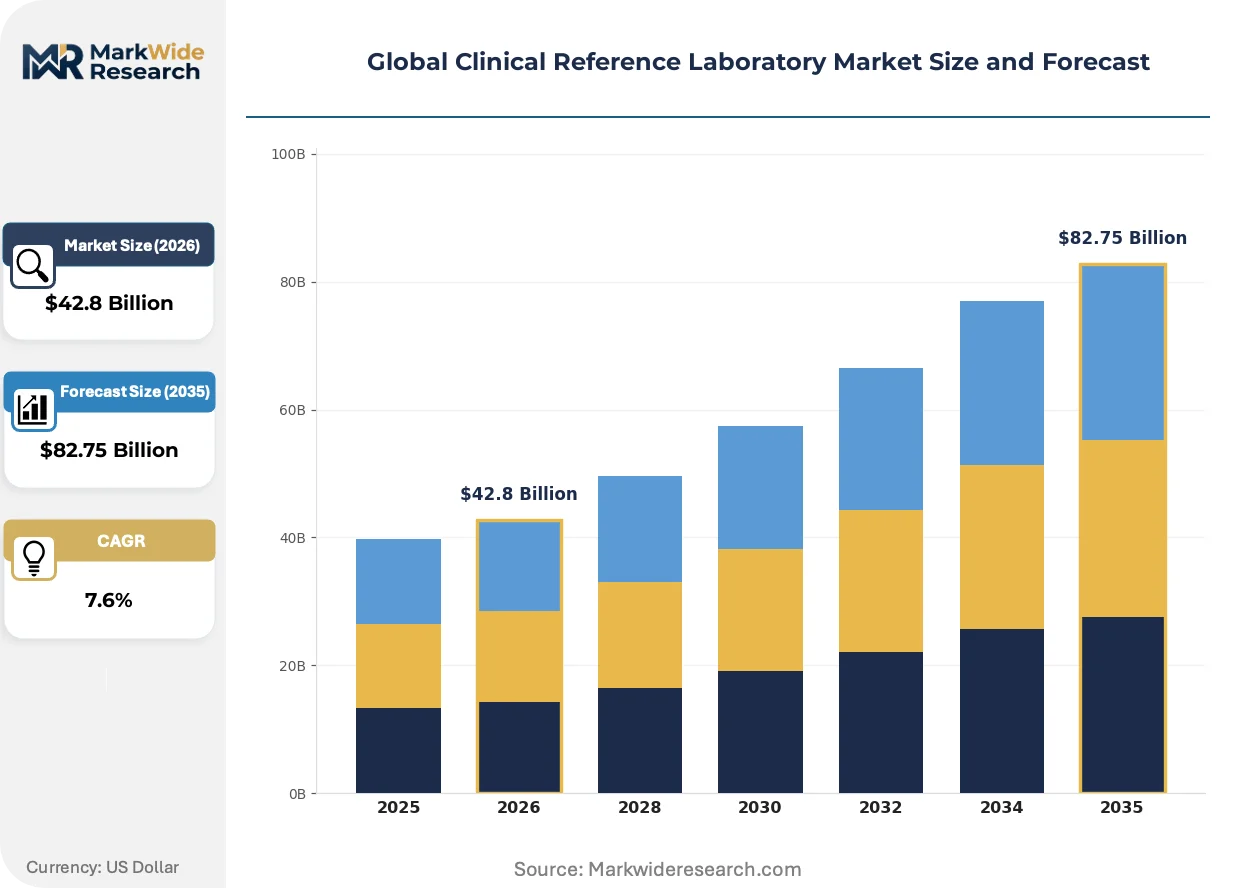
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Testing, Molecular Diagnostics, Genetic Testing, Microbiology Services, Toxicology Screening Technology: High-Throughput Screening, Mass Spectrometry, Immunoassays, Next-Generation Sequencing, Polymerase Chain Reaction Client Type: Hospitals, Private Clinics, Research Institutes, Pharmaceutical Companies, Government Agencies Sample Type: Blood, Urine, Tissue Biopsies, Saliva, Cerebrospinal Fluid |
| Companies Covered | Sonic Healthcare, Mayo Clinic Laboratories, Quest Diagnostics, Fresenius Medical Care, OPKO Health (BioReference Health), Laboratory Corporation of America, Siemens Healthineers, ARUP Laboratories, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Reference Laboratory Market Shifts & Advancements
Next-generation sequencing platforms are compressing turnaround times for tumor profiling while mass spectrometry advances expand metabolomics applications. These technological currents are restructuring competitive differentiation around analytical depth rather than specimen volume alone.
Mass spectrometry-based proteomics is electrifying clinical toxicology and therapeutic drug monitoring workflows. Hospital laboratories lacking in-house capability are outsourcing these assays to reference providers with dedicated LC-MS/MS infrastructure. This capability gap is electrifying consolidation pressure as smaller reference laboratories face capital barriers to platform adoption.
The EMA's In Vitro Diagnostic Medical Devices Regulation is extending conformity assessment timelines for companion diagnostics. European reference laboratories must now maintain notified body certifications across multiple member states to sustain cross-border specimen flows. Germany's centralized laboratory networks are responding by harmonizing quality management systems ahead of 2027 transition deadlines.
Physician ordering patterns are fragmenting as specialist societies release divergent guidelines for molecular testing appropriateness. Academic medical centers are establishing internal test utilization committees that override reference laboratory preference lists. This governance shift is most visible in United States oncology practices where prior authorization requirements for next-generation sequencing panels have multiplied.
Global Clinical Reference Laboratory Market Segmentation
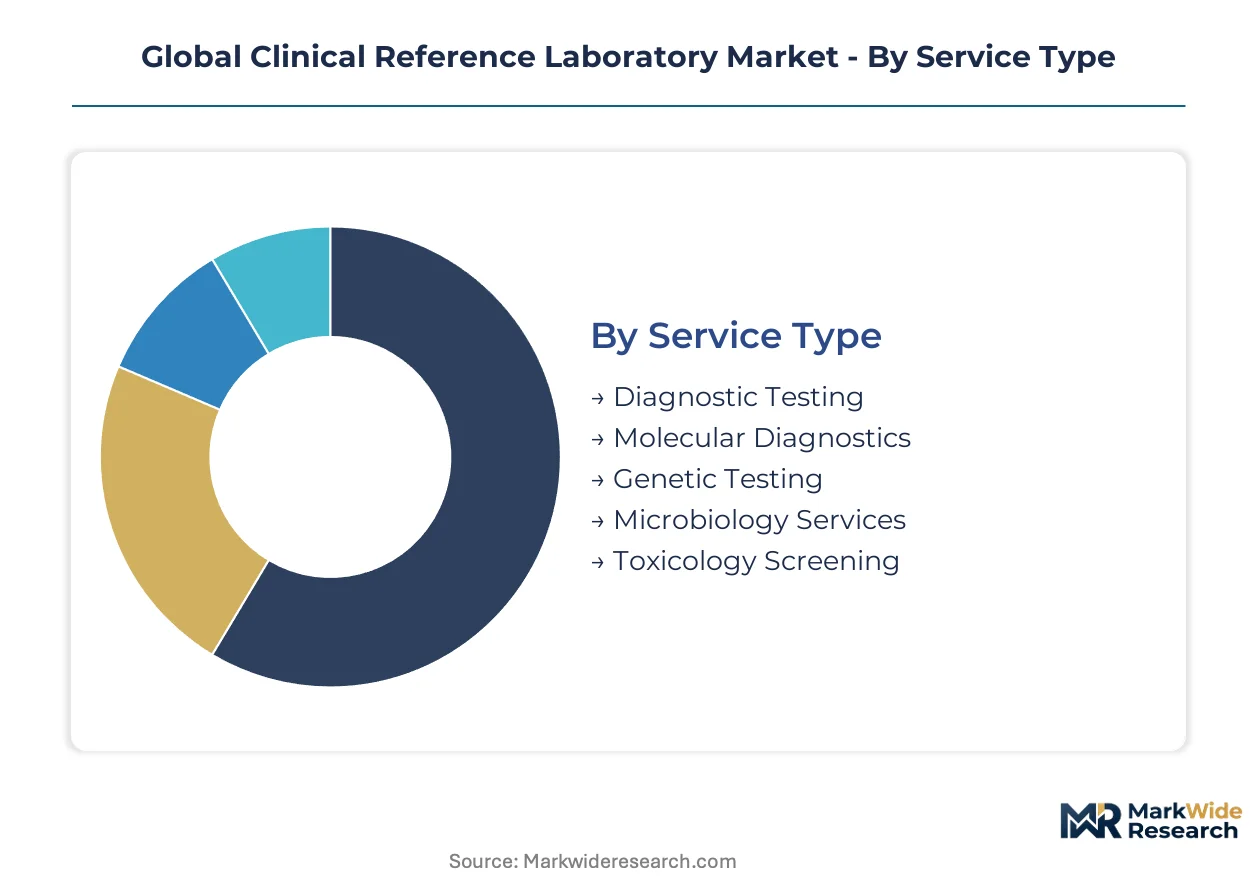
Service differentiation in clinical reference laboratories determines capital allocation, regulatory pathway complexity, and reimbursement positioning across health systems. Technology integration depth and client procurement maturity further stratify competitive advantage within each segment category.
Service Type:
Standalone diagnostic testing operates through discrete laboratory workflows, while molecular and genetic services embed into precision medicine protocols requiring clinical interpretation depth.
- Diagnostic Testing:Routine chemistry and hematology panels processed through automated high-throughput analyzers. Hospital networks in Germany outsource these high-volume assays to centralized reference providers to eliminate fixed infrastructure costs.
- Molecular Diagnostics:Oncology biomarker detection and infectious disease genotyping using nucleic acid amplification platforms. United States academic medical centers concentrate demand for companion diagnostic testing aligned with FDA-approved therapeutic protocols.
- Genetic Testing:Pharmacogenomic and carrier screening applications.
- Microbiology Services:Antimicrobial susceptibility testing and pathogen identification.
- Toxicology Screening:Workplace compliance and forensic applications.
Diagnostic Testing leads volumes today; Molecular Diagnostics is gaining share fastest.
Technology:
Capital intensity and personnel qualification requirements create tiered barriers to platform adoption across laboratory networks.
- High-Throughput Screening:Automated chemistry and immunoassay systems processing thousands of specimens daily. United States hospital consolidations drive demand for outsourced routine testing where per-unit economics favor centralized scale.
- Next-Generation Sequencing:Tumor profiling and germline variant detection requiring bioinformatics pipelines. Germany's centralized laboratory networks are expanding NGS capacity to serve oncology practices across multiple federal states.
- Mass Spectrometry:Therapeutic drug monitoring and metabolomics applications.
- Immunoassays:Endocrine and cardiac marker quantification.
- Polymerase Chain Reaction:Rapid pathogen detection and viral load quantification.
High-Throughput Screening dominates current test volumes; Next-Generation Sequencing shows the steepest expansion trajectory.
Client Type:
Procurement sophistication varies from centralized hospital contracting to decentralized physician ordering through electronic health record portals.
- Hospitals:Health system laboratory directors negotiate multi-year reference testing contracts. United States hospital networks are dismantling in-house esoteric testing capabilities in favor of outsourced partnerships.
- Pharmaceutical Companies:Clinical trial biomarker services and companion diagnostic co-development. EMA regulatory frameworks for in vitro diagnostic medical devices shape European contracting requirements.
- Private Clinics:Direct-to-physician ordering for specialized assays.
- Research Institutes:Investigational use and protocol development services.
- Government Agencies:Public health surveillance and forensic applications.
Hospitals anchor current revenue concentration; Pharmaceutical Companies are expanding contract value most rapidly.
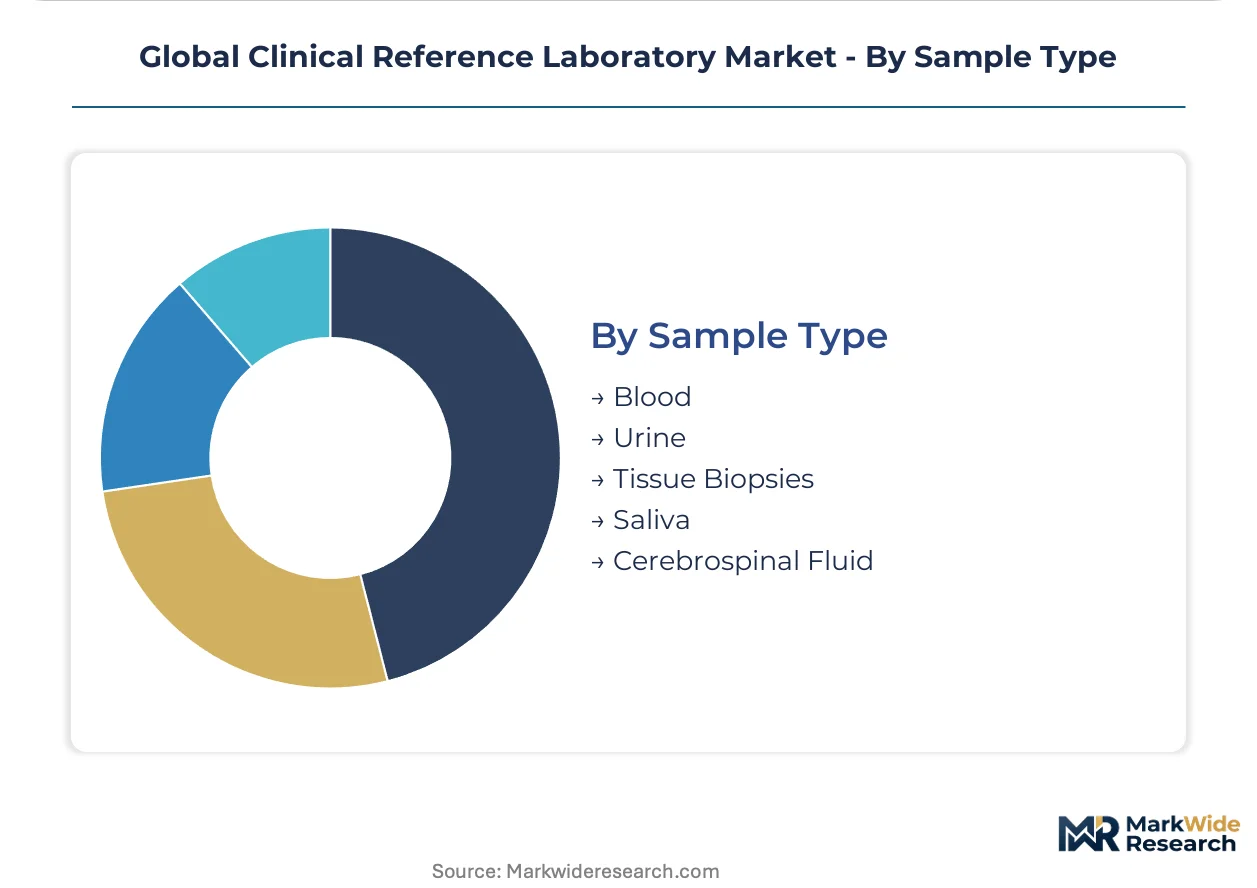
Sample Type:
Collection logistics and stability requirements determine geographic service radius and processing location strategy.
- Blood:Serum and plasma-based chemistry, hematology, and immunoassay testing. Germany's centralized laboratory networks optimize specimen transport from rural federal states to urban processing hubs.
- Tissue Biopsies:Formalin-fixed paraffin-embedded samples for histopathology and molecular profiling. United States oncology practices concentrate demand for rapid turnaround tumor sequencing.
- Urine:Toxicology and metabolic screening applications.
- Saliva:Non-invasive genetic and infectious disease detection.
- Cerebrospinal Fluid:Neurological and infectious disease diagnostics.
Blood samples dominate processing volumes; Tissue Biopsies command premium pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hospital laboratory outsourcing wave concentrates procurement authority within centralized health system contracting offices. Germany's federal laboratory networks optimize specimen logistics across rural and urban catchment areas. India's tier-2 city diagnostic infrastructure gaps attract reference laboratory expansion capital.
United States
Hospital network consolidation dismantles in-house esoteric testing capabilities across multi-state health systems. The FDA's Clinical Laboratory Improvement Amendments enforce personnel qualification standards that favor high-volume reference laboratories over fragmented hospital operations. Academic medical centers in Boston and the Research Triangle concentrate companion diagnostic testing demand aligned with oncology therapeutic protocols.
Germany
Centralized laboratory networks serve aging populations across multiple federal states with high-throughput screening infrastructure. The EMA's In Vitro Diagnostic Medical Devices Regulation extends conformity assessment timelines for cross-border specimen flows. Bavaria's Munich-Stuttgart corridor anchors molecular diagnostics capacity expansion to meet oncology biomarker demand from southern federal states.
India
Tier-2 and tier-3 cities generate unmet diagnostic demand as outpatient volumes outstrip hospital laboratory capacity. The CDSCO's underdeveloped in vitro diagnostic regulatory pathways create market entry flexibility for reference laboratory operators. Maharashtra's Mumbai-Pune cluster attracts capital deployment for centralized processing hubs serving western state networks.
China
Urban hospital overcrowding shifts routine diagnostic volumes toward independent reference laboratory chains. The NMPA's medical device registration requirements shape quality management system investments for molecular testing platforms. The Yangtze River Delta's Shanghai-Suzhou axis concentrates next-generation sequencing capacity serving precision medicine initiatives across eastern provinces.
United Kingdom
NHS consolidation of pathology services into regional hub laboratories accelerates outsourced reference testing partnerships. The MHRA's post-Brexit regulatory divergence from EU frameworks creates parallel certification requirements for cross-border IVD suppliers. London's Imperial College-Francis Crick corridor anchors genomic medicine research translation into clinical diagnostic workflows.
Global Clinical Reference Laboratory Market Competitive Landscape
Global majors compete with regional champions across specimen volume leadership and subspecialty esoteric depth. National logistics networks and cross-border accreditation harmonization create tiered competitive positions. Three archetypes dominate: integrated health system laboratories, commercial reference chains with density advantages, and academic medical center spin-outs with interpretation depth. M&A consolidation and EHR-integrated digital ordering channels represent the dominant competitive moves reshaping procurement relationships.
Among US-based reference laboratory operators, Quest Diagnostics and Laboratory Corporation of America occupy positions as scale-driven specimen processors with national logistics infrastructure. Mayo Clinic Laboratories exemplifies the academic medical center archetype, anchoring competitive differentiation through subspecialty clinical interpretation depth rather than throughput volume alone. Sonic Healthcare represents the international consolidator model with laboratory density across multiple geographies.
| Leading Market Players |
|---|
| Sonic Healthcare |
| Mayo Clinic Laboratories |
| Quest Diagnostics |
| Fresenius Medical Care |
| OPKO Health (BioReference Health) |
| Laboratory Corporation of America |
| Siemens Healthineers |
| ARUP Laboratories |
| Eurofins Scientific |
| Others |
Supply & Pricing Matrix
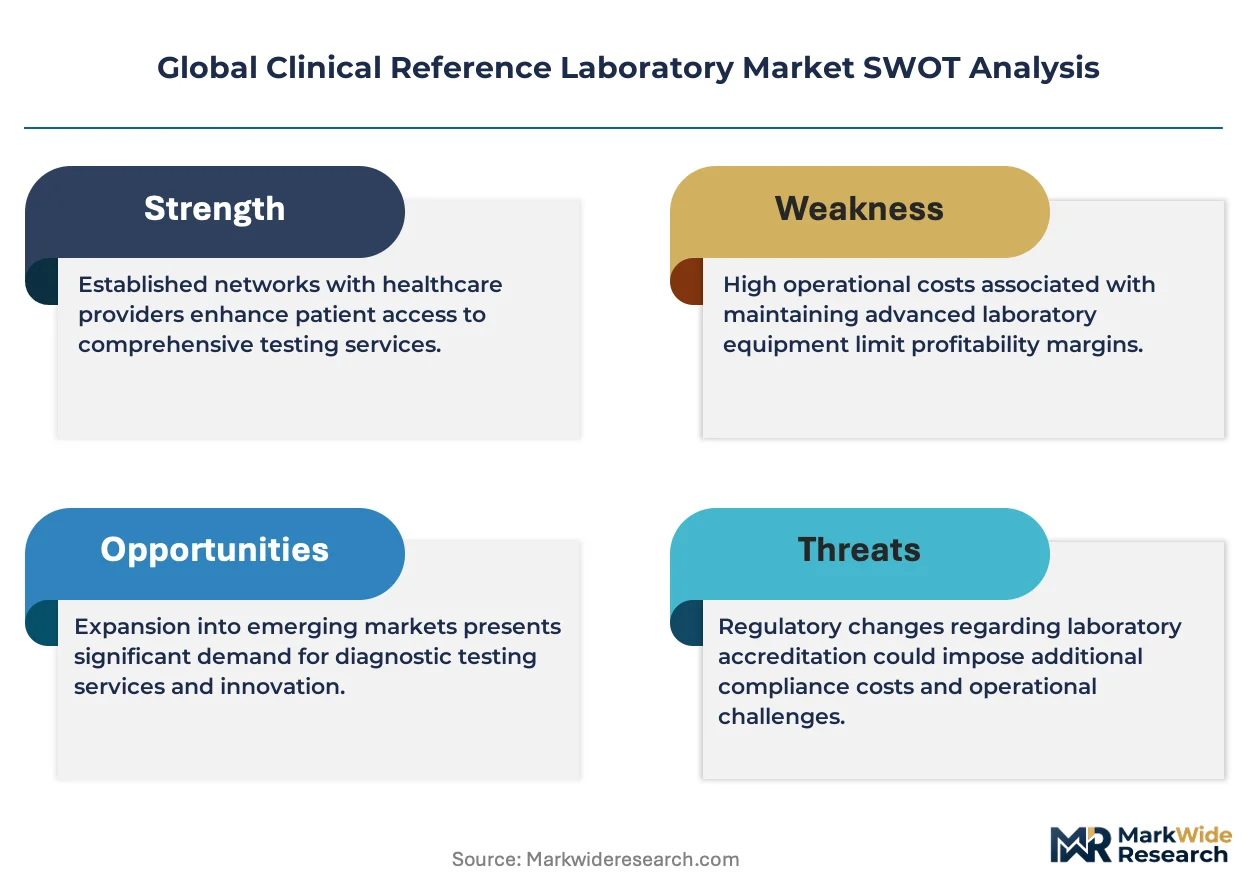
Hospital procurement consolidation across United States health systems is squeezing reference laboratory margins, forcing suppliers to restructure cost bases and abandon low-volume esoteric assays that fail scale thresholds.
Pricing Analysis
Reagent and consumable cost pass-through dominates contract economics, with CLIA-mandated quality tiers creating price stratification across high-complexity certification levels. Volume scale and geographic delivery density differentiate standard from premium positioning, while reimbursement compression from Medicare Advantage plans intensifies pricing pressure in molecular diagnostics. Academic medical centers exhibit lowest price sensitivity due to clinical interpretation requirements; routine chemistry panels face highest commoditization.
Supply Chain Analysis
FDA CLIA and EMA IVDR certifications gate supplier qualification, concentrating instrument and reagent sourcing among United States, Germany, and China manufacturing hubs. Supply chains draw from specialized biochemical reagents, diagnostic-grade plastics, and sequenced oligonucleotide libraries. Single-source dependency on Illumina sequencing platforms creates vulnerability concentration. Distribution runs through hospital system logistics networks and direct-to-physician courier services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in molecular diagnostics as automation drives per-test cost reduction and oncology biomarker panels command premium positioning.
For Market Incumbents: Anchor competitive position through EMA IVDR pre-certification investments ahead of 2027 transition deadlines, while consolidating esoteric testing capabilities in Germany's Munich-Stuttgart corridor to exploit centralized laboratory network procurement. Defend against physician ordering fragmentation by embedding test ordering portals within Epic and Cerner electronic health record workflows. For New Entrants and Emerging Players: The premium-economy price gap in next-generation sequencing tumor profiling creates white-space opportunity in India's tier-2 cities, where CDSCO regulatory flexibility permits faster platform deployment than United States or European markets. Target Maharashtra's Mumbai-Pune cluster with mass spectrometry-immunoassay hybrid platforms for therapeutic drug monitoring, leveraging direct-to-clinic digital channels to bypass hospital procurement committees. For Investors and Strategic Acquirers: Asymmetric upside sits with academic medical center laboratory spin-outs possessing CLIA high-complexity director benches and subspecialty interpretation depth. Long-term viability hinges on molecular diagnostics portfolio concentration rather than routine chemistry volume leadership. Watch for FDA laboratory-developed test reimbursement policy shifts as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | Creates accreditation moats against hospital laboratory re-internalization attempts in the United States. |
| EMA IVDR Notified Body Pre-Certification | Accelerates cross-border specimen flows across Germany's federal laboratory networks before 2027 deadlines. |
| Epic EHR Integration Partnership | Bypasses hospital procurement committee gatekeeping through embedded test ordering workflows. |
| Next-Generation Sequencing Platform Scale-Up | Captures oncology biomarker demand from United States academic medical centers and Germany's southern federal states. |
| India Tier-2 City Hub Deployment | Exploits CDSCO regulatory gaps to establish centralized processing infrastructure ahead of formal pathway development. |
Research Methodology
Coverage spans the United States, Germany, India, China, and the United Kingdom, with primary inputs from each market gathered through interviews with hospital laboratory directors, reference laboratory operations executives, CLIA compliance officers, and EMA regulatory affairs specialists. Secondary validation drew from FDA CLIA guidance documents, EMA IVDR implementation timelines, CMS Medicare laboratory fee schedules, and hospital procurement database extracts. Bottom-up test volume modeling triangulated against top-down health system expenditure analysis.
Rate-of-change decomposition structured the analytical framework across the projection horizon, with segmentation dimensions spanning service type, technology platform, client procurement sophistication, and specimen logistics requirements. CAGRs derived from historical volume trajectories adjusted for reimbursement policy shifts and regulatory transition timelines. Forecast inputs incorporated CLIA personnel shortage projections and NGS platform utilization ramp assumptions.
The model assumes a particular technology adoption path; alternative pathways for mass spectrometry-immunoassay convergence would alter the outlook. Forecasts reflect assumptions regarding EMA IVDR implementation pacing and United States laboratory-developed test reimbursement stability. A model refresh is warranted upon material change in FDA precision diagnostic coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
LIMS Market
Laboratory Services
Pathology Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Office Based Lab Market