
 Global Virology Specimen Collection Market | 2026-2036
Global Virology Specimen Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virology Specimen Collection Market Foresight
The EU In Vitro Diagnostic Regulation is pivoting the cost-of-entry calculus for manufacturers seeking CE-marked viral transport kits and collection tubes. Copan Italia leverages its automated flocking technology to sustain premium positioning in nasopharyngeal swabs across European reference laboratories. Thermo Fisher Scientific anchors its specimen collection portfolio through integrated cold-chain logistics that extend reach into decentralized testing networks. Becton Dickinson and Company competes on manufacturing scale, operating high-throughput injection molding lines that dominate collection tube supply to U.S. hospital systems.
Virology specimen collection encompasses the engineered devices and stabilized media used to harvest, preserve, and transport viral material from human subjects to analytical platforms, with transport media typically formulated with antimicrobial agents and protein stabilizers to maintain nucleic acid integrity across temperature excursions from 2°C to 30°C. This discipline serves the industrial purpose of enabling accurate downstream molecular diagnostics, serological assays, and genomic surveillance. Swabs and viral transport kits command the largest revenue share within product type segments, reflecting their irreplaceable role in respiratory pathogen protocols, while saliva collection is displacing nasopharyngeal methods in routine screening applications due to patient compliance advantages. Diagnostic laboratories represent the most concentrated end-user margin pool, though biotechnology companies are capturing fastest growth through contract research demand tied to vaccine development pipelines.
The U.S. FDA, the European Medicines Agency, and India's Central Drugs Standard Control Organization each enforce distinct premarket and quality system requirements that shape product design, sterilization validation, and labeling for virology collection devices. ISO 13485 certification and compliance with the EU AI Act's traceability provisions are becoming baseline conditions for market access in regulated jurisdictions. Stakeholders must monitor divergent national timetables for IVD regulatory transitions and calibrate regional manufacturing footprints accordingly.
Market Dynamics
Automated specimen handling systems are compressing turnaround times for diagnostic laboratories while the EU In Vitro Diagnostic Regulation rewrites conformity requirements for transport media and viral transport kits.
Growth Catalysts
- IVDR Conformity Pressure:The EU In Vitro Diagnostic Regulation is elevating barriers for CE-marked viral transport kits, concentrating procurement among certified manufacturers and accelerating replacement cycles for non-compliant inventory.
- Saliva Collection Displacement:Patient compliance advantages are pulling routine screening applications away from nasopharyngeal swabs toward stabilized saliva collection devices in occupational health programs.
- India Surveillance Scaling:The Central Drugs Standard Control Organization is streamlining import pathways for viral transport media as India expands its national genomic surveillance infrastructure.
Market Restraints
- Polymer Supply Concentration:High-throughput injection molding for collection tubes depends on medical-grade polypropylene supply chains concentrated in East Asian petrochemical corridors.
- Cold-Chain Cost Burden:Nucleic acid integrity requirements across 2°C to 30°C excursions impose refrigerated logistics costs that compress margins for decentralized testing networks.
- Antimicrobial Formulation Limits:Transport media protein stabilizers face compatibility constraints with emerging lyophilized preservation chemistries.
Strategic Opportunities
- Biotechnology Contract Research:Vaccine development pipelines are generating specimen collection demand from biotechnology companies that outpaces traditional diagnostic laboratory procurement velocity.
- ISO 13485 Certification Arbitrage:Quality system certification is becoming a baseline condition for market access, creating service revenue streams for compliance consultancies in emerging manufacturing jurisdictions.
- Lyophilized Media Convergence:Room-temperature-stable transport media combined with ambient logistics networks are opening distribution channels into resource-limited settings previously excluded by cold-chain requirements.
Industry Challenges
- Validation Timeline Compression:Sterilization validation protocols for viral collection devices are extending premarket submission timelines under FDA 510(k) and IVDR Article 10.
- Traceability System Integration:The EU AI Act's traceability provisions are forcing manufacturers to reconfigure labeling and serialization infrastructure for viral transport kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virology Specimen Collection Market |
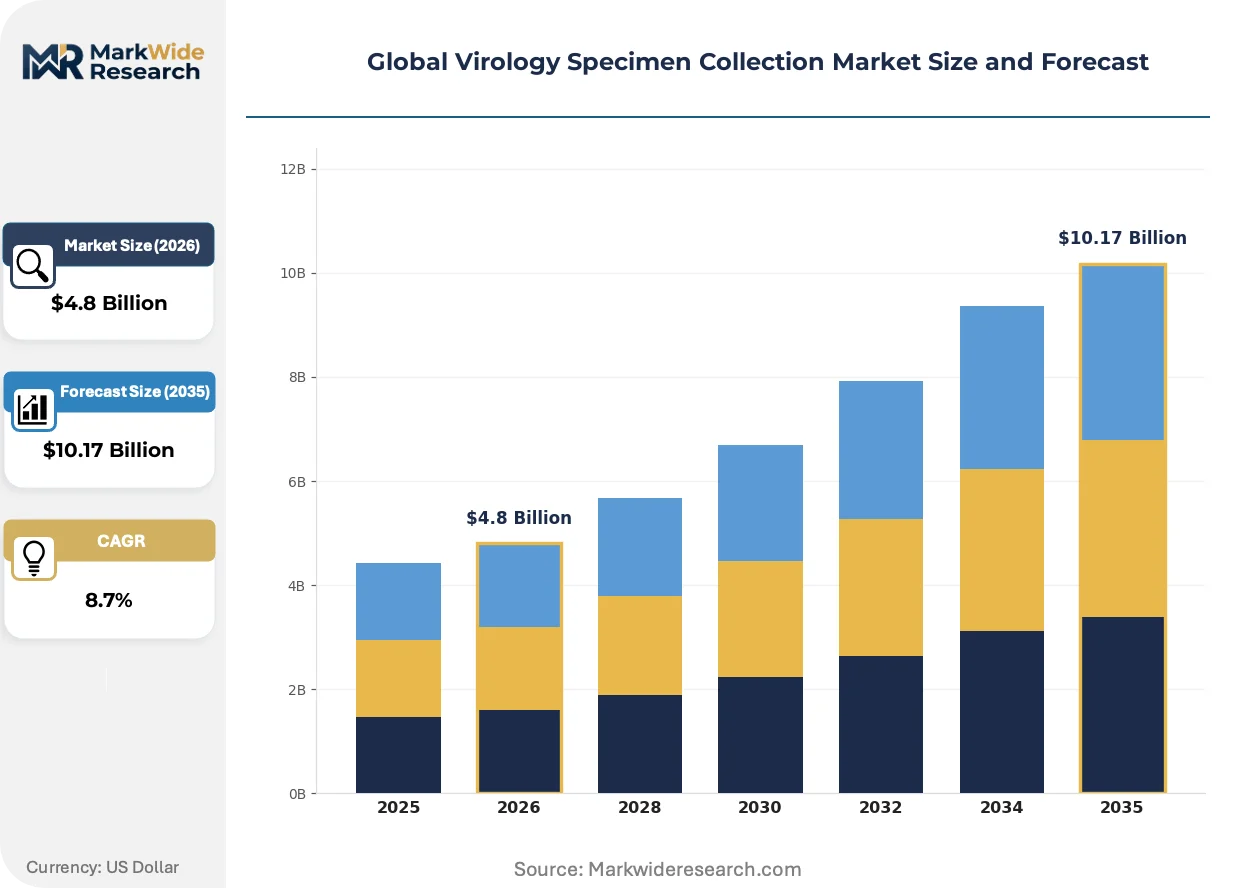
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swabs, Transport Media, Collection Tubes, Storage Reagents, Viral Transport Kits Specimen Type: Nasopharyngeal, Oropharyngeal, Blood, Saliva, Urine, Stool End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Biotechnology Companies, Academic Centers Application: Viral Load Monitoring, Disease Surveillance, Vaccine Development, Epidemiological Studies, Infection Diagnosis |
| Companies Covered | Copan Italia, Trinity Biotech, Puritan Medical Products, Vircell, DiaSorin, Becton Dickinson and Company, Thermo Fisher Scientific, Hardy Diagnostics, Quidel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virology Specimen Collection Market Shifts & Advancements
Specimen collection workflows are absorbing automation investments while regulatory frameworks fragment across jurisdictions, forcing manufacturers to maintain parallel compliance architectures.
Flocked nylon swabs are absorbing surface-area engineering advances that improve viral yield recovery rates. Reference laboratories in Germany and the United States are adopting these formats for respiratory pathogen protocols at replacement cycle velocities of eighteen to twenty-four months. The technology is absorbing premium positioning in automated specimen handling lines that reject legacy spun-polyester formats.
REACH restrictions on chemical substances are extending to preservatives used in viral transport media, compelling reformulation investments for manufacturers serving European diagnostic networks. The industrial consequence is a bifurcation between CE-marked and non-CE product lines with incompatible supply chains. Collection tube suppliers are responding by segregating manufacturing footprints and duplicating quality system documentation.
Diagnostic laboratories are consolidating procurement authority into centralized supply chain functions that negotiate multi-year framework agreements with preferred manufacturers. Group purchasing organizations are displacing spot-market purchasing for viral transport kits in United States hospital systems. This concentration is most visible in integrated delivery networks spanning multiple states, where standardization mandates override individual laboratory preferences.
Global Virology Specimen Collection Market Segmentation
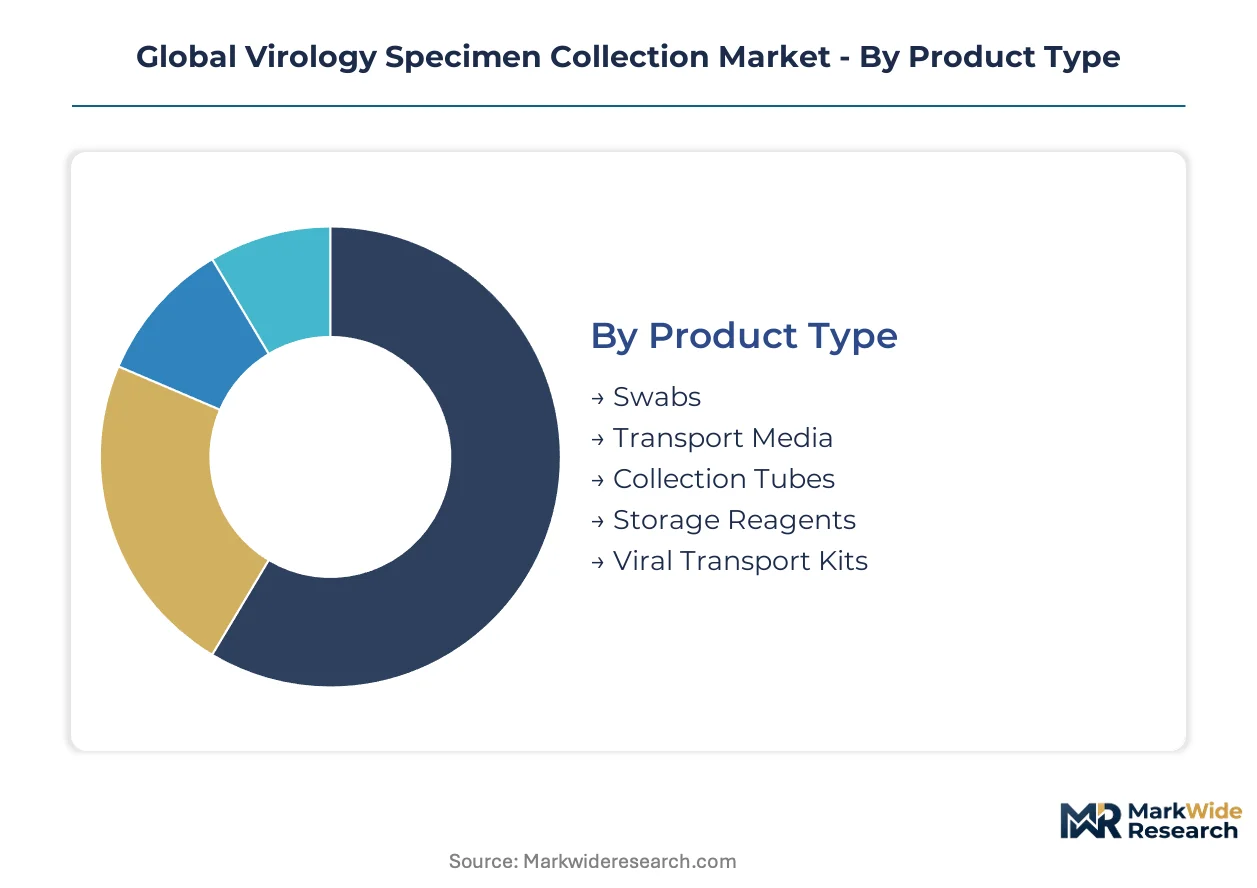
Segmentation in virology specimen collection reveals how product architecture, specimen source, and end-user workflow requirements create distinct procurement patterns. Each dimension carries implications for sterilization validation, cold-chain logistics, and regulatory submission pathways.
Product Type:
Standalone collection devices operate independently in field settings, while embedded systems integrate with automated laboratory processing lines.
- Swabs:Engineered with flocked nylon or polyester tips optimized for viral yield recovery. Diagnostic laboratories in Germany and the United States are replacing spun-polyester formats with flocked variants on eighteen-to-twenty-four-month replacement cycles.
- Transport Media:Liquid or gel formulations containing antimicrobial agents and protein stabilizers maintain nucleic acid integrity across 2°C to 30°C temperature excursions. Blood banks and decentralized testing networks in India absorb the highest procurement volumes.
- Collection Tubes:Medical-grade polypropylene containers manufactured through high-throughput injection molding.
- Storage Reagents:Lyophilized and liquid chemistries for long-term specimen preservation.
- Viral Transport Kits:Pre-configured swab-media combinations for standardized collection protocols.
Swabs lead volumes today; viral transport kits are gaining share fastest.
Specimen Type:
Sample source determines container engineering, preservative compatibility, and downstream analytical compatibility with molecular or serological platforms.
- Nasopharyngeal:Deep nasal cavity sampling via flexible shaft swabs remains the reference standard for respiratory pathogen detection. Reference laboratories retain this format for influenza and SARS-CoV-2 confirmation protocols despite patient discomfort.
- Saliva:Stabilized collection devices with buffer chemistry enable self-collection without healthcare worker supervision. Occupational health programs in the United States are displacing nasopharyngeal methods for routine screening applications.
- Oropharyngeal:Throat-based sampling using tongue depressor-assisted swab insertion.
- Blood:Serum and plasma separation tubes for serological antibody detection.
- Urine:Midstream catch containers with preservative tablets for viral shedding detection.
- Stool:Leak-resistant containers with nucleic acid stabilizers for enteric pathogen surveillance.
Nasopharyngeal specimens dominate laboratory confirmation workflows; saliva collection shows the steepest expansion trajectory in screening applications.
End User:
Procurement authority concentrates differently across customer types, with some segments negotiating multi-year framework agreements while others operate on spot purchasing.
- Diagnostic Laboratories:Centralized supply chain functions in integrated delivery networks negotiate standardized procurement across multiple states. Group purchasing organizations displace spot-market purchasing for viral transport kits in United States hospital systems.
- Biotechnology Companies:Contract research demand tied to vaccine development pipelines generates specimen collection procurement velocity exceeding traditional diagnostic laboratory growth rates.
- Research Institutes:Academic and government facilities with fragmented purchasing authority.
- Blood Banks:Collection and processing facilities requiring sterile donor screening protocols.
- Academic Centers:University-affiliated hospitals with mixed research-clinical missions.
Diagnostic laboratories capture the largest revenue concentration; biotechnology companies are climbing the fastest.
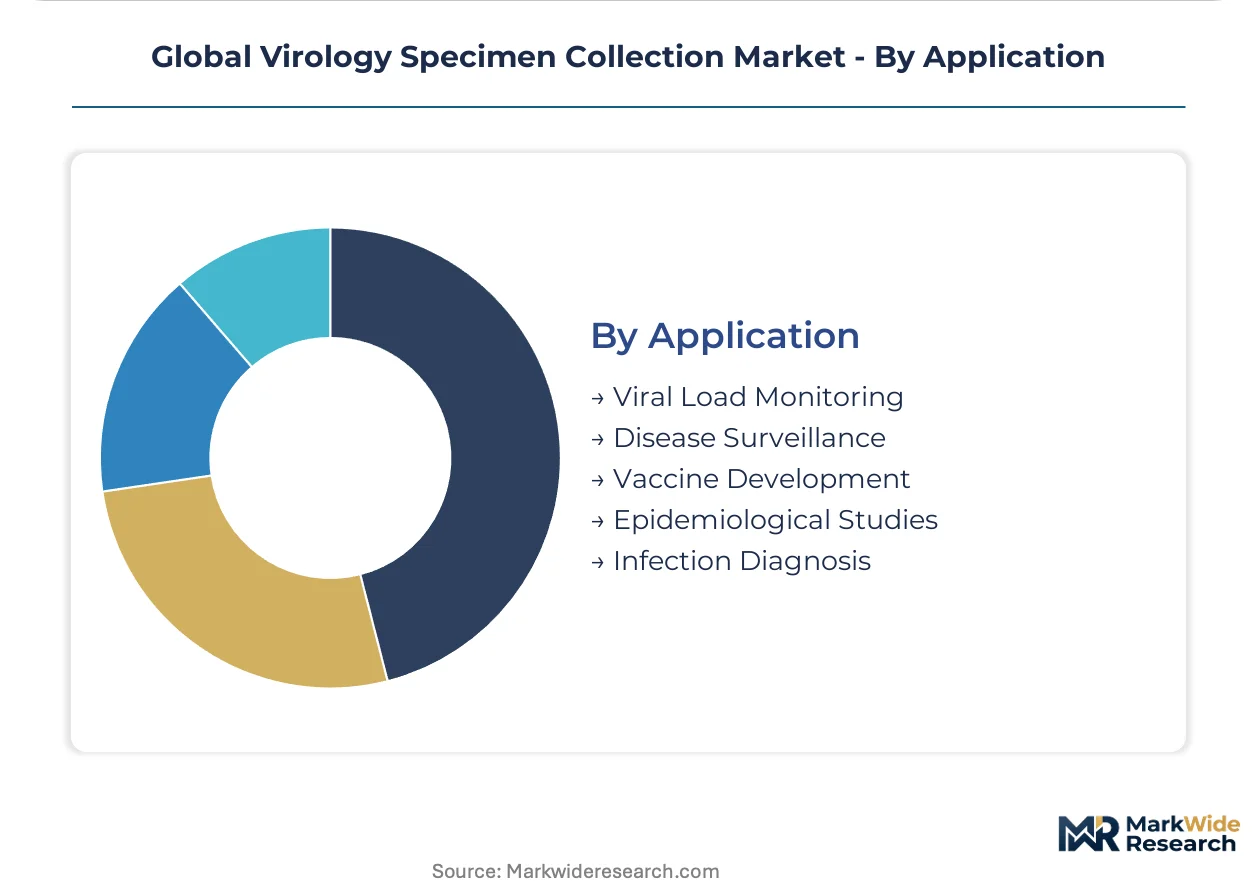
Application:
Intended use shapes regulatory classification, with some applications triggering in vitro diagnostic conformity requirements and others falling under research-use-only designations.
- Viral Load Monitoring:Quantitative nucleic acid testing for treatment response assessment in chronic infections. HIV and hepatitis C management programs in the United States and Germany drive recurring demand for standardized collection protocols.
- Vaccine Development:Immunogenicity and efficacy trials require high-volume specimen collection with chain-of-custody documentation. Biotechnology sponsors absorb premium-priced collection devices with integrated traceability features.
- Disease Surveillance:Population-level pathogen detection for public health authorities.
- Epidemiological Studies:Research cohorts tracking transmission dynamics and variant emergence.
- Infection Diagnosis:Point-of-care and laboratory confirmation of acute illness.
Viral load monitoring anchors current procurement volumes; vaccine development applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled laboratory technicians and molecular biologists concentrate in the United States, Germany, and India, anchoring specimen collection demand to these three national markets as they scale genomic surveillance infrastructure and diagnostic testing networks.
United States
Integrated delivery networks spanning multiple states consolidate procurement authority for viral transport kits through group purchasing organizations. The FDA enforces 510(k) premarket submission requirements that extend sterilization validation timelines for collection device manufacturers. High-throughput diagnostic laboratories in the Northeast Corridor and California absorb the largest procurement volumes for flocked nasopharyngeal swabs.
Germany
Reference laboratories in Bavaria and Baden-Württemberg drive replacement cycles for automated specimen handling lines every eighteen to twenty-four months. REACH restrictions on chemical preservatives compel reformulation investments for transport media serving European diagnostic networks. The EMA coordinates with national health institutes to standardize viral load monitoring protocols for HIV and hepatitis C management programs.
India
The Central Drugs Standard Control Organization streamlines import pathways for viral transport media as national genomic surveillance infrastructure expands. Diagnostic laboratories in Maharashtra and Karnataka absorb rising procurement volumes for stabilized saliva collection devices. Contract research organizations in Hyderabad and Bangalore generate specimen collection demand from vaccine development pipelines.
United Kingdom
Academic medical centers in London and the Southeast anchor demand for research-use-only collection formats in epidemiological studies. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, creating parallel conformity pathways for manufacturers. Blood banks in the Midlands operate sterile donor screening protocols that sustain collection tube procurement.
Japan
PMDA quality system requirements shape product design and labeling for virology collection devices entering the Japanese market. Diagnostic manufacturers in the Kanto region around Tokyo integrate automated specimen handling systems that reject legacy spun-polyester swab formats. Research institutes in Osaka and Nagoya participate in regional surveillance networks tracking respiratory pathogen emergence.
Global Virology Specimen Collection Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: diversified life sciences conglomerates with integrated cold-chain logistics, mid-scale diagnostic specialists with automated manufacturing lines, and regional fabricators serving spot-market procurement. Dominant competitive moves include manufacturing scale expansion through high-throughput injection molding investments and strategic partnerships with group purchasing organizations to secure multi-year framework agreements.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Becton Dickinson and Company exemplify scale-driven positioning through integrated supply chain control. Copan Italia occupies a specialist position representing premium-tier automated flocking technology for European reference laboratories. Among focused diagnostic players, Puritan Medical Products and Quidel Corporation sit within the mid-scale segment serving decentralized testing networks and occupational health screening programs.
| Leading Market Players |
|---|
| Copan Italia |
| Trinity Biotech |
| Puritan Medical Products |
| Vircell |
| DiaSorin |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Hardy Diagnostics |
| Quidel Corporation |
| Others |
Supply & Pricing Matrix
CE-marking certification tiers split procurement flows between premium automated flocking lines and commodity spun-polyester formats, with this divergence mapping directly onto divergent logistics architectures: certified manufacturers absorb cold-chain validation costs while spot-market suppliers compete on stripped-down packaging for decentralized testing networks.
Pricing Analysis
Bundled viral transport kits with pre-configured swab-media combinations command 15-25% premiums over unbundled standalone devices, with price differentiation anchored in ISO 13485 certification status and integrated cold-chain logistics capabilities. Pricing pressure intensifies in the standard tier as group purchasing organizations consolidate procurement authority across United States hospital systems. Diagnostic laboratories within integrated delivery networks exhibit lowest price sensitivity due to standardization mandates, while occupational health screening programs in decentralized settings drive hardest bargain negotiations.
Supply Chain Analysis
Medical-grade polypropylene for collection tubes rests on petrochemical corridors concentrated in China, South Korea, and Germany, with flocked nylon fiber inputs drawing from specialty textile manufacturers in Italy and Japan. Antimicrobial formulation chemistries hinge on supply from Indian and Chinese active pharmaceutical ingredient producers. Single-source vulnerability concentrates in East Asian injection molding equipment for high-throughput tube manufacturing. Distribution runs through group purchasing organization contracts dominating United States hospital procurement, with direct-to-laboratory channels serving European reference networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Virology Specimen Collection Market compounds steadily as national genomic surveillance infrastructure mandates recurring replacement cycles for collection devices across diagnostic networks.
For Market Incumbents: Deploy automated flocking capacity additions in Germany and the United States to defend against lyophilized media substitution threats. Secure multi-year framework agreements with group purchasing organizations before IVDR transition deadlines eliminate non-certified competitors. Channel control through integrated cold-chain logistics locks in reference laboratory loyalty against mid-scale challengers. For New Entrants and Emerging Players: Begin with stabilized saliva collection devices for Indian and United States occupational health programs, the most penetrable white-space segment displacing nasopharyngeal protocols. Target biotechnology contract research demand with customizable viral transport kits featuring chain-of-custody documentation. ISO 13485 certification arbitrage offers service revenue entry before manufacturing scale investments. For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization validation timelines extend premarket submission pathways beyond smaller competitor cash runways. Five-to-ten-year viability favors manufacturers with dual CE-marked and FDA-cleared product lines spanning automated and manual collection workflows. Acquisition targets with lyophilized media pipelines and ambient logistics networks signal portfolio resilience. Watch IVDR enforcement variance across notified bodies as inflection indicator for competitive shakeout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR Article 10 compliance unlocks European reference laboratory procurement worth billions in replacement cycles. |
| Hospital System Partnership | Multi-year framework agreements with United States integrated delivery networks secure volume commitments against spot-market volatility. |
| Lyophilized Media Development | Room-temperature stability eliminates refrigerated logistics costs enabling resource-limited setting penetration. |
| Automated Flocking Scale-Up | Copan Italia's technology premium extends through eighteen-to-twenty-four-month replacement velocities in German laboratories. |
| ISO 13485 Certification Service | Quality system consulting revenue streams emerge as baseline market access condition across regulated jurisdictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with diagnostic laboratory procurement directors, biotechnology contract research managers, GPO contracts specialists, and regulatory affairs leads at collection device manufacturers with secondary validation against FDA 510(k) filings, EMA IVDR guidance documents, CDSCO import pathway notifications, and hospital procurement database extracts. Bottom-up demand modeling across product type, specimen source, and end-user segments triangulated against top-down market sizing from trade flow analysis.
Comparable-period anchoring linked projection assumptions to historical replacement cycle velocities and regulatory transition timetables across the analysis window. Segmentation dimensions spanned product architecture, specimen type, end-user procurement authority, and application regulatory classification. CAGRs derived from fitted growth curves incorporating biotechnology pipeline expansion rates, surveillance infrastructure investment announcements, and diagnostic laboratory automation adoption patterns. Forecast inputs included lyophilized media technology maturation curves and IVDR notified body capacity constraints.
Several conditions sit outside the modeled scope, including pandemic emergency use authorization reinstatements, abrupt polymer commodity price shocks, and geopolitical trade corridor disruptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and replacement cycle stability. A small set of named triggers warrants ongoing watch: IVDR implementation variance, lyophilized media regulatory acceptance timelines, and group purchasing organization consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Assessment Services Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Pathology Services Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Office Based Lab Market