
 Global Coagulation-Hemostasis Analyzer Market | 2026-2036
Global Coagulation-Hemostasis Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coagulation-Hemostasis Analyzer Market Foresight
The EU In Vitro Diagnostic Regulation is recalibrating the cost-of-entry calculus for coagulation-hemostasis analyzer manufacturers seeking European market access. Siemens Healthineers leverages its broad diagnostic portfolio to sustain compliance investments across multiple regulatory jurisdictions. Werfen anchors its competitive stance through specialized hemostasis testing systems that dominate hospital laboratory workflows.
Coagulation-hemostasis analyzers are electromechanical or optical instruments that measure blood clotting parameters such as prothrombin time, activated partial thromboplastin time, and fibrinogen concentration to guide anticoagulant therapy and surgical readiness decisions. Automated analyzers occupy the largest installed base due to throughput demands in high-volume hospital laboratories, while portable devices represent the fastest-expanding segment as point-of-care protocols extend into emergency departments and ambulatory surgical centers. Chromogenic assay technology leads in precision for direct oral anticoagulant monitoring, whereas immunoassay methods are gaining ground in specialized coagulation factor deficiency screening.
The FDA, EMA, and Japan's PMDA enforce divergent clinical evidence requirements for coagulation assay validations, fragmenting product registration timelines and regional launch sequences. ISO 15189 accreditation standards for medical laboratories are reshaping analyzer procurement specifications toward integrated quality management and traceability features. Stakeholders must weigh regulatory divergence against platform standardization when allocating R&D budgets across geographic markets.
Market Dynamics
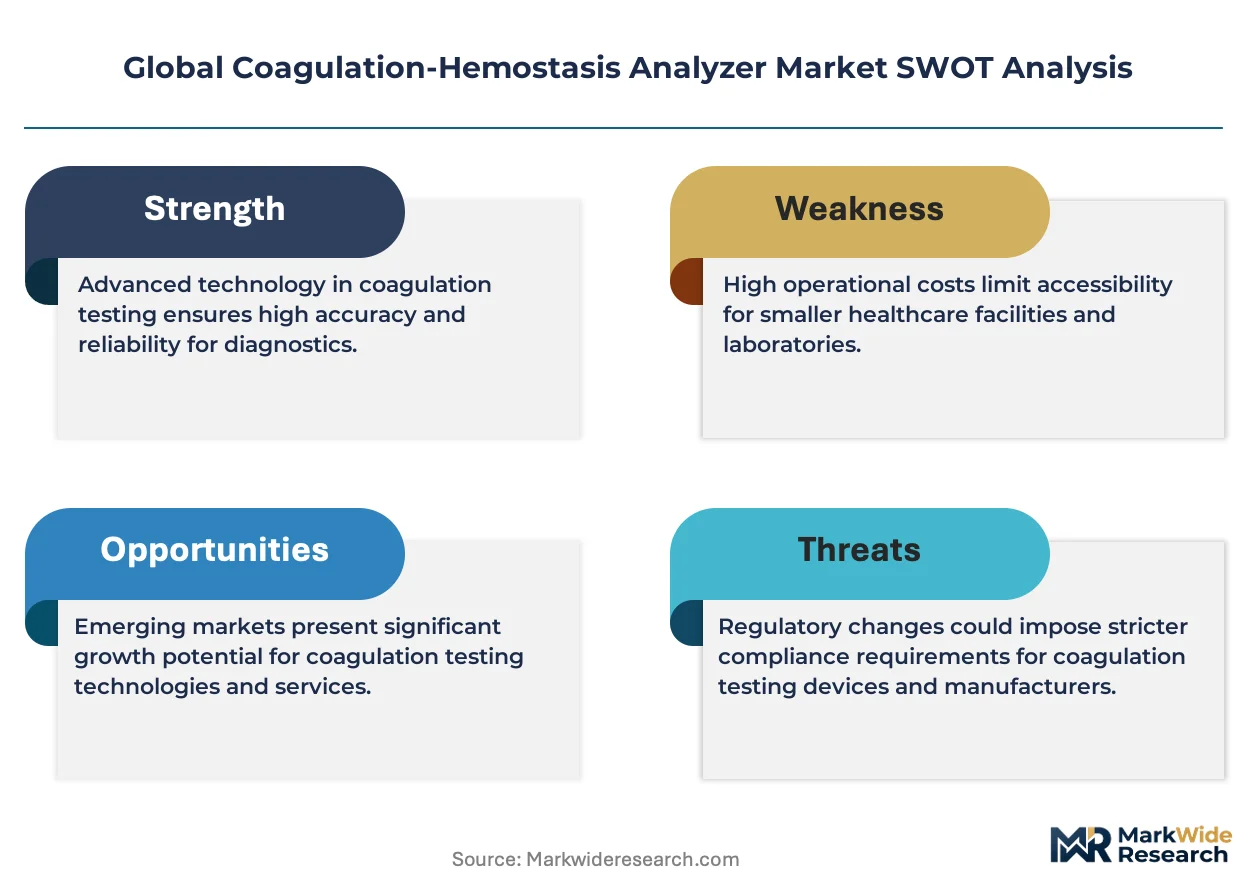
The EU In Vitro Diagnostic Regulation (IVDR) is fragmenting product registration timelines and forcing manufacturers to recalibrate compliance investments across multiple jurisdictions simultaneously. This regulatory recalibration is reshaping competitive positioning as specialized hemostasis testing systems face elevated cost-of-entry barriers.
Growth Catalysts
- Point-of-care protocol expansion:Emergency departments in the United States are deploying portable coagulation analyzers to accelerate anticoagulant therapy decisions and reduce time-to-treatment for trauma patients.
- ISO 15189 accreditation mandates:Medical laboratories across Germany and Japan are procuring analyzers with integrated quality management and traceability features to meet accreditation specifications.
- Direct oral anticoagulant monitoring demand:Chromogenic assay technology is capturing expanded clinical utility as physicians require precise monitoring of novel anticoagulant therapies.
Market Restraints
- IVDR compliance cost escalation:European market access now demands substantially higher clinical evidence investments, compressing margins for mid-tier manufacturers without diversified diagnostic portfolios.
- Optical component supply concentration:Precision photodetectors and laser modules concentrate among specialized Japanese and German component suppliers, creating input vulnerability.
- Assay standardization fragmentation:Divergent reference ranges across FDA, EMA, and PMDA validation protocols prevent unified product configurations.
Strategic Opportunities
- Ambulatory surgical center penetration:United States outpatient facilities represent underpenetrated deployment sites for compact coagulation analyzers supporting pre-operative screening workflows.
- Immunoassay-chromogenic convergence:Hybrid assay platforms combining immunoassay sensitivity with chromogenic precision are opening specialized coagulation factor deficiency screening applications.
- Japan's PMDA fast-track pathway:Accelerated approval mechanisms for innovative diagnostic devices are shortening time-to-market for next-generation analyzer platforms.
Industry Challenges
- Multi-jurisdictional regulatory expertise scarcity:Manufacturers struggle to staff teams capable of navigating simultaneous FDA, EMA, and PMDA submission requirements.
- Legacy hospital laboratory system integration:New analyzer platforms face complex interoperability demands with entrenched laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coagulation-Hemostasis Analyzer Market |
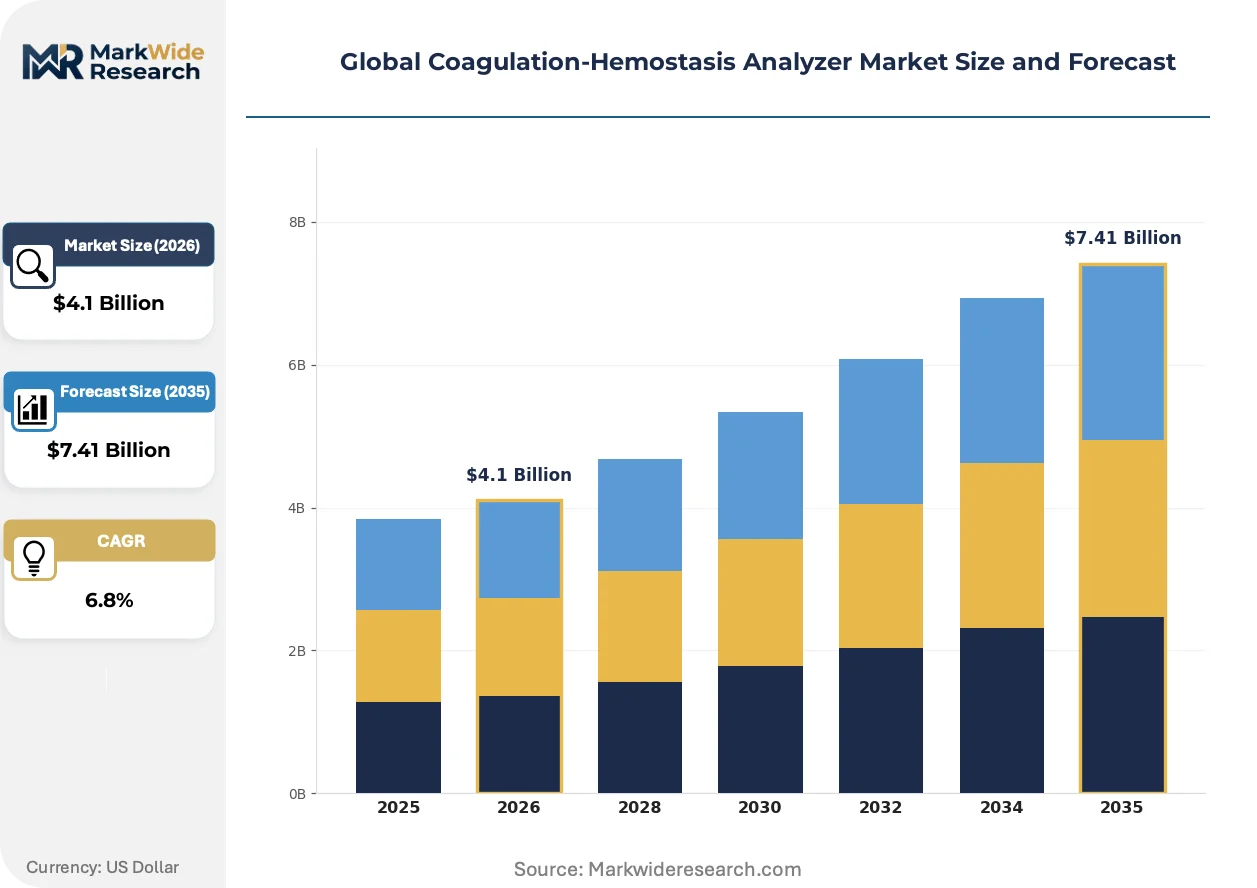
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Semi-automated Analyzers, Portable Devices, Coagulation Reagents Technology: Clotting Time Measurement, Chromogenic Assay, Immunoassay, Electromechanical Analysis Application: Diagnostic Testing, Monitoring Anticoagulant Therapy, Research Analysis, Blood Donor Screening End User: Hospitals, Diagnostic Laboratories, Blood Banks, Clinical Research Organizations |
| Companies Covered | Siemens Healthineers AG, Thermo Fisher Scientific Inc., Werfen, Helena Laboratories Corporation, Nihon Kohden Corporation, Sysmex Corporation, F. Hoffmann-La Roche Ltd, HORIBA Medical, Diagnostica Stago, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coagulation-Hemostasis Analyzer Market Shifts & Advancements
Analyzer architecture is modularizing to accommodate fragmented regulatory requirements and heterogeneous laboratory infrastructures. This structural shift is compressing development cycles while expanding configuration flexibility.
Microfluidic cartridge technology is modularizing coagulation testing workflows by integrating sample preparation, reagent delivery, and optical detection into disposable single-use units. Hospital laboratories in Germany are adopting these systems to reduce maintenance overhead and cross-contamination risk. The technology is modularizing capital deployment models, enabling smaller facilities to access high-precision testing without full-scale analyzer investments.
REACH substance restrictions are forcing reagent reformulation across European analyzer installations, particularly affecting chromogenic substrates and immunoassay conjugates. Manufacturers are accelerating substitution programs for restricted chemical classifications ahead of sunset dates. Hemostasis testing systems with reagent-agnostic architectures are capturing preference as laboratories seek regulatory resilience.
Consolidated procurement by United States health system networks is compressing vendor negotiation cycles and unbundling after-sales service contracts from hardware agreements. Integrated delivery networks are demanding outcome-based performance guarantees for analyzer uptime and assay accuracy. This behavioral shift is most visible in multi-hospital systems across Texas and Florida, where procurement teams centralize laboratory capital decisions.
Global Coagulation-Hemostasis Analyzer Market Segmentation
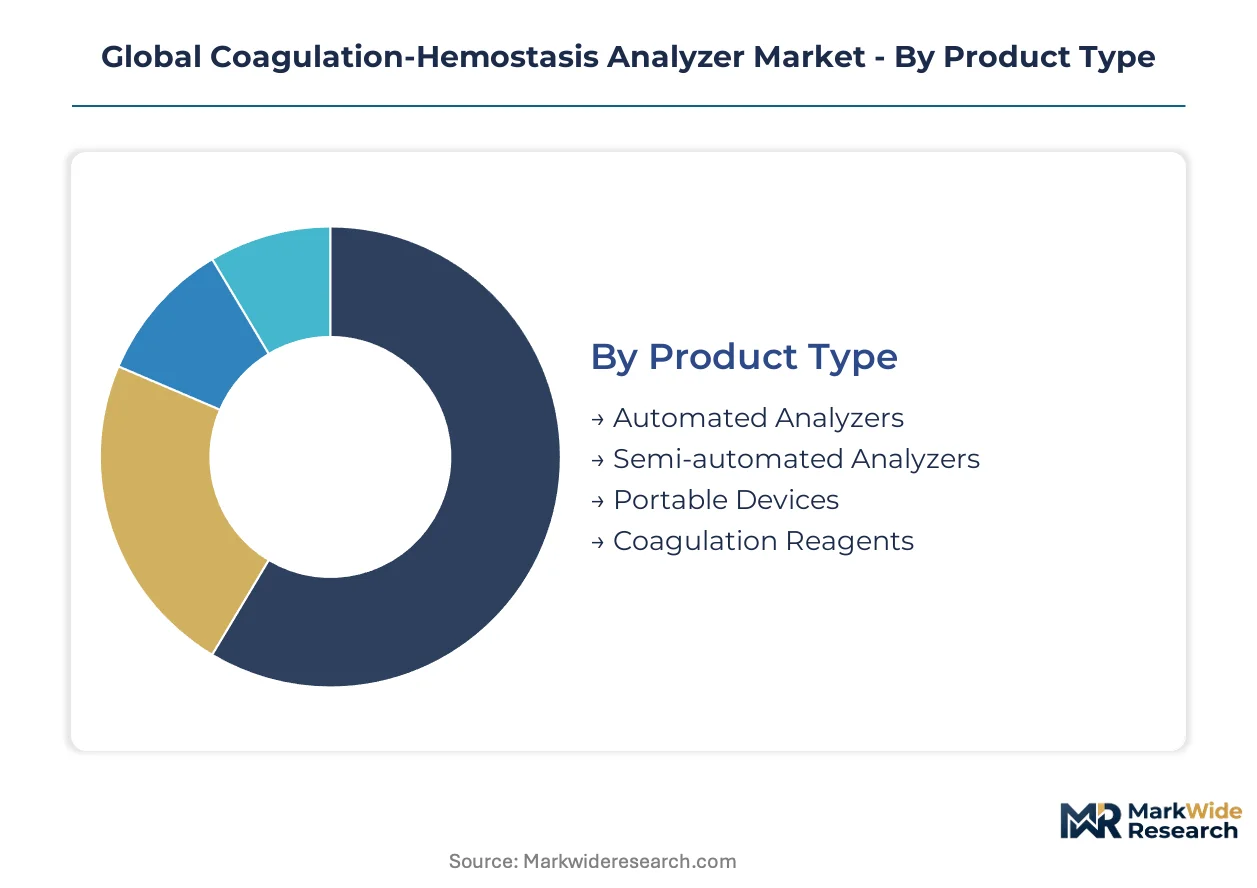
Segmentation in the coagulation-hemostasis analyzer market reveals how procurement decisions split across throughput requirements, testing precision needs, and care setting infrastructure. Understanding these divides clarifies why automated systems dominate hospital laboratories while portable formats penetrate emergency departments.
Product Type:
Procurement teams prioritize throughput capacity and maintenance overhead when selecting analyzer formats for their laboratory workflows.
- Automated Analyzers:These systems integrate sample handling, reagent delivery, and optical detection into continuous-flow architectures capable of processing hundreds of tests hourly. Demand concentrates in high-volume hospital laboratories across the United States and Germany where ISO 15189 accreditation mandates drive investments in integrated quality management features. Siemens Healthineers and Werfen anchor their competitive positions through scalable platform architectures that accommodate expanding test menus without hardware replacement.
- Portable Devices:Compact electromechanical units deploy at point-of-care sites to deliver prothrombin time and activated partial thromboplastin time results within minutes. Emergency departments in the United States and Japan are accelerating deployment to reduce time-to-treatment for trauma patients requiring rapid anticoagulant therapy decisions. Battery-operated designs with cartridge-based reagent systems minimize maintenance requirements in ambulatory settings lacking dedicated laboratory staff.
- Semi-automated Analyzers:Intermediate systems requiring manual sample introduction serve mid-sized diagnostic laboratories balancing test volume against capital constraints.
- Coagulation Reagents:Liquid-stable formulations and lyophilized preparations for prothrombin time, fibrinogen, and D-dimer assays constitute recurring revenue streams tied to installed analyzer bases.
Automated analyzers lead on scale; portable devices lead on momentum.
Technology:
Assay methodology selection hinges on the precision requirements of specific coagulation parameters and the anticoagulant therapies under monitoring.
- Clotting Time Measurement:Optical detection of fibrin clot formation remains the foundational technique for prothrombin time and activated partial thromthoplastin time determination. Hospital laboratories in Germany and Japan standardize on these methods for routine coagulation screening where regulatory validation pathways favor established optical endpoints.
- Chromogenic Assay:Synthetic substrate hydrolysis quantifies enzyme activity with precision essential for direct oral anticoagulant monitoring. Demand is climbing the fastest in specialized hemostasis laboratories across the United States and Switzerland where dabigatran and rivaroxaban therapy management requires calibrated anti-Xa and anti-IIa activity measurements. REACH substance restrictions in Europe are forcing reagent reformulation for chromogenic substrates containing restricted chemical classifications.
- Immunoassay:Antibody-based detection captures D-dimer, von Willebrand factor, and other coagulation markers with sensitivity exceeding clot-based methods.
- Electromechanical Analysis:Viscosity-based clot detection eliminates optical interference from lipemic or icteric samples, serving point-of-care environments with compromised sample quality.
Clotting time measurement leads on scale; chromogenic assay leads on momentum.
Application:
Clinical utility patterns differentiate between routine screening workflows and specialized therapeutic monitoring protocols.
- Diagnostic Testing:Pre-operative coagulation screening and bleeding disorder investigation constitute the highest-volume application segment. United States hospitals process millions of prothrombin time and activated partial thromboplastin time tests annually for surgical clearance and emergency department triage.
- Monitoring Anticoagulant Therapy:Warfarin, heparin, and direct oral anticoagulant surveillance demands precise, frequent testing to maintain therapeutic windows. Outpatient anticoagulation clinics across Germany and Japan are expanding testing frequency as aging populations require chronic therapy management.
- Research Analysis:Academic medical centers and pharmaceutical developers utilize specialized coagulation analyzers for novel anticoagulant development and hemostasis mechanism studies.
- Blood Donor Screening:Blood banks perform coagulation factor assays to qualify plasma donations for fractionation into clotting factor concentrates.
Diagnostic testing leads on scale; monitoring anticoagulant therapy leads on momentum.
End User:
Facility type determines capital investment capacity, staffing expertise, and regulatory compliance requirements.
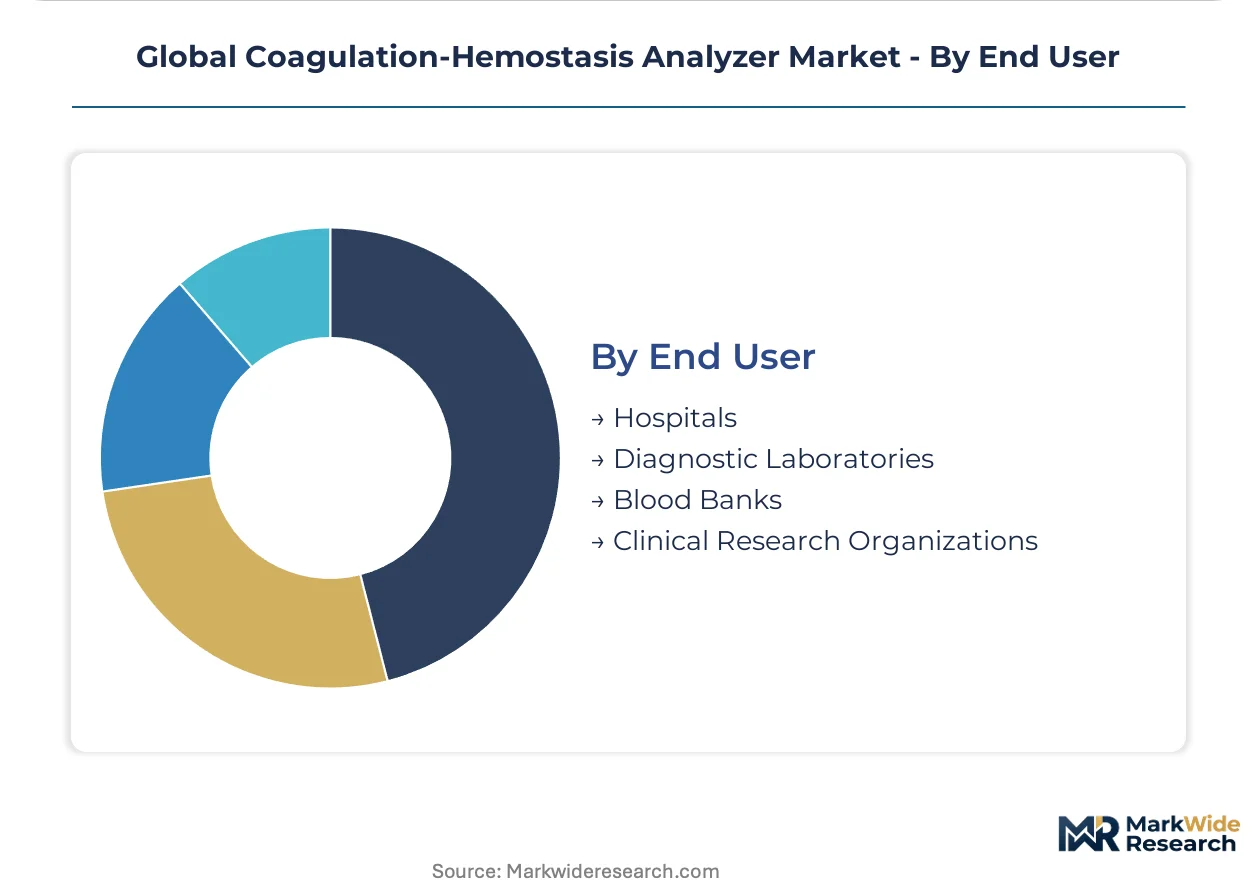
- Hospitals:Acute care institutions deploy comprehensive analyzer platforms across clinical laboratories, emergency departments, and surgical suites. Integrated delivery networks in Texas and Florida are consolidating procurement decisions for multi-hospital systems, compressing vendor negotiation cycles and demanding outcome-based performance guarantees.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated testing facilities process high-throughput coagulation panels for outpatient and inpatient populations. ISO 15189 accreditation mandates across Germany and Japan are reshaping analyzer procurement specifications toward integrated quality management and traceability features.
- Blood Banks:Collection and processing facilities require specialized coagulation testing for donor qualification and plasma product release.
- Clinical Research Organizations:Contract research facilities support pharmaceutical trials with validated coagulation assays for investigational anticoagulant development.
Hospitals lead on scale; diagnostic laboratories lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized clinical laboratory workforces in Germany, Japan, and the United States anchor analyzer procurement expertise. Health system modernization across these markets is concentrating coagulation testing infrastructure investments. Regulatory divergence between FDA, EMA, and PMDA protocols is fragmenting product launch sequences.
United States
Emergency departments in Texas and Florida are deploying portable coagulation analyzers to compress anticoagulant therapy decision timelines. FDA clinical evidence requirements for assay validations are extending product registration timelines. Integrated delivery networks in Houston and Miami are consolidating multi-hospital laboratory procurement decisions.
Germany
ISO 15189 accreditation mandates are reshaping analyzer specifications toward integrated quality management features. REACH substance restrictions are forcing chromogenic substrate reformulation across installed hemostasis testing systems. Bavarian hospital laboratories in Munich and Nuremberg are adopting microfluidic cartridge technology to reduce cross-contamination risk.
Japan
PMDA fast-track pathways for innovative diagnostic devices are shortening time-to-market for next-generation analyzer platforms. Aging populations in Tokyo and Osaka are expanding outpatient anticoagulation clinic testing frequency. Chromogenic assay demand is climbing in specialized hemostasis laboratories monitoring direct oral anticoagulant therapies.
Switzerland
Swissmedic enforcement of IVDR compliance is elevating clinical evidence investments for European market access. Precision photodetector supply relationships with German and Japanese component suppliers are creating input concentration vulnerabilities. Basel-area pharmaceutical developers are utilizing specialized coagulation analyzers for novel anticoagulant development.
Global Coagulation-Hemostasis Analyzer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across analyzer platform development. The vendor base clusters around three strategic archetypes: diversified diagnostic conglomerates with broad compliance capabilities, specialized hemostasis testing system developers, and point-of-care portable device innovators. Dominant competitive moves include strategic partnerships for regulatory navigation and portfolio diversification into hybrid assay platforms.
Within the diversified diagnostic tier, Siemens Healthineers AG exemplifies conglomerate positioning across multiple regulatory jurisdictions. Thermo Fisher Scientific Inc. occupies a scale-driven position in laboratory instrumentation. Among specialized hemostasis developers, Werfen anchors focused system architecture for hospital laboratory workflows. Sysmex Corporation represents Japanese-origin precision instrumentation expertise. These archetypes illustrate how compliance investment capacity and assay specialization define competitive positioning under fragmented regulatory requirements.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Werfen |
| Helena Laboratories Corporation |
| Nihon Kohden Corporation |
| Sysmex Corporation |
| F. Hoffmann-La Roche Ltd |
| HORIBA Medical |
| Diagnostica Stago |
| Others |
Supply & Pricing Matrix
Specialized optical engineering talent concentrated in Stuttgart and Osaka sustains premium pricing for precision photodetector modules, widening spreads between integrated system tiers and reagent-agnostic platforms as labor-cost differentials compound component sourcing premiums.
Pricing Analysis
Bundled after-sales service contracts are unbundling from hardware agreements as United States integrated delivery networks centralize procurement decisions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15189 accreditation grade and installed-base scale. Pricing pressure stems from IVDR compliance cost escalation compressing margins for mid-tier manufacturers. Diagnostic laboratories in Germany exhibit highest price sensitivity due to REACH-driven reagent reformulation burdens, while emergency departments in Texas prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume analyzer demand from integrated delivery networks, while distributor-mediated routes serve independent diagnostic laboratories. Precision photodetectors and laser modules concentrate among specialized Japanese and German component suppliers. Chromogenic substrates draw from Swiss and German chemical manufacturers, with lyophilized reagent formulations anchored in United States production facilities. Single-source vulnerability in optical component supply creates input concentration risk. Distribution runs through regional equipment distributors with service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in coagulation-hemostasis analyzers rests on chromogenic assay premiumization and microfluidic cartridge technology reducing field-service dependency.
For Market Incumbents: Anchor compliance investment capacity across FDA, EMA, and PMDA jurisdictions simultaneously to outspend mid-tier competitors on IVDR clinical evidence requirements. Deepen backward integration into precision optical component supply through captive relationships with Stuttgart-area engineering firms. Defend installed-base stickiness by expanding hybrid immunoassay-chromogenic test menus without hardware replacement. For New Entrants and Emerging Players: Japan's PMDA fast-track pathway for innovative diagnostic devices opens a window for portable analyzer platforms targeting outpatient anticoagulation clinics in Tokyo and Osaka. Ambulatory surgical centers across Florida and Texas represent underpenetrated deployment sites lacking dedicated laboratory staff. Pursue cartridge-based reagent systems minimizing maintenance overhead as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized hemostasis testing system developers without diversified diagnostic portfolios to absorb compliance cost shocks. Long-term viability over a five-to-ten year window favors platforms with reagent-agnostic architectures resilient to REACH substance restrictions. Watch chromogenic assay demand inflection in Swiss and United States specialized laboratories monitoring direct oral anticoagulant therapies as the priority signal.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Investment | EMA clinical evidence requirements elevate cost-of-entry barriers for European market access. |
| Microfluidic Cartridge Development | Bavarian hospital laboratories adopt disposable single-use units to reduce cross-contamination risk. |
| Hybrid Assay Platform Launch | Immunoassay-chromogenic convergence opens specialized coagulation factor deficiency screening applications. |
| Point-of-Care Expansion | Emergency departments in Texas deploy portable analyzers to compress anticoagulant therapy decision timelines. |
| Reagent-Agnostic Architecture | REACH substance restrictions force reformulation of chromogenic substrates across European installations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at diagnostic manufacturers with secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, PMDA approval databases, and hospital procurement records. Bottom-up installed-base estimates and top-down market sizing triangulated across multiple data streams.
Comparable-period anchoring linked projection assumptions to historical reference points across the modeling period without year-specific calibration. Segmentation dimensions modeled include product type, assay technology, application workflow, end-user facility category, and regional regulatory cluster. CAGRs derived from volume-weighted growth trajectories incorporating direct oral anticoagulant therapy expansion rates and point-of-care protocol penetration curves.
Revisions become necessary when IVDR implementation timelines accelerate, REACH substance restriction lists expand, or PMDA fast-track pathway eligibility criteria shift. Forecasts reflect assumptions about regulatory stability and component supply continuity that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Pessary Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Microcatheter Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Infant Oxygen Hoods Market