
 Enterprise Laboratory Informatics Market | 2026-2036
Enterprise Laboratory Informatics Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Laboratory Informatics Market Foresight
The capability gap between cloud-native architectures and legacy client-server stacks is rotating competitive advantage toward vendors with modern platform investments. LabWare leverages its deep on-premises install base across pharmaceutical quality control labs while sustaining channel relationships that lock in multi-year service contracts. Thermo Fisher Scientific anchors its position through backward integration into instrument connectivity, competing on seamless data flow from analytical hardware to informatics platforms.
Enterprise laboratory informatics encompasses software systems that capture, manage, archive, and analyze laboratory data through centralized databases with audit trail functionality, electronic signatures, and role-based access controls, serving primarily to ensure data integrity across regulated research and manufacturing workflows. Laboratory Information Management Systems occupy the largest revenue pool given their ubiquity in quality control and regulatory compliance workflows, while Electronic Lab Notebooks capture the fastest expansion as biotech firms replace paper-based documentation to meet FDA and EMA data integrity expectations. Cloud-Based Solutions are displacing on-premises deployments in mid-market accounts where IT staffing constraints limit self-managed infrastructure maintenance.
FDA 21 CFR Part 11, EU Annex 11, and ISO/IEC 17025 collectively shape product requirements by mandating electronic records, audit trails, and data integrity controls that vendors must embed to serve regulated industries. The FDA's ALCOA+ guidance and EMA's GMP data integrity definitions raise compliance barriers for smaller software providers lacking dedicated regulatory affairs functions. Stakeholders must monitor evolving AI/ML validation frameworks from regulators, as predictive analytics modules become standard in drug discovery and clinical research applications.
Market Dynamics
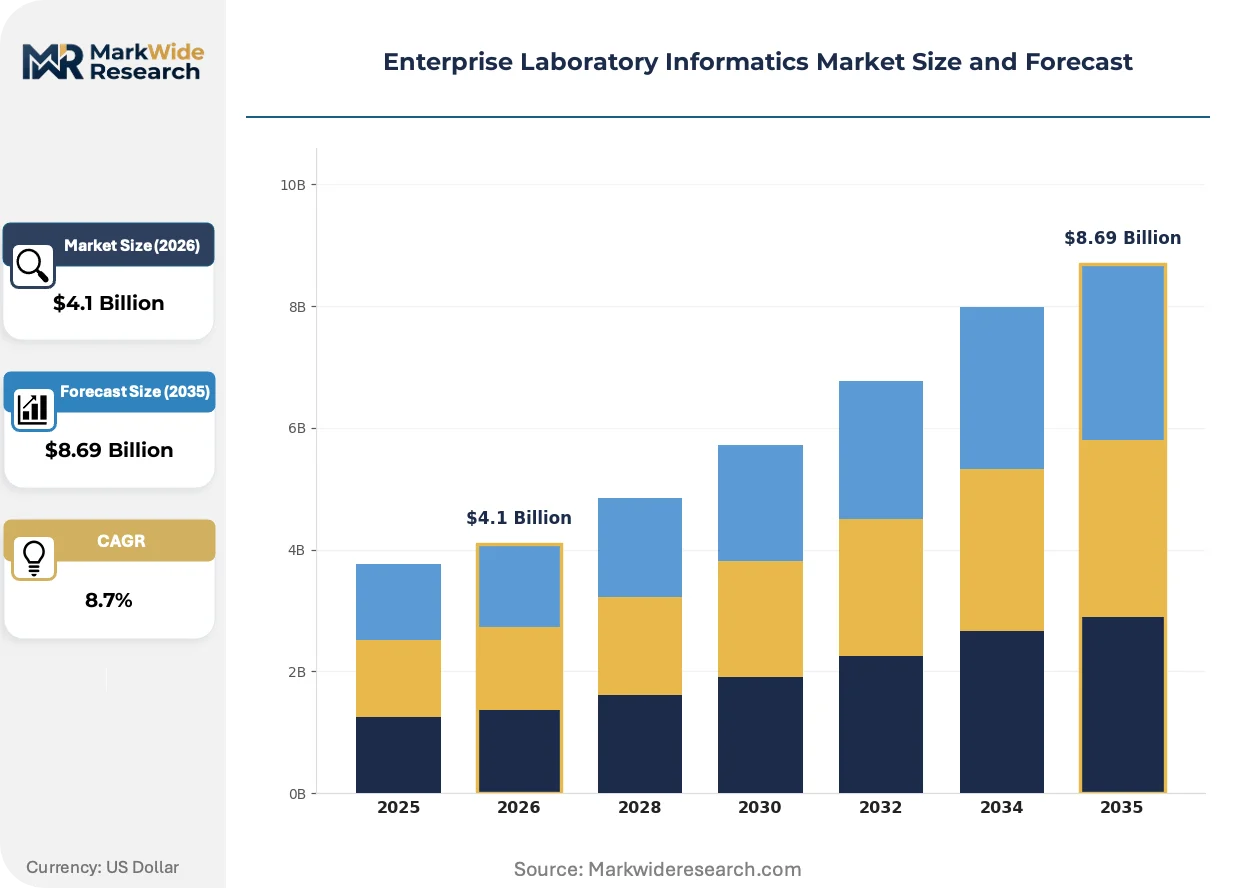
Cloud migration is compressing replacement cycles for legacy on-premises laboratory informatics systems as pharmaceutical quality control labs face escalating FDA 21 CFR Part 11 audit scrutiny and IT staffing constraints.
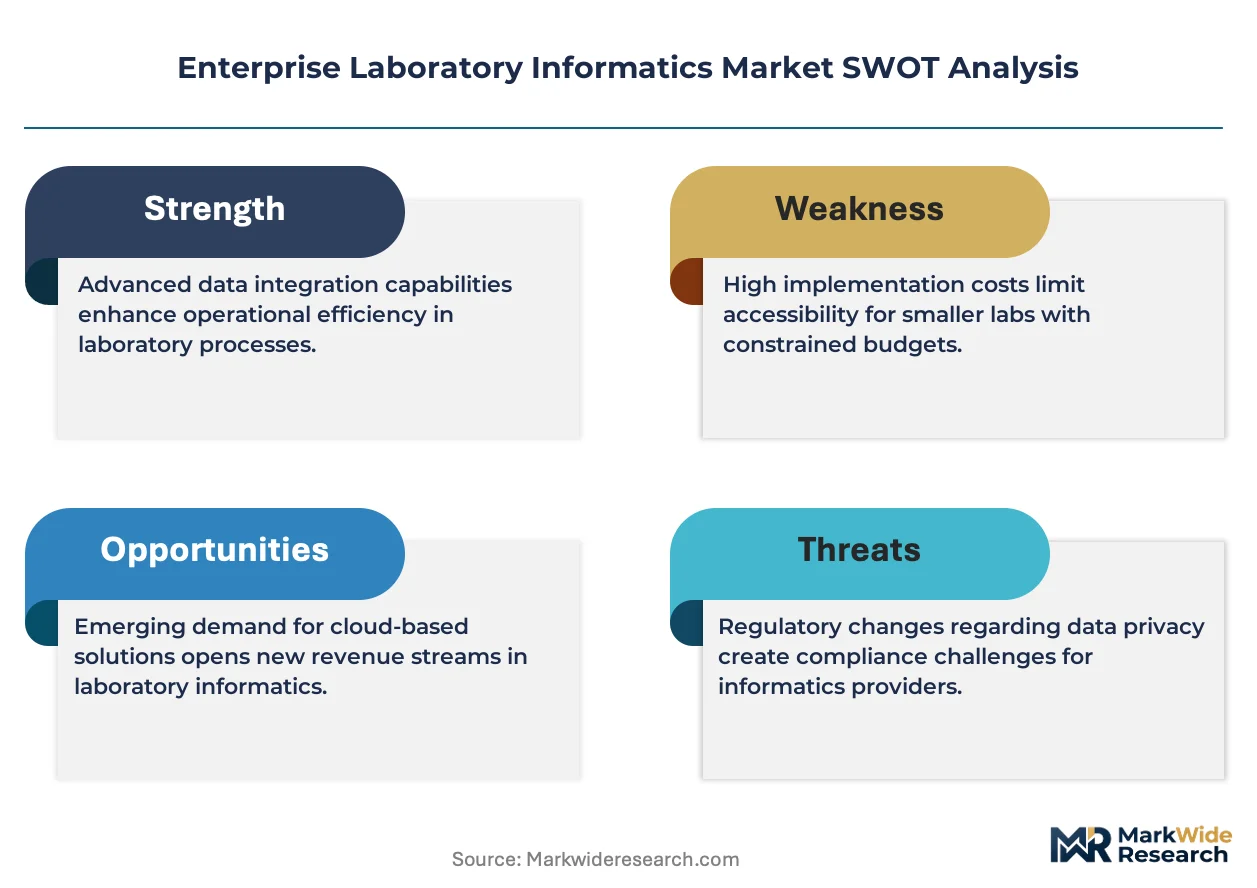
Growth Catalysts
- FDA 21 CFR Part 11 Enforcement:Pharmaceutical manufacturers are accelerating electronic records adoption to satisfy intensified audit trail requirements in quality control workflows.
- Bioinformatics Convergence:AI/ML modules are embedding into drug discovery pipelines, creating pull for platforms with native predictive analytics capabilities.
- Boston-San Francisco Cluster Density:Biopharma R&D concentration in these metros sustains premium deployment demand for integrated laboratory suites.
Market Restraints
- Validation Cost Burden:Computer system validation for regulated deployments consumes 18-24 month timelines and specialized QA resources.
- Data Migration Complexity:Legacy LIMS archives in proprietary formats create vendor lock-in and switching friction for established pharmaceutical accounts.
- Hybrid IT Skill Scarcity:Shortage of personnel fluent in both GxP compliance and cloud infrastructure administration constrains mid-market adoption velocity.
Strategic Opportunities
- Contract Research Organization Expansion:CROs serving decentralized clinical trials require multi-tenant cloud architectures with tenant-isolated audit trails.
- Cell and Gene Therapy Manufacturing:Advanced therapy production workflows need informatics platforms with chain-of-identity tracking and environmental monitoring integration.
- EU MDR Data Integrity Mandates:European medical device manufacturers face upgraded documentation requirements that favor electronic lab notebook deployment.
Industry Challenges
- Interoperability Standardization Gaps:Instrument data formats lack universal protocols, forcing costly custom integration development for multi-vendor lab environments.
- AI/ML Validation Framework Uncertainty:Absence of finalized regulatory guidance on algorithmic decision-making in GxP contexts delays predictive module deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Laboratory Informatics Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Information Management Systems, Electronic Lab Notebooks, Scientific Data Management Systems, Laboratory Execution Systems End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Laboratories Deployment: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Managed Services Application: Quality Control, Drug Discovery, Clinical Research, Regulatory Compliance |
| Companies Covered | LabWare, PerkinElmer, Thermo Fisher Scientific, IDBS, Waters Corporation, Abbott, LabVantage Solutions, LabLynx, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Laboratory Informatics Market Shifts & Advancements
Platform architecture decisions are determining competitive survival as laboratory informatics vendors race to deliver cloud-native compliance capabilities before legacy technical debt erodes customer retention.
API-first cloud-native architectures are displacing monolithic client-server stacks in mid-market pharmaceutical accounts. Quality control labs with limited IT infrastructure are adopting SaaS LIMS deployments to outsource validation maintenance and security patching. This shift is compressing vendor margins while expanding addressable market reach into emerging biotech segments previously priced out of enterprise systems.
EMA's GMP Annex 11 revisions and FDA ALCOA+ guidance are tightening data integrity definitions across European and American regulated facilities. Pharmaceutical manufacturers must now demonstrate complete data lifecycle traceability from instrument acquisition through archival destruction. Electronic lab notebook vendors are responding with blockchain-anchored audit trails and automated data reconciliation modules.
Subscription-based platform licensing is replacing perpetual software purchases in clinical research organizations. CROs managing multi-site trials prefer operational expenditure models that align informatics costs with project duration rather than capitalizing multi-year deployments. This preference is most pronounced in Massachusetts and California biotech corridors where venture-funded firms prioritize cash flow flexibility over asset ownership.
Enterprise Laboratory Informatics Market Segmentation
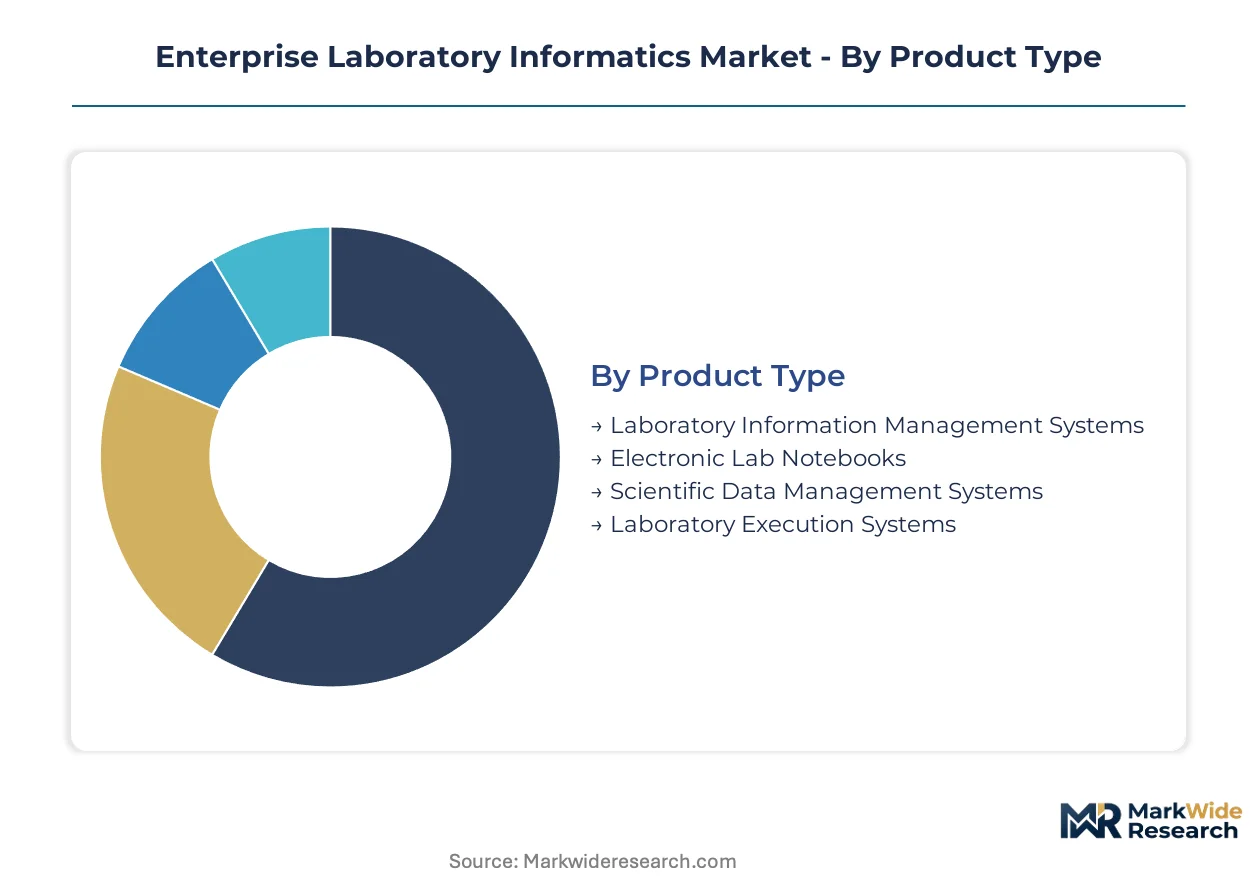
Segmentation in enterprise laboratory informatics reveals how compliance requirements, IT infrastructure maturity, and R&D investment intensity reshape purchasing patterns across buyer categories. Each dimension exposes different margin structures and vendor competitive priorities.
Product Type:
Channel mix varies sharply by product complexity, with LIMS and SDMS flowing through systems integrators while ELNs deploy direct-to-site via SaaS platforms.
- Laboratory Information Management Systems:Core platform managing sample tracking, workflow orchestration, and regulatory reporting through centralized databases with audit trail architecture. Pharmaceutical quality control labs in the United States and Germany sustain premium perpetual licensing demand due to FDA and EMA validation requirements.
- Electronic Lab Notebooks:Digital documentation environment replacing paper notebooks with structured data capture, electronic signatures, and searchable experiment archives. Biotechnology firms in Massachusetts and California are replacing paper documentation fastest to satisfy ALCOA+ data integrity expectations.
- Scientific Data Management Systems:Repository infrastructure for analytical instrument output with metadata indexing and long-term archival compliance.
- Laboratory Execution Systems:Shop-floor control layer directing manual and automated bench operations with step-by-step procedural enforcement.
LIMS dominates installed base. ELN is where expansion concentrates.
End User:
Customer type determines procurement sophistication, with pharmaceutical manufacturers demanding validated enterprise deployments while academic buyers prioritize cost and flexibility.
- Pharmaceutical Companies:Large-scale manufacturers with dedicated IT validation teams and multi-year capital planning cycles for GxP-compliant infrastructure. FDA 21 CFR Part 11 enforcement and EU Annex 11 revisions in the United States and Germany are accelerating replacement of legacy client-server installations.
- Biotechnology Firms:Venture-funded development-stage companies with limited IT staff and preference for subscription pricing aligned to funding milestones. San Francisco and Boston clusters are driving cloud-native platform adoption to avoid capital expenditure.
- Academic Institutions:Research universities with decentralized purchasing and emphasis on open-source compatibility and grant-funded equipment.
- Research Laboratories:Government and private non-profit facilities with standardized procurement processes and multi-vendor instrument environments.
Pharmaceutical companies anchor vendor revenue stability. Biotechnology firms represent the steepest expansion trajectory.
Deployment:
Delivery model selection tracks IT staffing availability and regulatory risk tolerance, with cloud options gaining share where internal infrastructure expertise is scarce.
- Cloud-Based Solutions:Vendor-hosted multi-tenant or single-tenant deployments with outsourced security patching, backup, and validation maintenance. Mid-market pharmaceutical accounts in the United States are adopting SaaS LIMS to circumvent IT hiring constraints.
- On-Premises Solutions:Customer-managed infrastructure with full control over physical data location and custom integration architecture. German and Swiss pharmaceutical manufacturers maintain on-premises preference for intellectual property protection and audit trail sovereignty.
- Hybrid Solutions:Split architecture with sensitive data on-premises and collaborative functions in cloud environments.
- Managed Services:Outsourced platform administration with vendor or third-party handling validation, upgrades, and user support.
On-premises solutions dominate installed base. Cloud-based solutions are climbing the fastest.
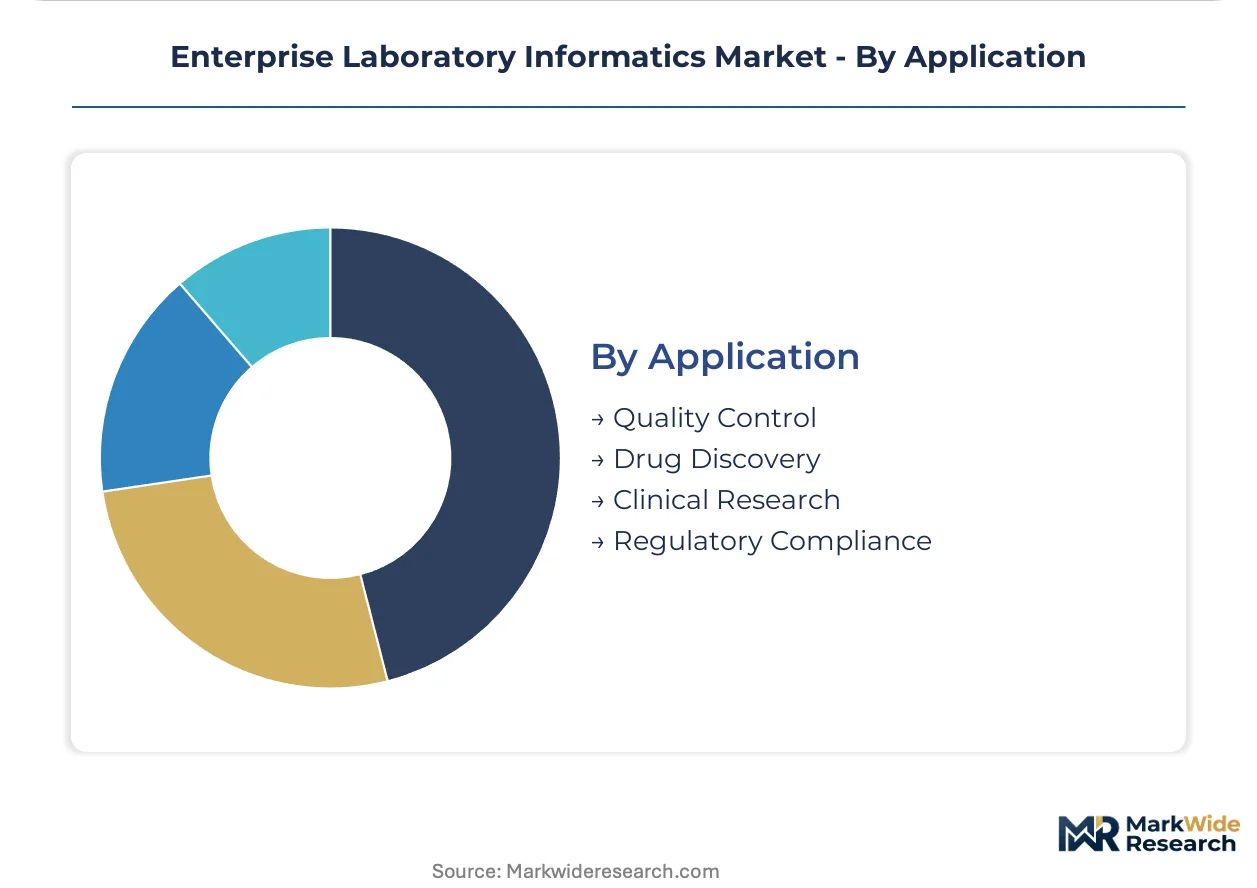
Application:
Use case focus shapes feature prioritization, with quality control demanding rigorous audit capabilities while discovery workflows emphasize analytical flexibility.
- Quality Control:Production testing workflows requiring complete batch traceability, specification enforcement, and release documentation for regulatory submission. FDA inspection intensity in the United States is forcing replacement of paper-based QC records with validated electronic systems.
- Drug Discovery:Early-stage research with high experiment volume, diverse analytical methods, and emphasis on collaboration and intellectual property capture. AI/ML module integration is pulling demand in Boston and Basel discovery operations.
- Clinical Research:Multi-site trial management with patient data privacy requirements and regulatory submission package assembly.
- Regulatory Compliance:Dedicated documentation and submission preparation with structured authoring and health authority correspondence tracking.
Quality control anchors vendor revenue. Drug discovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German pharmaceutical manufacturers absorb premium perpetual licensing for validation sovereignty, while Indian contract research organizations prioritize subscription elasticity. United States buyers split between Boston-San Francisco premium clusters and cost-constrained Midwest manufacturing sites.
United States
FDA 21 CFR Part 11 enforcement intensifies audit trail mandates for pharmaceutical quality control labs. Biopharma R&D clusters in Greater Boston and San Francisco sustain premium deployments of integrated laboratory suites. Cloud-native platform adoption accelerates among venture-funded biotechnology firms seeking operational expenditure flexibility.
Germany
EMA GMP Annex 11 revisions tighten data integrity definitions for regulated manufacturing facilities. Baden-Württemberg and Bavaria pharmaceutical manufacturers maintain on-premises preference for intellectual property protection and physical data location control. Computer system validation requirements consume specialized QA resources across Rhine-Main industrial corridors.
Switzerland
Swissmedic oversight elevates compliance barriers for electronic records systems serving pharmaceutical manufacturing. Basel discovery operations pull demand for AI/ML-embedded platforms in early-stage drug research. Swiss manufacturers balance cloud migration pressure against stringent audit trail sovereignty requirements.
United Kingdom
MHRA alignment with EMA data integrity standards post-Brexit maintains regulatory stringency for pharmaceutical exporters. Cambridge and Oxford biotech corridors drive electronic lab notebook replacement of paper documentation. Subscription licensing models gain traction among venture-funded firms prioritizing cash flow flexibility.
India
CDSCO data integrity expectations rise for domestic pharmaceutical manufacturers serving export markets. Hyderabad and Bengaluru contract research organizations adopt multi-tenant cloud architectures for decentralized clinical trial support. IT staffing constraints accelerate SaaS LIMS preference over self-managed infrastructure.
Enterprise Laboratory Informatics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in enterprise laboratory informatics. Instrument-anchored conglomerates compete against pure-play software vendors through contrasting integration strategies. Three archetypes dominate: analytical hardware suppliers extending into data platforms, dedicated informatics specialists with deep validation expertise, and cloud-native entrants compressing deployment timelines. Consolidation pressure intensifies through strategic partnerships and technology licensing arrangements rather than outright acquisition.
Within the instrument-anchored tier, Thermo Fisher Scientific and Agilent Technologies exemplify backward integration strategies that bind hardware sales to informatics platform adoption. LabWare occupies a distinct position among validation-heavy specialists serving pharmaceutical quality control labs with entrenched on-premises install bases. These three anchors illustrate how competitive advantage rotates between seamless instrument connectivity and regulatory compliance depth.
| Leading Market Players |
|---|
| LabWare |
| PerkinElmer |
| Thermo Fisher Scientific |
| IDBS |
| Waters Corporation |
| Abbott |
| LabVantage Solutions |
| LabLynx |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation requirements simultaneously gate supplier qualification and stratify pricing tiers by compliance depth. Pharmaceutical manufacturers absorb premium perpetual licensing for validated on-premises deployments while mid-market biotech firms trade sovereignty for SaaS elasticity.
Pricing Analysis
Multi-year service and validation maintenance contracts generate lifetime value exceeding initial license fees by substantial margins. Pricing stratifies across perpetual enterprise licensing, subscription SaaS tiers, and managed service bundles. Cost compression in cloud-native tiers intensifies as vendors compete for venture-funded biotech accounts in Boston and San Francisco. Academic institutions exhibit highest price sensitivity; large pharmaceutical manufacturers with dedicated QA resources show lowest.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes elevate inbound logistics costs for hardware-anchored platform vendors sourcing analytical instruments. Software development concentrates in the United States, Ireland, and India. Cloud infrastructure draws from hyperscaler data center networks. Single-source vulnerability in specialized compliance consulting creates bottleneck risk. Distribution runs through direct enterprise sales teams, systems integrators, and instrument vendor channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated pharmaceutical conglomerates with centralized procurement functions, fragmenting among decentralized biotech ventures. This asymmetry reshapes vendor negotiation leverage across contract structures.
For Market Incumbents: Shield installed base retention by embedding deeper into instrument connectivity architectures and locking in multi-year validation service contracts. Cloud-native entrants threaten legacy client-server accounts with compressed deployment timelines. Prioritize certification investment in EU MDR and FDA ALCOA+ alignment to sustain premium pricing. For New Entrants and Emerging Players: Differentiate on AI/ML module integration for drug discovery workflows where regulatory guidance remains unsettled. White-space targets include cell and gene therapy manufacturing informatics and multi-tenant CRO architectures. Pursue land-and-expand tactics through freemium ELN adoption in academic spinouts. For Investors and Strategic Acquirers: Carve-out targets emerge from analytical instrument conglomerates seeking to monetize non-core software divisions. Long-term viability hinges on cloud-native platform transitions completed within the current technology refresh cycle. Watch FDA draft guidance on AI/ML validation as inflection signal for predictive analytics module deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses deployment timelines for mid-market pharmaceutical accounts facing IT staffing gaps. |
| AI/ML Module Integration | Captures drug discovery demand in Boston and Basel where predictive analytics pulls platform selection. |
| Validation Service Expansion | Locks in recurring revenue from FDA 21 CFR Part 11 compliance maintenance contracts. |
| Instrument Connectivity Deepening | Binds hardware sales to informatics platform adoption through seamless data flow architecture. |
| Multi-Tenant CRO Architecture | Supports decentralized clinical trial growth with tenant-isolated audit trail infrastructure. |
Research Methodology
A standing panel of laboratory informatics directors, regulatory affairs leads, pharmaceutical IT procurement officers, and CRO operations managers provided ongoing calibration across the study. Primary interviews combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 11 revisions, ISO/IEC 17025 standards, and vendor SEC filings. Bottom-up deployment tracking and top-down market sizing underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user category, deployment architecture, and application workflow. CAGRs derived from year-over-year growth rate analysis applied to base-year sizing. Forecast inputs incorporated cloud migration velocity, regulatory enforcement intensity, and biotech funding cycle patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement posture and current cloud infrastructure cost curves would require recalibration. Forecasts reflect assumptions regarding validation timeline stability and AI/ML regulatory clarity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
LIMS Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Pathology Services Market
Laboratory Services
Pathology Laboratories Market