
 Microtome Knife Sharpeners Market | 2026-2036
Microtome Knife Sharpeners Market Size, Share, and Industry Trends Forecast 2026-2036
Microtome Knife Sharpeners Market Analytics
ISO 13485 certification for medical device quality management is collapsing the vendor landscape for microtome knife sharpeners, favoring suppliers with validated manufacturing processes. Leica Biosystems leverages its vertically integrated histology workflow portfolio to sustain recurring sharpener demand across installed instrument bases. Thermo Fisher Scientific anchors its position through broad distribution reach in North American research laboratories. Feather Safety Razor differentiates via specialized blade expertise transferred from its industrial cutting heritage.
Microtome knife sharpeners restore the cutting edge of precision sectioning blades used in histology, pathology, and materials science sample preparation, typically achieving edge angles between 30 and 45 degrees depending on specimen type. Electric sharpeners command the highest unit margins among product types due to programmable angle consistency and reduced technician variability. Research laboratories represent the most concentrated end-user segment, though healthcare facilities exhibit faster expansion tied to centralized histology service expansion. Diamond abrasives in sharpening matrices extend blade longevity for tungsten carbide and ceramic knife inventories.
FDA quality system regulation for medical devices and ISO 13485 standards govern sharpener manufacturing in the United States, while the EU Medical Device Regulation imposes conformity assessment burdens on European suppliers. Japan's PMDA and METI coordinate pre-market technical requirements that favor domestic manufacturers with established quality documentation. Stakeholders must monitor evolving MDR transition timelines and automated sharpening validation protocols as procurement criteria shift from capital expenditure to total cost of ownership metrics.
Market Dynamics
ISO 13485 certification requirements are consolidating the vendor base for microtome knife sharpeners, eliminating smaller suppliers lacking validated quality management systems while rewarding manufacturers with documented process controls. This regulatory filter is reshaping procurement patterns across histopathology laboratories and research institutions.
Growth Catalysts
- EU MDR Conformity Pressure:The European Union Medical Device Regulation mandates documented sharpening validation protocols, compelling laboratories to upgrade from manual to automated systems with traceable quality records.
- Histopathology Diagnostic Volumes:Academic medical centers in Germany, Japan, and the United States are expanding centralized histology services, creating recurring demand for precision blade maintenance infrastructure.
- Diamond Abrasive Matrices:Advanced synthetic diamond sharpening surfaces extend tungsten carbide and ceramic knife lifespans, reducing total cost of ownership for high-throughput facilities.
Market Restraints
- Raw Material Concentration:High-purity synthetic diamond supply concentrates in limited manufacturing clusters, exposing sharpener producers to input cost volatility and single-source dependency risks.
- Technical Limitation:Conventional sharpening systems cannot restore sub-micron edge geometry on advanced ceramic blades, forcing premature replacement of premium knife inventories.
- Regulatory Friction:Japan's PMDA pre-market technical documentation requirements favor domestic manufacturers with established quality histories, creating asymmetric market access for foreign entrants.
Strategic Opportunities
- Underpenetrated Research Segments:Materials science laboratories in South Korea and Australia remain underserved by precision sharpening services, presenting expansion targets for automated system providers.
- Technology Convergence:Integration of machine vision edge-inspection with automated sharpening cycles enables real-time quality feedback, differentiating next-generation equipment from conventional systems.
- Service Unbundling:Independent blade refurbishment services are emerging as an alternative channel, bypassing capital-intensive equipment purchases for mid-volume users.
Industry Challenges
- Certification Timeline Compression:ISO 13485 audit cycles and FDA quality system inspections extend product launch schedules by 12-18 months, straining R&D-to-revenue conversion for new entrants.
- Integration Complexity:Automated sharpeners must interface with existing laboratory information management systems, requiring customized middleware development for each major histology workflow platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microtome Knife Sharpeners Market |
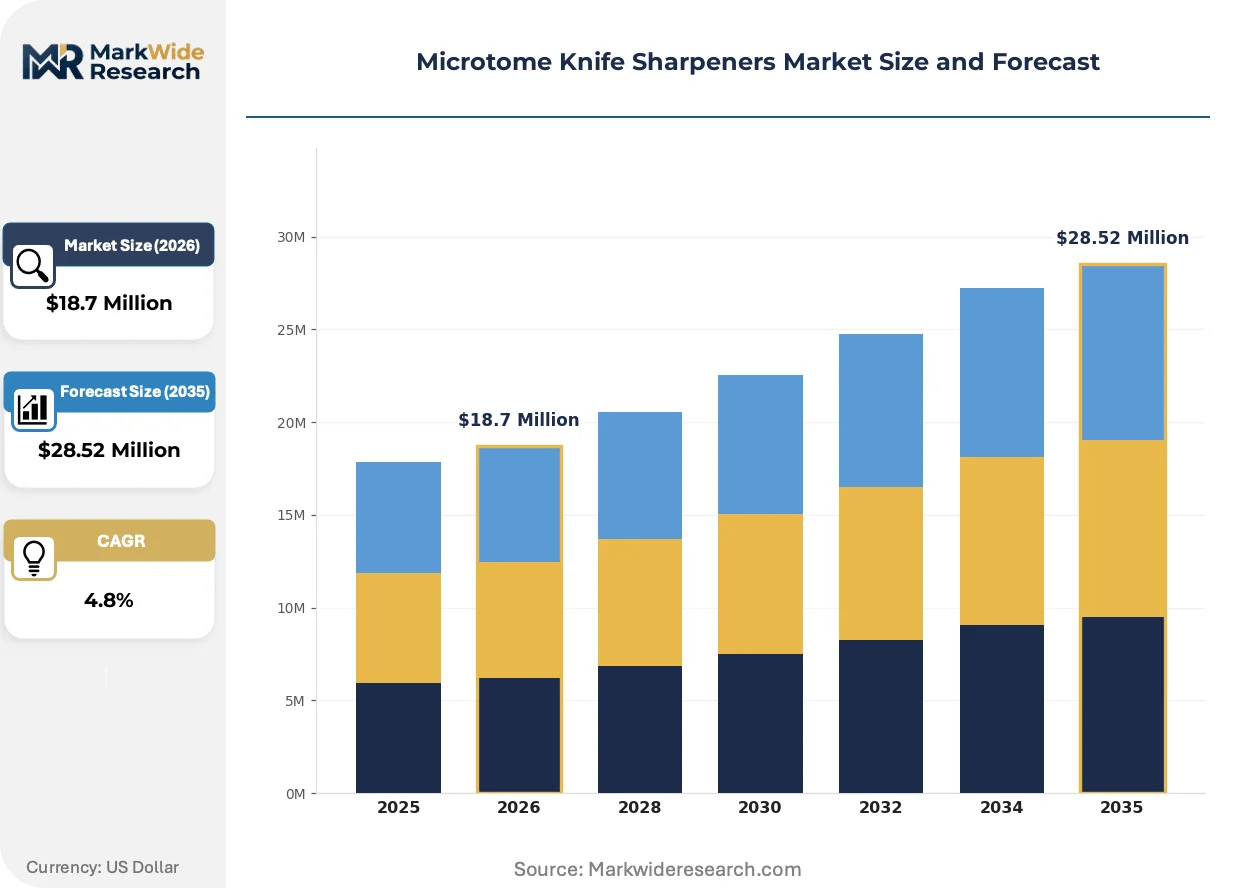
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.52 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sharpeners, Electric Sharpeners, Diamond Sharpeners, Abrasive Sharpeners End User: Research Laboratories, Educational Institutions, Healthcare Facilities, Industrial Users Material: Stainless Steel, Diamond, Tungsten Carbide, Ceramic Operation Mode: Manual, Automated, Semi-Automated, Portable |
| Companies Covered | Leica Biosystems, SLEE Medical, Hacker Instruments, Thermo Fisher Scientific, Sakura Finetek, AmScope, Feather Safety Razor, Pathology Devices, Medimeas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microtome Knife Sharpeners Market Evolving Landscape
Sharpening technology is converging with diagnostic workflow digitization, creating pressure for equipment that delivers traceable, reproducible outcomes rather than artisan-dependent results. Three developments are restructuring competitive requirements.
Programmable microprocessor-controlled sharpening units are miniaturizing benchtop footprints while maintaining precision angle control. Research laboratories with space-constrained histology suites are adopting these compact systems at accelerated rates. This downsizing is compressing the addressable market for traditional floor-standing equipment and favoring suppliers with electronics integration capabilities.
The EU Medical Device Regulation's conformity assessment procedures are extending documentation burdens to sharpening equipment classified as accessory devices. European suppliers are restructuring quality management systems to accommodate notified body oversight. Germany's notified bodies are experiencing audit backlogs that delay market entry for non-established manufacturers.
Consolidated purchasing by multi-site pathology networks is displacing decentralized equipment procurement. Group purchasing organizations are aggregating sharpener demand across regional hospital systems, extracting volume-based pricing concessions. This concentration is most visible in the United States, where integrated delivery networks now control a majority of capital equipment decisions.
Microtome Knife Sharpeners Market Segmentation
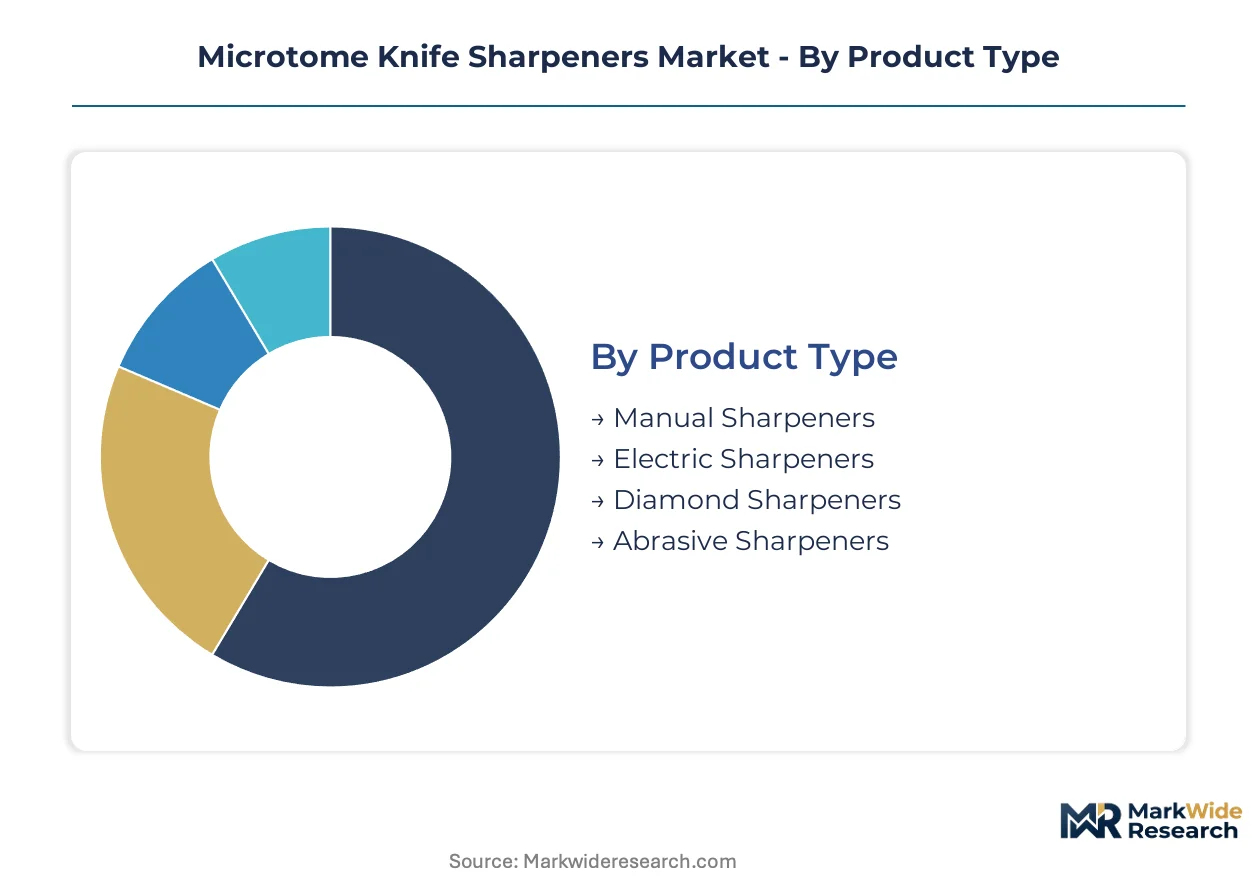
Segmentation in microtome knife sharpeners reveals how procurement criteria diverge across laboratory workflows and regulatory environments. Electric and automated systems command premium positioning where ISO 13485 compliance and traceability documentation drive purchasing decisions.
Product Type:
Electric sharpeners capture the widest margin spreads due to programmable angle precision and reduced technician-to-technician variability in edge geometry.
- Electric Sharpeners:Microprocessor-controlled units maintain edge angles between 30 and 45 degrees with programmable consistency. Academic medical centers in Germany and Japan prioritize these systems for high-throughput histopathology diagnostics where reproducibility documentation satisfies EU MDR and PMDA audit requirements.
- Diamond Sharpeners:Synthetic diamond abrasive matrices restore tungsten carbide and ceramic blades without thermal damage to edge microstructure. Research laboratories with premium knife inventories absorb higher unit costs to extend blade replacement cycles and reduce total cost of ownership.
- Manual Sharpeners:Benchtop units with fixed-angle guides serve low-volume educational settings and field pathology services where capital constraints outweigh throughput requirements.
- Abrasive Sharpeners:Aluminum oxide and silicon carbide wheel systems address standard steel blade maintenance in industrial materials science applications with less stringent edge geometry specifications.
The dominant share belongs to Electric Sharpeners, while Diamond Sharpeners is closing the gap fastest.
End User:
Volume concentration tilts toward facilities managing centralized histology services with recurring blade maintenance demand.
- Research Laboratories:Materials science and life science institutes in the United States and Germany generate concentrated demand for precision sharpening infrastructure. Multi-site pathology networks aggregate procurement through group purchasing organizations, extracting volume-based pricing concessions from suppliers.
- Healthcare Facilities:Hospital-based histopathology departments face EU MDR conformity pressure to upgrade from manual to automated systems with traceable quality records. Centralized service expansion across academic medical centers accelerates capital deployment for compliant sharpening equipment.
- Educational Institutions:University histology training programs prioritize cost-minimized manual systems for student instruction over production-grade edge consistency.
- Industrial Users:Quality control laboratories in metals and composites testing deploy portable sharpeners for field sample preparation outside traditional histology workflows.
Research Laboratories hold the largest installed base, though Healthcare Facilities is expanding most quickly.
Material:
Supply chain positioning for synthetic diamond abrasives creates asymmetric margin capture between sharpening surface technologies.
- Diamond:High-purity synthetic diamond sharpening matrices command input cost premiums but deliver superior performance on advanced blade materials. Limited manufacturing clusters for industrial-grade synthetic diamond expose producers to single-source dependency risks and price volatility.
- Tungsten Carbide:Specialized sharpening protocols for carbide blades require diamond-abrasive compatibility, segmenting demand toward premium equipment configurations.
- Stainless Steel:Conventional abrasive systems address standard steel blade maintenance across entry-level product tiers and educational market segments.
- Ceramic:Advanced ceramic blades challenge conventional sharpening geometry restoration, forcing premature replacement where equipment cannot achieve sub-micron edge specifications.
Diamond dominates material-based revenue contribution, while Tungsten Carbide is gaining share fastest.
Operation Mode:
Automation intensity determines integration complexity with laboratory information management systems and middleware development requirements.
- Automated:Fully automated sharpening cycles with machine vision edge-inspection enable real-time quality feedback and documentation for regulatory audit trails. FDA quality system regulation and ISO 13485 standards govern manufacturing and validation protocols for these systems in the United States.
- Semi-Automated:Technician-supervised operation balances throughput gains against capital expenditure constraints for mid-volume histology laboratories.
- Manual:Hand-guided sharpening with mechanical angle fixtures serves cost-sensitive segments where artisan-dependent results remain acceptable.
- Portable:Battery-powered compact units address field pathology and industrial quality control applications outside fixed laboratory infrastructure.
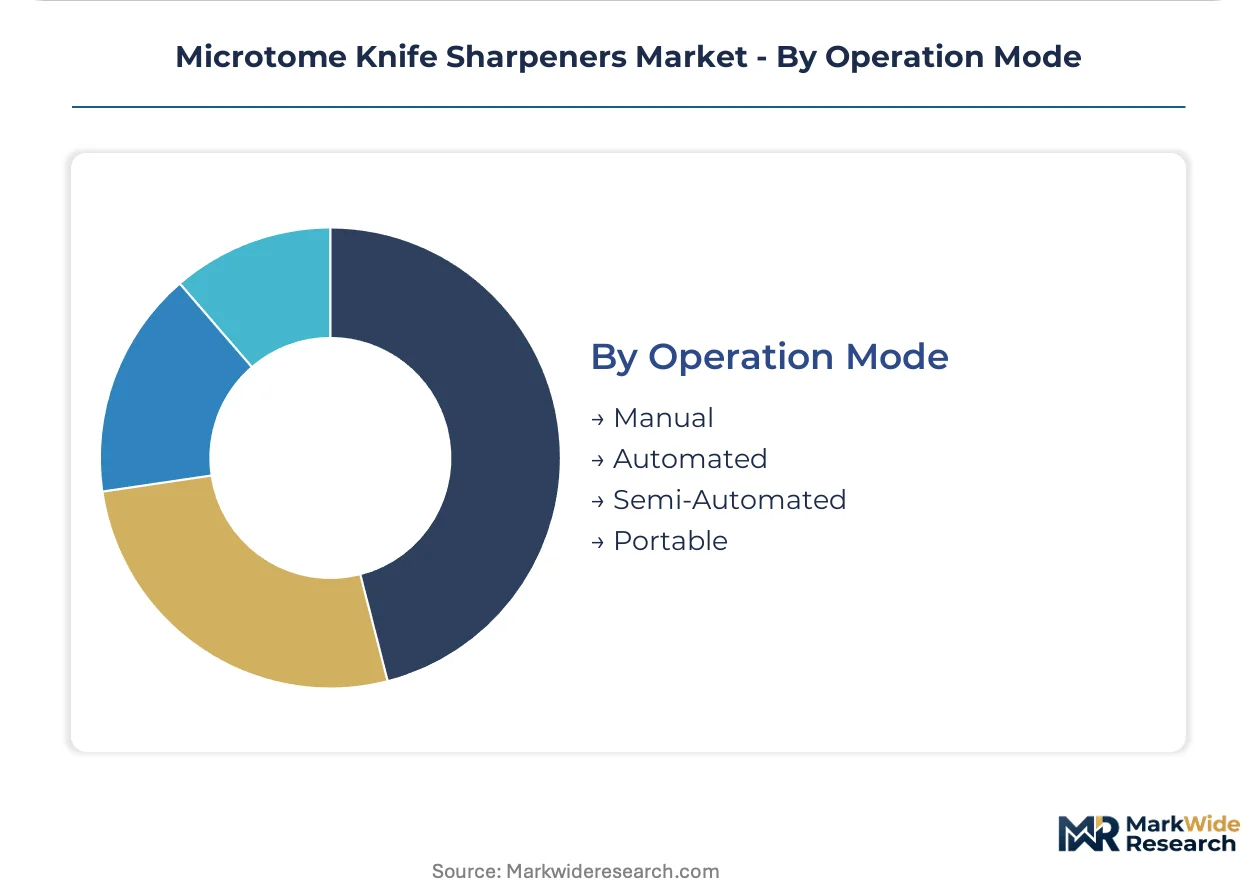
Automated systems command the premium tier, while Semi-Automated is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR conformity timelines and ISO 13485 audit backlogs are redistributing procurement volumes toward jurisdictions with established quality infrastructure. Academic medical centers in Germany, Japan, and the United States anchor demand concentration, while emerging diagnostic networks in South Korea and Australia create expansion vectors for automated sharpening systems.
United States
FDA quality system regulation governs sharpener manufacturing validation, extending product launch timelines for new entrants. Hospital-based pathology networks in Greater Boston and the Research Triangle aggregate procurement through integrated delivery networks, extracting volume concessions from suppliers. The Pacific Northwest hosts precision instrument manufacturing clusters serving materials science research laboratories.
Germany
Notified body audit backlogs under EU MDR delay market entry for non-established manufacturers, consolidating demand around domestic quality leaders. Bavaria's histopathology equipment manufacturing corridor supplies automated sharpening systems across European academic medical centers. North Rhine-Westphalia's centralized histology service expansion drives recurring blade maintenance infrastructure deployment.
Japan
PMDA pre-market technical documentation requirements favor domestic manufacturers with established quality histories, creating asymmetric access for foreign entrants. METI coordinates industrial standards that govern sharpening validation protocols in high-throughput diagnostic facilities. The Kanto region's precision instrument manufacturing base supplies ceramic blade-compatible systems to domestic pathology networks.
South Korea
MFDS medical device registration requirements are tightening conformity assessment for imported sharpening equipment, extending distributor qualification cycles. Seoul Capital Area's expanding biotech research complex generates underpenetrated demand for precision blade maintenance services. Busan-Ulsan's materials science laboratories remain underserved by automated sharpening system providers.
Australia
TGA medical device conformity assessment procedures align with EU MDR documentation standards, streamlining approval pathways for European-certified manufacturers. Victoria's pathology network consolidation creates procurement scale for multi-site sharpening equipment contracts. New South Wales research institutes in materials science and life sciences drive demand for diamond-abrasive sharpening matrices.
Microtome Knife Sharpeners Market Competitive Landscape
Player mix skews toward precision instrument specialists with vertically integrated histology workflow portfolios and industrial cutting heritage transferred into medical applications. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with broad distribution infrastructure; specialized histopathology equipment manufacturers with captive installed bases; and industrial blade specialists pivoting into diagnostic sharpening applications. Competitive dynamics center on ISO 13485 certification velocity and integration partnerships with laboratory information management system platforms.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying distribution-scale competitive advantage, while Leica Biosystems anchors the specialized histopathology equipment tier with workflow-integrated portfolio breadth. Feather Safety Razor represents the industrial heritage pivot archetype, transferring blade manufacturing expertise into medical diagnostic applications. These three companies collectively illustrate how quality certification depth and installed base relationships determine procurement positioning across academic medical centers and research networks.
| Leading Market Players |
|---|
| Leica Biosystems |
| SLEE Medical |
| Hacker Instruments |
| Thermo Fisher Scientific |
| Sakura Finetek |
| AmScope |
| Feather Safety Razor |
| Pathology Devices |
| Medimeas |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with synthetic diamond suppliers lock in both abrasive matrix access and unit cost visibility for sharpener manufacturers serving ISO 13485-certified production lines. These arrangements concentrate pricing power among established vendors with validated supply relationships in Germany and Japan.
Pricing Analysis
Certification level (ISO 13485/FDA-grade versus uncertified) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance documentation depth, with electric automated systems commanding the highest positioning. Pricing pressure stems from group purchasing organization consolidation in United States hospital networks, which extracts volume concessions from suppliers. Educational institutions exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Inventory cycles for high-purity synthetic diamond abrasives extend 16-20 weeks, tethering sharpener production schedules to abrasive matrix availability. Manufacturing concentrates in Germany, Japan, and the United States, with synthetic diamond sourcing anchored in limited industrial-grade production clusters. Supply chain risk centers on single-source dependency for premium abrasive substrates. Distribution runs through specialized histopathology equipment distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ISO 13485 certification creates regulatory entrenchment that foreign entrants struggle to replicate. Switching costs for installed automated systems reinforce incumbent positions.
For Market Incumbents: Compound installed base advantages by deepening integration partnerships with laboratory information management system platforms. Expand captive blade refurbishment services to capture recurring revenue from mid-volume users. Counter emerging independent service providers by bundling sharpening validation documentation with equipment leases. For New Entrants and Emerging Players: Differentiate on machine vision edge-inspection capabilities that incumbent automated systems have not yet integrated. Target South Korean materials science laboratories and Australian research institutes where precision sharpening infrastructure remains underdeployed. Pursue distributor qualification pathways that bypass direct certification timeline compression. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized histopathology equipment manufacturers with captive installed bases and consumables attachment. Five-to-ten year viability favors vendors with backward integration into synthetic diamond abrasive supply or exclusive distribution agreements with academic medical center networks. Monitor EU MDR notified body audit backlog resolution as inflection signal for European market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates market access in Germany and Japan where regulatory documentation requirements favor established quality systems. |
| Laboratory Information Management System Integration | Creates middleware dependency that locks in multi-year equipment contracts with academic medical center networks. |
| Machine Vision Edge-Inspection Development | Differentiates next-generation automated sharpeners from conventional systems in research laboratory procurement evaluations. |
| Independent Blade Refurbishment Service Launch | Bypasses capital-intensive equipment purchases to capture mid-volume users in cost-constrained segments. |
| Synthetic Diamond Supply Agreement | Secures abrasive matrix access against single-source concentration risks in high-purity manufacturing clusters. |
Research Methodology
Initial hypotheses were tested against primary input from histopathology laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and aftermarket service technicians and refined through secondary validation. Primary fieldwork combined structured interviews with hospital-based pathology networks and research institute facilities across Germany, Japan, and the United States. Secondary sources encompassed FDA quality system inspection records, EU MDR notified body documentation, PMDA pre-market submission filings, and hospital procurement database extracts. Bottom-up unit economics triangulated against top-down market sizing from precision instrument manufacturing clusters.
Variance decomposition across product type, end-user segment, material substrate, and operation mode segmentation dimensions structured the analytical framework. CAGRs were derived from installed base growth projections and replacement cycle analysis across the projection horizon. Forecast inputs incorporated EU MDR transition timeline assumptions and automated sharpening validation protocol adoption curves in academic medical centers.
Material uncertainties — regulatory audit backlog duration, synthetic diamond supply disruption, ceramic blade geometry restoration breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline compression and procurement centralization trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Foley Trays Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Premixed IV Minibags Market