
 AI in Laboratory Solution Market | 2026-2036
AI in Laboratory Solution Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Laboratory Solution Market Insights
The capital-intensity divergence between cloud-native startups and established instrument manufacturers is reorganizing competitive dynamics in laboratory AI. Thermo Fisher Scientific leverages its installed base of analytical instruments to embed predictive analytics directly at the point of data generation. Danaher anchors its position through workflow automation platforms that integrate with its life sciences instrumentation portfolio. Agilent Technologies specializes in chromatography-mass spectrometry data pipelines where machine learning reduces compound identification time.
AI in Laboratory Solution encompasses software and hardware systems that apply machine learning algorithms, computer vision, and natural language processing to automate laboratory workflows, analyze experimental data, and predict outcomes from complex biological and chemical datasets. These systems typically process spectral data, microscopy images, and genomic sequences with throughput exceeding thousands of samples per day, primarily serving to accelerate research cycles and reduce human error in high-complexity testing environments. Predictive analytics and image recognition solutions command premium pricing due to their direct impact on diagnostic accuracy and discovery timelines. Deep learning applications within drug discovery represent the fastest-expanding technology segment as pharmaceutical sponsors seek to compress preclinical development phases.
The FDA's evolving framework for AI-enabled medical devices and the EPA's Good Automated Laboratory Practices create dual compliance obligations for vendors serving regulated industries. ISO 15189 and CLIA standards further constrain algorithm validation requirements in clinical diagnostic settings. Stakeholders must monitor emerging EMA guidance on adaptive AI systems to anticipate European market access conditions.
Market Dynamics
Deep learning architectures are compressing preclinical timelines from years to months, forcing pharmaceutical sponsors to restructure their R&D partnerships and data infrastructure investments around AI-native vendors rather than traditional contract research organizations.
Growth Catalysts
- ISO 15189 and CLIA standards:Diagnostic laboratories in the United States face mandatory algorithm validation requirements that create captive demand for compliant AI platforms, locking in vendor relationships once systems achieve accreditation.
- Biotech clusters in Munich and Heidelberg:Germany's concentrated life sciences infrastructure generates network effects where AI tool adoption by anchor institutions cascades through supplier ecosystems and regional research consortia.
- FDA guidance on AI-enabled medical devices:The agency's predicate device pathway for software as a medical device accelerates market entry for validated algorithms, reducing regulatory uncertainty for sponsors investing in laboratory automation.
Market Restraints
- GPU and specialized AI accelerator costs:Cloud compute pricing for training large foundation models on genomic and spectral datasets consumes disproportionate budget share versus traditional wet-lab expenditures, squeezing mid-tier research institutions.
- Data concentration in hyperscale cloud providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform control the infrastructure layer for laboratory AI deployments, creating vendor lock-in and egress cost barriers for multi-cloud strategies.
- Interoperability gaps between instrument data formats:Proprietary file structures from legacy chromatography and mass spectrometry systems fragment training datasets and impede model generalization across equipment generations.
Strategic Opportunities
- Japan's PMDA regulatory pathway:The agency's Sakigake designation system offers priority review for AI diagnostic algorithms, creating a faster commercialization route than FDA 510(k) clearance for qualifying innovations.
- Convergence of computer vision and robotic liquid handling:Integration of automated microscopy interpretation with physical sample manipulation enables closed-loop experimental systems that reduce human intervention in high-throughput screening.
- India's pharmaceutical contract research expansion:The country's CDSCO regulatory harmonization efforts and cost-competitive talent pool position it as an emerging destination for AI-enabled drug discovery outsourcing from Western sponsors.
Industry Challenges
- Computational biology and machine learning engineering skill gaps:Laboratory AI deployment requires hybrid expertise spanning biological domain knowledge and MLOps infrastructure management, with talent scarcity concentrated in mid-market CROs and academic core facilities.
- FDA adaptive AI system validation timelines:Continuous learning algorithms that update based on new experimental data trigger re-validation obligations under current guidance, complicating deployment planning for sponsors seeking iterative improvement capabilities.
- Legacy LIMS integration complexity:Enterprise laboratory information management systems from the 2010s lack API-native architectures, forcing costly middleware development to connect AI analytics layers with operational data repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Laboratory Solution Market |
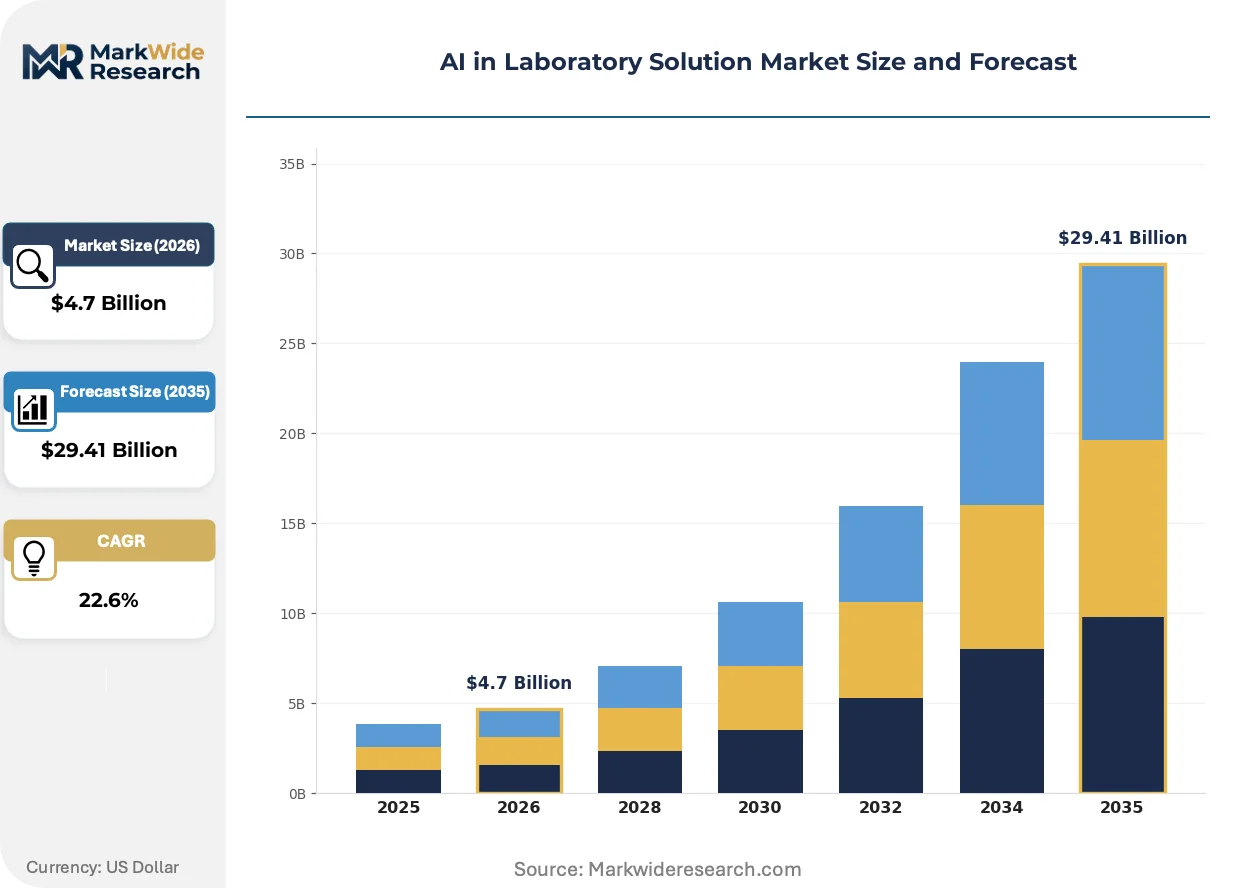
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Predictive Analytics, Workflow Automation, Quality Control, Data Management, Image Recognition Technology: Machine Learning, Natural Language Processing, Computer Vision, Deep Learning, Robotic Process Automation Application: Genomic Research, Clinical Diagnostics, Drug Discovery, Environmental Testing, Food Safety End User: Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Biotechnology Firms, Academic Labs |
| Companies Covered | Thermo Fisher Scientific, Danaher, Agilent Technologies, F. Hoffmann-La Roche, Siemens Healthineers, Tecan Group, Eppendorf, Becton, Dickinson and Company, Waters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Laboratory Solution Market Trends and Innovations
Foundation models trained on molecular and biological data are displacing task-specific algorithms, reshaping how laboratory AI vendors architect their product stacks and how pharmaceutical buyers evaluate platform scalability.
Federated learning architectures for multi-site drug discovery are bifurcating competitive positioning in the contract research space. Large pharmaceutical sponsors with internal data infrastructure deploy privacy-preserving collaborative models across global R&D sites. Mid-tier biotech firms without comparable capital access partner with platform vendors offering pre-trained models with fine-tuning capabilities. This technology is compressing the viable middle ground between fully outsourced and fully in-house AI capabilities.
The EU AI Act's risk classification system for medical device software imposes conformity assessment obligations on laboratory diagnostic algorithms deployed in European member states. High-risk categorization for AI systems influencing patient treatment decisions triggers notified body involvement and post-market surveillance requirements. Vendors serving the European market are responding by segregating product versions, with restricted feature sets for EU deployment versus fuller capabilities in jurisdictions with lighter touch frameworks.
Pharmaceutical procurement teams now unbundle AI software licenses from instrument hardware purchases, reversing the bundled analytics packages that dominated the 2015-2022 period. This pattern shift disrupts traditional instrument manufacturers who relied on software attach rates to subsidize hardware margins. The unbundling is most visible in North American biopharma, where centralized IT procurement functions have gained authority over laboratory technology decisions previously controlled by individual research units.
AI in Laboratory Solution Market Segmentation
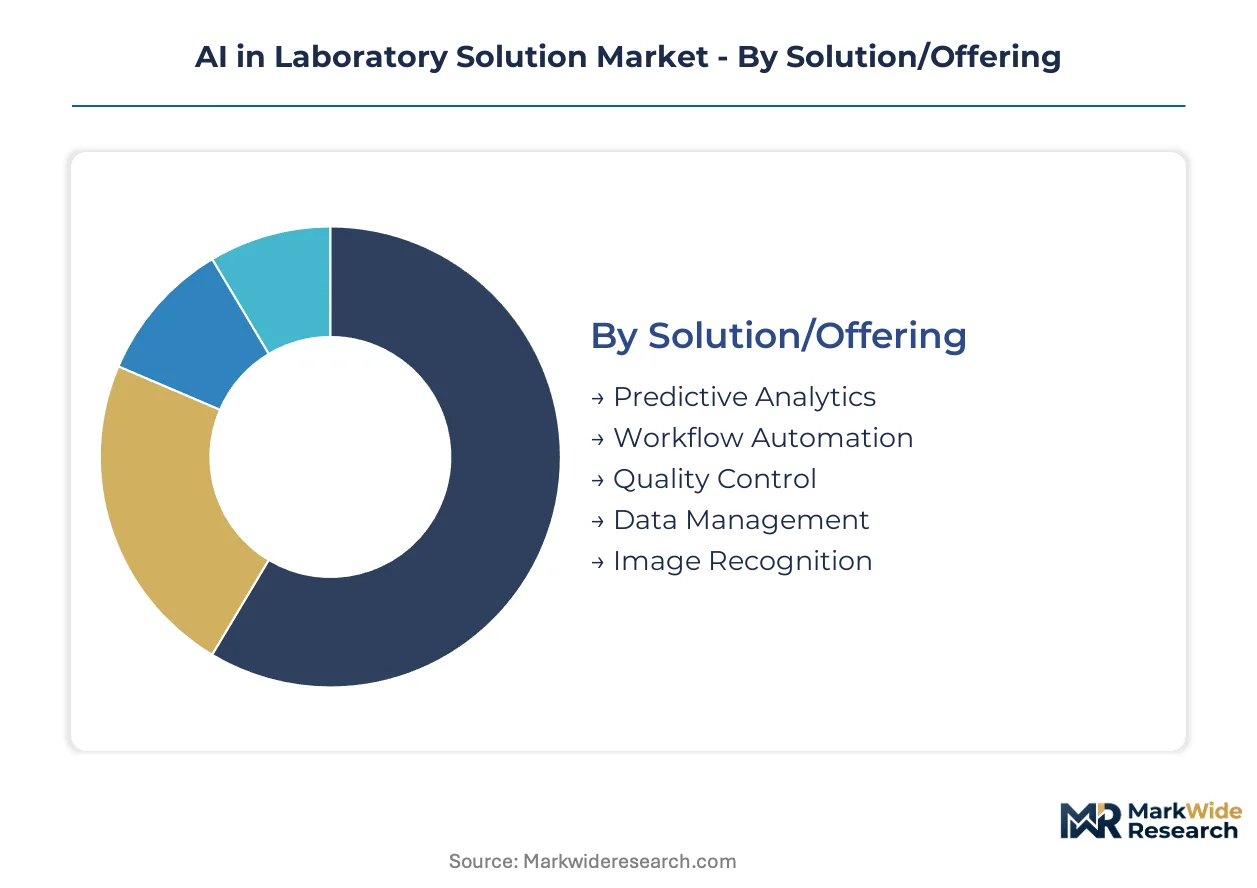
Segmentation in AI laboratory solutions reveals how technology substitution pressures reshape procurement priorities across different capability layers. Pharmaceutical sponsors and diagnostic operators segment investments based on regulatory validation requirements, data infrastructure maturity, and the compressive impact of foundation models on traditional algorithm categories.
Solution/Offering:
Predictive analytics platforms face acute substitution pressure from pre-trained biological foundation models that absorb forecasting capabilities into general-purpose architectures.
- Predictive Analytics:Algorithms trained on historical experimental data forecast compound behavior, patient response probabilities, and equipment maintenance needs. Demand concentrates in pharmaceutical companies restructuring R&D partnerships around AI-native vendors rather than traditional contract research organizations.
- Image Recognition:Computer vision systems classify microscopy images, pathology slides, and cell culture states with throughput exceeding thousands of samples daily. Diagnostic laboratories in the United States drive procurement under mandatory ISO 15189 and CLIA algorithm validation requirements that lock in vendor relationships post-accreditation.
- Workflow Automation:Orchestration layers integrate instrument control, sample tracking, and data pipeline execution.
- Quality Control:Real-time deviation detection and compliance monitoring systems.
- Data Management:Structured and unstructured laboratory data ingestion, annotation, and retrieval infrastructure.
Predictive analytics retains volume leadership; image recognition holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive deep learning training from deployable inference technologies accessible to mid-tier research institutions.
- Deep Learning:Neural architectures with millions of parameters trained on genomic sequences, spectral data, and molecular structures compress preclinical timelines from years to months. Pharmaceutical sponsors in Germany's biotech clusters around Munich and Heidelberg cascade adoption through supplier ecosystems and regional research consortia.
- Machine Learning:Classical supervised and unsupervised methods including random forests, support vector machines, and gradient boosting on structured laboratory datasets. Academic labs and mid-market contract research organizations leverage these for validated applications where interpretability requirements exceed deep learning's black-box constraints.
- Computer Vision:Convolutional and transformer-based architectures for spatial data interpretation.
- Natural Language Processing:Text extraction from scientific literature, protocol documents, and regulatory filings.
- Robotic Process Automation:Rule-based task automation without adaptive learning capabilities.
Machine learning retains volume leadership; deep learning commands the steepest expansion trajectory.
Application:
Application segmentation tracks how customer type influences deployment complexity and regulatory pathway selection.
- Drug Discovery:Target identification, lead optimization, and preclinical safety prediction workflows. Demand concentrates in pharmaceutical companies seeking to compress development phases through AI-native vendor partnerships.
- Clinical Diagnostics:Patient sample analysis and pathology interpretation with diagnostic-grade accuracy requirements. FDA guidance on AI-enabled medical devices accelerates market entry for validated algorithms through predicate device pathways.
- Genomic Research:Sequence analysis, variant calling, and functional genomics interpretation.
- Environmental Testing:Contaminant detection and ecological monitoring applications.
- Food Safety:Pathogen detection and supply chain verification systems.
Clinical diagnostics retains volume leadership; drug discovery is climbing the fastest.
End User:
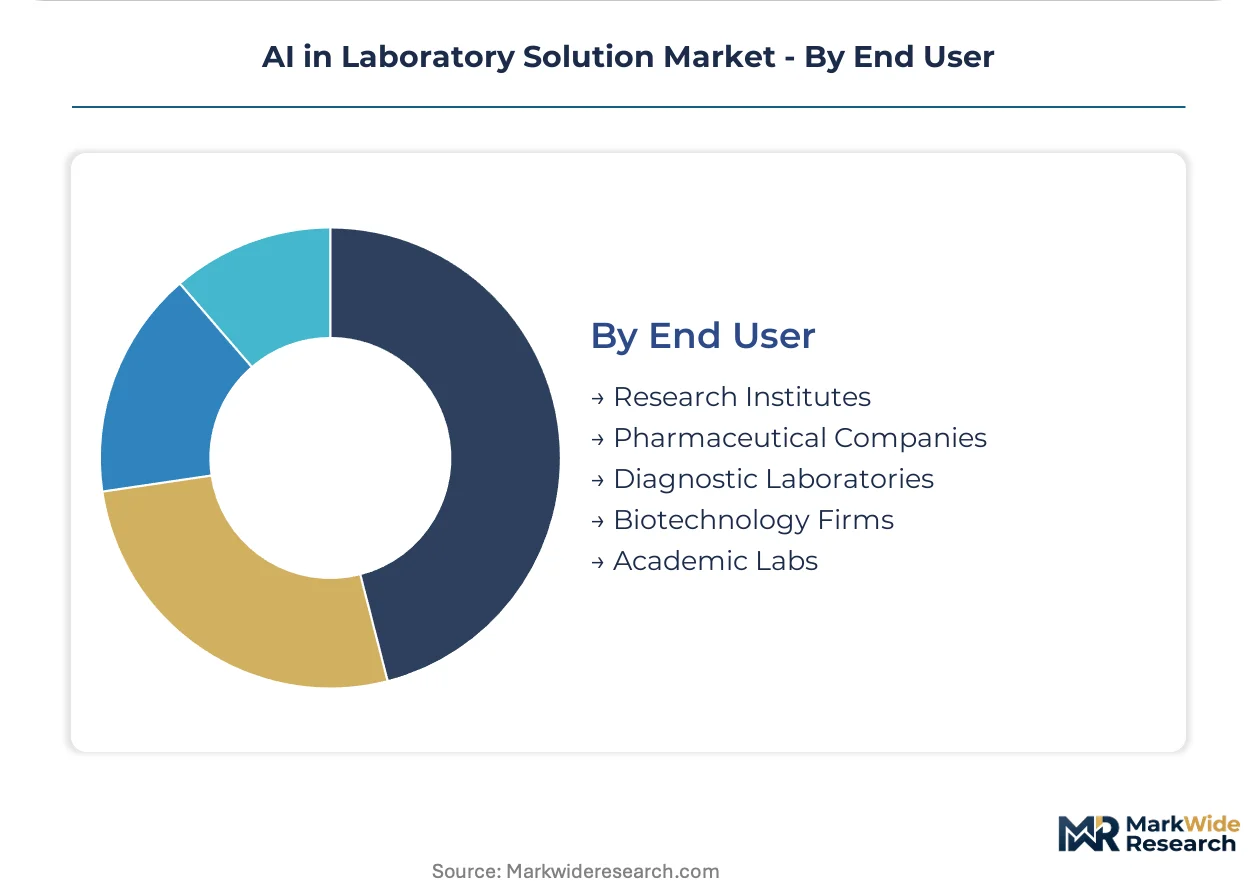
End user maturity determines whether procurement prioritizes validated compliance or experimental flexibility.
- Pharmaceutical Companies:Enterprise-scale deployments integrating internal data infrastructure with external AI platforms. Internal MLOps capabilities and global R&D site coordination drive preference for federated learning architectures and privacy-preserving collaborative models.
- Diagnostic Laboratories:Regulated environments requiring algorithm validation under CLIA, ISO 15189, and FDA medical device frameworks. Accredited facilities in the United States generate captive demand for compliant platforms that lock in vendor relationships post-implementation.
- Research Institutes:Discovery-oriented environments prioritizing experimental flexibility over regulatory validation.
- Biotechnology Firms:Venture-funded operations balancing capital constraints against platform scalability requirements.
- Academic Labs:Grant-funded research with limited infrastructure budgets and publication-driven incentive structures.
Diagnostic laboratories retain volume leadership; pharmaceutical companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for AI laboratory solutions diverge sharply by geography: pharmaceutical sponsors in Germany and the United States prioritize predictive analytics for drug discovery acceleration, while diagnostic operators in Japan and India concentrate procurement on regulatory-validated image recognition platforms for clinical deployment.
United States
Diagnostic laboratories drive captive demand for FDA-validated AI platforms under CLIA and ISO 15189 mandates that lock in vendor relationships post-accreditation. The FDA's predicate device pathway for software as a medical device accelerates market entry for qualifying algorithms. Greater Boston and San Francisco Bay Area biotech clusters anchor enterprise-scale deployments integrating federated learning architectures across global R&D sites.
Germany
Biotech clusters around Munich and Heidelberg generate network effects where AI tool adoption by anchor institutions cascades through supplier ecosystems and regional research consortia. The country's national pharmaceutical regulator enforces MDR conformity assessments for diagnostic algorithms deployed in clinical settings. Bavaria's concentrated life sciences infrastructure positions it as the primary demand center for deep learning applications in preclinical compound screening.
Japan
PMDA's Sakigake designation system offers priority review for AI diagnostic algorithms, creating a faster commercialization route than FDA 510(k) clearance for qualifying innovations. Pharmaceutical sponsors leverage this pathway to compress regulatory timelines for image recognition platforms in pathology interpretation. The Kanto region around Tokyo anchors domestic demand for computer vision systems integrated with robotic liquid handling infrastructure.
India
CDSCO regulatory harmonization efforts and cost-competitive talent pools position the country as an emerging destination for AI-enabled drug discovery outsourcing from Western sponsors. Contract research expansion concentrates in Maharashtra and Karnataka, where mid-tier biotech firms partner with platform vendors offering pre-trained models with fine-tuning capabilities. The national pharmaceutical regulator's alignment with ICH guidelines reduces friction for multi-site validation studies.
United Kingdom
Research institutes and academic core facilities prioritize experimental flexibility over regulatory validation, driving demand for machine learning methods where interpretability requirements exceed deep learning constraints. The Medicines and Healthcare products Regulatory Agency's evolving framework for AI-enabled medical devices shapes deployment planning for sponsors seeking iterative improvement capabilities. The Golden Triangle of London, Oxford, and Cambridge anchors discovery-oriented procurement for genomic research applications.
AI in Laboratory Solution Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in laboratory AI, with capital-intensity divergence between cloud-native startups and established instrument manufacturers reorganizing competitive dynamics. The market structure reflects tiered positioning: full-platform vendors with embedded hardware-software integration compete against point-solution specialists in predictive analytics and image recognition. Strategic archetypes include instrument manufacturers leveraging installed bases for predictive analytics embedding, workflow automation platforms anchoring life sciences portfolios, and chromatography-mass spectrometry data pipeline specialists. Dominant competitive moves span M&A activity targeting AI-native capabilities and strategic partnerships restructuring R&D collaborations around federated learning architectures.
Within the integrated instrumentation tier, Thermo Fisher Scientific and Danaher exemplify archetypes of vendors leveraging analytical instrument installed bases to embed AI directly at data generation points. Agilent Technologies occupies a specialist position in chromatography-mass spectrometry data pipelines where machine learning reduces compound identification timelines. These three companies represent contrasting strategic vectors: full-platform integration, workflow automation anchoring, and domain-specific algorithmic specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Agilent Technologies |
| F. Hoffmann-La Roche |
| Siemens Healthineers |
| Tecan Group |
| Eppendorf |
| Becton, Dickinson and Company |
| Waters |
| Others |
Pricing and Supply Chain Analysis
Pre-trained biological foundation models displacing task-specific predictive analytics simultaneously concentrate supplier power among hyperscale cloud providers in the United States and compress pricing premiums for legacy algorithm vendors serving mid-tier research institutions.
Pricing Analysis
After-sales revenue from algorithm re-validation services and extended compliance support contracts drives lifetime value for diagnostic-grade AI platforms. Three-tier pricing structure across enterprise, mid-market, and academic levels separates FDA-validated deployments with ISO 15189 certification from experimental licenses with limited liability coverage. Cost compression in the mid-market tier is intensifying because GPU cloud compute consumption for foundation model training consumes disproportionate budget share versus traditional wet-lab expenditures. Academic labs exhibit highest price sensitivity due to grant-funded procurement constraints, while pharmaceutical sponsors with internal MLOps capabilities demonstrate lowest sensitivity to per-seat licensing premiums.
Supply Chain Analysis
Inbound logistics costs for specialized AI accelerators shipped through the Trans-Pacific trade lane from Taiwan and South Korea face persistent container availability constraints at West Coast ports. Hardware component sourcing draws from Taiwan for GPU fabrication, South Korea for high-bandwidth memory modules, and the United States for cloud orchestration software. Single-source vulnerability concentrates in NVIDIA's dominant position for laboratory-scale training infrastructure. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and value-added resellers serving diagnostic laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: CLIA and ISO 15189 validation requirements create captive demand that locks vendor relationships post-accreditation and erects substantial barriers to algorithm substitution.
For Market Incumbents: Shield installed-base relationships by embedding predictive analytics directly at the point of data generation on legacy chromatography and mass spectrometry instruments, countering cloud-native entrants seeking to disintermediate hardware-software bundles. Deepen vertical integration into federated learning infrastructure to capture pharmaceutical sponsor demand for privacy-preserving multi-site collaboration. Prioritize certification investment in Japan's PMDA Sakigake pathway to accelerate commercialization timelines versus FDA 510(k) clearance. For New Entrants and Emerging Players: Japan's PMDA Sakigake designation system offers priority review for AI diagnostic algorithms, creating a faster commercialization route than FDA pathways for qualifying innovations. Target India's pharmaceutical contract research expansion in Maharashtra and Karnataka, where CDSCO regulatory harmonization and cost-competitive talent pools position the country for AI-enabled drug discovery outsourcing from Western sponsors. Deploy platform-as-a-service models with pre-trained biological foundation models and fine-tuning capabilities to penetrate mid-tier biotech firms lacking internal data infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed workflow automation platforms that have achieved CLIA accreditation lock-in at diagnostic laboratory networks but lack cloud-native architecture for foundation model deployment. Long-term viability hinges on five-to-ten year regulatory entrenchment durability as FDA adaptive AI guidance evolves. Watch for inflection signals in pharmaceutical procurement team unbundling of AI software licenses from instrument hardware purchases, which accelerates consolidation pressure on traditional manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Platform Deployment | Enables pharmaceutical sponsors to train collaborative models across global R&D sites without data centralization. |
| Regulatory Fast-Track Certification | Japan's PMDA Sakigake designation compresses commercialization timelines versus FDA 510(k) clearance pathways. |
| Legacy LIMS API Integration | Middleware development connects AI analytics layers with operational data repositories in enterprise laboratories. |
| Foundation Model Fine-Tuning Service | Pre-trained biological models with customization capabilities penetrate mid-tier biotech firms lacking internal infrastructure. |
| Hyperscaler Cloud Partnership | Strategic alliances with AWS, Azure, or GCP reduce vendor lock-in risks for multi-cloud laboratory deployments. |
Research Methodology
The analysis maps predictive analytics platforms, image recognition systems, workflow automation layers, and deep learning training infrastructure, each validated through primary interviews with laboratory directors, regulatory affairs specialists at diagnostic operators, pharmaceutical R&D procurement managers, and AI platform engineering leads. Secondary sources include FDA 510(k) clearance databases, EMA medical device guidance documents, ISO 15189 accreditation registries, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across vendor revenue disclosures and top-down cross-checks against pharmaceutical R&D spending patterns ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include solution type, technology tier, application area, and end-user maturity, with additional granularity on regulatory validation status. CAGRs were derived through logistic diffusion curves fitted to adoption rate data, with inputs from genomic data generation growth, cloud compute pricing trajectories, and diagnostic laboratory accreditation timelines.
Underlying assumptions cover stable FDA guidance interpretation on adaptive AI systems, with deviation risk concentrated in EMA regulatory evolution and potential EU AI Act risk reclassification for laboratory diagnostic algorithms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Assessment Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
US Clinical Laboratory Services Market