
 Laboratory Developed Tests Market | 2026-2036
Laboratory Developed Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Developed Tests Market Intelligence
Modular assay bundling is rebalancing procurement decisions across hospital laboratories and commercial reference sites. Mayo Clinic Laboratories leverages its integrated health system footprint to sustain captive demand for complex molecular diagnostics. Guardant Health competes through liquid biopsy specialization, while Labcorp anchors national scale with broad esoteric test menus.
Laboratory Developed Tests are analytical procedures designed, validated, and performed within a single clinical laboratory, typically employing PCR amplification, next-generation sequencing, or microarray hybridization with specimen-specific reagents to generate diagnostic or prognostic information for patient management. Genetic tests and cancer tests command premium positioning due to complex validation requirements and specialized interpretive expertise. Next-generation sequencing applications are expanding fastest as oncology workflows shift toward comprehensive genomic profiling, while ELISA-based infectious disease panels remain mature, high-volume staples.
The FDA oversees LDT quality through enforcement discretion policies and emerging premarket review frameworks, while the Centers for Medicare and Medicaid Services governs laboratory operations under CLIA certification tiers that dictate test complexity and personnel qualifications. State laboratory licensing boards impose supplementary proficiency testing mandates that shape regional market access conditions. Stakeholders must monitor regulatory rulemaking timelines to calibrate validation investments against commercialization horizons.
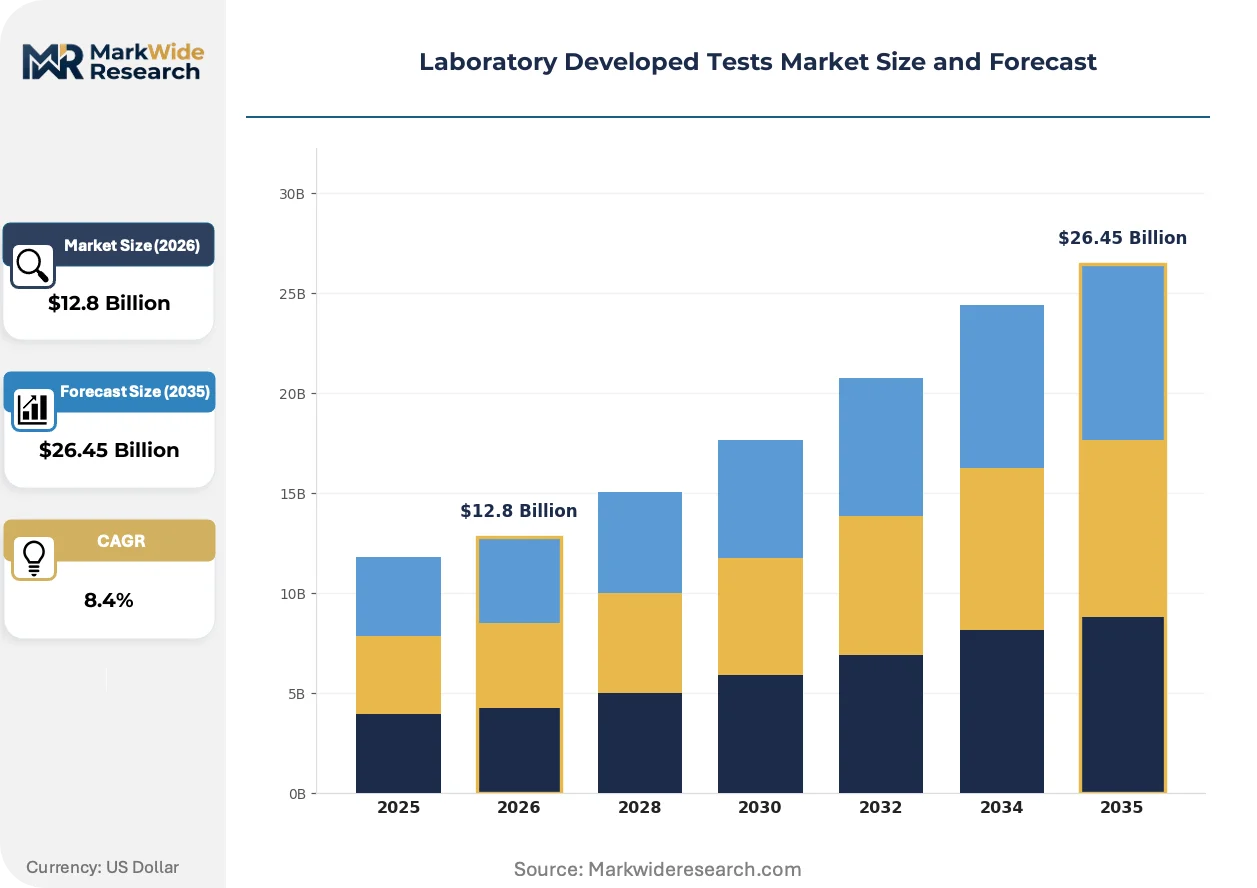
Market Dynamics
The FDA's premarket review framework for high-risk LDTs is forcing laboratories to restructure analytical validation workflows and accelerate infrastructure investments ahead of enforcement timelines.
Growth Catalysts
- Oncology workflow transformation:Academic medical centers are building in-house comprehensive genomic profiling capabilities to reduce send-out volumes and capture margin.
- CLIA high-complexity certification expansion:The Centers for Medicare and Medicaid Services has expanded personnel qualification pathways, enabling more laboratories to perform next-generation sequencing-based assays.
- Integrated health system consolidation:Captive laboratory networks within US health systems are absorbing reference testing volume previously directed to commercial laboratories.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction enzymes and sequencing flow cells depend on a limited supplier base concentrated in California and Massachusetts.
- Validation cost escalation:Analytical and clinical validation for next-generation sequencing panels requires 18-24 month timelines and specialized bioinformatics infrastructure.
- Liquid biopsy substitution pressure:Blood-based circulating tumor DNA assays are displacing tissue-based molecular testing in late-stage cancer monitoring applications.
Strategic Opportunities
- Pharmacogenomic expansion:Psychiatric medication management and cardiovascular drug dosing represent underpenetrated clinical applications for preemptive genotyping panels.
- AI-assisted variant interpretation:Machine learning tools are converging with laboratory information systems to reduce manual review burden for rare variant classification.
- Direct-to-employer contracting:Self-insured employers are establishing direct laboratory access agreements to bypass traditional payer networks for wellness screening programs.
Industry Challenges
- Bioinformatics talent scarcity:Variant scientists and computational biologists command premium compensation, constraining laboratory scaling velocity.
- Electronic health record integration complexity:Discrete genomic data elements require custom interface development with legacy systems from Epic and Cerner.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Developed Tests Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Assays, Genetic Tests, Infectious Disease Tests, Cancer Tests Technology: PCR, Next-Generation Sequencing, Microarrays, ELISA End User: Hospitals, Diagnostic Laboratories, Research Institutions, Commercial Laboratories Application: Oncology, Infectious Diseases, Cardiovascular, Neurology |
| Companies Covered | Mayo Clinic Laboratories, Guardant Health, Labcorp, Roche, Thermo Fisher Scientific, Quest Diagnostics, Exact Sciences, Illumina, ARUP Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Developed Tests Market Strategic Shifts & Innovations
Automation and artificial intelligence are compressing assay development timelines while regulatory clarity is reshaping competitive entry barriers. Three developments are redefining operational models.
Multiplexed next-generation sequencing panels are consolidating discrete single-gene tests into comprehensive genomic profiling workflows. Community oncology practices are adopting these platforms to retain molecular testing revenue locally. This consolidation is compressing the addressable market for standalone fluorescence in situ hybridization and immunohistochemistry assays.
The FDA's phased enforcement discretion withdrawal for high-risk LDTs is mandating premarket submission pathways for oncology companion diagnostics and pharmacogenomic tests. Laboratories must now budget for quality system documentation and clinical validation studies comparable to in vitro diagnostic manufacturers. Academic medical centers with existing regulatory affairs infrastructure are adapting faster than independent reference laboratories.
Health system laboratories are unbundling interpretive services from wet lab processing, selling variant classification and clinical reporting as standalone consultative products to external clients. This service disaggregation is disrupting traditional reference laboratory relationships with community hospitals. The shift is most visible in the United States, where integrated delivery networks leverage CLIA certification across multiple states to serve distributed client bases.
Laboratory Developed Tests Market Segmentation
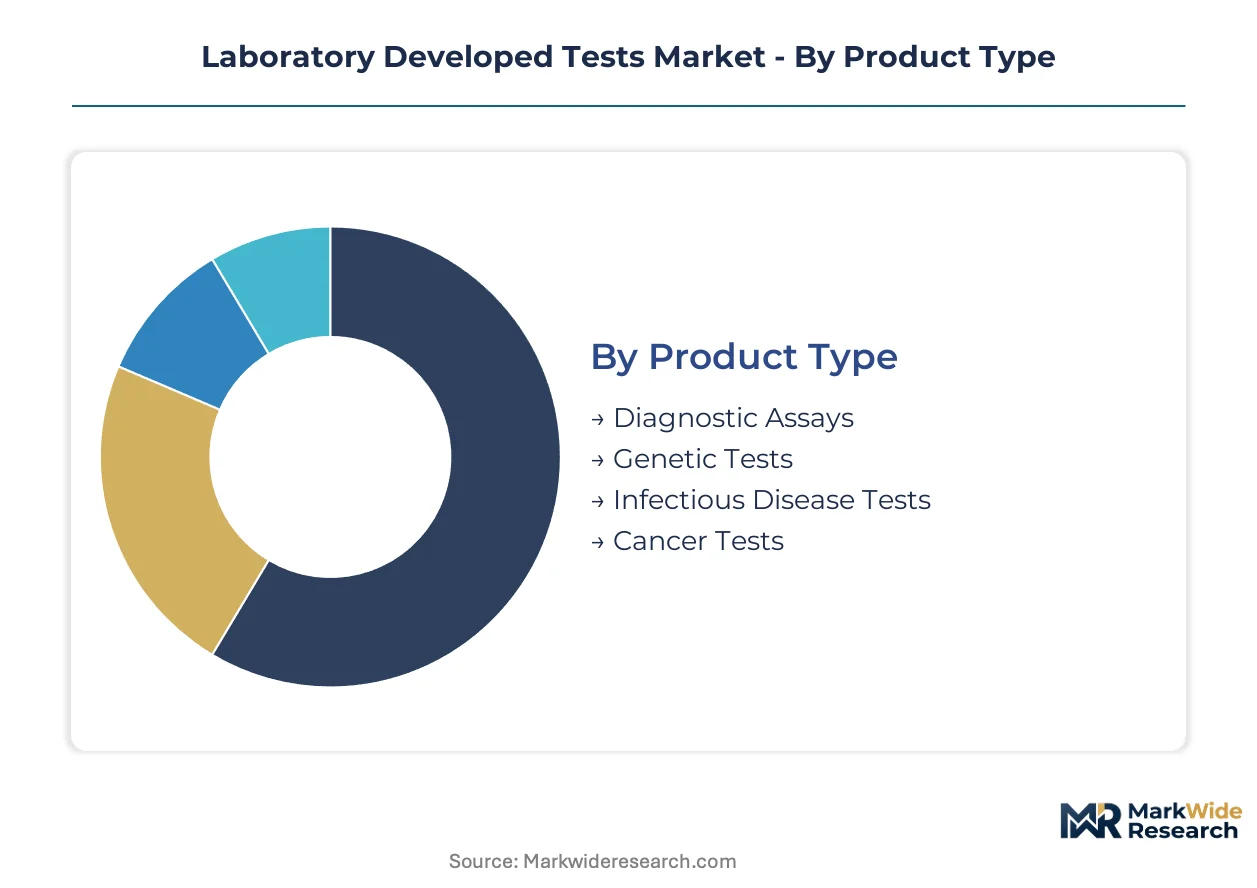
Laboratory Developed Tests segment along four critical dimensions that determine commercial strategy. Product type and technology choices dictate regulatory pathways and capital requirements, while end-user concentration and application focus shape pricing power and account management intensity.
Product Type:
Standalone diagnostic assays operate independently within laboratory workflows, while genetic and cancer tests embed within broader clinical decision systems requiring interpretive services.
- Diagnostic Assays:Enzymatic and immunoassay-based procedures detect biomarkers, metabolites, or pathogens with standardized reagent kits. Hospital laboratories in Texas and Florida deploy these for routine chemistry and immunoassay panels, driven by CLIA moderate-complexity certification expansion that reduces personnel barriers.
- Genetic Tests:DNA-based assays identify inherited variants using PCR amplification or hybridization techniques. Academic medical centers in California and Massachusetts concentrate demand for prenatal carrier screening and hereditary cancer panels, constrained by bioinformatics pipeline validation costs that extend development timelines.
- Infectious Disease Tests:Pathogen-specific molecular diagnostics detect viral, bacterial, or fungal targets.
- Cancer Tests:Tumor profiling assays guide therapeutic selection and monitoring.
Diagnostic assays lead volumes today; cancer tests are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive platforms from benchtop instruments, with reimbursement rates scaling accordingly.
- PCR:Polymerase chain reaction amplifies target nucleic acid sequences through thermal cycling with fluorescent detection. Community hospital laboratories across the United States rely on PCR for infectious disease diagnostics and pharmacogenomic screening, pressured by supply concentration of Taq polymerase enzymes from limited California suppliers.
- Next-Generation Sequencing:Massively parallel sequencing generates comprehensive genomic data through clonal amplification and synthesis-based detection. Oncology departments at academic medical centers in New York and Pennsylvania adopt these platforms for comprehensive genomic profiling, compelled by FDA premarket review timelines that demand accelerated validation investments.
- Microarrays:Solid-phase hybridization platforms enable high-throughput genotyping.
- ELISA:Enzyme-linked immunosorbent assays provide standardized protein detection.
PCR anchors current volume; next-generation sequencing shows steepest expansion trajectory.
End User:
Customer type determines procurement complexity, with integrated health systems leveraging captive networks against independent reference laboratories.
- Hospitals:Inpatient and outpatient facilities perform LDTs within clinical pathology departments. Large health systems in Illinois and Ohio build centralized molecular diagnostics hubs, absorbing send-out volume previously directed to commercial laboratories.
- Diagnostic Laboratories:Independent reference sites process specimens from multiple client institutions. Regional laboratories in North Carolina and Georgia compete on turnaround time and specialized assay menus.
- Research Institutions:Academic centers develop and validate novel assays under investigational protocols.
- Commercial Laboratories:National reference laboratories operate at scale across state jurisdictions.
Hospitals dominate specimen volume; diagnostic laboratories face margin compression from health system consolidation.
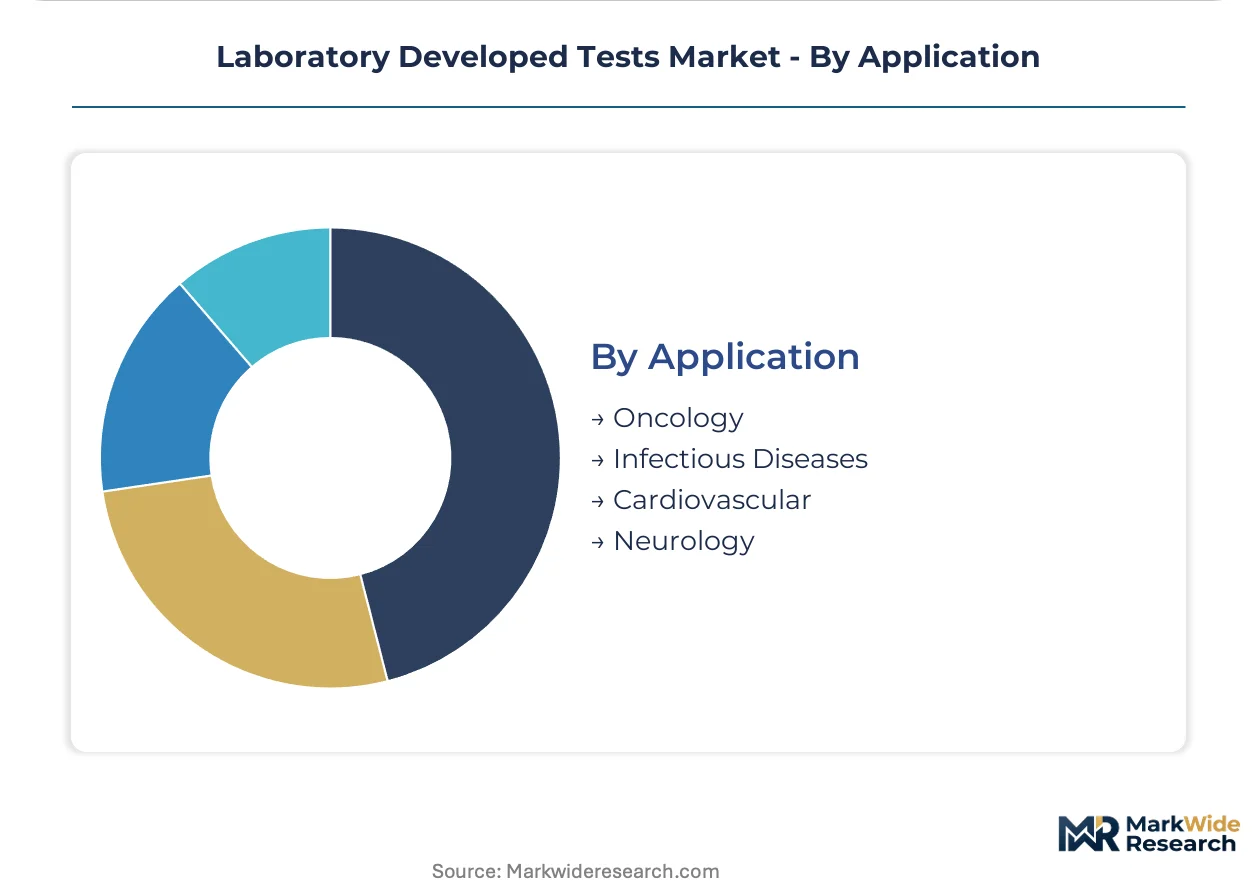
Application:
Maturity varies sharply across clinical domains, with oncology commanding premium positioning against commoditized infectious disease panels.
- Oncology:Tumor profiling and liquid biopsy applications guide precision therapy selection. Comprehensive genomic profiling concentrates at academic medical centers in California and Texas, driven by companion diagnostic requirements that mandate analytical validation rigor.
- Infectious Diseases:Pathogen detection and antimicrobial resistance testing address high-frequency clinical needs. Hospital laboratories deploy respiratory and bloodstream infection panels, constrained by reimbursement compression on routine molecular diagnostics.
- Cardiovascular:Pharmacogenomic and risk stratification assays support statin selection and anticoagulation management.
- Neurology:Cerebrospinal fluid biomarkers and genetic panels aid neurodegenerative diagnosis.
Infectious diseases generates highest test frequency; oncology captures greatest revenue per specimen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory Developed Tests originated within academic medical centers in the United States during the 1970s, with the field expanding through CLIA certification frameworks that enabled hospital laboratories to develop customized diagnostic protocols for specialized clinical needs.
United States
Integrated health systems in Illinois and Ohio operate captive molecular diagnostics hubs that absorb reference testing volume previously outsourced to commercial laboratories. The FDA's phased enforcement discretion withdrawal for high-risk LDTs mandates premarket submission pathways for oncology companion diagnostics. Academic medical centers in California and Texas concentrate comprehensive genomic profiling capabilities, driven by companion diagnostic requirements that demand rigorous analytical validation.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia maintain sophisticated in-house molecular pathology departments serving precision oncology workflows. The country's national pharmaceutical regulator implements EU In Vitro Diagnostic Regulation transition timelines that reshape laboratory validation requirements. Industrial clusters around Heidelberg and Berlin anchor specialized diagnostics development, with regional laboratories competing on turnaround time for complex molecular assays.
United Kingdom
National Health Service trusts in London and the Southeast build centralized genomics laboratory hubs to process specialized testing for distributed hospital networks. NHS England's genomic medicine service contracts determine regional laboratory access and reimbursement frameworks for rare disease diagnostics. The Cambridge-Oxford-London triangle concentrates next-generation sequencing infrastructure development, with academic-industry partnerships accelerating assay validation timelines.
Japan
University hospitals in the Kanto region around Tokyo deploy comprehensive genomic profiling for cancer patients under national health insurance coverage expansion. The national pharmaceutical and medical device agency reviews laboratory-developed oncology companion diagnostics through structured consultation pathways. The Osaka-Kobe industrial corridor hosts specialized reagent suppliers and precision medicine research consortia that support clinical laboratory infrastructure.
India
Corporate hospital chains in Maharashtra and Karnataka establish accredited molecular diagnostics laboratories to retain specialized testing revenue domestically. The national pharmaceutical regulator's medical device rules classify certain LDT categories under risk-based registration requirements that affect commercialization timelines. Hyderabad and Bengaluru concentrate bioinformatics service providers and contract research organizations that support validation studies for regional diagnostic developers.
Laboratory Developed Tests Market Key Industry Players
Premium-margin players sit above commodity-margin players across test complexity tiers, with comprehensive genomic profiling and specialized oncology assays commanding superior positioning against routine infectious disease panels. The market structure stratifies between integrated health system laboratories with captive demand, national reference laboratories with broad assay menus, and technology-anchored specialists with platform-specific expertise. Three archetypes dominate: academic medical center laboratories leveraging regulatory infrastructure, commercial reference laboratories competing on scale and turnaround time, and liquid biopsy specialists focused on blood-based cancer monitoring. Consolidation through health system mergers and strategic partnerships between laboratories and technology vendors reshapes competitive boundaries.
Within the integrated health system tier, Mayo Clinic Laboratories and ARUP Laboratories exemplify academic medical center models that convert clinical expertise into reference service offerings. Guardant Health occupies a specialization position anchored in liquid biopsy technology. These three entities represent distinct competitive vectors—captive network leverage, esoteric test depth, and platform-specific innovation—that define strategic positioning across customer segments.
| Leading Market Players |
|---|
| Mayo Clinic Laboratories |
| Guardant Health |
| Labcorp |
| Roche |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Exact Sciences |
| Illumina |
| ARUP Laboratories |
| Others |
Cost & Logistics Intelligence
Next-generation sequencing platform consolidation is simultaneously compressing per-test cost economics and concentrating bargaining power among a handful of California and Massachusetts-based instrument manufacturers. This technology shift forces laboratories to absorb capital-intensive platform commitments while navigating reagent pricing that scales with test volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates academic medical center reference laboratories from regional hospital labs and high-volume commercial processors. Price differentiation hinges on CLIA high-complexity certification tier and interpretive service bundling. Cost compression in the economy tier is intensifying because integrated health systems are internalizing reference testing volume. Commercial reference laboratories exhibit highest price sensitivity; academic medical centers with captive demand demonstrate lowest sensitivity.
Supply Chain Analysis
Taq polymerase enzymes and sequencing flow cells rest on concentrated production bases in California, Massachusetts, and selected German industrial clusters. Raw material dependencies include fluorophore-conjugated oligonucleotides, semiconductor-grade sequencing chips, and specialized specimen transport media. Single-source vulnerability characterizes the flow cell supply chain where one manufacturer dominates. Distribution runs through direct vendor contracts with large health systems and regional laboratory distributors serving independent reference sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory Developed Tests markets function as geographic-arbitrage plays where CLIA certification requirements in the United States create cost barriers that European laboratories bypass through EU In Vitro Diagnostic Regulation transition timelines.
For Market Incumbents: Acquire bioinformatics pipeline capabilities to defend against AI-assisted variant interpretation startups threatening manual review revenue. Pursue backward integration into specimen logistics networks to lock in community hospital send-out volume. Liquid biopsy substitution pressure demands preemptive investment in blood-based assay development. For New Entrants and Emerging Players: Capture pharmacogenomic psychiatric medication management panels where preemptive genotyping penetration remains underdeveloped. Direct-to-employer contracting for wellness screening programs offers the most penetrable go-to-market angle, bypassing traditional payer network complexity. For Investors and Strategic Acquirers: Roll-up economics work for regional reference laboratories with CLIA certification across multiple states because health system consolidation is fragmenting commercial reference market share. Five-to-ten year viability favors platforms with FDA premarket submission experience. Watch FDA enforcement discretion withdrawal timelines as the critical inflection signal for validation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Submission Pathway | Positions oncology companion diagnostics for reimbursement stability under evolving FDA oversight frameworks. |
| CLIA High-Complexity Certification Expansion | Enables next-generation sequencing assay deployment in community hospital laboratories previously constrained by personnel requirements. |
| AI-Assisted Variant Interpretation Integration | Reduces manual review burden for rare variant classification while compressing turnaround times. |
| Direct-to-Employer Contracting | Bypasses traditional payer networks for wellness screening programs with self-insured employers. |
| Interpretive Service Unbundling | Disrupts traditional reference laboratory relationships by selling variant classification as standalone consultative products. |
Research Approach
Coverage spans the United States, Germany, United Kingdom, Japan, and India, with primary inputs from each geography combining structured interviews with laboratory directors, regulatory affairs specialists, health system procurement officers, and bioinformatics pipeline architects. Secondary validation draws from FDA 510(k) filings, CMS CLIA certification databases, EU MDR transition guidance documents, and hospital procurement system contracts. Bottom-up test volume estimates triangulate against top-down health system expenditure analysis.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the analysis window. Segmentation dimensions modeled include product type complexity tier, technology platform capital intensity, end-user consolidation status, and application maturity curve. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns in academic medical centers, with inputs from companion diagnostic approval timelines and CLIA personnel qualification expansion rates.
FDA enforcement discretion withdrawal timing, EU MDR implementation delays, and health system merger acceleration are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
LIMS Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Pathology Services Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Sera and Reagents Market