
 Ophthalmic Examination Chairs Market | 2026-2036
Ophthalmic Examination Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Examination Chairs Market Intelligence
Chinese component manufacturing is consolidating as the dominant supply base for motorized lift mechanisms and steel framing used in ophthalmic seating. Takagi Seiko Co., Ltd. leverages its precision engineering heritage to dominate high-end electric chair production for Japanese and Southeast Asian markets. Topcon Corporation anchors its position through integrated diagnostic workstation ecosystems that bundle examination chairs with imaging systems. Haag-Streit Group specializes in premium surgical chairs designed for laser procedure compatibility, competing on clinical workflow integration rather than price.
Ophthalmic examination chairs are height-adjustable patient seating systems engineered for ocular diagnostic and therapeutic procedures, typically incorporating electric or hydraulic actuation for supine positioning within 90 to 180 degrees and load capacities exceeding 150 kilograms. These systems serve primary eye care delivery by enabling slit-lamp biomicroscopy, fundus examination, and minor surgical interventions without patient transfer. Electric chairs command the dominant share of product type revenue due to reimbursement alignment with procedural efficiency metrics in hospital outpatient departments. Integrated lighting technology within the technology dimension captures expanding interest as clinics seek to reduce capital equipment footprints. Pediatric ophthalmology application segments are outpacing routine eye exams in growth velocity, driven by school screening program expansions and early-intervention protocols.
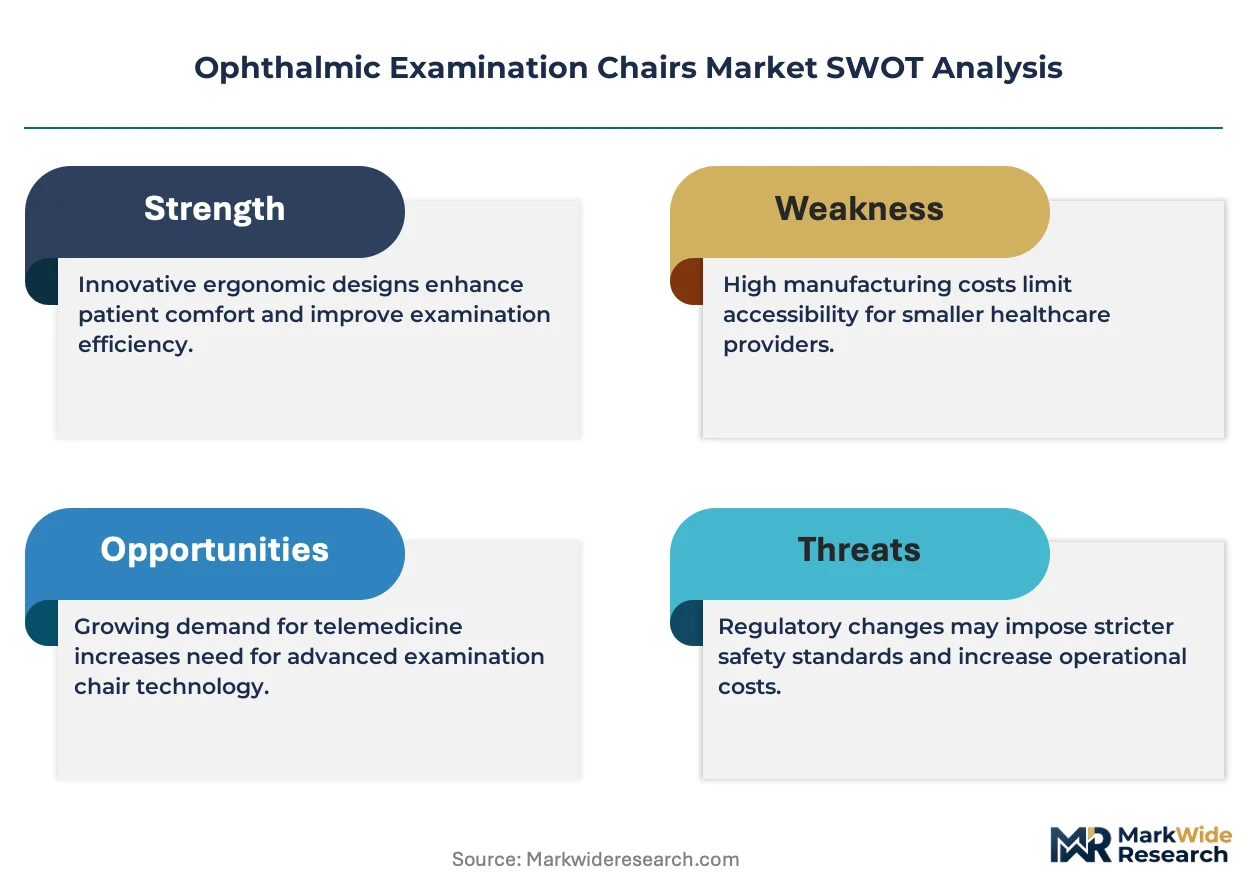
FDA 510(k) clearance requirements govern powered chair safety interlocks and electromagnetic compatibility for devices marketed in the United States, while EU MDR technical documentation obligations extend conformity assessment burdens for European Economic Area access. ISO 13485 quality management certification functions as a de facto market access threshold for contract manufacturing relationships with branded device firms. Stakeholders must monitor evolving cybersecurity guidance from regulators as chair-integrated diagnostic networks become standard in connected clinic environments.
Market Dynamics
EU MDR conformity obligations and FDA 510(k) clearance pathways are compressing product development timelines for powered examination systems, forcing manufacturers to front-load certification costs while ambulatory surgical centers accelerate procurement of electric chairs with integrated diagnostic interfaces.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient ophthalmology facilities in Germany and Japan are replacing hydraulic systems with powered examination chairs to align with procedural efficiency metrics and reimbursement optimization.
- EU MDR technical documentation requirements:Stricter conformity assessment obligations for European Economic Area access are filtering out non-compliant suppliers and consolidating demand around certified manufacturers with established quality management systems.
- Pediatric screening program mandates:School-based early-intervention protocols in multiple jurisdictions are driving specialized chair configurations with child-appropriate dimensions and safety interlocks.
Market Restraints
- Steel and aluminum input volatility:Framing material costs for motorized lift mechanisms fluctuate with commodity markets, compressing margin buffers for mid-tier manufacturers without captive supply arrangements.
- Chinese component supply concentration:Motorized actuation systems and precision-engineered lift assemblies source predominantly from East Asian manufacturing clusters, exposing procurement timelines to geopolitical friction and logistics disruption.
- Electromagnetic compatibility certification burden:FDA electromagnetic interference testing requirements for powered chairs with integrated diagnostic networks extend development cycles and raise capital barriers for new entrants.
Strategic Opportunities
- Connected clinic infrastructure convergence:Diagnostic workstation ecosystems bundling examination chairs with imaging systems and lighting modules are capturing premium positioning in Japanese and Southeast Asian markets.
- Indian ophthalmology network expansion:Specialized clinic chains in tier-2 and tier-3 cities present underpenetrated demand for mid-range electric chairs with localized service support.
- Cybersecurity guidance anticipation:Early alignment with evolving FDA and EU guidance on networked medical device security creates differentiation for manufacturers ahead of formalized mandates.
Industry Challenges
- ISO 13485 quality management implementation:Contract manufacturing relationships with branded device firms require certification timelines that strain smaller suppliers' administrative capacity and audit readiness.
- Legacy hydraulic system integration:Clinic infrastructure with existing non-electric chairs faces capital-intensive retrofitting to accommodate networked diagnostic workflows and positioning automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Examination Chairs Market |
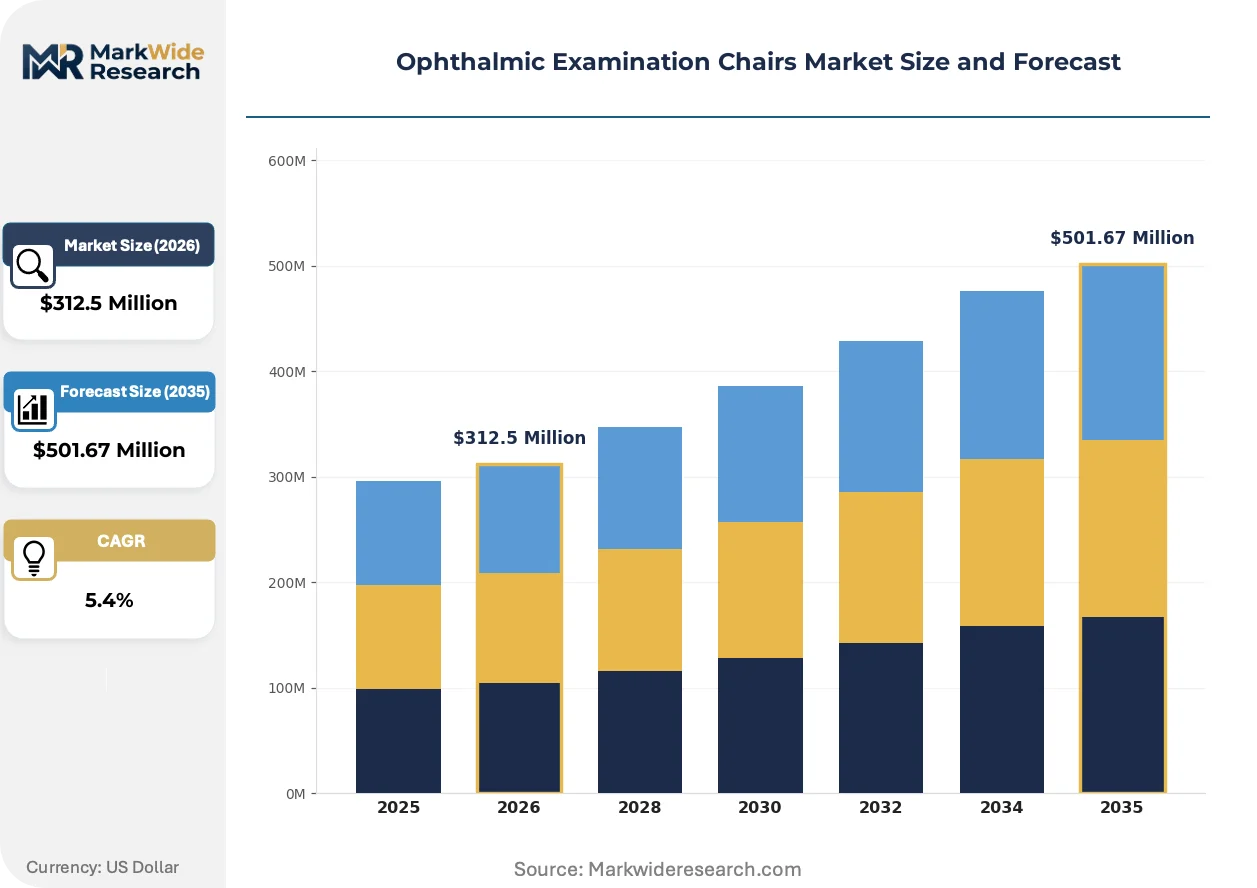
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Hydraulic Technology: Adjustable Height, Rotating Base, Integrated Lighting, Ergonomic Design Application: Routine Eye Exams, Surgical Procedures, Pediatric Ophthalmology, Optometry Clinics End User: Eye Care Centers, Vision Therapy Clinics, Specialty Clinics, Private Practices |
| Companies Covered | Takagi Seiko Co., Ltd., bon Optic Vertriebsgesellschaft mbH, Topcon Corporation, Lemi Group, BTC SRL, Haag-Streit Group, S4OPTIK, Frastema Srl, Coburn Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Examination Chairs Market Strategic Shifts & Innovations
Examination chair architecture is converging with diagnostic imaging and illumination systems, compressing capital equipment footprints while regulatory frameworks harden cybersecurity and electromagnetic compatibility requirements for networked clinical environments.
Integrated LED illumination modules with adjustable color temperature and intensity controls are decentralizing the traditional separation between patient seating and standalone slit-lamp lighting systems. Ambulatory surgical centers and specialized ophthalmology clinics in Germany and Japan are adopting these converged configurations to reduce equipment clutter and streamline procedural workflows. This consolidation is compressing demand for discrete lighting capital goods while elevating chair-integrated technology specifications as a procurement criterion.
EU MDR post-market surveillance obligations and FDA cybersecurity guidance drafts are tightening documentation requirements for powered chairs with network-connected diagnostic interfaces. Manufacturers must now maintain technical files spanning electromagnetic compatibility, software validation, and vulnerability management across the device lifecycle. High-end electric chair segments in European and North American markets are responding by embedding security-by-design architectures and over-the-air update capabilities during initial product development.
Hospital outpatient departments are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party maintenance providers or in-house biomedical engineering teams for powered chair upkeep. This disintermediation pressures traditional manufacturer revenue models dependent on service attach rates. The pattern is most pronounced in United States healthcare systems where procurement autonomy has concentrated among centralized supply chain functions seeking operational cost transparency.
Ophthalmic Examination Chairs Market Segmentation
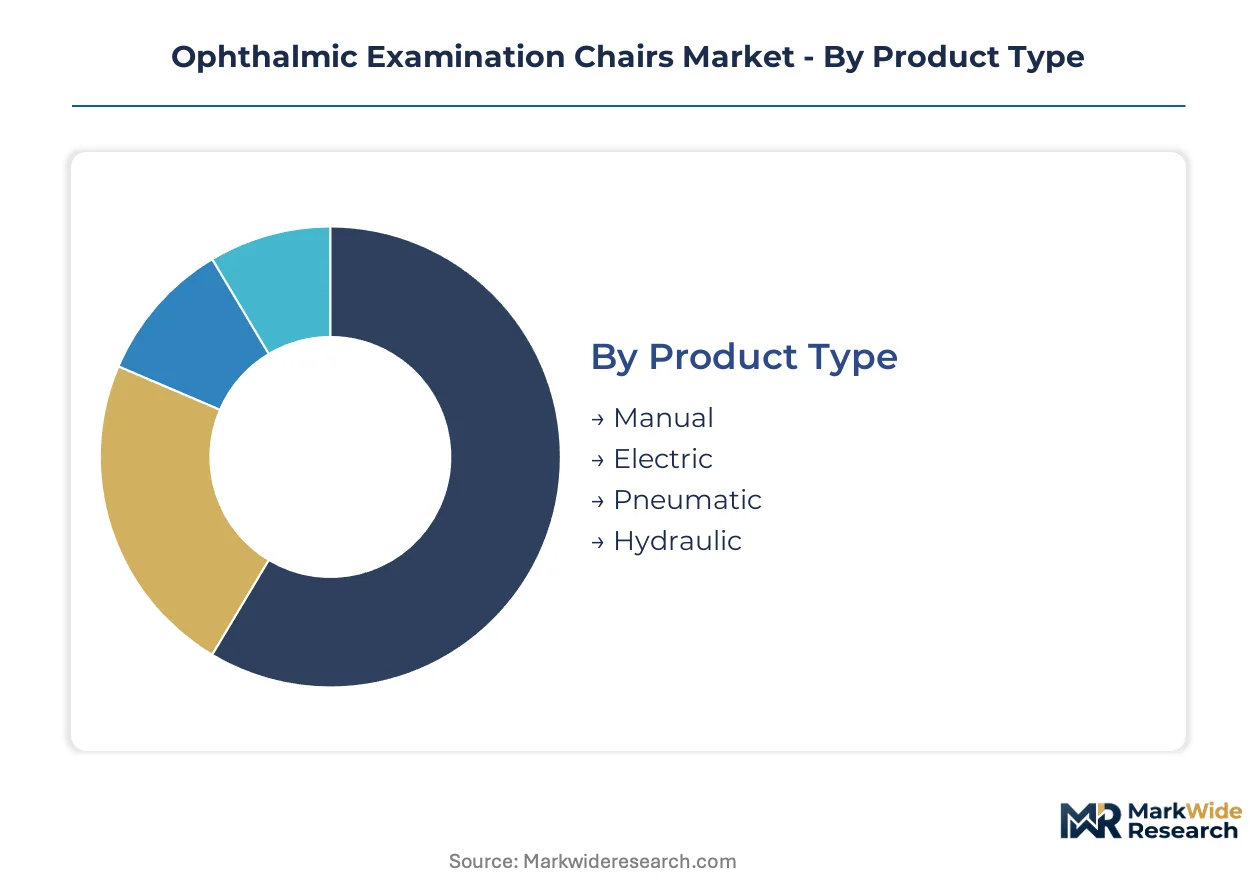
Segmentation reveals how certification burdens concentrate in powered systems while manual alternatives serve cost-sensitive procurement. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
FDA 510(k) clearance requirements apply strictly to powered actuation systems, while manual configurations face lighter documentation burdens. EU MDR technical files for electric chairs must span electromagnetic compatibility and safety interlock validation across the device lifecycle.
- Manual:Hand-crank or lever-operated height adjustment with fixed base positioning. Procurement concentrates in rural Indian and Southeast Asian private practices where capital constraints override workflow efficiency demands. No powered certification requirements reduce market entry barriers for regional fabricators.
- Electric:Motorized lift mechanisms enabling programmable positioning memory and supine articulation. German ambulatory surgical centers and Japanese specialized clinic networks drive replacement demand for premium configurations with integrated diagnostic interfaces. FDA electromagnetic interference testing and EU MDR conformity assessment extend development timelines and front-load certification costs.
- Pneumatic:Gas-spring assisted height adjustment with manual lock mechanisms. Budget-conscious eye care centers in tier-2 Indian cities favor these for intermediate positioning capability without full electric infrastructure requirements.
- Hydraulic:Fluid-pressure lift systems with foot-pedal operation. Legacy installed base dominates Latin American and Middle Eastern markets where service infrastructure for electric systems remains underdeveloped.
Electric chairs sit at the top of the volume ranking, with Pediatric Ophthalmology configurations climbing the fastest.
Technology:
Cost tier stratification separates premium integrated systems from standalone mechanical features. High-end procurement in Germany and Japan bundles multiple technologies while emerging markets prioritize single-function reliability.
- Adjustable Height:Vertical travel range typically spanning 50-70 centimeters to accommodate standing and seated practitioner positions. Universal requirement across all market tiers with electric actuation commanding price premiums in hospital outpatient departments.
- Rotating Base:360-degree swivel capability with locking detents at standard examination angles. Surgical procedure applications in Japanese clinics demand precision bearing systems with minimal maintenance intervals.
- Integrated Lighting:LED illumination modules with adjustable color temperature and intensity controls embedded in chair architecture. German specialized ophthalmology clinics adopt these converged configurations to reduce capital equipment footprints and streamline slit-lamp biomicroscopy workflows. EU MDR technical documentation must now cover optical safety and thermal management alongside mechanical specifications.
- Ergonomic Design:Contoured cushioning with pressure distribution mapping and lumbar support articulation. Pediatric ophthalmology applications drive specialized configurations with child-appropriate dimensions and enhanced safety interlocks.
Adjustable Height maintains the broadest installed base, with Integrated Lighting gaining share fastest in premium procurement.
Application:
Volume concentration in routine diagnostics contrasts with margin expansion in specialized interventions. Reimbursement alignment varies sharply across procedure categories.
- Routine Eye Exams:Standard positioning for slit-lamp biomicroscopy and fundus examination without surgical preparation. High patient throughput requirements in United States hospital outpatient departments favor electric chairs with programmable positioning memory.
- Surgical Procedures:Supine articulation to 180 degrees with laser procedure compatibility and sterile field maintenance. Haag-Streit Group and comparable specialists compete on clinical workflow integration rather than price in this premium tier. FDA 510(k) clearance pathways impose extended electromagnetic compatibility validation for powered systems used in laser environments.
- Pediatric Ophthalmology:Reduced-scale dimensions with enhanced safety interlocks and child-appropriate upholstery materials. School screening program expansions across multiple jurisdictions are accelerating procurement of specialized configurations with rapid height adjustment for varying patient sizes.
- Optometry Clinics:Refraction-focused positioning with emphasis on patient comfort during extended examination sequences. Private practice consolidation in India is driving mid-range electric chair demand with localized service support requirements.
Routine Eye Exams command the largest procedure volume, with Pediatric Ophthalmology expanding most quickly.
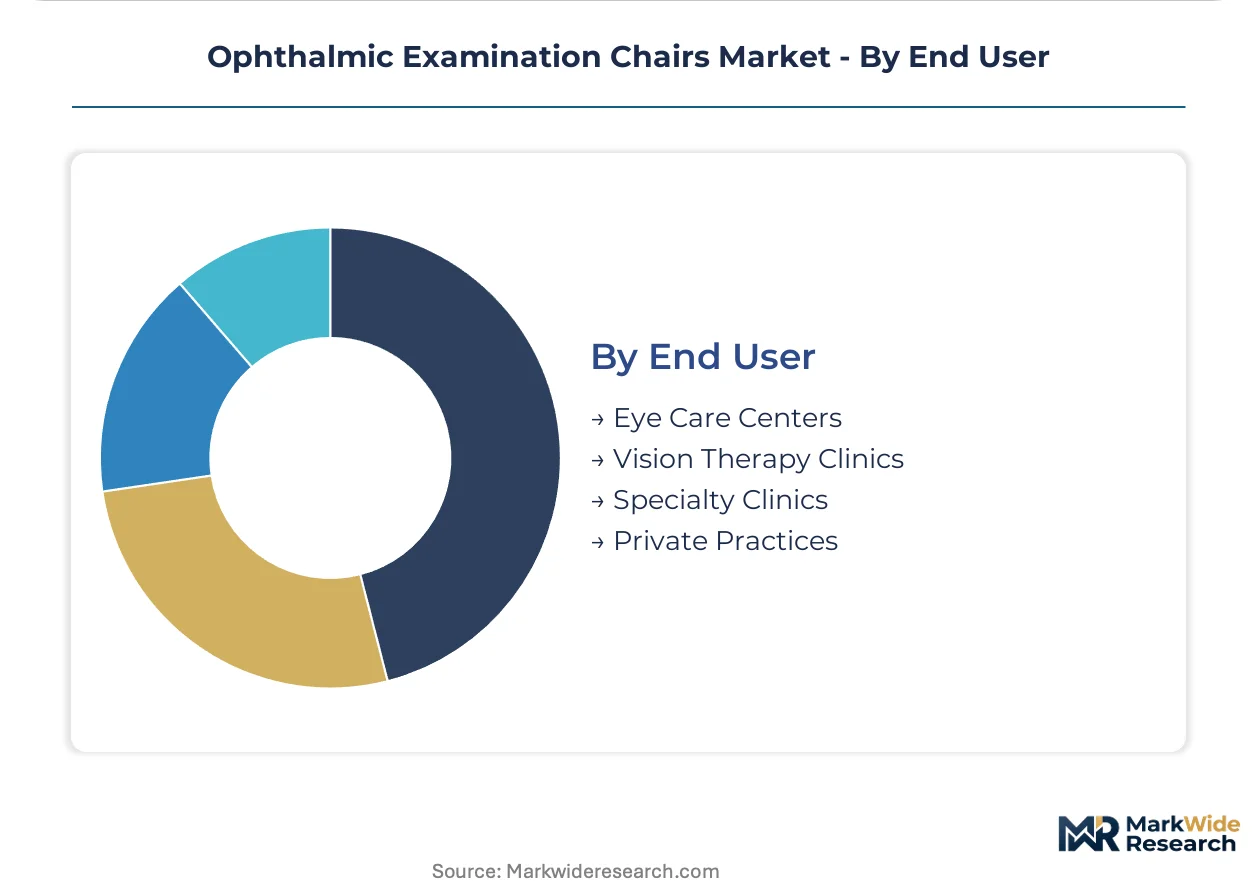
End User:
Customer type determines service contract structure and replacement cycle timing. Institutional procurement centralization contrasts with fragmented private practice decision-making.
- Eye Care Centers:Multi-practitioner facilities with centralized capital budgeting and standardized equipment protocols. United States healthcare systems with supply chain autonomy are unbundling after-sales service contracts toward third-party maintenance providers.
- Vision Therapy Clinics:Rehabilitation-focused settings requiring extended patient positioning durations. Ergonomic design specifications prioritize pressure distribution and adjustability for therapeutic session comfort.
- Specialty Clinics:Concentrated ophthalmology networks in Germany and Japan driving replacement cycles for premium electric chairs with integrated diagnostic interfaces. EU MDR post-market surveillance obligations tighten documentation requirements for these high-value installations.
- Private Practices:Individual practitioner ownership with capital constraints and extended equipment lifecycles. Manual and pneumatic systems retain significant share in rural and emerging market contexts.
Eye Care Centers represent the dominant procurement channel, with Specialty Clinics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek cost-of-compliance advantages outside stringent FDA and EU MDR jurisdictions. Chinese component suppliers capture motorized lift mechanism contracts while Japanese and German producers absorb premium-tier certification burdens.
United States
FDA 510(k) clearance pathways for powered examination chairs compress development timelines for domestic manufacturers serving hospital outpatient departments. Electromagnetic compatibility testing requirements for networked diagnostic interfaces raise capital barriers for new entrants. The Greater Boston and Pacific Northwest clusters concentrate procurement decision-making among centralized healthcare supply chain functions.
Germany
Specialized ophthalmology clinic networks in Bavaria and North Rhine-Westphalia drive replacement cycles for premium electric chairs with integrated diagnostic capabilities. EU MDR post-market surveillance obligations tighten documentation requirements for manufacturers accessing the European Economic Area. Baden-Württemberg engineering clusters supply precision bearing systems for rotating base mechanisms.
Japan
Kanto and Kansai regional markets exhibit concentrated demand for high-end electric chairs bundled within diagnostic workstation ecosystems. METI industrial standards and PMDA quality system requirements shape certification pathways for domestic producers. Tokyo-based precision engineering heritage anchors premium-tier manufacturing for Southeast Asian export markets.
China
Yangtze River Delta and Pearl River Delta manufacturing clusters dominate motorized actuation system supply for global chair assembly. NMPA device registration requirements and GB standards compliance create dual-track certification obligations for domestic market access. Component fabricators in Shenzhen and Suzhou consolidate supply relationships with branded device firms lacking captive production.
India
Tier-2 and tier-3 city ophthalmology networks in Maharashtra and Karnataka present underpenetrated demand for mid-range electric chairs with localized service support. CDSCO medical device rules and BIS quality certification requirements are tightening import substitution pressures. Delhi-NCR and Tamil Nadu clusters emerge as assembly locations for regional market distribution.
Ophthalmic Examination Chairs Market Key Industry Players
Japanese producers anchor the premium-tier segment; Chinese fabricators hold mid-range supply; European specialists maintain certification-heavy positioning for EU market access. Market structure exhibits moderate consolidation around integrated diagnostic workstation providers and precision-engineering heritage firms. Three archetypes dominate: ecosystem bundlers combining chairs with imaging systems, component specialists supplying lift mechanisms to branded assemblers, and regional fabricators serving cost-sensitive procurement. Competitive moves concentrate on strategic partnerships for diagnostic network integration and backward integration into motorized actuation manufacturing.
Within the precision-engineering tier, Takagi Seiko Co., Ltd. and Haag-Streit Group exemplify Japanese and Swiss heritage positioning respectively. Topcon Corporation occupies the ecosystem-bundler archetype through diagnostic workstation integration. These three firms represent contrasting strategic postures: component mastery, surgical-procedure specialization, and full-system convergence.
| Leading Market Players |
|---|
| Takagi Seiko Co., Ltd. |
| bon Optic Vertriebsgesellschaft mbH |
| Topcon Corporation |
| Lemi Group |
| BTC SRL |
| Haag-Streit Group |
| S4OPTIK |
| Frastema Srl |
| Coburn Technologies |
| Others |
Cost & Logistics Intelligence
Integrated LED illumination modules embedded directly into chair architecture are compressing capital equipment footprints while simultaneously elevating material cost structures and concentrating procurement leverage among Japanese and German precision-engineering clusters. This convergence reshapes both manufacturing economics and supplier power dynamics across premium and mid-market tiers.
Pricing Analysis
Distributor margins on electric examination chairs compress as hospital outpatient departments in the United States unbundle after-sales service contracts and shift toward third-party maintenance providers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared powered systems with electromagnetic compatibility validation from manual configurations serving rural Indian private practices. Pricing pressure stems from Chinese component supply concentration in motorized lift mechanisms, with cost compression in mid-tier electric chairs intensifying as steel and aluminum input volatility squeezes margin buffers. Pediatric ophthalmology clinics demonstrate lowest price sensitivity due to reimbursement alignment with early-intervention protocols, while tier-2 Indian optometry networks exhibit highest sensitivity to capital equipment outlays.
Supply Chain Analysis
India's phased domestic-content mandates under CDSCO medical device rules and BIS quality certification requirements are reshaping sourcing patterns for regional assembly operations. Motorized actuation systems and precision-engineered lift assemblies draw predominantly from Yangtze River Delta and Pearl River Delta manufacturing clusters in China, with secondary sourcing from Baden-Württemberg engineering clusters in Germany for rotating base mechanisms. Steel framing, aluminum extrusions, and LED illumination modules constitute critical input dependencies. Single-source vulnerability in Chinese motor-controller supply exposes procurement timelines to geopolitical friction and logistics disruption. Distribution runs through specialized ophthalmology equipment distributors in developed markets and direct-to-clinic sales teams in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ophthalmic examination chairs market represents a late-cycle quality story as ambulatory surgical centers and specialized clinic networks in Germany and Japan accelerate replacement demand toward premium electric configurations with integrated diagnostic interfaces and programmable positioning memory.
For Market Incumbents: Cement defensive positioning through backward integration into motorized lift mechanism manufacturing and captive supply of precision bearing systems for rotating base assemblies. The threat of emerging Chinese component fabricators upgrading to branded assembly operations demands immediate ISO 13485 quality management certification investment and EU MDR technical documentation readiness. Channel control through exclusive diagnostic workstation bundling with Topcon Corporation-style ecosystem integration serves as the priority defensive lever.
For New Entrants and Emerging Players: Direct-to-specialist-clinic digital procurement platforms offer a low-friction entry route into underpenetrated tier-2 and tier-3 Indian ophthalmology networks seeking mid-range electric chairs with localized service support. Pediatric ophthalmology applications present the most penetrable segment given school screening program expansions and specialized configuration requirements that established players have not fully addressed. A go-to-market angle emphasizing rapid height adjustment for varying patient sizes and child-appropriate safety interlocks differentiates against legacy hydraulic system incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with ISO 13485 certification and established relationships with branded device firms lacking captive production. Long-term viability hinges on regulatory compliance scalability across FDA 510(k) and EU MDR pathways rather than pure manufacturing scale. Acquisition targets should display embedded security-by-design architectures for networked diagnostic interfaces. The signal to watch is FDA cybersecurity guidance formalization, which will abruptly revalue compliant manufacturers against laggards.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Front-loaded certification costs filter non-compliant suppliers and consolidate demand around quality-certified manufacturers. |
| Diagnostic Workstation Ecosystem Bundling | Topcon Corporation-style integration of examination chairs with imaging systems captures premium positioning in Japanese markets. |
| Backward Integration into Motorized Actuation | In-house production of lift mechanisms reduces exposure to Chinese component supply concentration and geopolitical friction. |
| Pediatric Configuration Specialization | Child-appropriate dimensions and enhanced safety interlocks align with school screening program procurement mandates. |
| Third-Party Maintenance Partnership | United States hospital systems unbundling service contracts create recurring revenue streams independent of capital equipment sales. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ophthalmology clinic directors, hospital purchasing committee members, biomedical engineering managers, GPO contracts administrators, and regulatory affairs specialists at device manufacturers with secondary validation. FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, hospital procurement databases, and GPO contract filings anchored the secondary foundation. Bottom-up segment sizing and top-down market reconciliation ensured analytical robustness across modeling approaches.
Segment-weighting approaches distributed value and volume estimates across product type, technology integration level, application procedure category, and end-user facility archetype throughout the forecast period. CAGRs derived from regression analysis of replacement cycle timing, reimbursement alignment shifts, and regulatory compliance cost trajectories. Procedure efficiency metrics in hospital outpatient departments and pediatric screening program expansion rates served as industry-specific demand drivers in the projection framework.
The model assumes a particular technology adoption path; alternative pathways for networked diagnostic interface integration would alter the outlook if cybersecurity guidance delays or reimbursement disincentives emerge. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and Chinese component supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market