
 Passwordless Authentication Market | 2026-2036
Passwordless Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Passwordless Authentication Market Intelligence
Healthcare and government agency adoption is broadening as ransomware attacks on legacy credential systems intensify. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor enterprise transitions toward FIDO2-compliant architectures. Okta Inc. competes through cloud-native identity orchestration that reduces deployment friction for mid-market buyers. Thales Group specializes in hardware-backed biometric modules that serve defense and critical infrastructure operators requiring offline verification resilience.
Passwordless authentication eliminates static credentials through cryptographic key pairs, biometric templates, or one-time tokens bound to registered devices, typically operating at false acceptance rates below 0.001% for enterprise-grade facial recognition. Its primary commercial purpose is to sever the attack surface exploited by phishing, credential stuffing, and brute-force intrusions while streamlining user access workflows. Biometric technology leads current deployments due to consumer familiarity with fingerprint and facial unlock patterns, though FIDO2 standards are capturing fastest growth as browser and operating system native support eliminates client-side software dependencies. Cloud-based delivery models concentrate margin pools through recurring subscription structures, while on-premise installations retain traction among financial services entities subject to data sovereignty requirements.
The National Institute of Standards and Technology (NIST) Special Publication 800-63B shapes U.S. federal procurement by deprecating knowledge-based authentication, while the EU AI Act imposes conformity assessments on biometric inference systems deployed across European member states. The UK's National Cyber Security Centre reinforces this trajectory through zero-trust architecture guidance that mandates phishing-resistant authenticators for sensitive access tiers. Stakeholders must monitor evolving liability frameworks around biometric data breaches and algorithmic bias litigation as these determine insurability terms and vendor selection criteria.
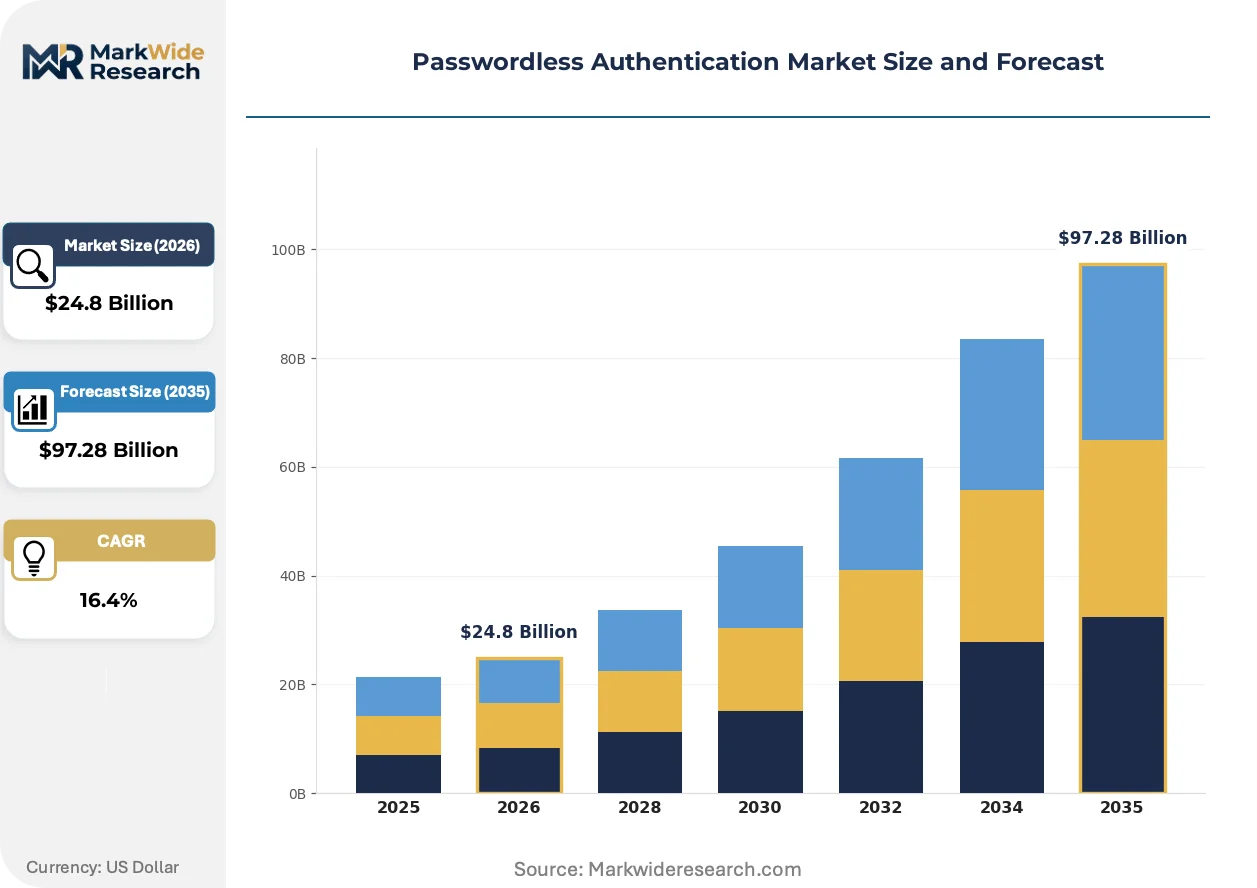
Market Dynamics
The migration toward FIDO2 standards is compressing deployment timelines as browser-native cryptographic support eliminates client-side software dependencies that previously anchored enterprises to legacy credential architectures.
Growth Catalysts
- EU AI Act Conformity Assessments:Biometric inference systems deployed across European member states now face mandatory algorithmic audits, creating procurement pull for certified vendors and accelerating replacement of unverified legacy authentication stacks.
- Zero-Trust Federal Mandates:United States government agencies are deprecating knowledge-based authentication under NIST Special Publication 800-63B, forcing phishing-resistant authenticator adoption across defense and civilian networks.
- Healthcare Ransomware Exposure:Legacy credential breaches in hospital systems are driving biometric and token-based authentication procurement as institutions seek to sever attack surfaces exploited by credential-stuffing intrusions.
Market Restraints
- Hardware Security Module Costs:FIDO2-compliant deployments requiring dedicated cryptographic processors face elevated capital outlays that compress margins for mid-market buyers lacking enterprise-scale procurement leverage.
- Biometric Template Storage Concentration:Cloud-based identity providers in the United States control critical infrastructure for template encryption and revocation, creating single-point-of-failure exposure for multinational enterprises.
- Algorithmic Bias Litigation Risk:Facial recognition systems exhibiting elevated false rejection rates for specific demographic cohorts face insurability premium spikes and vendor liability exposure under emerging tort frameworks.
Strategic Opportunities
- Japan's Critical Infrastructure Modernization:METI-guided zero-trust mandates for energy and transportation operators create demand for offline-capable biometric modules that function during network segmentation events.
- Converged Physical-Logical Access:Smart card and mobile credential fusion is converging with building access control systems, enabling unified identity orchestration across corporate campuses and remote work endpoints.
- Germany's Data Sovereignty Requirements:Financial services entities subject to BaFin oversight are procuring on-premise FIDO2 deployments that retain cryptographic material within national borders, bypassing cross-border data transfer restrictions.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:FIDO2 protocol implementation requires specialized expertise in public-key infrastructure and secure enclave architecture that remains concentrated among a limited vendor pool.
- Legacy Directory Integration Complexity:Enterprises maintaining Active Directory forests face protracted migration timelines as conditional access policies must be rearchitected to support passwordless authentication flows.
- Cross-Border Certification Fragmentation:Biometric systems must satisfy divergent conformity assessment procedures across the EU AI Act, NIST frameworks, and Japan's PIPA amendments, elongating product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passwordless Authentication Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $97.28 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, FIDO2, OTP, Email Link Delivery Model: Cloud-based, On-Premise, Hybrid, Managed Service Application: Financial Services, E-commerce, Healthcare, Education End User: Small Enterprises, Large Corporations, Government Agencies, Non-Profit |
| Companies Covered | Microsoft Corporation, Okta Inc., Ping Identity, Duo Security, Thales Group, HID Global Corporation, NEC Corporation, Yubico, Auth0, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passwordless Authentication Market Strategic Shifts & Innovations
Authentication architectures are shedding static credential dependencies as cryptographic key pairs bound to registered devices displace knowledge-based verification across enterprise and consumer contexts.
Passkey technology is converging with device-bound biometric verification to eliminate shared secrets from authentication flows. Financial services institutions in Germany and the United States are deploying FIDO2 credentials at scale, replacing SMS one-time passwords and hardware token fleets. This convergence is compressing time-to-authentication while severing phishing attack vectors that previously exploited credential reuse patterns.
The EU AI Act's risk-based classification system is imposing conformity assessments on biometric inference systems deployed across European member states. High-risk authentication applications now require algorithmic impact documentation and human oversight protocols. Healthcare and border control operators in France and the Netherlands are restructuring procurement specifications to preempt regulatory enforcement actions.
Buyer preference is rotating toward consumption-based identity service models that unbundle perpetual licensing from operational support. Mid-market enterprises in Japan and the United States are adopting monthly active user pricing structures that align vendor compensation with actual authentication volume. This shift is displacing upfront capital expenditure models that previously locked buyers into multi-year maintenance commitments.
Passwordless Authentication Market Segmentation
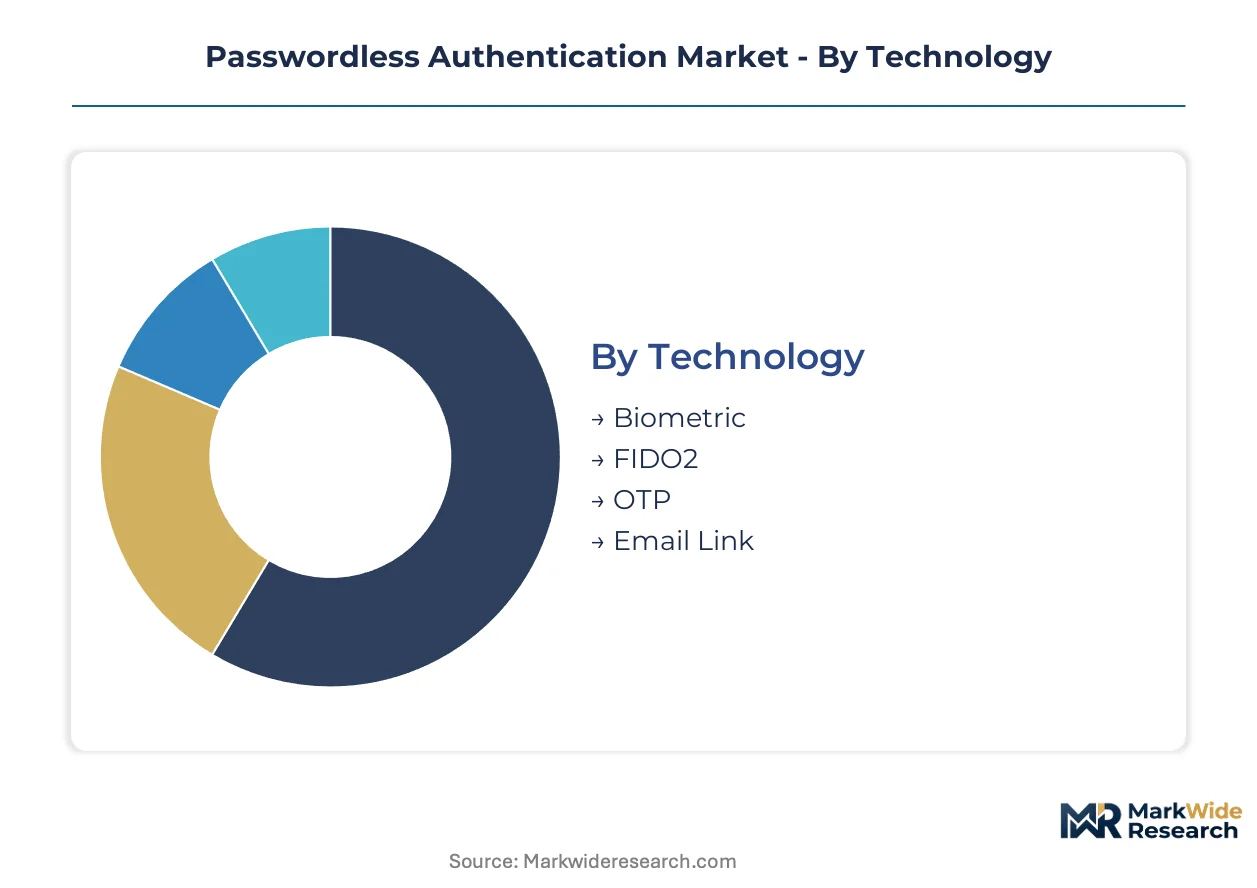
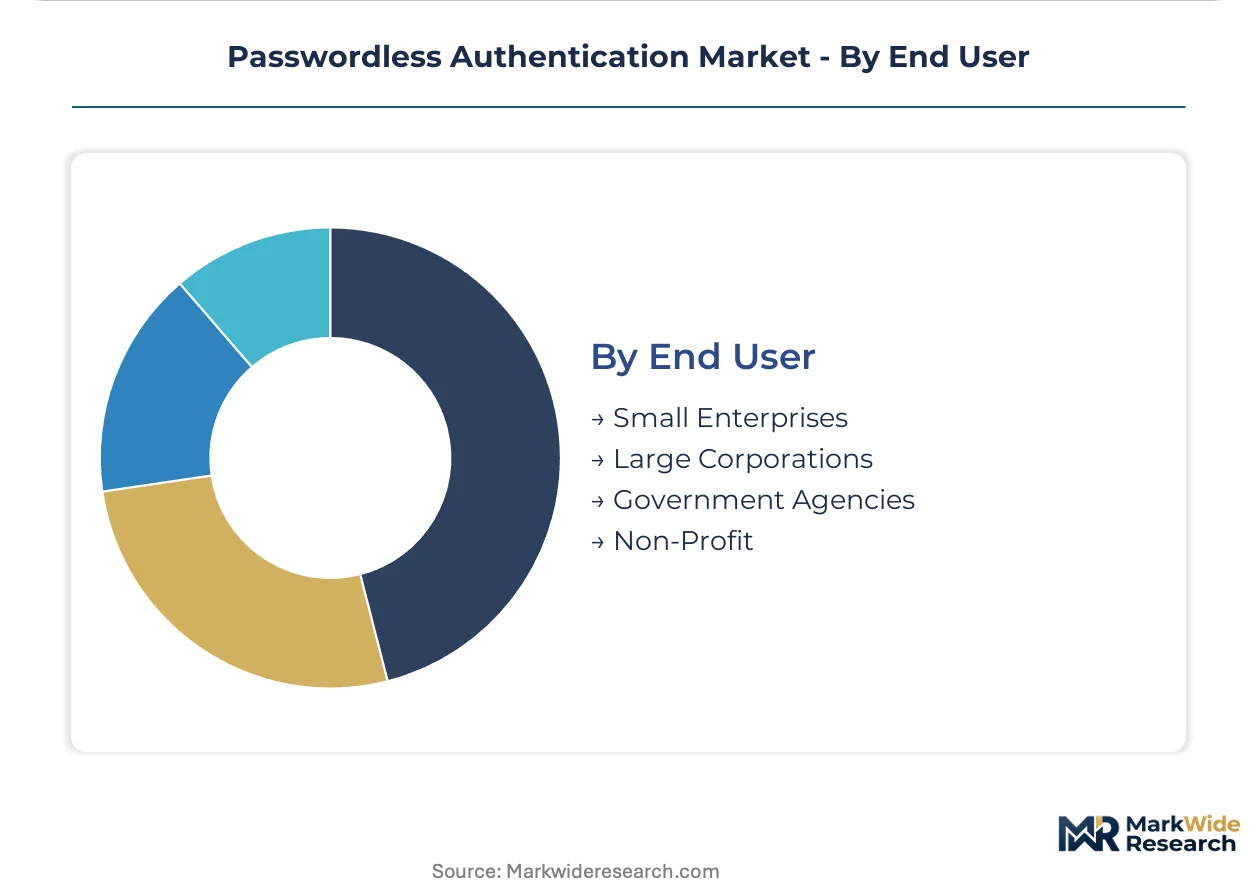
Passwordless authentication deployments fragment across technology maturity, infrastructure control requirements, and regulatory exposure. Each segment carries distinct procurement patterns, integration complexity, and vendor selection criteria that shape commercial outcomes.
Technology:
Standardization pressure from FIDO Alliance specifications compresses differentiation at the protocol layer while biometric modalities retain customization through sensor hardware and algorithm tuning.
- Biometric:Fingerprint, facial, and iris recognition systems bind identity verification to physiological characteristics stored as encrypted templates. Healthcare networks in the United States deploy these modalities to satisfy HIPAA audit requirements for workforce access. False rejection rate sensitivity drives procurement toward multimodal systems that combine fingerprint with facial capture.
- FIDO2:Public-key cryptography eliminates shared secrets through asymmetric key pairs generated and stored within device secure enclaves. Browser-native support from Chrome, Safari, and Edge accelerates enterprise rollout timelines. German financial institutions under BaFin oversight favor FIDO2 for cross-border transaction authentication that satisfies PSD2 strong customer authentication mandates.
- OTP:Time-synchronized or event-based one-time codes transmitted through SMS, voice, or authenticator applications. SMS OTP faces deprecation under NIST SP 800-63B guidance due to SIM-swapping vulnerabilities.
- Email Link:Cryptographic tokens embedded in time-limited hyperlinks delivered to registered addresses. Consumer-facing e-commerce platforms favor this modality for guest checkout flows with minimal friction.
Most installed capacity flows through Biometric systems. Expansion is steepest in FIDO2.
Delivery Model:
Control over cryptographic material and identity metadata determines whether buyers absorb operational burden or delegate to specialized providers.
- Cloud-based:Subscription access to identity orchestration platforms with vendor-managed infrastructure and automatic protocol updates. Mid-market enterprises in Japan adopt this model to bypass capital expenditure constraints and accelerate deployment timelines.
- On-Premise:Dedicated hardware and software installations within buyer-controlled data centers retaining all authentication logs and biometric templates. German financial services entities subject to data sovereignty requirements procure on-premise FIDO2 deployments that prevent cross-border data transfer exposure.
- Hybrid:Split architectures that process high-risk authentication events on-premise while routing standard access through cloud infrastructure. United States federal agencies deploy hybrid models to satisfy FedRAMP authorization tiers while maintaining classified network isolation.
- Managed Service:Outsourced operation of authentication infrastructure with service-level agreements governing uptime, incident response, and compliance attestation. Healthcare systems facing ransomware exposure contract managed services to access specialized security operations center capabilities without internal staffing.
Cloud-based deployments concentrate revenue volume. Hybrid architectures gain share fastest among regulated industries.
Application:
Threat surface severity and transaction value density create divergent authentication intensity requirements across vertical markets.
- Financial Services:Real-time payment authorization, trading system access, and customer account protection demand phishing-resistant authenticators. United States banks under FFIEC guidance deploy biometric and FIDO2 systems to replace knowledge-based authentication deprecated by NIST frameworks.
- E-commerce:Checkout friction reduction competes with fraud prevention as merchants balance conversion optimization against chargeback exposure. European retailers adapt to Strong Customer Authentication requirements under PSD2 by implementing biometric verification for high-value transactions.
- Healthcare:Patient record access, medical device authentication, and telemedicine session validation face intensified ransomware targeting. Hospital systems procure passwordless systems to sever credential-stuffing attack vectors.
- Education:Campus-wide identity management spanning learning management systems, dormitory access, and library resources. University procurement prioritizes student device diversity support over high-assurance verification.
Financial Services commands the largest procurement budgets. Healthcare demonstrates the steepest expansion trajectory.
End User:
Scale economies and compliance exposure stratify vendor engagement models from self-service deployment to bespoke integration.
- Small Enterprises:Organizations with under 500 employees lacking dedicated identity infrastructure teams. Cloud-native solutions with pre-configured connectors to Microsoft 365 and Google Workspace dominate this segment.
- Large Corporations:Multi-national entities with heterogeneous technology estates requiring unified identity orchestration across legacy and modern applications. These buyers negotiate enterprise licensing with professional services for Active Directory forest migration.
- Government Agencies:Civilian and defense entities subject to zero-trust mandates and classified information handling requirements. United States agencies procure FIDO2-compliant authenticators under NIST SP 800-63B guidance.
- Non-Profit:Resource-constrained organizations prioritizing donor data protection and volunteer access management. Grant-funded security initiatives drive adoption of subsidized cloud authentication services.
Large Corporations absorb the majority of vendor professional services capacity. Government Agencies expand procurement most aggressively under federal mandate pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cybersecurity cluster drives early-stage FIDO2 innovation and venture deployment. Federal zero-trust mandates across civilian agencies accelerate procurement timelines. Biometric hardware manufacturers concentrate in Shenzhen and Seoul, supplying sensor modules to global integrators.
United States
Defense contractors and financial institutions dominate enterprise procurement, with NIST SP 800-63B compliance driving phishing-resistant authenticator replacement cycles. The Cybersecurity and Infrastructure Security Agency enforces zero-trust architecture deadlines through 2027. Seattle hosts Microsoft's Azure identity engineering teams developing passkey infrastructure for federal cloud environments.
Germany
BaFin-regulated banks under PSD2 strong customer authentication mandates favor on-premise FIDO2 deployments with data sovereignty guarantees. The EU AI Act's conformity assessment framework imposes algorithmic audit requirements on biometric inference systems. Frankfurt's financial services cluster anchors procurement for hardware-backed authentication modules serving cross-border payment networks.
Japan
METI-guided critical infrastructure operators modernize energy and transportation access control under zero-trust directives. Amendments to the Personal Information Protection Act tighten biometric data handling standards for enterprise deployments. Tokyo's identity technology vendors supply offline-capable modules to nuclear facilities and rail operators requiring network-segmentation resilience.
United Kingdom
The National Cyber Security Centre mandates phishing-resistant authenticators for sensitive government tiers through zero-trust architecture guidance. NHS Digital procurement prioritizes biometric workforce access systems to mitigate ransomware exposure against legacy credential stores. London's fintech cluster drives FIDO2 adoption for open banking authentication flows.
South Korea
Financial Services Commission oversight accelerates FIDO2 deployment for internet banking and mobile payment authorization. The Personal Information Protection Commission enforces strict biometric template encryption standards for cloud identity providers. Seoul's semiconductor fabricators manufacture secure enclave processors embedded in enterprise-grade authentication hardware.
Passwordless Authentication Market Key Industry Players
Strategic partnership formation dominates the current landscape as vendors bundle identity orchestration with cloud infrastructure commitments. The vendor base stratifies across three tiers: hyperscale platform operators with directory integration depth, hardware specialists with secure element manufacturing capabilities, and cloud-native challengers with API-first deployment models. Competitive positioning hinges on FIDO Alliance certification velocity and FedRAMP authorization status for federal eligibility. Vertical integration into cryptographic processor design and biometric sensor fabrication represents the dominant capability-building trajectory.
Within the hyperscale platform tier, Microsoft Corporation and Okta Inc. anchor enterprise identity migration toward passwordless architectures. Thales Group occupies a position among hardware-backed security specialists serving defense and critical infrastructure operators with offline verification requirements. These three entities exemplify divergent strategic archetypes: cloud-native subscription scaling, directory-integrated ecosystem lock-in, and sovereign-grade hardware resilience.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Okta Inc. |
| Ping Identity |
| Duo Security |
| Thales Group |
| HID Global Corporation |
| NEC Corporation |
| Yubico |
| Auth0 |
| Others |
Cost & Logistics Intelligence
Backward integration into secure enclave processor design anchors both supply security and pricing power for authentication hardware vendors serving defense and financial services buyers. Microsoft and Thales control captive manufacturing of cryptographic modules that insulate margins from semiconductor foundry volatility while commanding premium positioning against software-only competitors.
Pricing Analysis
Input-cost pass-through from secure element chip shortages runs through hardware-backed authentication tiers, compressing margins for FIDO2 security key manufacturers dependent on Taiwanese foundry capacity. Three-tier pricing structure across FedRAMP-authorized premium, enterprise-standard, and mid-market economy levels separates buyers by compliance certification and deployment scale. Pricing pressure stems from cloud-native challengers offering consumption-based identity orchestration that undercuts perpetual license models. Small enterprises exhibit highest price sensitivity, while United States federal agencies absorb premium tiers under zero-trust mandate deadlines.
Supply Chain Analysis
Dual-sourcing requirements from United States defense contractors mandate qualified secondary suppliers for hardware security modules, elongating vendor onboarding timelines. Manufacturing concentrates in Taiwan, South Korea, and China for biometric sensors and secure enclave processors. Raw material dependencies span rare earth elements for sensor fabrication, cryptographic-grade silicon substrates, and FIDO Alliance certification testing services. Single-source vulnerability concentrates in Taiwanese semiconductor foundries serving hardware authentication module producers. Distribution runs through direct enterprise sales teams for federal and financial services accounts, supplemented by cloud marketplace integrations for mid-market SaaS delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The passwordless authentication market functions as a stable compounder, with regulatory mandate timelines across United States federal agencies and European conformity assessments creating predictable procurement visibility.
For Market Incumbents: Deepen FIDO Alliance certification velocity to maintain federal eligibility against emerging cloud-native challengers. Invest in captive secure element manufacturing to offset foundry cost volatility and defend hardware margin tiers. Prioritize Active Directory forest migration tooling to accelerate enterprise deployment timelines and reduce customer switching flexibility.
For New Entrants and Emerging Players: Begin with biometric inference systems for healthcare mid-market buyers facing ransomware exposure but lacking enterprise procurement leverage. Target Japan's critical infrastructure operators under METI zero-trust directives, where offline-capable modules face limited domestic competition. Pursue API-first deployment models that bypass legacy directory integration complexity.
For Investors and Strategic Acquirers: Roll-up economics work for regional identity orchestration specialists because fragmented mid-market procurement patterns prevent national-scale vendor concentration. Five-to-ten year viability hinges on FedRAMP authorization moats and biometric algorithm audit capabilities. Monitor NIST framework revision cycles as inflection indicators for replacement demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Certification Acceleration | FedRAMP authorization unlocks United States federal procurement pipelines under CISA zero-trust deadlines. |
| Biometric Algorithm Audit Investment | EU AI Act conformity assessment capability captures European healthcare and border control procurement. |
| Secure Element Manufacturing Scale-Up | Captive foundry relationships insulate margins from Taiwanese semiconductor supply volatility. |
| Active Directory Migration Tooling | Conditional access policy automation compresses enterprise deployment timelines and reduces churn. |
| Consumption-Based Pricing Launch | Monthly active user models align vendor compensation with authentication volume and displace perpetual licenses. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand calibration. The research combines structured interviews with CISOs, identity infrastructure architects, federal procurement officers, and biometric systems integrators with secondary validation from NIST publications, FIDO Alliance deployment statistics, SEC filings of publicly traded vendors, and EU regulatory impact assessments. Bottom-up authentication volume estimates triangulate against top-down security software spending benchmarks.
Rate-of-change decomposition separates technology substitution effects from net-new enterprise adoption across the analysis window. Segmentation dimensions include technology modality, delivery model, application vertical, and end-user scale tier, with additional modeling of regulatory compliance intensity by geography. CAGRs derive from fitted adoption curves against mandate implementation timelines, incorporating hardware shipment data and cloud identity service revenue disclosures as industry-specific inputs.
Several conditions sit outside the modeled scope, including catastrophic biometric data breaches, algorithmic bias litigation outcomes, and sovereign data localization policy shifts. Forecasts assume continued browser-native FIDO2 support and stable cross-border data transfer frameworks. Deviation in NIST framework revision timing or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
DNS Protection Software Market
Security Software
Business Email Compromise (BEC) Market
Security Software
AI in Security Market
Security Software
Software Assurance Market
Security Software
Smart Video Doorbell Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Global Network Encryption Market
Security Software
US Evidence Management Market
Security Software
US Hardware Encryption Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Global Electronic Passports Market
Security Software
Global Data Breach Notification Software Market
Security Software
ATM Security Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Global Security Software in Telecom Market
Security Software
Global Wireless Intrusion Prevention System Market