
 Global Electronic Passports Market | 2026-2036
Global Electronic Passports Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Passports Market Analysis
Software-defined personalization platforms is pivoting the value proposition from hardware delivery to continuous identity-service contracts. Thales Group leverages its aerospace and defense heritage to anchor large-scale government deployments across multiple continents. IDEMIA competes through integrated biometric enrollment-to-issuance systems that reduce vendor fragmentation for immigration agencies.
An electronic passport embeds a contactless integrated circuit chip storing biometric and biographical data, compliant with ICAO Doc 9303 and ISO/IEC 7501 standards, designed to authenticate traveler identity at automated border control gates. Biometric passports lead issuance volumes as governments mandate facial-recognition interoperability with existing airport infrastructure. Fingerprint recognition technology sustains premium positioning where civil registries demand multi-modal biometric enrollment against national ID databases.
ICAO sets the baseline technical framework for machine-readable travel documents, while ETSI and national regulators such as BIS in India enforce country-specific chip and antenna performance certifications. The EU Entry/Exit System and comparable programs in other regions mandate biometric verification at external borders, directly expanding replacement cycles for legacy document stocks. Stakeholders must monitor which governments bundle e-passport procurement with national digital identity platforms, as this integration pattern reshapes vendor selection criteria and contract structures.
Market Dynamics
Biometric enrollment infrastructure is consolidating vendor relationships as immigration agencies demand end-to-end identity systems rather than discrete document procurement. This shift from hardware transactions to service contracts restructures contract durations and margin profiles across the value chain.
Growth Catalysts
- EU Entry/Exit System:The biometric verification mandate at external borders forces member states to replace legacy document stocks, creating sustained replacement demand through 2035.
- India:The BIS certification framework for chip and antenna performance drives standardization that accelerates procurement cycles for biometric-enabled civil registry systems.
- Contactless integrated circuit technology:Facial-recognition interoperability requirements at automated border control gates expand deployment volumes across Southeast Asian modernization programs.
Market Restraints
- Semiconductor supply concentration:Secure element fabrication concentrates among a limited set of certified foundries, creating bottlenecks for ICAO-compliant chip sourcing.
- ICAO Doc 9303 compliance costs:The technical harmonization framework imposes expensive certification cycles that extend time-to-revenue for new market entrants.
- Digital identity substitution:Mobile travel credentials and wallet-based identity verification threaten physical document issuance volumes in premium traveler segments.
Strategic Opportunities
- Indonesia:Underpenetrated civil registry infrastructure creates whitespace for integrated biometric enrollment-to-issuance system deployment.
- Software-defined personalization:Cloud-based personalization platforms enable recurring service revenue models that displace one-time hardware sales.
- Multi-modal biometric convergence:Fingerprint and facial recognition combination systems open premium positioning against national ID database integration requirements.
Industry Challenges
- Embedded systems security engineering:Scarce talent pools for secure operating system development on contactless smart cards constrain product pipeline velocity.
- Legacy immigration IT integration:Decades-old border control databases require expensive middleware development to achieve real-time biometric verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Passports Market |
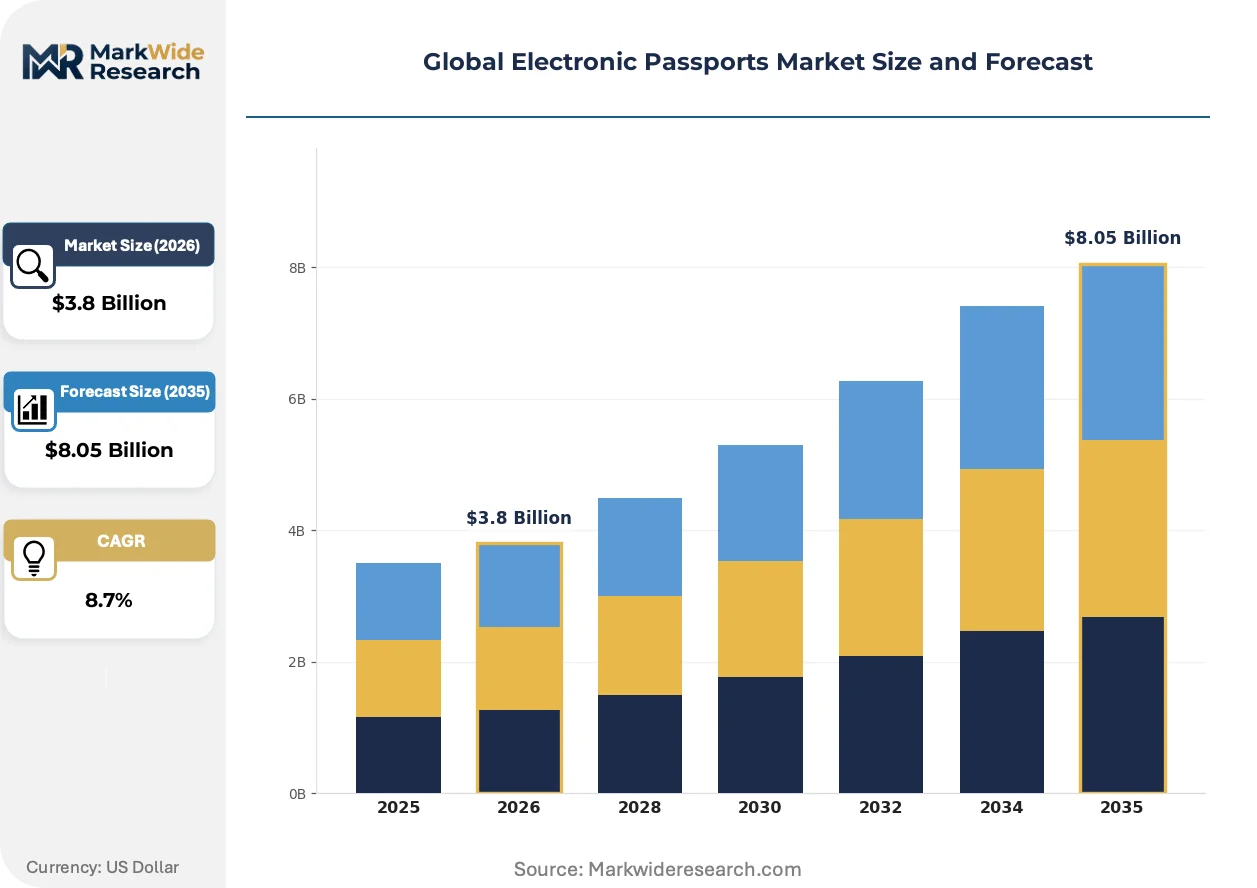
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
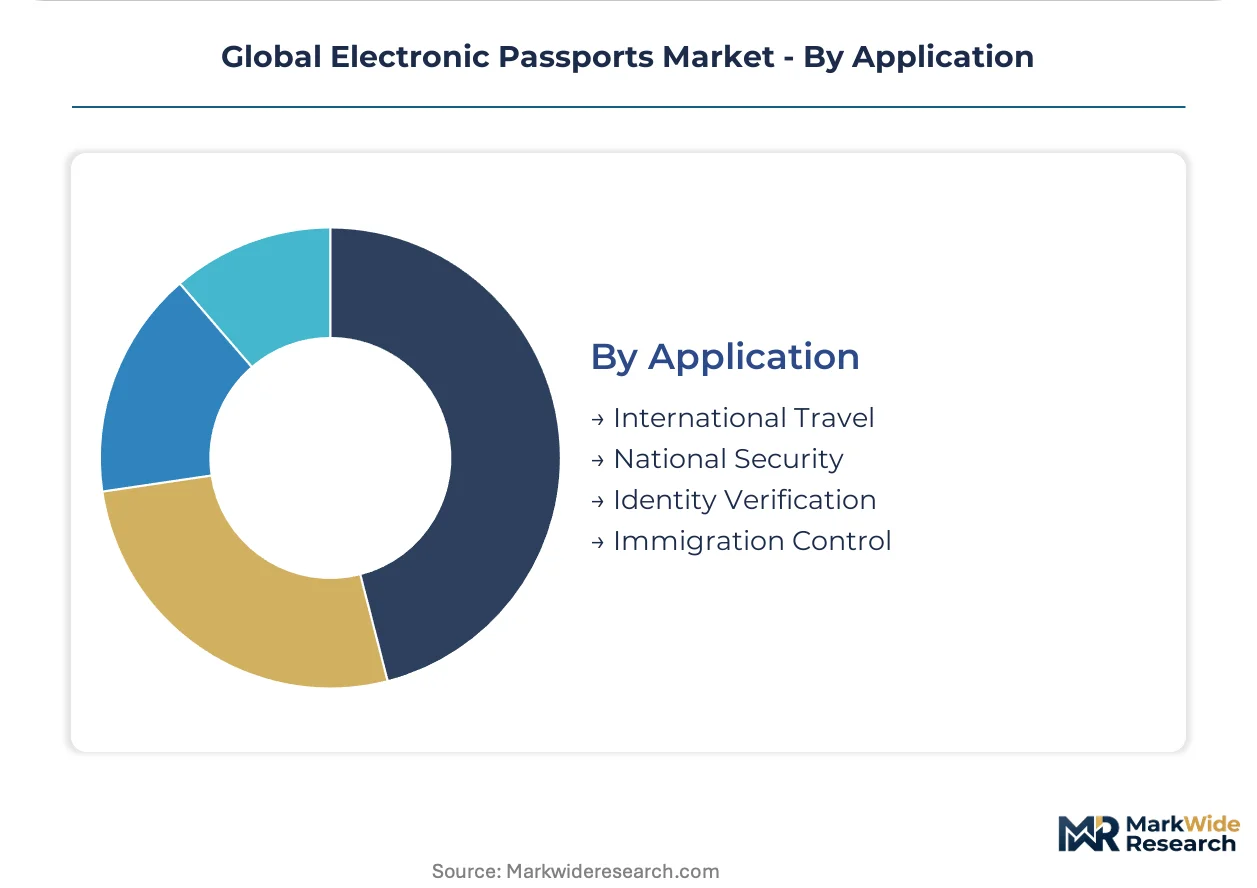
| Segmentation | Product Type: Smart Card, Biometric Passport, E-Visa, RFID Tag Technology: Optical Character Recognition, Fingerprint Recognition, RFID, Biometric Encryption End User: Government Agencies, Airlines, Border Control Authorities, Travel Agencies Application: International Travel, National Security, Identity Verification, Immigration Control |
| Companies Covered | IDEMIA, Thales Group, Mühlbauer Group, Entrust Corporation, HID Global Corporation, Infineon Technologies AG, Safran, Eastcompeace Technology Co., Ltd., 4G Identity Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Passports Market Emerging Trajectories
Document personalization is migrating from centralized printing facilities to distributed issuance points, enabled by portable biometric enrollment kits and secure cloud connectivity. This decentralization reshapes logistics, security protocols, and vendor service architectures.
Polycarbonate data pages with laser-engraved portraits is integrating secondary facial biometric capture directly into the physical substrate, eliminating separate lamination steps. Immigration agencies in Thailand and Vietnam are piloting these consolidated workflows to reduce enrollment station footprint. The technology is integrating document production with field enrollment, compressing total issuance timelines from weeks to days.
ETSI antenna performance standards are tightening electromagnetic compatibility requirements for contactless chip modules, forcing redesigns of inlay manufacturing processes. The industrial consequence is qualification delays for suppliers lacking in-house electromagnetic simulation capabilities. European border control authorities are most affected, responding with extended technical evaluation periods and dual-source procurement strategies.
Service-based contracting is displacing capital expenditure models as finance ministries prioritize operational budget flexibility. Immigration agencies in the Philippines and Malaysia now specify biometric enrollment as a managed service rather than owned infrastructure. This pattern is most visible in emerging economies with constrained upfront fiscal capacity but sustained multi-year identity modernization programs.
Global Electronic Passports Market Segmentation
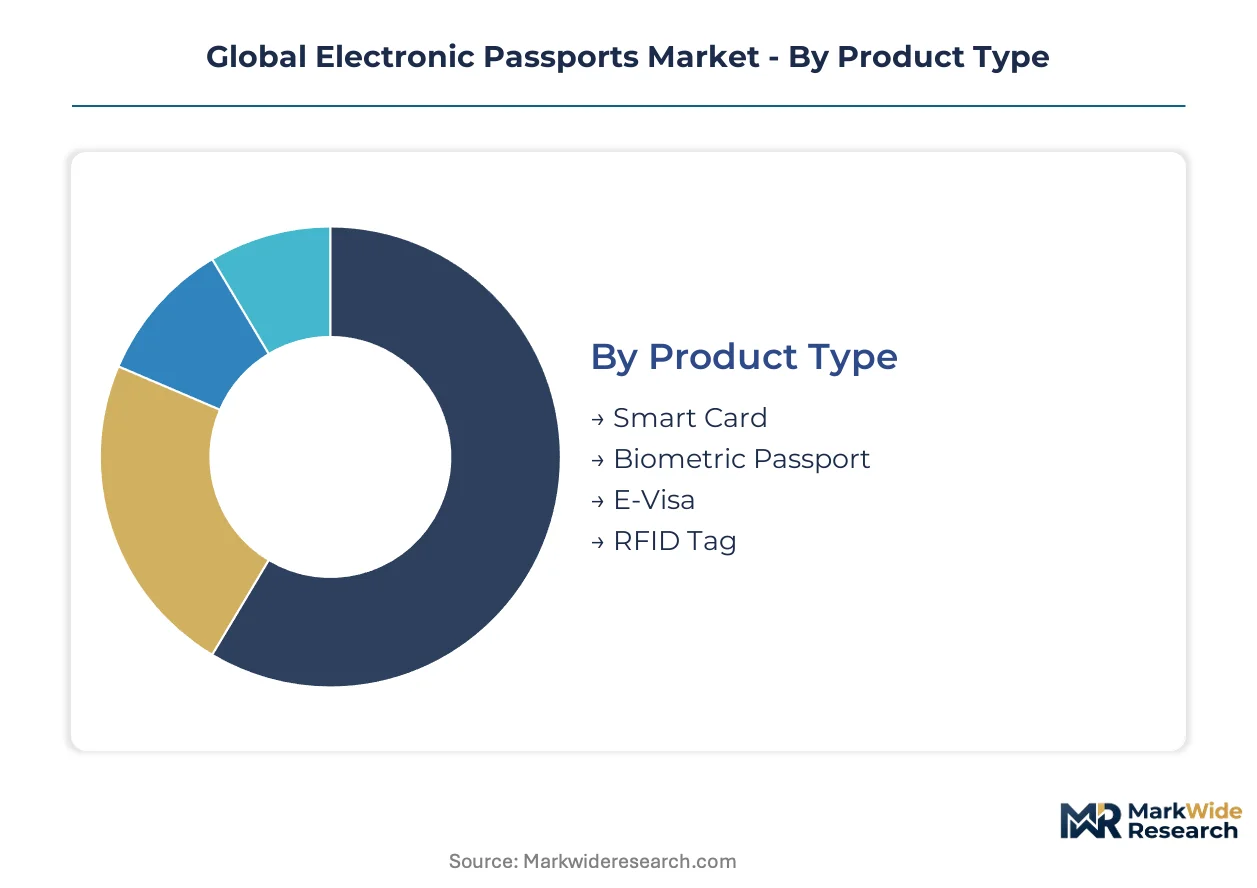
Electronic passport procurement divides sharply between hardware-centric document issuance and service-integrated identity platforms. Vendor selection criteria differ materially across these boundaries, reshaping contract structures and margin profiles throughout the value chain.
Product Type:
Governments prioritize certification depth and interoperability guarantees when selecting document formats for national deployment.
- Biometric Passport:Contactless integrated circuit chips store facial recognition templates and biographical data per ICAO Doc 9303. India and Indonesia drive procurement volumes as civil registry modernization programs mandate facial-recognition interoperability with automated border control infrastructure.
- Smart Card:Multi-application secure elements support both travel document functions and national digital identity convergence. Demand concentrates where finance ministries bundle e-passport procurement with broader citizen service platforms, extending contract durations from one-time hardware sales to recurring service agreements.
- E-Visa:Digital travel authorization systems reduce physical document processing overhead for short-stay visitor categories.
- RFID Tag:Basic contactless identification for limited-functionality travel credentials and temporary document applications.
Volume sits with biometric passports; growth tilts toward smart cards.
Technology:
Technology selection follows border infrastructure maturity and existing biometric database architecture.
- Fingerprint Recognition:Multi-modal enrollment systems capture dermal ridge patterns alongside facial templates for highest-assurance identity verification. Premium positioning persists in markets with established national ID databases requiring cross-referenced biometric matching, particularly where civil registries demand forensic-grade identity assurance.
- Biometric Encryption:Secure cryptographic protocols protect stored templates against cloning and unauthorized extraction. Adoption accelerates where data protection regulators mandate template-level security independent of physical document safeguards.
- RFID:Contactless communication protocols enable automated gate processing at high-throughput border crossings.
- Optical Character Recognition:Legacy machine-readable zone scanning sustains backward compatibility with pre-biometric border infrastructure.
Deployment breadth favors RFID; capability premiums attach to fingerprint recognition.
End User:
Budget authority and technical integration requirements segment buyer behavior across institutional categories.
- Government Agencies:National civil registry and interior ministries control procurement for citizen passport issuance. Contract specifications increasingly mandate end-to-end biometric enrollment-to-issuance systems rather than discrete document manufacturing.
- Border Control Authorities:Immigration agencies at ports of entry drive verification infrastructure investment separate from document production. The EU Entry/Exit System mandates biometric verification at external borders, forcing replacement demand for legacy gate infrastructure.
- Airlines:Carrier-operated document verification at check-in and boarding gates creates secondary demand for portable biometric enrollment kits.
- Travel Agencies:Facilitation services for visa and document processing represent minimal direct technology procurement.
Procurement scale concentrates with government agencies; implementation urgency sits with border control authorities.
Application:
Use case specificity determines performance requirements and certification rigor.
- International Travel:Cross-border document verification demands ICAO Doc 9303 compliance and bilateral recognition agreements. Standardization enforcement through ETSI antenna performance certifications and BIS chip specifications in India accelerates procurement cycles for harmonized document formats.
- National Security:Counter-terrorism and watchlist integration applications require real-time biometric matching against centralized databases. Middleware development costs escalate where legacy immigration IT systems predate modern biometric protocols.
- Identity Verification:Domestic citizen service access extends e-passport infrastructure to non-travel applications.
- Immigration Control:Enforcement-focused document inspection prioritizes forgery resistance over traveler convenience.
Document issuance volume flows through international travel; security premium pricing attaches to national security applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secure element fabrication concentrates in Germany and France, while biometric enrollment system deployment dominates procurement cycles in India and Indonesia. Document personalization services flow toward Southeast Asian civil registry modernization programs.
India
BIS certification mandates for chip and antenna performance accelerate vendor qualification timelines for biometric-enabled passport systems. The national civil registry modernization program drives integrated enrollment-to-issuance procurement. Karnataka's Bangalore cluster hosts technical evaluation centers where electromagnetic compatibility testing occurs for ICAO-compliant document modules.
Germany
ETSI antenna performance standards enforce electromagnetic compatibility requirements that reshape inlay manufacturing specifications. Federal Interior Ministry procurement bundles border control infrastructure with document issuance systems. Munich and Berlin anchor secure element design clusters where semiconductor foundries qualify ICAO-compliant chip architectures.
Indonesia
Civil registry infrastructure gaps create deployment whitespace for portable biometric enrollment kits and cloud-connected personalization platforms. The national identity modernization program mandates facial-recognition interoperability with automated border gates. Jakarta and Surabaya concentrate pilot programs for polycarbonate data page integration with field enrollment workflows.
France
EU Entry/Exit System mandates force replacement demand for legacy document stocks through biometric verification requirements at external borders. National security procurement prioritizes multi-modal biometric systems for watchlist integration. The Paris-Saclay corridor hosts secure operating system development for contactless smart card applications.
Thailand
Immigration agency modernization programs specify managed service contracts for biometric enrollment rather than owned infrastructure. Polycarbonate data page pilots with laser-engraved portraits compress issuance timelines from centralized printing facilities. Bangkok concentrates vendor technical support operations for distributed personalization platform deployment.
Global Electronic Passports Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the value chain. Secure element foundries in Europe anchor hardware supply while software-defined personalization platforms enable recurring service revenue models. The market structures around three archetypes: integrated aerospace-defense conglomerates, specialized biometric enrollment-to-issuance vendors, and semiconductor secure element specialists. Competitive moves concentrate on strategic partnerships for cloud-based service delivery and geographic expansion through managed service contracting in emerging economies.
Within the integrated systems tier, Thales Group and IDEMIA occupy anchor positions representing end-to-end identity platform deployment. Thales exemplifies the aerospace-defense heritage archetype leveraging multi-continent government relationships. IDEMIA sits within the specialized biometric vendor category, its integrated enrollment-to-issuance approach reducing procurement fragmentation for immigration agencies. Among semiconductor specialists, Infineon Technologies AG represents the secure element fabrication archetype where ICAO-compliant chip sourcing concentrates.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| Mühlbauer Group |
| Entrust Corporation |
| HID Global Corporation |
| Infineon Technologies AG |
| Safran |
| Eastcompeace Technology Co., Ltd. |
| 4G Identity Solutions |
| Others |
Supply Flow & Price Mechanics
Government procurement agencies concentrated in India and Southeast Asia negotiate multi-year service contracts that compress hardware margins while elevating recurring revenue streams. This buyer archetype concentration forces vendors toward software-defined personalization platforms that trade upfront document sales for sustained identity-service subscriptions.
Pricing Analysis
Margin tightening in biometric enrollment systems reflects semiconductor supply concentration among ICAO-certified foundries. Three-tier pricing structure across premium multi-modal, standard facial-recognition, and economy RFID-only configurations segments by certification depth and database integration complexity. Cost-down pressure on hardware components accelerates as finance ministries prioritize operational budget flexibility over capital expenditure. Border control authorities prove least price-sensitive due to EU Entry/Exit System mandates, while emerging economy civil registries exhibit highest sensitivity to total cost of ownership.
Supply Chain Analysis
Refurbishment flows for legacy document personalization equipment concentrate in Germany and France where original secure element fabrication clusters anchor reverse logistics networks. Secure microcontroller production draws from German and French semiconductor foundries, with polycarbonate substrate supply tethered to specialized chemical processors in Belgium and the Netherlands. Single-source vulnerability pervades ICAO-compliant chip certification where qualified fabrication capacity concentrates among three European suppliers. Distribution runs through government contracting officers rather than open market channels, extending sales cycles but locking in multi-year revenue visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures intensify as software-defined service models favor scaled platform vendors over discrete hardware specialists, forcing sub-scale document manufacturers toward acquisition or exit.
For Market Incumbents: Cement market position through backward integration into secure element design and captive supply of ICAO-compliant chip architectures. Deepen biometric enrollment service capabilities to capture recurring revenue streams that offset hardware margin compression from government procurement aggregation. Prioritize certification investment in BIS and ETSI frameworks to maintain qualification barriers against emerging competitors. For New Entrants and Emerging Players: EU Entry/Exit System mandates in member states open a window for specialized middleware developers addressing legacy immigration IT integration pain points. Target Indonesia's underpenetrated civil registry infrastructure with portable biometric enrollment kits and cloud-connected personalization platforms. Pursue managed service contracting as the go-to-market angle, positioning operational budget flexibility against incumbent capital-sale models. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light software-defined personalization platforms in Southeast Asia where fiscal constraints accelerate service-model adoption. Five-to-ten year viability hinges on recurring revenue visibility from multi-year government identity modernization programs rather than transactional document volumes. Monitor BIS and ETSI certification queue lengths as inflection indicators for vendor qualification bottlenecks that reshape competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Personalization Platform Deployment | Cloud-based service models displace one-time hardware sales with recurring identity-service contracts. |
| Multi-Modal Biometric Enrollment System Integration | Facial-recognition and fingerprint combination systems capture premium positioning against national ID database requirements. |
| Secure Element Fabrication Capacity Expansion | In-house semiconductor production reduces ICAO-compliant chip sourcing vulnerability from concentrated European foundries. |
| Managed Service Contracting in Emerging Economies | Operational budget flexibility appeals to finance ministries in Indonesia and the Philippines with constrained fiscal capacity. |
| Polycarbonate Data Page Manufacturing Consolidation | Laser-engraved portrait integration compresses issuance timelines from weeks to days for Thailand and Vietnam pilots. |
Methodological Framework
Multi-period observation of biometric enrollment system deployment rates and government procurement contract structures anchored the trend analysis, supplemented by interviews with civil registry program directors, border control IT architects, secure element procurement leads, and identity platform integration specialists. Secondary validation drew from ICAO Doc 9303 implementation reports, BIS certification databases, ETSI electromagnetic compatibility filings, and EU Entry/Exit System technical specifications. Bottom-up vendor shipment tracking and top-down government budget appropriation analysis provided cross-referenced triangulation.
Segment-weighting across biometric passport, smart card, and e-visa product types combined with technology segmentation by fingerprint recognition, RFID, and biometric encryption protocols shaped the analytical framework. End-user weighting distinguished government agency procurement scale from border control authority implementation urgency. CAGRs derived from polynomial trend fitting against historical issuance volumes, with adjustments for replacement cycle acceleration from regulatory mandates. Forecast inputs incorporated ICAO compliance timeline assumptions and semiconductor foundry qualification queue projections.
Caveats apply where semiconductor supply disruptions, ICAO standard revision schedules, or digital identity substitution rates could materially shift the outlook. Practitioners should monitor BIS and ETSI certification backlog indicators, EU Entry/Exit System deployment pace, and mobile travel credential adoption curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Anomaly Detection Tools Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Global User Provisioning Market
Security Software
Key Management Service Market
Security Software
Application Control Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Network Security Appliance Market
Security Software
Global Advanced Authentication Market
Security Software
Global Anti-Spam Software Market
Security Software
Endpoint Security Solutions Market
Security Software
DC and PKI Market
Security Software
Global Security Software in Telecom Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Global Enterprise Key Management Market
Security Software
Communication Encryption Software Market