
 DNS Protection Software Market | 2026-2036
DNS Protection Software Market Size, Share, and Industry Trends Forecast 2026-2036
DNS Protection Software Market Insights
Managed service providers and mid-market enterprises are redrawing the buyer landscape for DNS protection, displacing reliance on traditional IT security procurement channels. Cisco Systems Inc leverages its integrated networking portfolio to anchor DNS security within broader zero-trust architectures. Akamai Technologies dominates edge-based DNS resolution, while Palo Alto Networks competes through native firewall-DNS orchestration.
DNS protection software encompasses systems that intercept, filter, and authenticate domain name resolution requests to prevent cache poisoning, tunneling, and hijacking attacks, typically operating at query volumes exceeding millions of requests per second with sub-millisecond latency requirements. Cloud-based deployment leads in new customer acquisition due to minimal infrastructure overhead and elastic scaling, though hybrid architectures are gaining traction among regulated industries requiring on-premises data sovereignty. Threat intelligence solutions command premium positioning as organizations prioritize predictive blocking over reactive domain blacklisting.
The FCC enforces communications infrastructure reliability standards that implicate DNS availability, while GDPR and the EU AI Act shape how DNS query logs are retained and analyzed for security purposes. ISO 27001 and IEC 62443 certifications increasingly gate enterprise procurement decisions, particularly in energy and manufacturing verticals. Stakeholders must weigh sovereign cloud requirements against the operational simplicity of multi-tenant DNS services as jurisdictional data rules proliferate.
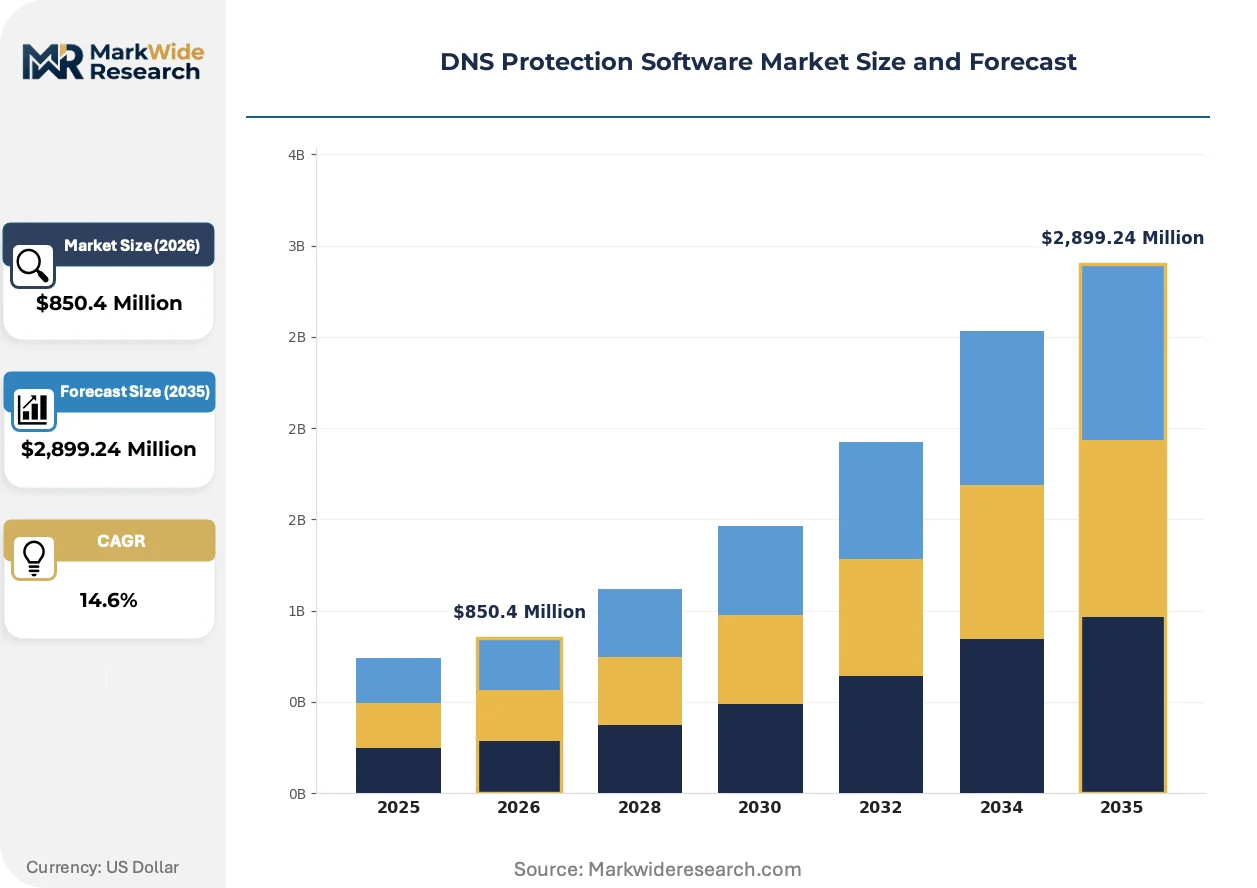
Market Dynamics
Financial services firms and managed service providers are reconfiguring procurement patterns for DNS-layer security, compressing sales cycles and elevating threat intelligence capabilities above hardware-centric defenses. This demand-side rotation is forcing vendors to embed predictive analytics into resolution infrastructure.
Growth Catalysts
- EU NIS2 Directive:The directive mandates DNS infrastructure hardening for essential and important entities across European member states, creating compliance-driven procurement waves in energy, transport, and digital infrastructure sectors.
- Cloud migration architectures:Enterprise shifts to multi-cloud and remote work topologies have expanded DNS query surfaces, elevating DNS protection from network hygiene to critical security control status.
- Ransomware defense prioritization:Financial services institutions now treat DNS-layer filtering as first-line defense against data exfiltration and command-and-control communications, accelerating budget allocation toward resolution security.
Market Restraints
- Skilled operator scarcity:DNS security architecture expertise concentrates among specialized consultants, constraining enterprise deployment velocity and inflating implementation costs.
- Latency-performance tradeoffs:Deep packet inspection and threat intelligence lookup at resolution time introduce microsecond delays that conflict with high-frequency trading and real-time application requirements.
- Data sovereignty fragmentation:Divergent national data localization rules complicate multi-tenant DNS service architectures, forcing redundant infrastructure investment.
Strategic Opportunities
- Edge computing convergence:Integration of DNS protection with 5G edge nodes and IoT gateways opens deployment channels in manufacturing and smart city infrastructure.
- AI-augmented threat prediction:Machine learning models trained on query pattern anomalies enable preemptive blocking of novel tunneling techniques before signature-based systems detect them.
- Mid-market MSP packaging:Bundled DNS security within broader managed security service offerings penetrates under-served professional services and regional healthcare networks.
Industry Challenges
- Legacy resolver integration:Enterprises with BIND or Microsoft DNS investments face complex migration paths to modern filtering architectures without service disruption.
- ISO 27001 certification timelines:Energy and manufacturing procurement committees now gate vendor selection on current certification status, extending sales cycles for uncertified providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNS Protection Software Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $2,899.24 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Managed Services End User: Enterprises, SMBs, Government, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Single Tenant Solution: Threat Intelligence, Malware Protection, Phishing Protection, Firewall Integration |
| Companies Covered | Cisco Systems Inc, Akamai Technologies, DNSFilter Inc., TitanHQ, Infoblox, Comodo Security Solutions, Inc, Open Text Corporation, Palo Alto Networks, F5 Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNS Protection Software Market Trends and Innovations
DNS protection is migrating from standalone appliance deployments toward embedded, intelligence-driven resolution services. This structural shift compresses vendor margins while elevating the strategic value of proprietary threat data.
DNS-over-HTTPS (DoH) and DNS-over-TLS (DoT) encryption protocols are miniaturizing the visibility window that security teams have into outbound queries. Financial institutions and healthcare networks adopting these standards for privacy compliance now demand resolver-integrated inspection to maintain threat detection. The technology is miniaturizing the traditional perimeter-based security model into encrypted transport layers, forcing vendors to deploy client-side agents and recursive resolver co-location.
The EU AI Act imposes algorithmic transparency requirements on automated threat scoring systems used in DNS filtering decisions. Security vendors must now document training data provenance and decision logic for query blocking, particularly when EU citizen data is involved. German and French enterprise buyers are prioritizing vendors with established AI governance frameworks, creating procurement segmentation between compliant and non-compliant providers.
Consumption-based billing for DNS resolution volume is displacing perpetual licensing in mid-market procurement. Managed service providers and SaaS companies prefer per-query pricing that scales with cloud workload expansion, compressing upfront commitment requirements. This pattern is most visible among United States technology firms undergoing cloud-native transformation, where CapEx avoidance drives security tooling selection.
DNS Protection Software Market Segmentation
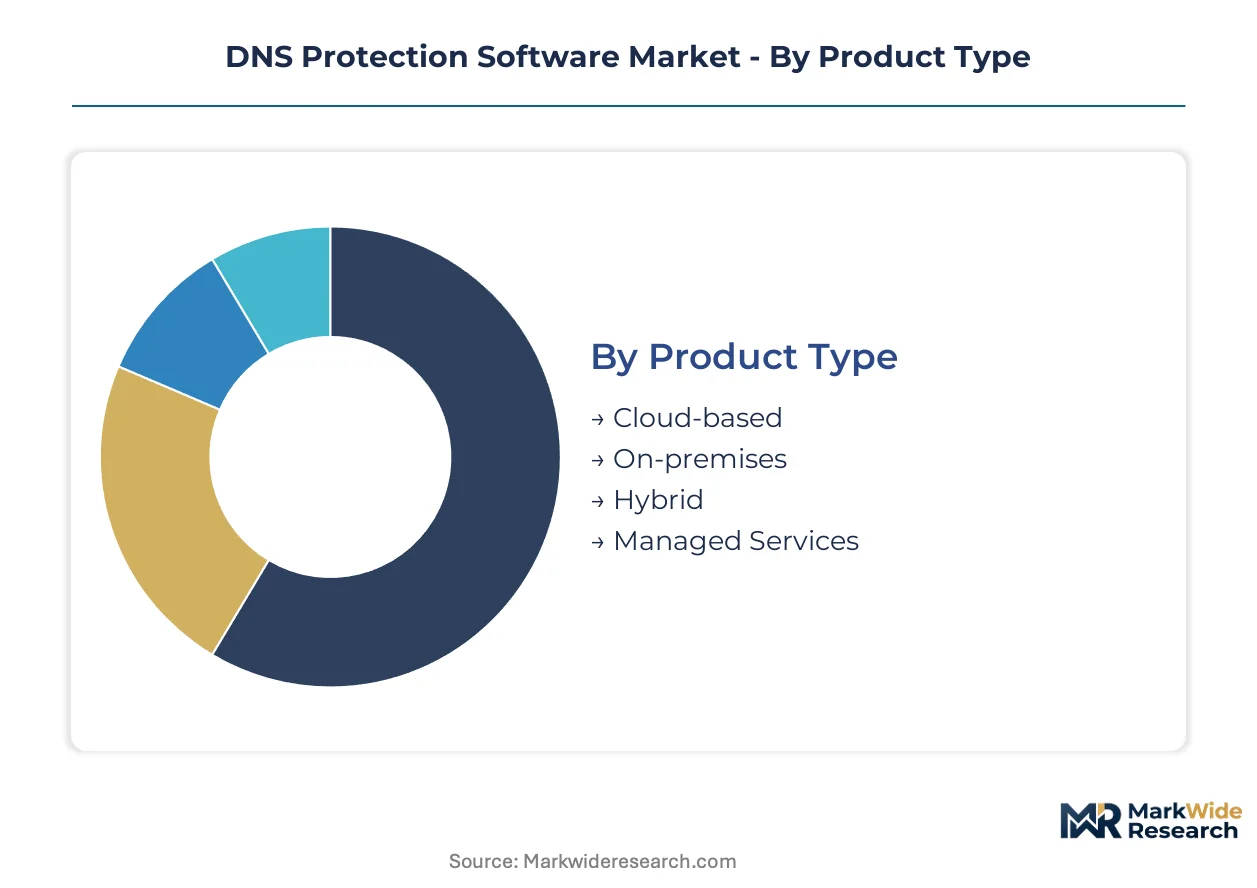
DNS protection software segments reflect divergent infrastructure requirements across cloud maturity levels and compliance postures. Procurement patterns vary sharply between enterprises prioritizing threat intelligence depth and mid-market buyers seeking operational simplicity.
Product Type:
Margin pools concentrate in recurring service models that minimize customer acquisition costs while embedding sticky monitoring capabilities.
- Cloud-based:Multi-tenant architectures deliver elastic resolution capacity without capital expenditure. Financial services firms in the United States favor this model for rapid ransomware defense deployment alongside existing cloud workloads.
- Managed Services:Providers assume full resolver operations including threat feed curation and incident response. European energy utilities under NIS2 compliance pressure are accelerating procurement of fully outsourced DNS security operations.
- On-premises:Physical appliance deployments serving data sovereignty mandates in regulated jurisdictions.
- Hybrid:Split architectures combining cloud resolution with local caching for latency-sensitive applications.
The dominant share belongs to Cloud-based deployments, while Managed Services is closing the gap fastest.
End User:
Enterprise procurement concentrates security budget toward predictive threat capabilities while government buyers emphasize certification-gated vendor selection.
- Enterprises:Large organizations operate recursive resolver farms exceeding millions of queries per second. Manufacturing conglomerates in Germany and France prioritize ISO 27001-certified providers to satisfy supply chain security requirements.
- Government:Public sector entities mandate sovereign infrastructure with domestic data residency. Federal agencies in the United States align procurement with FCC communications reliability standards and FedRAMP authorization requirements.
- SMBs:Resource-constrained organizations relying on bundled security suites with basic DNS filtering.
- Educational Institutions:Universities managing decentralized network architectures with limited security staffing.
Enterprise accounts command the largest revenue concentration, though Government verticals are expanding most quickly under mandatory cybersecurity directives.
Deployment Model:
Architecture choices reflect tradeoffs between operational control and infrastructure burden across cloud-native and legacy environments.
- Multi-Cloud:Organizations distribute DNS resolution across AWS, Azure, and Google Cloud to eliminate single-provider dependency. Technology firms undergoing cloud-native transformation favor this model for workload portability and redundancy.
- Private Cloud:Dedicated resolver instances within virtualized data center environments. Healthcare networks in the United States deploy this architecture to maintain HIPAA-compliant query logging without third-party exposure.
- Public Cloud:Shared infrastructure with provider-managed resolver services.
- Single Tenant:Physically isolated resolution stacks for maximum data segregation.
Multi-Cloud configurations lead new adoption, while Private Cloud maintains steady share among compliance-intensive sectors.
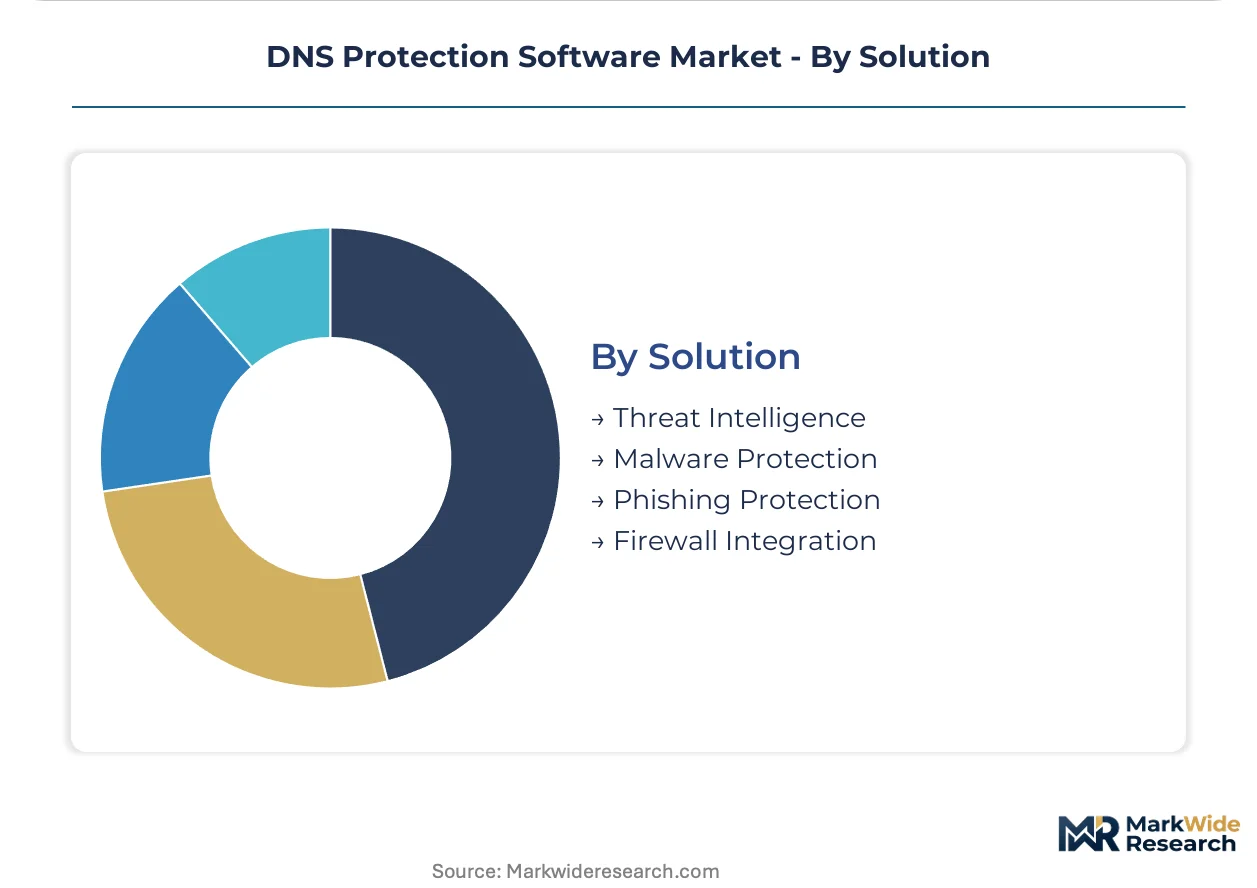
Solution:
Premium pricing attaches to intelligence-driven capabilities that preempt novel attack vectors rather than reactive signature matching.
- Threat Intelligence:Predictive blocking systems analyze query pattern anomalies to identify tunneling techniques before signature databases update. Financial institutions treat this capability as essential for command-and-control communication disruption.
- Firewall Integration:Native orchestration between DNS filtering and perimeter security policies. Palo Alto Networks and similar vendors compete through unified policy enforcement across resolution and traffic inspection layers.
- Malware Protection:Domain reputation scoring to block known malicious infrastructure.
- Phishing Protection:Real-time analysis of newly registered domains for credential theft indicators.
Threat Intelligence solutions capture premium positioning, while Firewall Integration is gaining share fastest through zero-trust architecture consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the deepest DNS protection infrastructure, with transatlantic fiber landing stations at Ashburn, Virginia, and Hillsboro, Oregon, anchoring global recursive resolver capacity. Financial services firms and cloud hyperscalers drive procurement concentration along these coastal corridors.
United States
Cloud migration and remote work architectures have expanded DNS attack surfaces for enterprises. The FCC enforces communications infrastructure reliability standards that implicate DNS availability for critical services. Silicon Valley and Northern Virginia data center clusters host the majority of recursive resolver farms serving North American query volumes exceeding millions of requests per second.
Germany
Industrial conglomerates and automotive manufacturers prioritize predictive threat intelligence for operational technology networks. The EU NIS2 Directive mandates DNS infrastructure hardening for essential and important entities across energy and transport sectors. Manufacturing clusters in Bavaria and Baden-Württemberg are accelerating ISO 27001-certified provider selection to satisfy supply chain security requirements.
United Kingdom
Financial services institutions in the City of London treat DNS-layer filtering as first-line defense against ransomware and data exfiltration. GDPR shapes how DNS query logs are retained and analyzed for security purposes across multinational banking operations. The Thames Valley technology corridor concentrates managed security service providers bundling DNS protection for mid-market professional services firms.
France
German and French enterprise buyers under the EU AI Act prioritize vendors with established AI governance frameworks for automated threat scoring. The directive imposes algorithmic transparency requirements on DNS filtering decisions involving EU citizen data. Paris-Saclay and Lyon technology clusters are emerging as procurement centers for compliant predictive blocking systems.
Japan
Manufacturing and electronics firms deploy hybrid DNS architectures combining cloud resolution with local caching for latency-sensitive applications. METI guidelines influence cybersecurity investment priorities for critical infrastructure operators. Tokyo-Osaka industrial corridors concentrate demand for edge-integrated DNS protection serving IoT gateway deployments in smart factory environments.
DNS Protection Software Market Competitive Landscape
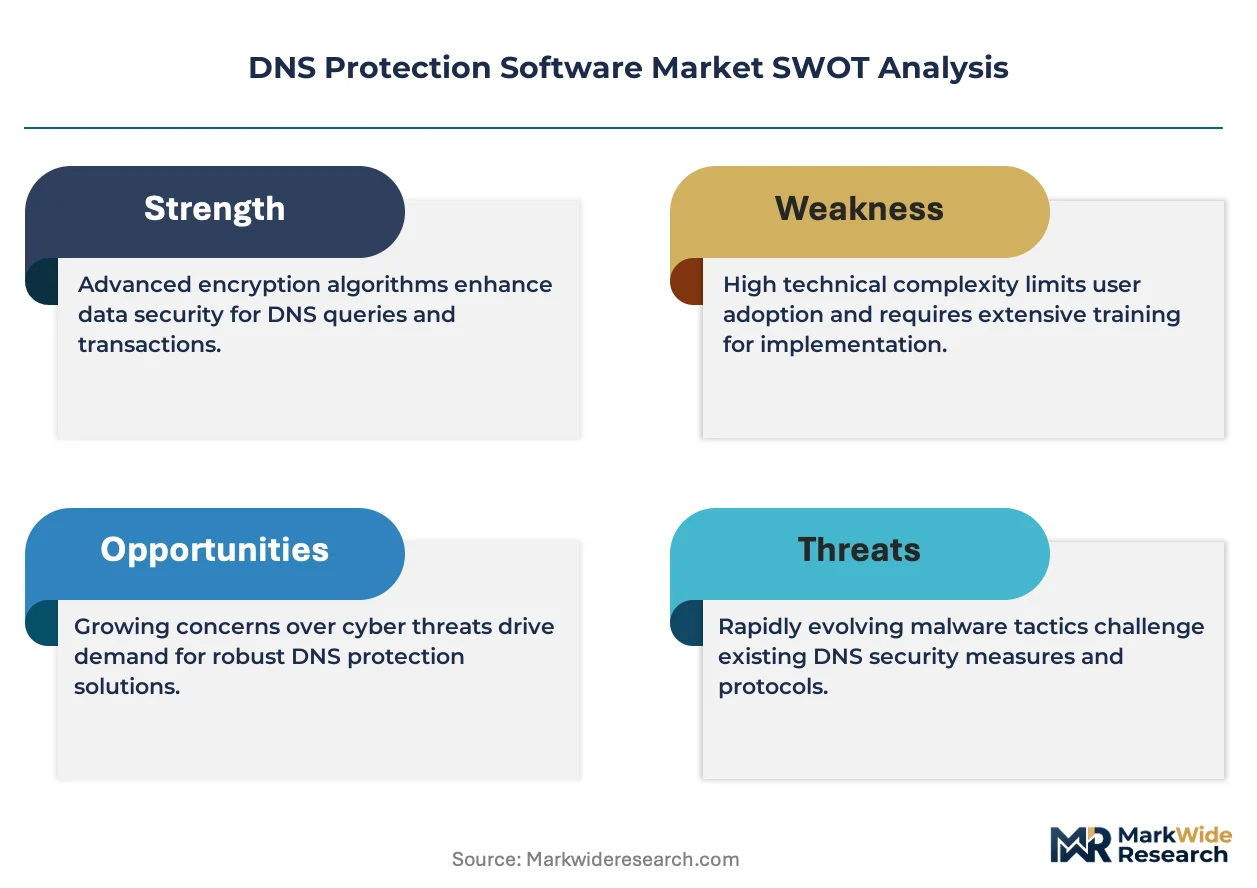
Concentration sits with networking incumbents and cloud security specialists that control recursive resolver infrastructure at scale. The vendor landscape segments into integrated platform providers, edge-native resolution specialists, and threat intelligence purveyors. Strategic moves center on embedding DNS security within zero-trust architecture consolidations and expanding managed service packaging for mid-market penetration.
Among the integrated networking tier, Cisco Systems Inc anchors positions through portfolio breadth, while Palo Alto Networks exemplifies firewall-DNS orchestration strategies. Akamai Technologies occupies the edge-native specialist archetype with resolution infrastructure distributed at internet exchange proximity. These three represent distinct competitive vectors: platform integration, perimeter convergence, and edge density.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Akamai Technologies |
| DNSFilter Inc. |
| TitanHQ |
| Infoblox |
| Comodo Security Solutions, Inc |
| Open Text Corporation |
| Palo Alto Networks |
| F5 Networks |
| Others |
Pricing and Supply Chain Analysis
Thirty-to-ninety-day provisioning cycles for recursive resolver capacity shape how vendors price DNS protection services and where they deploy infrastructure. This lead-time band concentrates pricing power with cloud operators holding excess resolution capacity, while compressing margins for hardware-dependent appliance vendors facing silicon inventory constraints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates DNS protection procurement. Premium tiers attach to ISO 27001-certified threat intelligence feeds and sub-millisecond latency guarantees for financial services. Standard tiers serve mid-market enterprises through per-query SaaS billing. Economy tiers bundle basic filtering within broader security suites. Price differentiation hinges on certification grade and query volume scale. Cost compression in the economy tier is intensifying because hyperscalers are absorbing basic DNS resolution into platform services at near-zero marginal cost. Managed service providers exhibit highest price sensitivity, while central banks and defense agencies show minimal elasticity.
Supply Chain Analysis
The United States and Ireland anchor global recursive resolver infrastructure, with Ashburn and Dublin data center clusters processing millions of queries per second for North American and European workloads. Singapore and Tokyo serve as Asia-Pacific resolution hubs. Raw material dependencies center on specialized ASICs for high-throughput packet inspection, threat intelligence data feeds from commercial and open-source providers, and submarine fiber capacity for inter-regional query routing. Single-source vulnerability concentrates in submarine cable landing stations at chokepoints like the Strait of Malacca. Distribution runs through direct enterprise sales for large accounts, managed security service providers for mid-market penetration, and cloud marketplaces for developer-centric adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DNS protection incumbents face substitution pressure from network security platforms integrating resolution functions as standard features. Platform consolidation threatens standalone DNS specialists with margin compression and customer churn.
For Market Incumbents: Consolidate threat intelligence assets through exclusive data partnerships with telecom operators and ISPs, creating proprietary query pattern databases that platform competitors cannot replicate. Deepen integration with zero-trust architecture deployments to embed DNS security within broader network access policies. Cisco Systems and Palo Alto Networks exemplify this defensive posture through firewall-DNS orchestration.
For New Entrants and Emerging Players: Mid-market MSP packaging gaps expose under-served regional healthcare networks and professional services firms lacking dedicated security architecture teams. European energy utilities under NIS2 compliance pressure represent the most penetrable vertical, requiring fully outsourced DNS security operations with domestic data residency. A channel-first go-to-market through established managed security service providers accelerates customer acquisition without direct enterprise sales investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from networking hardware vendors seeking to divest non-core security software divisions. Long-term viability in DNS protection rests on proprietary threat data moats rather than resolution infrastructure scale. Watch for inflection signals in EU AI Act enforcement creating procurement segmentation between compliant and non-compliant vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Threat Intelligence Data Partnership | Exclusive telecom operator agreements build proprietary query pattern databases for predictive blocking. |
| Zero-Trust Architecture Integration | Embedding DNS security within Cisco and Palo Alto Networks platforms reduces standalone displacement risk. |
| Managed Service Provider Packaging | Bundled offerings penetrate mid-market healthcare networks lacking dedicated security staffing. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation opens procurement channels with German and French enterprises. |
| Edge Computing Node Deployment | 5G and IoT gateway integration captures manufacturing and smart city infrastructure demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CISOs at financial services institutions, DNS infrastructure architects at cloud hyperscalers, procurement officers at European energy utilities, managed security service provider executives, and regulatory compliance leads. Secondary validation drew from FCC communications reliability standards filings, EU NIS2 Directive implementation guidance, ISO 27001 certification registries, hyperscaler capex disclosures, and threat intelligence industry reports. Bottom-up sizing of query volumes and resolution infrastructure investment combined with top-down triangulation against aggregate security software spending.
Across the analysis window, the forecasting framework modeled deployment architecture splits, end-user vertical concentration, solution capability tiering, and regional regulatory compliance clusters. CAGRs were derived from elasticity-adjusted adoption curves incorporating NIS2 enforcement timelines and cloud migration velocity by sector. Industry-specific inputs included recursive resolver query volume growth rates, threat intelligence feed subscription renewal patterns, and ISO 27001 certification penetration by vertical.
Material uncertainties — abrupt shifts in encryption protocol standards like DNS-over-HTTPS adoption rates, sovereign cloud mandates fragmenting multi-tenant architectures, and hyperscaler platform bundling — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and enterprise cloud migration continuity. Recalibration cycles align with material shifts in EU directive implementation, FCC rulemaking, and threat actor technique evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Single Sign-On Market
Security Software
Global Anti-Spam Software Market
Security Software
Global Digital Signature Software Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Global User Activity Monitoring Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Cybersecurity Software Market
Security Software
AD-Blocking Software Market
Security Software
Data Privacy Software Market
Security Software
Stalkerware Market
Security Software
Employee Fraud Detection Market
Security Software
Encryption Software Market
Security Software
Geofencing Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Security Testing Market
Security Software
Employee Surveillance and Monitoring Software Market