
 Smart Video Doorbell Market | 2026-2036
Smart Video Doorbell Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Video Doorbell Market Insights
Aftermarket service revenue from cloud storage subscriptions and extended warranty programs is fragmenting across hardware vendors and third-party platform operators. Ring Inc. leverages its parent-company logistics network to control fulfillment density in North American markets. Google Nest anchors its position through deep integration with the Android smart home stack, while Arlo Technologies Inc. differentiates via wireless battery-powered architectures that reduce installation friction for rental properties.
A smart video doorbell is an internet-connected entry monitoring device incorporating a wide-angle camera, passive infrared motion sensor, and bidirectional audio codec, typically operating on Wi-Fi or low-power wireless protocols to stream encrypted video to cloud servers and mobile applications. Wired units with smart home integration dominate installed value, while battery-powered wireless variants represent the fastest-growing product type as landlords and multi-family property managers prioritize retrofit flexibility over hardwired reliability. DIY installation captures volume leadership, though professional installation commands margin concentration in luxury residential and commercial security deployments where network hardening and insurance compliance apply.
FCC Part 15 emissions standards govern radio frequency certification for US market entry, while GDPR and the EU AI Act constrain biometric data processing and cloud retention policies for European deployments. China's MIIT enforces GB standards on wireless transmission power and data localization, forcing architecture divergence between regional product variants. Stakeholders must decide whether to absorb compliance-driven hardware cost inflation or push tiered subscription models that monetize regulatory complexity as a service differentiator.
Market Dynamics
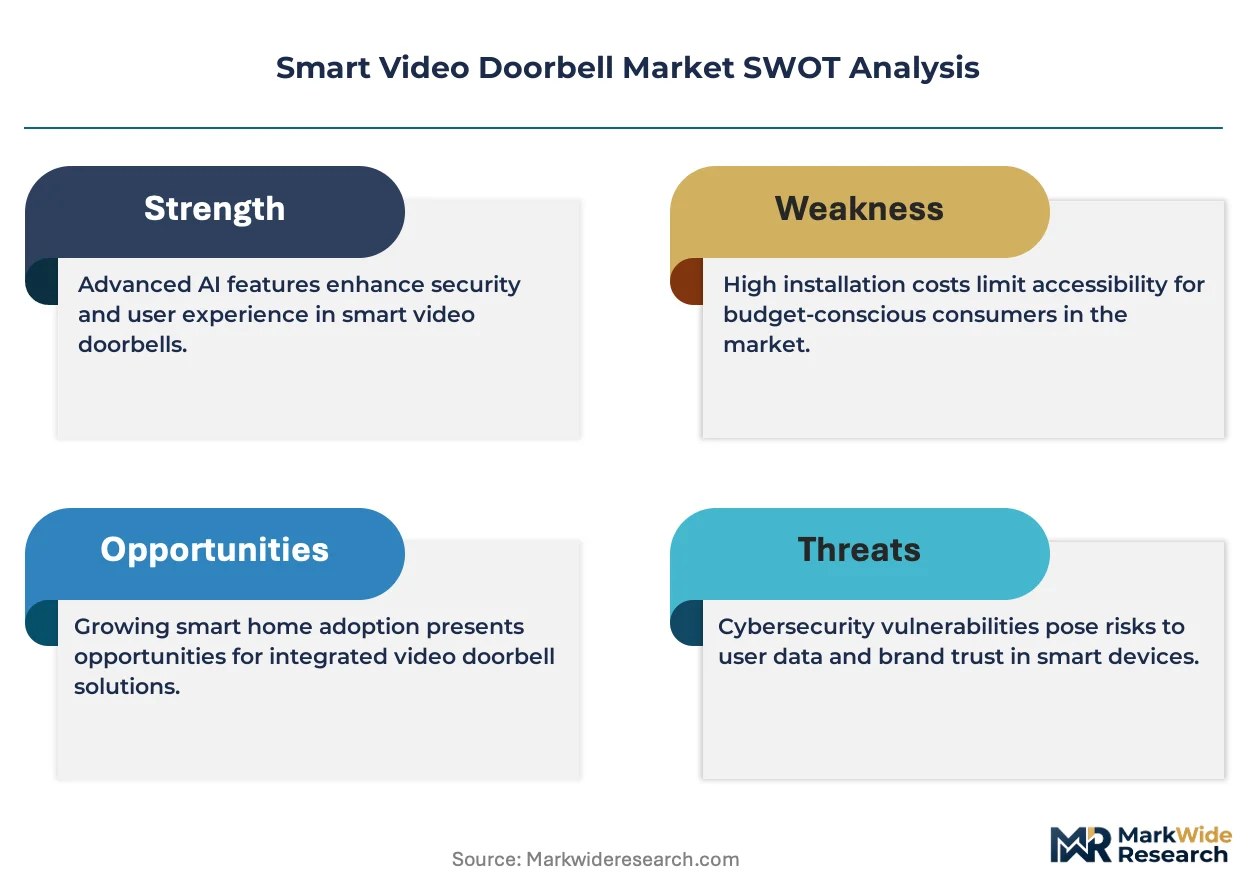
Subscription monetization is collapsing the traditional hardware-only revenue model as cloud storage and AI analytics bundles capture recurring value from suburban residential installations across North America.
Growth Catalysts
- GDPR biometric processing mandates:European cloud retention rules compel vendors to architect premium compliance tiers, creating service differentiation that landlords in multi-family housing willingly pay for.
- Wi-Fi 6 protocol penetration:Low-latency streaming enables battery-powered doorbells to match wired performance, accelerating landlord adoption in rental property retrofits.
- Suburban development concentration:New single-family construction in Texas, Florida, and Arizona generates concentrated demand corridors where professional installation networks achieve route density.
Market Restraints
- Lithium-ion cell cost volatility:Wireless doorbell margins compress when battery input costs spike, forcing vendors to absorb fluctuations or sacrifice volume in price-sensitive DIY channels.
- Cloud infrastructure supplier concentration:AWS and Azure dominance in video storage creates dependency risk when hyperscalers adjust egress pricing for surveillance workloads.
- FCC Part 15 certification timelines:Radio frequency approval delays of 8-14 months stall product launches and freeze engineering roadmaps ahead of holiday retail windows.
Strategic Opportunities
- India smart city integration:Municipal surveillance tenders in Bangalore and Hyderabad create B2G channels where doorbells feed into centralized public safety networks.
- Matter protocol convergence:Cross-platform interoperability between Apple HomeKit, Google Home, and Amazon Alexa collapses ecosystem lock-in, opening switching opportunities for challenger brands.
- Insurance premium incentives:US homeowners carriers in coastal states now discount premiums for verified video doorbell installations, creating a financed demand channel through agent distribution.
Industry Challenges
- Embedded computer vision talent scarcity:Edge AI engineers capable of optimizing person-detection models for sub-watt processors command compensation premiums that inflate R&D fixed costs.
- Legacy alarm panel integration friction:Professional installers face protocol translation complexity when retrofitting doorbells into existing DSC or Honeywell security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Video Doorbell Market |
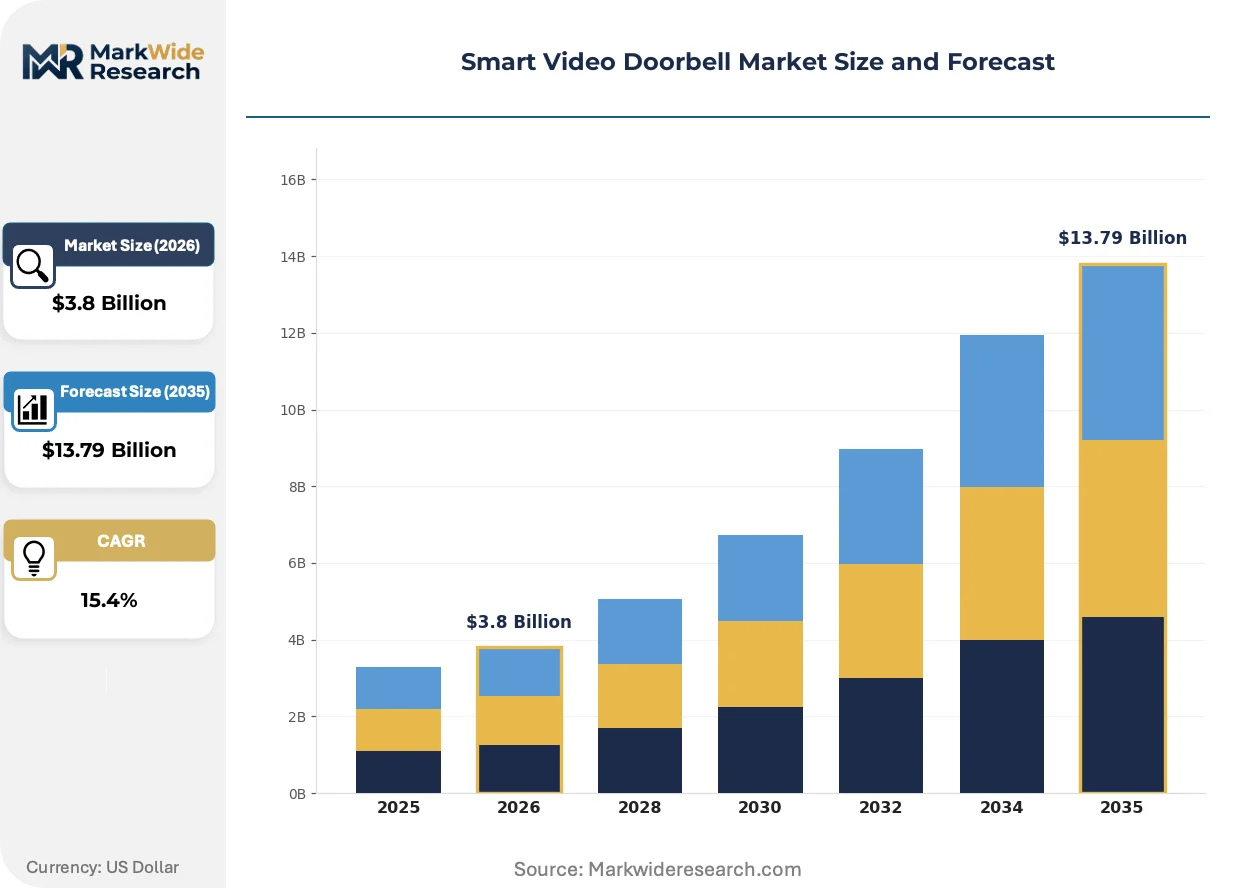
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $13.79 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Battery-Powered, Smart Home Integration Security Features: Motion Detection, Night Vision, Two-Way Audio, Cloud Storage Installation Type: DIY, Professional, Retrofit, New Construction End User: Residential Users, Property Managers, Commercial Businesses, Smart Home Enthusiasts |
| Companies Covered | Ring Inc., SkyBell Technologies Inc., Google Nest, Vivint Inc., Arlo Technologies Inc., August Home Inc., Aeotec Technology (Shenzhen) Co. Ltd., EZVIZ, ADT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Video Doorbell Market Trends and Innovations
Edge inference is redistributing computational load from cloud servers to doorbell-mounted processors, altering power budgets, subscription pricing models, and data sovereignty architectures simultaneously.
On-device neural processing units are collapsing the latency advantage of wired ethernet doorbells by enabling real-time person, package, and vehicle classification without round-trip cloud transmission. Battery-powered vendors in the rental property segment now pitch sub-200-millisecond alert speeds as competitive parity with hardwired units. This compression is forcing cloud-centric incumbents to redesign subscription tiers around value-added analytics rather than raw storage.
EU AI Act biometric surveillance restrictions are reclassifying facial recognition doorbells as high-risk AI systems, triggering conformity assessment obligations that add 6-9 months to European product launches. Hardware vendors must now document training data provenance and algorithmic accuracy metrics for notified body review. The compliance burden is advantaging larger platforms with dedicated regulatory affairs functions over mid-tier specialists.
Professional monitoring services are unbundling from hardware sales as third-party central stations offer standalone video verification subscriptions compatible with multiple doorbell brands. Home security dealers in California and Arizona increasingly lead with monitoring contracts and source hardware agnostically. This shift compresses brand loyalty and elevates installation service quality as the retention mechanism.
Smart Video Doorbell Market Segmentation
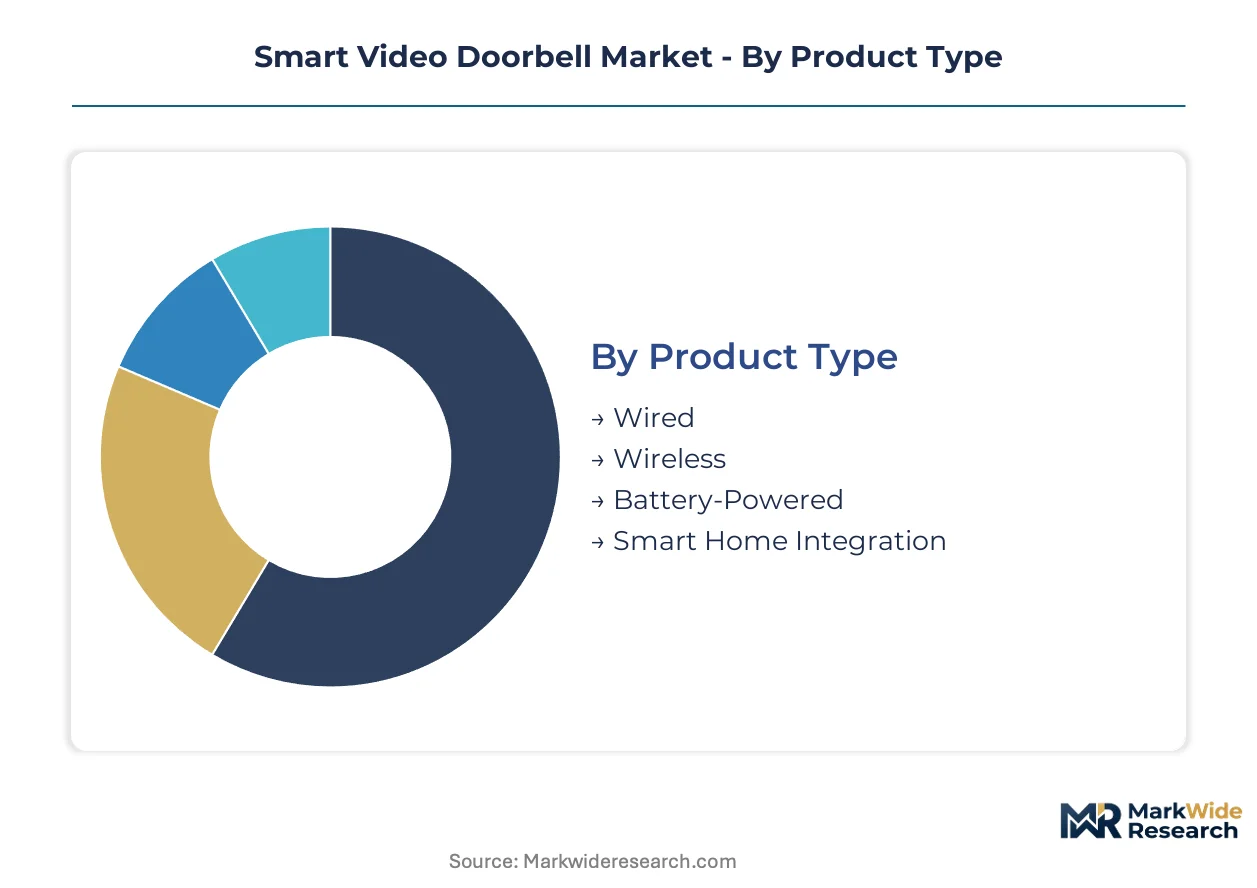
Smart video doorbell segmentation reveals divergent replacement cycles across hardware architectures, installation methods, and buyer sophistication levels. Understanding these velocity differences enables vendors to align inventory planning with demand timing and margin capture.
Product Type:
Wired units turn over slowest due to installation friction, while battery-powered variants refresh fastest as landlords prioritize flexibility over longevity.
- Wired:Ethernet or low-voltage transformer connections deliver uninterrupted power and sub-50-millisecond latency for real-time streaming. Demand concentrates in luxury suburban developments across Texas and Florida where new construction permits integrated pre-wiring. Professional installer networks achieve route density in these corridors.
- Wireless:Wi-Fi dependency eliminates cabling but introduces interference vulnerability in multi-dwelling environments. Property managers in Arizona rental markets favor these for tenant turnover scenarios where hardwiring is impractical.
- Battery-Powered:Lithium-ion cells enable 3-6 month untethered operation; fastest replacement cycle as battery degradation drives upgrade decisions. Landlords absorb recurring hardware costs to avoid electrical contractor dependencies.
- Smart Home Integration:Native compatibility with Alexa, Google Home, or Apple HomeKit protocols; slower turnover due to ecosystem lock-in effects and hub investment recovery timelines.
Wired units anchor the volume base while battery-powered variants gain share at the steepest rate.
Security Features:
Feature bundling stratifies across cost tiers, with premium analytics commanding subscription multiples over basic recording functions.
- Motion Detection:Passive infrared or radar-based sensing triggers recording initiation; standard across all price tiers with diminishing differentiation.
- Night Vision:Infrared LED arrays or starlight sensors enable sub-lux imaging; essential for insurance compliance in coastal California markets where carriers mandate 24-hour coverage verification.
- Two-Way Audio:Full-duplex codecs with echo cancellation permit real-time visitor interaction; property managers in multi-family housing deploy these for remote access management without on-site staffing.
- Cloud Storage:Encrypted offsite retention with tiered retention periods; GDPR-mandated EU data localization and China's MIIT requirements force regional architecture divergence, creating compliance-tier pricing premiums.
Cloud storage anchors the volume base while AI-enhanced analytics bundles gain share at the steepest rate.
Installation Type:
Installation method determines margin structure, with professional deployment capturing service revenue that DIY channels forfeit to price competition.
- DIY:Self-guided mounting via adhesive plates or existing doorbell transformer wiring; dominates Amazon and big-box retail volumes with compressed margins and high return rates.
- Professional:Certified installer deployment with network hardening and insurance documentation; concentrates in luxury residential and commercial security deployments where compliance liability applies.
- Retrofit:Replacement of legacy doorbell infrastructure without structural modification; fastest-growing category as rental property owners upgrade aging hardware without landlord electrical permits.
- New Construction:Pre-wiring during framing stage enables concealed cable runs and integrated smart home hub placement; slowest cycle tied to housing start volatility.
DIY installation anchors the volume base while professional deployment gains share at the steepest rate.
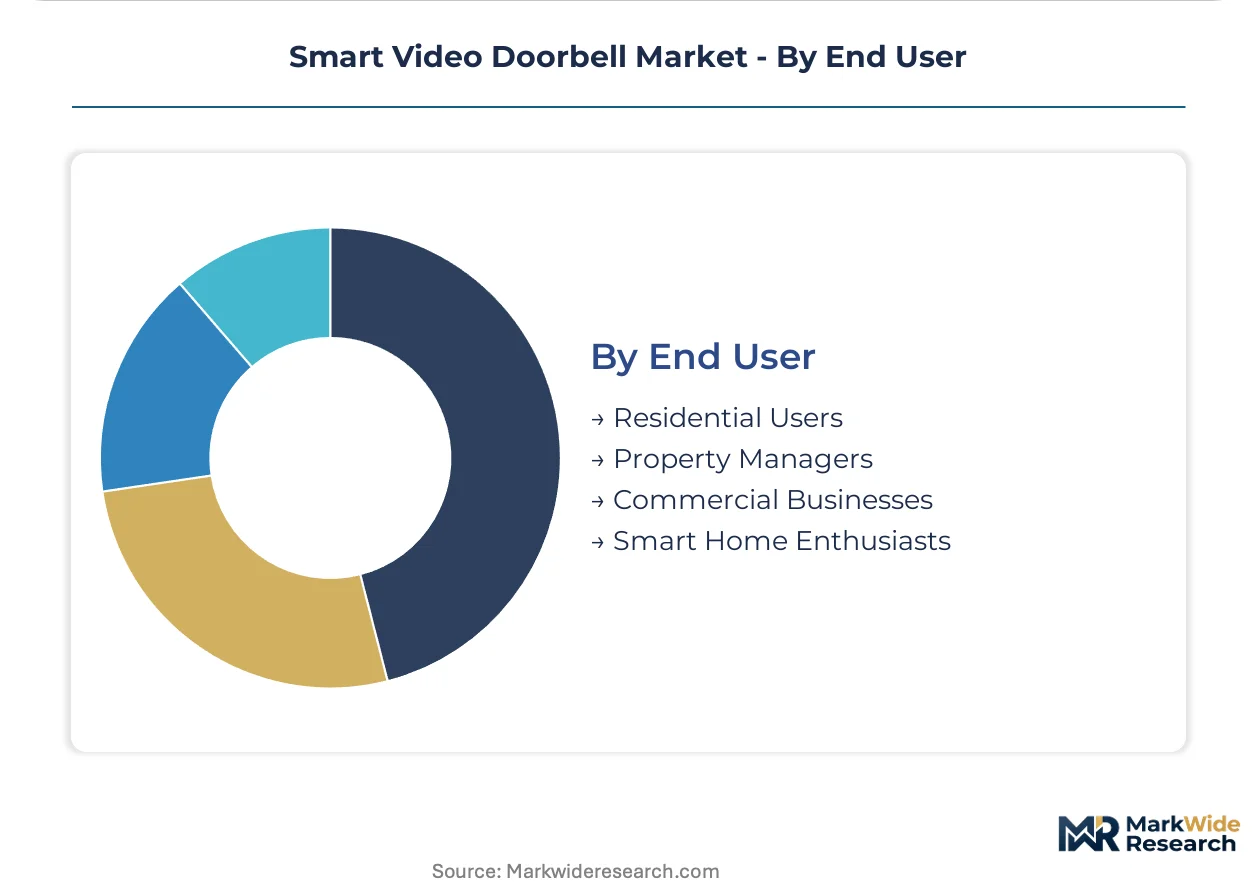
End User:
Buyer type dictates purchasing cadence, with commercial entities running formal replacement schedules and enthusiasts driving impulse upgrade cycles.
- Residential Users:Single-family homeowners prioritizing package theft prevention and visitor screening; suburban Texas and Florida markets show highest penetration density.
- Property Managers:Multi-family housing operators managing tenant access and liability reduction; institutional procurement processes slow adoption but secure volume commitments.
- Commercial Businesses:Retail storefronts and office buildings requiring centralized monitoring integration; GDPR and EU AI Act biometric restrictions constrain facial recognition deployments in European operations.
- Smart Home Enthusiasts:Early adopters cycling hardware to capture latest protocol support and edge AI capabilities; fastest replacement cadence with price insensitivity to premium tiers.
Residential users anchor the volume base while property managers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: suburban homeowners in the United States prioritize ecosystem integration, while European buyers respond to compliance-tier pricing, and Chinese landlords favor retrofit flexibility over hardwired reliability.
United States
Amazon Alexa and Google Home ecosystems drive replacement cycles in Texas and Florida suburban corridors. FCC Part 15 emissions standards govern radio frequency certification, creating 8-14 month approval timelines that stall holiday retail launches. Professional installer networks achieve route density in Arizona rental markets where battery-powered retrofits dominate.
Germany
GDPR biometric processing mandates compel vendors to architect premium compliance tiers for multi-family housing operators. The EU AI Act reclassifies facial recognition doorbells as high-risk AI systems, triggering 6-9 month conformity assessments. Industrial concentration in Bavaria supports dedicated regulatory affairs functions for notified body documentation.
China
MIIT enforces GB standards on wireless transmission power and data localization, forcing architecture divergence between regional product variants. Shenzhen-based manufacturers supply wireless battery-powered units to landlord-dominated rental markets in Beijing and Shanghai. Domestic vendors absorb compliance-driven hardware cost inflation through tiered subscription models.
United Kingdom
Insurance premium incentives from coastal homeowners carriers create financed demand channels through agent distribution. CE marking requirements align with broader EU regulatory frameworks post-Brexit transition periods. London and Southeast England concentrate smart home enthusiast adoption with fastest hardware replacement cadences.
India
Municipal surveillance tenders in Bangalore and Hyderabad create B2G channels where doorbells feed into centralized public safety networks. BIS certification requirements for wireless equipment delay market entry for foreign vendors. Karnataka and Telangana state governments pilot smart city integrations with multi-vendor compatibility requirements.
Smart Video Doorbell Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base stratifies between cloud-centric platforms with logistics integration and wireless hardware specialists with retrofit expertise. Three archetypes dominate: ecosystem-anchored platforms, battery-powered hardware innovators, and professional monitoring aggregators. Competitive moves concentrate on subscription tier redesign and third-party central station partnerships.
Among ecosystem-anchored platforms, Ring Inc. and Google Nest exemplify divergent scale strategies. Ring Inc. leverages parent-company fulfillment density in North American markets, while Google Nest anchors position through Android smart home stack integration. Arlo Technologies Inc. occupies the wireless battery-powered tier, representing retrofit flexibility priorities among rental property managers. These three entities illustrate how vendor positioning maps to distinct installation-method and end-user segments.
| Leading Market Players |
|---|
| Ring Inc. |
| SkyBell Technologies Inc. |
| Google Nest |
| Vivint Inc. |
| Arlo Technologies Inc. |
| August Home Inc. |
| Aeotec Technology (Shenzhen) Co. Ltd. |
| EZVIZ |
| ADT |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-based lithium-ion cell suppliers and CMOS sensor foundries in Taiwan anchor upstream concentration, directing margin pools toward subscription-tier vendors who bundle cloud storage with hardware rather than competing on unit economics alone.
Pricing Analysis
Long-term offtake contracts for image sensors and battery cells dominate procurement, while spot-market exposure for memory components creates quarterly cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant EU variants from baseline models and DIY economy units. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from hyperscaler egress fee adjustments for surveillance workloads, compressing margins in cloud-centric tiers. DIY residential buyers exhibit highest price sensitivity; commercial security integrators show lowest sensitivity due to insurance compliance requirements.
Supply Chain Analysis
Foxconn, Pegatron, and Jabil hold contract-manufacturing capacity for doorbell assembly, with additional concentration in Goertek for acoustic component integration. Manufacturing concentrates in China, Vietnam, and Mexico to balance tariff exposure against logistics cost. Raw material dependencies include lithium-ion cells from CATL and LG Chem, CMOS sensors from Sony and OmniVision, and NOR flash memory from Winbond. Single-source vulnerability in edge AI chip supply from Taiwan Semiconductor Manufacturing creates bottleneck risk. Distribution runs through Amazon Marketplace, big-box retail, and professional security dealer networks in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart video doorbell penetration remains below saturation in rental housing and commercial retrofit segments, with Wi-Fi 6 protocol penetration and insurance premium incentives sustaining early-cycle expansion momentum.
For Market Incumbents: Harden subscription retention through edge AI feature differentiation that reduces hyperscaler dependency, while consolidating professional installer networks in Texas and Florida suburban corridors to defend against third-party central station unbundling. Vertical integration into lithium-ion cell supply buffers margin compression from commodity volatility. For New Entrants and Emerging Players: Mid-market commercial buildings in India and Southeast Asia represent the most penetrable entry point, with municipal smart city tenders in Bangalore and Hyderabad offering B2G volume anchors. Battery-powered retrofit architectures for rental property managers provide product-market fit without competing against ecosystem-locked incumbents. Lead with Matter protocol compatibility to collapse switching costs. For Investors and Strategic Acquirers: Capital is best deployed toward wireless hardware specialists with retrofit expertise and dedicated regulatory affairs functions capable of navigating EU AI Act conformity assessments. Long-term viability favors vendors who monetize compliance complexity as service differentiation rather than absorbing hardware cost inflation. Monitor hyperscaler egress pricing adjustments as inflection signal for cloud-centric model sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | On-device inference reduces latency and hyperscaler dependency for battery-powered units. |
| GDPR Compliance Tier Architecture | Premium pricing capture in European multi-family housing offsets conformity assessment costs. |
| Professional Installer Network Consolidation | Route density in Arizona and Texas rental markets secures recurring monitoring contract flow. |
| Matter Protocol Certification | Cross-platform compatibility collapses ecosystem lock-in and opens challenger switching opportunities. |
| Insurance Carrier Partnership Development | Premium discount verification creates financed demand channel through agent distribution in coastal states. |
Research Methodology
A spread of perspectives from smart home platform engineers, professional security installers, property management procurement leads, and cloud infrastructure architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FCC certification databases, GDPR enforcement actions, hyperscaler capex disclosures, and municipal tender documents in India. Bottom-up unit economics modeling triangulated against top-down ecosystem penetration estimates.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning hardware architecture, installation method, end-user sophistication, and regional regulatory cluster. CAGRs derived from replacement cycle velocity differentials between wired and battery-powered variants, cross-referenced against housing start data and rental vacancy rates. Forecast inputs included Wi-Fi 6 chipset penetration curves and lithium-ion cell cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in residential construction activity, consumer electronics spending, or cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions on protocol adoption rates and regulatory enforcement intensity. Quarterly review of hyperscaler egress pricing, FCC certification backlogs, and EU AI Act notified body queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Global Enterprise Key Management Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Digital Credential Management Software Market
Security Software
Digital Risk Protection Platform Market
Security Software
Europe User Provisioning Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Device Vulnerability Management Market
Security Software
Bot Mitigation Market
Security Software
Web Content Filtering Market
Security Software
Europe Video Management System Market
Security Software
Mobile Antivirus Software Market
Security Software
Data Privacy Software Market
Security Software
Hardware Encryption Market
Security Software
Sound Masking Systems Market