
 Cloud Authentication Market | 2026-2036
Cloud Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Authentication Market Analysis
The capital-intensity divergence between hyperscale platform operators and boutique security vendors is bifurcating competitive dynamics across cloud authentication. Microsoft Corporation leverages its Azure Active Directory footprint to anchor enterprise-wide identity consolidation at scale. CyberArk Software specializes in privileged access management, competing through deep integration with DevSecOps pipelines rather than breadth of service.
Cloud authentication encompasses identity verification protocols, cryptographic credential frameworks, and policy enforcement engines delivered through distributed cloud infrastructure, typically operating at sub-200-millisecond latency for token validation and supporting protocols including OAuth 2.0, SAML, and FIDO2. Its primary commercial purpose is to replace perimeter-based security with continuous, context-aware identity assurance for distributed workforces. Multi-factor authentication and passwordless authentication represent the fastest-expanding solution categories as phishing-resistant standards gain procurement priority. Public cloud deployment dominates volume, though hybrid cloud configurations capture disproportionate margin pools from regulated verticals requiring data residency controls.
FDA cybersecurity guidance for connected medical devices, HIPAA identity safeguards for healthcare data access, and SEC disclosure rules for material cybersecurity incidents collectively elevate authentication to board-level governance priority across American enterprises. The EU AI Act and NIS2 Directive impose comparable obligations on European critical infrastructure operators, mandating multi-factor authentication for administrative access to essential services. Stakeholders must monitor convergence between zero-trust architecture mandates and emerging quantum-resistant cryptographic standards to anticipate credential infrastructure refresh cycles.
Market Dynamics
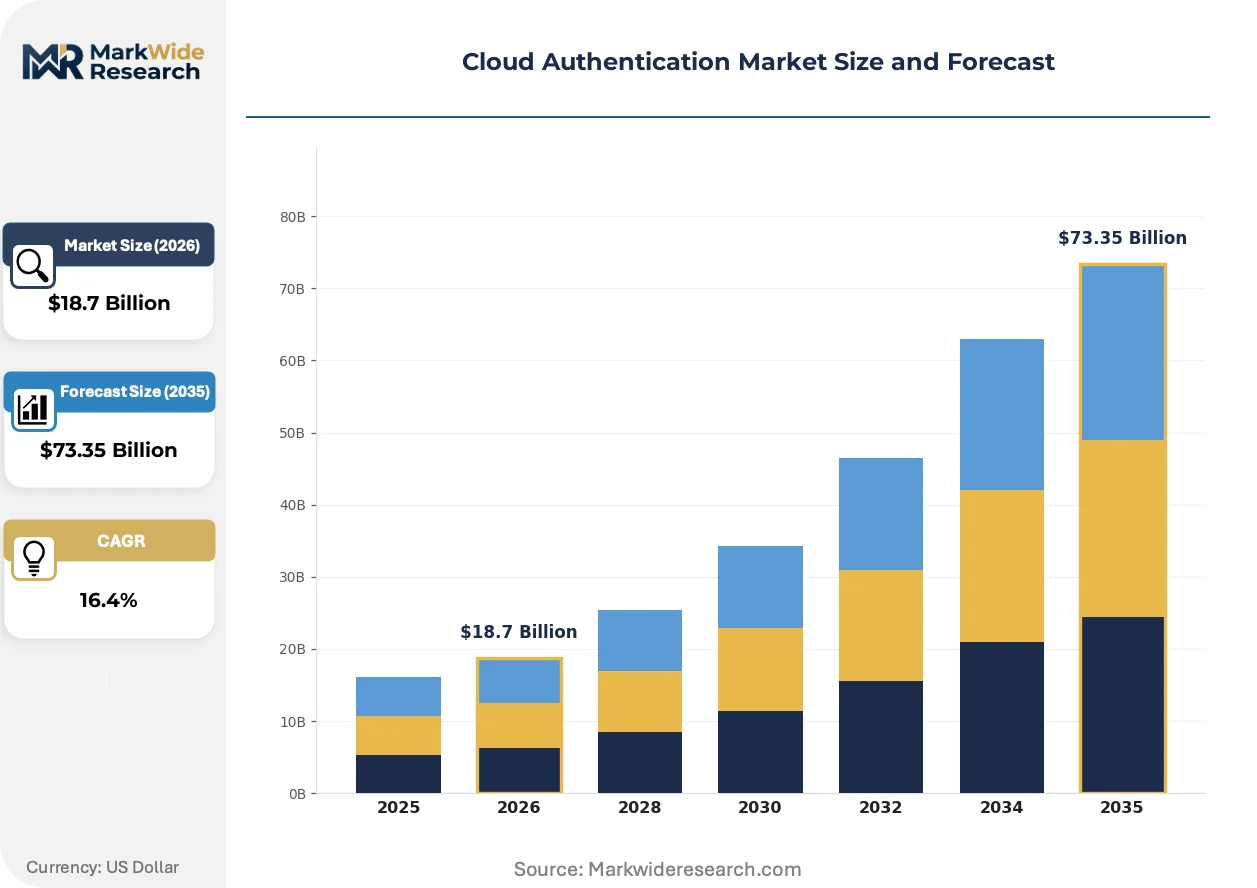
Zero-trust architecture mandates are compressing authentication refresh cycles across enterprise IT estates, forcing infrastructure teams to replace perimeter-based identity stacks with continuous verification systems that operate at cloud-native latency thresholds.
Growth Catalysts
- EU AI Act and NIS2 Directive:These frameworks mandate multi-factor authentication for administrative access to essential services, compelling critical infrastructure operators across Germany, France, and the United Kingdom to accelerate cloud identity migrations.
- Passwordless FIDO2 protocols:Phishing-resistant cryptographic credential frameworks are displacing SMS-based one-time passwords in financial services procurement specifications.
- Connected medical device expansion:FDA cybersecurity guidance for hospital networks requires identity verification for every device session, creating authentication demand in healthcare IoT deployments.
Market Restraints
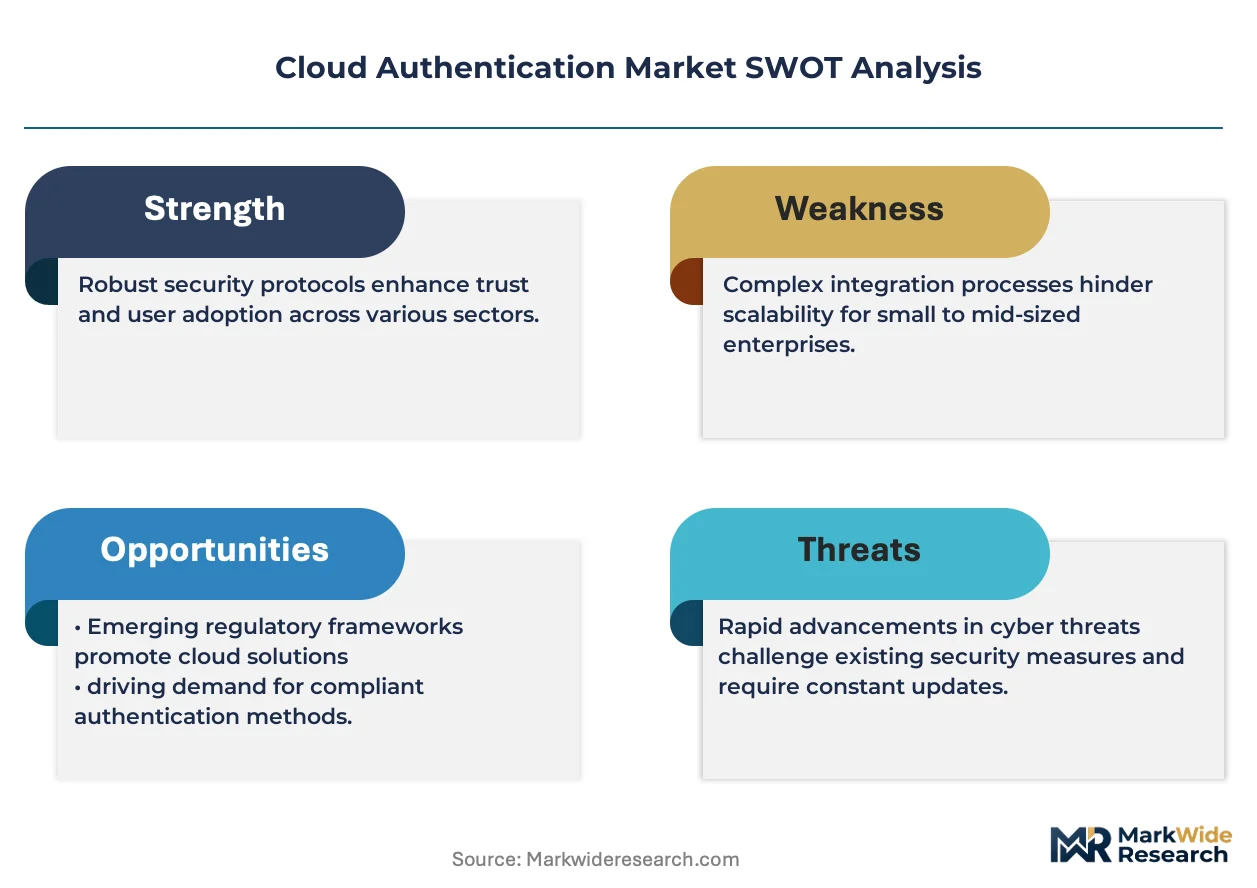
- Quantum vulnerability of existing PKI:Current RSA and elliptic curve cryptographic infrastructure faces obsolescence risk as quantum computing advances, threatening long-term credential system investments.
- Hybrid cloud complexity:Data residency requirements in regulated verticals fragment identity policy enforcement across on-premises and cloud-native stacks, elevating integration costs.
- Skilled identity architect scarcity:Enterprise demand for zero-trust implementation expertise outstrips supply of engineers proficient in OAuth 2.0, SAML, and FIDO2 protocol interoperability.
Strategic Opportunities
- DevSecOps pipeline integration:Privileged access management vendors can embed authentication into CI/CD workflows, capturing developer-centric security budgets previously allocated to separate tooling categories.
- Small and medium enterprise underpenetration:Mid-market firms in the United States remain reliant on basic Active Directory configurations, presenting conversion potential for cloud-native identity platforms.
- Continuous authentication convergence:Behavioral biometrics fused with device trust signals enables real-time risk scoring without explicit user prompts, opening premium pricing tiers.
Industry Challenges
- Legacy mainframe integration:Financial institutions running COBOL-based core banking systems face protocol translation complexity when connecting to modern OAuth 2.0 identity providers.
- Cross-border data sovereignty:Authentication token routing across jurisdictions triggers GDPR and national security law conflicts, requiring region-specific infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Authentication Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Identity as a Service, Multi-Factor Authentication, Single Sign-On, Passwordless Authentication Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Industry Vertical: Healthcare, BFSI, Retail, Telecommunications |
| Companies Covered | Microsoft Corporation, Okta, RSA Security, Ping Identity, Cisco Systems, IBM Corporation, Oracle Corporation, Thales Group, CyberArk Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Authentication Market Emerging Trajectories
Authentication infrastructure is fragmenting across specialized execution environments, with cryptographic operations migrating from centralized identity providers toward edge nodes and device-secure enclaves.
Passkey credential systems built on FIDO2 standards are supplanting password-based authentication in consumer and enterprise contexts alike. Major technology platforms have embedded passkey support into operating system keychains, accelerating end-user familiarity. This shift is compressing market share for traditional password manager vendors and redirecting security budgets toward biometric sensor integration.
The EU AI Act imposes strict identity verification requirements for high-risk AI system operators, including automated biometric identification in public spaces. Critical infrastructure entities must now maintain auditable authentication logs with cryptographic integrity guarantees. German energy utilities and French telecommunications operators are deploying hardware security modules to satisfy these evidentiary standards.
Enterprise buyers are unbundling identity verification from broader security service contracts, preferring specialized authentication vendors over integrated cybersecurity suites. This procurement pattern favors vendors with deep protocol expertise over generalist platforms. The phenomenon is most pronounced in United States healthcare networks responding to HIPAA audit pressures and SEC cybersecurity disclosure rules.
Cloud Authentication Market Segmentation
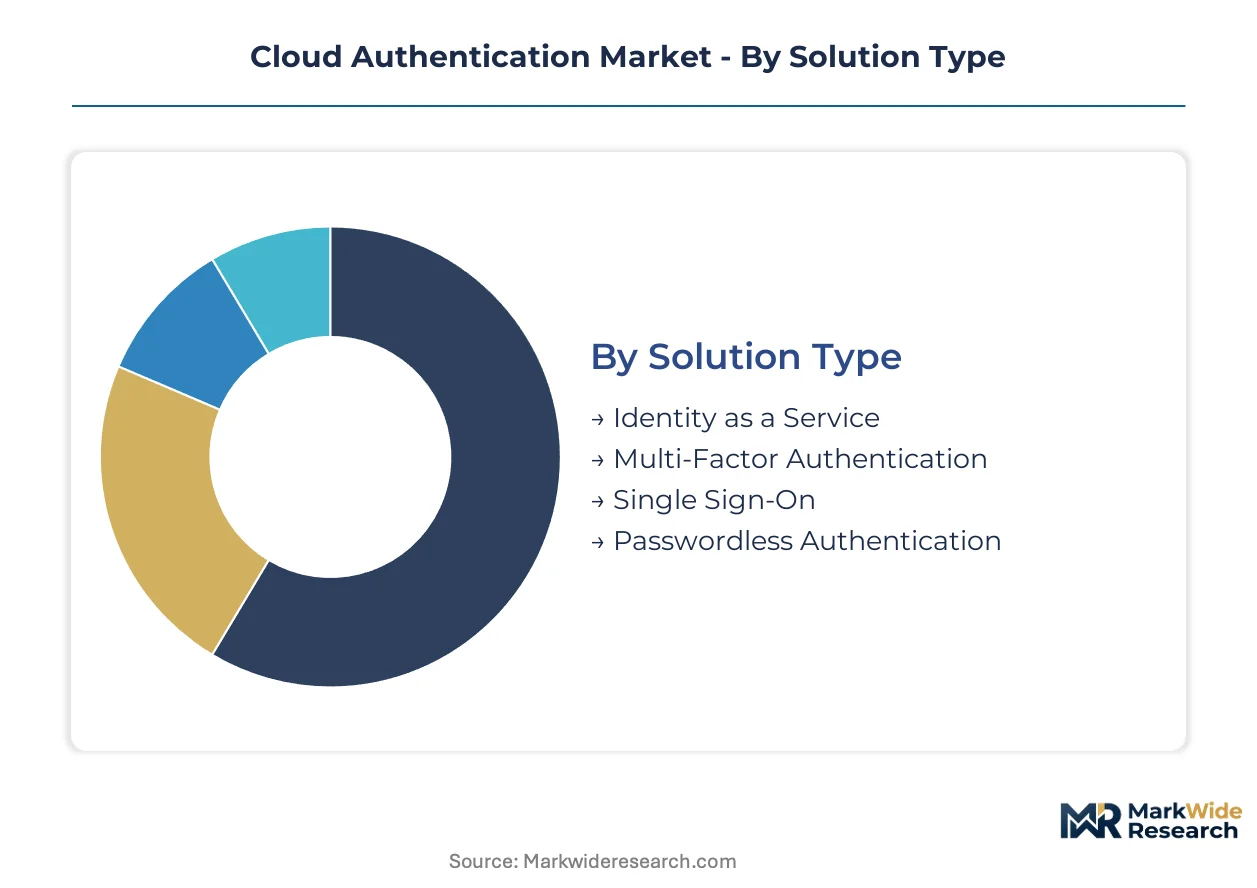
Cloud authentication procurement patterns diverge sharply across organizational scale and regulatory exposure. Solution selection reflects compliance burden intensity rather than uniform security posture, with financial services and healthcare operators driving premium feature adoption.
Solution Type:
FDA cybersecurity guidance and HIPAA identity safeguards create tiered procurement specifications across authentication modalities.
- Multi-Factor Authentication:Combines possession-based tokens with inherence or knowledge factors for stepped verification. German energy utilities and French telecommunications operators deploy hardware-backed MFA to satisfy EU AI Act audit requirements for essential services.
- Passwordless Authentication:Relies on FIDO2 cryptographic credentials bound to device secure enclaves, eliminating shared secrets entirely. Financial services institutions in the United Kingdom and the United States are displacing SMS-based one-time passwords with phishing-resistant passkey systems.
- Identity as a Service:Cloud-native identity orchestration delivered via subscription models with API-first architecture.
- Single Sign-On:Federated session management reducing credential re-prompting across enterprise application portfolios.
Established volume favors Multi-Factor Authentication; emerging adoption favors Passwordless Authentication.
Deployment Model:
Data residency mandates fragment infrastructure decisions across regulated verticals.
- Public Cloud:Shared-tenant identity infrastructure delivering sub-200-millisecond token validation at scale. Retail and telecommunications sectors in the United States prioritize public deployment for cost efficiency in non-regulated workloads.
- Hybrid Cloud:Policy enforcement split between on-premises directories and cloud-native identity providers. Healthcare networks responding to HIPAA audit pressures maintain patient identity data on-premises while extending authentication services to cloud-hosted clinical applications.
- Private Cloud:Dedicated tenant isolation for sovereign cloud requirements.
- Community Cloud:Shared infrastructure among organizations with common compliance obligations.
Public Cloud captures transactional volume; Hybrid Cloud commands premium pricing from regulated operators.
End User:
Security budget allocation scales non-linearly with organizational complexity.
- Large Enterprises:Distributed workforces requiring continuous verification across thousands of applications. BFSI institutions in Germany and the United Kingdom anchor demand for zero-trust architecture implementations with context-aware risk scoring.
- Small Enterprises:Basic Active Directory configurations predominate, presenting conversion potential for cloud-native platforms. Mid-market firms in the United States remain underpenetrated relative to enterprise adoption curves.
- Medium Enterprises:Transitioning from perimeter-based security to cloud identity stacks.
- Government Agencies:Sovereign authentication requirements with domestic infrastructure mandates.
Large Enterprises concentrate solution complexity; Small Enterprises offer expansion runway.
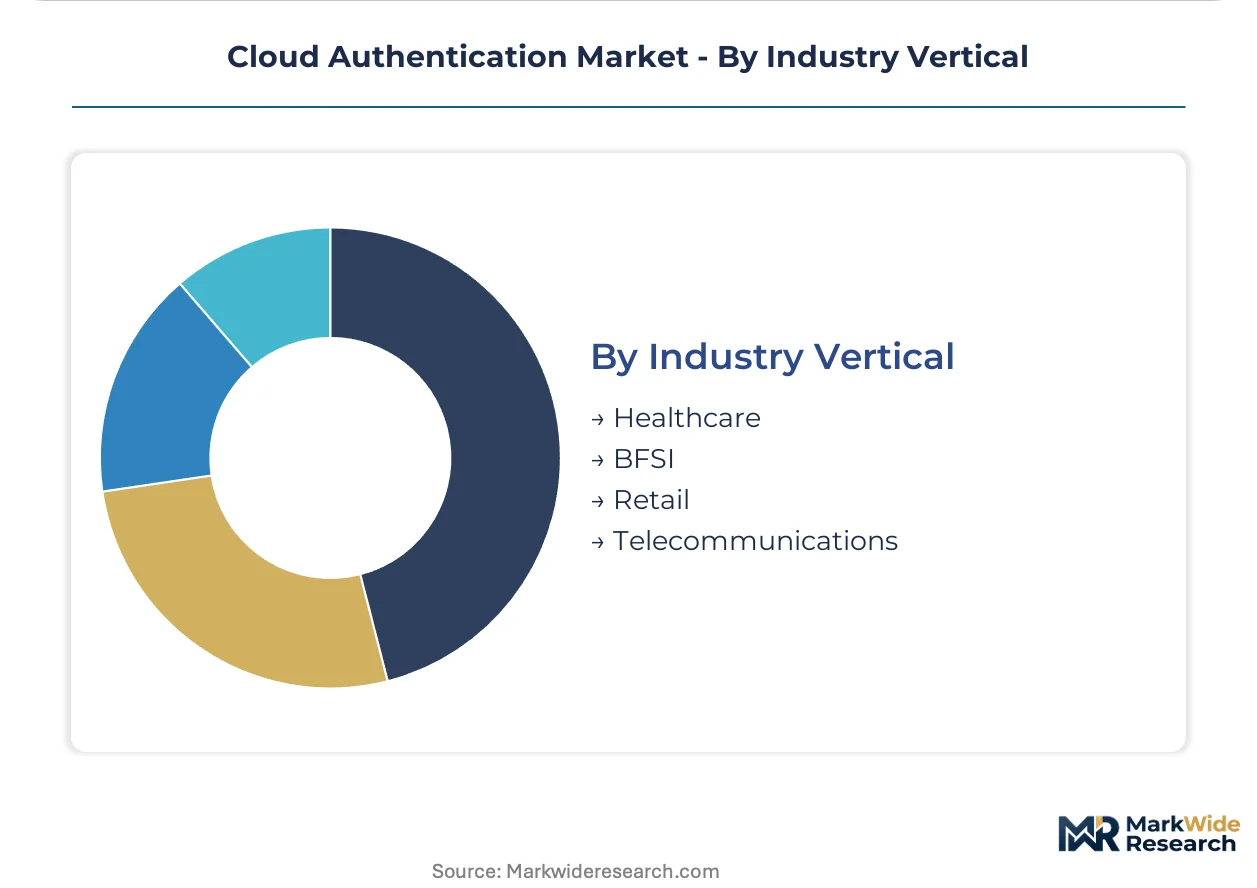
Industry Vertical:
Sector-specific breach disclosure rules elevate authentication to board-level governance priority.
- BFSI:Core banking system integration demands protocol translation between legacy COBOL infrastructure and modern OAuth 2.0 identity providers. Financial institutions across France and the United Kingdom lead passwordless FIDO2 procurement.
- Healthcare:Connected medical device expansion under FDA guidance requires identity verification for every device session. Hospital networks in the United States are unbundling identity verification from broader security service contracts.
- Telecommunications:Subscriber identity management at scale with fraud prevention overlays.
- Retail:Consumer-facing authentication with conversion-optimized friction balancing.
BFSI leads security spending intensity; Healthcare shows steepest expansion trajectory from regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for cloud authentication solutions varies sharply across geographies. United States buyers prioritize feature breadth and integration speed over unit cost. German and French procurement teams demand hardware-backed security modules regardless of premium pricing.
United States
Financial services institutions and hospital networks drive enterprise demand for FIDO2 passwordless systems. FDA cybersecurity guidance for connected medical devices mandates identity verification for every device session. Healthcare clusters in Boston and the San Francisco Bay Area anchor deployment of continuous authentication with behavioral biometrics.
Germany
Energy utilities and automotive manufacturers require sub-200-millisecond token validation for operational technology networks. The EU AI Act and NIS2 Directive impose multi-factor authentication mandates for administrative access to essential services. Industrial automation corridors in Bavaria and North Rhine-Westphalia deploy hardware security modules for cryptographic integrity guarantees.
United Kingdom
Banking and insurance operators lead FIDO2 passkey procurement across core banking modernization programs. The UK National Cyber Security Centre enforces phishing-resistant standards for critical infrastructure operators. London's financial district concentrates zero-trust architecture implementations with context-aware risk scoring.
France
Telecommunications operators and defense contractors anchor demand for sovereign cloud authentication with domestic infrastructure mandates. ANSM and CNIL oversight elevates biometric data handling requirements for authentication systems. Paris and Toulouse aerospace clusters deploy hardware-backed identity verification for classified program access.
Japan
Manufacturing conglomerates and financial institutions balance legacy mainframe integration with cloud-native identity stacks. METI guidance on critical infrastructure protection mandates multi-factor authentication for industrial control systems. Tokyo-Osaka manufacturing corridors concentrate hybrid cloud deployments bridging on-premises directories with cloud identity providers.
Cloud Authentication Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across cloud authentication. Hyperscale platform operators consolidate enterprise-wide identity stacks through breadth of service and API ecosystem density. Boutique security vendors compete through privileged access management depth and DevSecOps pipeline integration. Strategic moves concentrate on zero-trust architecture certifications and quantum-resistant cryptographic roadmap positioning.
Within the hyperscale tier, Microsoft Corporation anchors enterprise demand through Azure Active Directory footprint and operating system integration. CyberArk Software exemplifies the privileged access management specialist archetype, competing through deep protocol expertise rather than service breadth. Okta occupies a position in the cloud-native identity orchestration segment, serving mid-market and enterprise buyers seeking API-first architecture.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Okta |
| RSA Security |
| Ping Identity |
| Cisco Systems |
| IBM Corporation |
| Oracle Corporation |
| Thales Group |
| CyberArk Software |
| Others |
Supply Flow & Price Mechanics
Subscription-based capacity reservation contracts lock in multi-year access to hardware security module fleets and cloud identity orchestration platforms, anchoring price predictability for German energy utilities and United Kingdom banking operators while constraining vendor margin flexibility.
Pricing Analysis
Professional services and extended support tiers drive lifetime value in cloud authentication procurement. Three-tier pricing structure across premium, standard, and economy levels separates hardware-backed FIDO2 deployments from software-only MFA and basic SSO configurations. Price differentiation rests on certification grade — FIPS 140-2 Level 3 versus Level 1 — and geographic delivery cost for on-premises hardware modules. Cost compression in the standard tier is intensifying because hyperscale platform operators are bundling identity services with existing cloud compute commitments. Small enterprises in the United States exhibit highest price sensitivity, while French defense contractors and German automotive manufacturers accept premium positioning for sovereign cloud configurations.
Supply Chain Analysis
Semiconductor fabrication chokepoints in Taiwan and South Korea constrain hardware security module availability for European critical infrastructure operators. Supply concentration for cryptographic processors draws from Taiwan, South Korea, and the United States, with assembly and firmware provisioning distributed across Germany, France, and the United Kingdom. Raw material dependencies include silicon wafers, tamper-resistant packaging substrates, and quantum-resistant cryptographic accelerators. Single-source vulnerability in advanced node fabrication threatens long-term credential infrastructure refresh cycles. Distribution runs through direct enterprise sales teams for large deployments and hyperscaler marketplaces for mid-market self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and regulatory jurisdictions creates niche specialization opportunities as enterprises unbundle identity verification from integrated security suites.
For Market Incumbents: Shield market position through backward integration into hardware security module design and captive supply of FIPS-certified cryptographic processors. Consolidation moves should target DevSecOps-native authentication vendors before they capture developer-centric security budgets. The threat of quantum-resistant cryptographic migration demands immediate roadmap positioning to prevent stranded infrastructure investments. For New Entrants and Emerging Players: Anchor in the small enterprise segment across the United States, where Active Directory-to-cloud migration friction remains underexploited. White-space targets include continuous authentication with behavioral biometrics for healthcare networks and sovereign cloud identity stacks for French defense contractors. Go-to-market execution should emphasize API-first architecture and rapid SSO integration to bypass incumbent switching-cost advantages. For Investors and Strategic Acquirers: Privileged access management specialists with deep DevSecOps pipeline integration represent the most defensible acquisition archetype in this market. Long-term viability hinges on quantum-resistant cryptographic roadmap credibility and zero-trust architecture certification density. The signal to watch is NIST post-quantum cryptography standardization timing, which will trigger credential infrastructure replacement cycles across regulated verticals.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Passkey Platform Integration | Microsoft and Apple operating system keychain embedding accelerates enterprise passwordless migration timelines. |
| Hardware Security Module Scale-Up | German energy utilities deploy Thales and Utimaco HSM fleets to satisfy EU AI Act audit requirements. |
| DevSecOps Pipeline Partnership | GitLab and Jenkins plugin ecosystems channel authentication procurement toward specialized vendors. |
| Sovereign Cloud Geographic Expansion | French ANSM and CNIL mandates drive domestic infrastructure mandates for aerospace and defense clusters. |
| Quantum-Resistant Cryptographic R&D | NIST PQC algorithm selection determines next-generation credential framework investment priorities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with CISOs, identity architects, and cloud procurement officers at financial services and healthcare operators; and secondary validation against SEC cybersecurity disclosure filings, NIST authentication guidelines, and EU regulatory implementation texts. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across solution types and deployment models.
Across the analysis window, the forecasting framework modeled demand by organization size, industry vertical, deployment architecture, and regional regulatory cluster. CAGRs derived from segment-level adoption curves and replacement cycle assumptions. Quantum computing threat timelines and zero-trust mandate implementation schedules served as scenario inputs.
Material uncertainties — quantum-resistant standardization delays, sovereign cloud data localization enforcement, and skilled identity architect scarcity — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as NIST PQC algorithm finalization and EU AI Act penalty precedents evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
North America IoT Security Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Cloud Security Market
Cybersecurity
5G Security Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
DNS Security Market
Cybersecurity
V2X Cybersecurity Market
Cybersecurity
Europe Web Application Firewall Market
Cybersecurity
Spain Cybersecurity Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Ddos Protection and Mitigation Security Market
Cybersecurity
Germany Cybersecurity Market