
 Philippines Cybersecurity Market | 2026-2036
Philippines Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Cybersecurity Market Outlook
Managed security subscriptions is shifting how Filipino enterprises consume protection, replacing perpetual licenses with recurring operational expenditure. Fortinet Inc. anchors its position through integrated firewall-to-SD-WAN bundling for mid-market telco clients. Palo Alto Networks Inc. competes by specializing in cloud-native zero-trust architectures for Philippine financial institutions. ePLDT leverages its domestic fiber infrastructure to control delivery of sovereign-hosted SOC services.
Philippines cybersecurity encompasses hardware, software, and service layers designed to protect digital assets from unauthorized access, disruption, or exfiltration, with next-generation firewalls processing traffic at application-layer granularity using deep packet inspection engines. Its primary commercial purpose spans data confidentiality assurance, operational continuity enforcement, and regulatory compliance verification across interconnected enterprise environments. Endpoint security leads product-type deployment as remote work persistence expands device attack surfaces beyond traditional perimeter controls. Cloud-based deployment models capture fastest expansion as Philippine organizations migrate workloads to hyperscaler regions in Singapore and Hong Kong. Managed security services concentrate margin pools through multi-year MSSP contracts that embed incident response retainers.
The Department of Information and Communications Technology shapes demand through its National Cybersecurity Plan mandates requiring critical infrastructure operators to implement baseline controls and report incidents. The Bangko Sentral ng Pilipinas enforces Technology Risk Management guidelines that compel BFSI institutions to maintain independent security operations centers and undergo annual penetration testing. ISO 27001 certification increasingly gates enterprise procurement and government contract eligibility. Stakeholders must weigh build-versus-buy decisions for SOC capabilities as local talent scarcity intensifies competition for certified analysts.
Market Dynamics
Managed security subscriptions are compressing capital expenditure cycles across Philippine enterprises, converting upfront firewall and endpoint investments into recurring operational contracts that align spending with actual threat exposure.
Growth Catalysts
- BSP Technology Risk Management:The Bangko Sentral ng Pilipinas mandates independent security operations centers and annual penetration testing for banking institutions, forcing compliance-driven procurement of SOC services and vulnerability assessment tools.
- Cloud workload migration:Philippine enterprises relocating applications to hyperscaler regions in Singapore and Hong Kong require cloud-native security architectures, expanding demand for zero-trust network access and cloud workload protection platforms.
- Remote work persistence:Distributed workforces across Metro Manila, Cebu, and Davao expand endpoint attack surfaces beyond traditional perimeter controls, accelerating deployment of endpoint detection and response solutions.
Market Restraints
- Certified analyst scarcity:Local talent pools lack sufficient CISSP and GIAC-certified security operations personnel, inflating salary costs for SOC staffing and extending implementation timelines.
- Import-dependent hardware:Next-generation firewalls and specialized network security appliances rely on semiconductor supply chains concentrated in Taiwan and South Korea, exposing Philippine buyers to shipping delays and currency fluctuation risks.
- Legacy infrastructure drag:Family-owned conglomerates and provincial government agencies maintain decades-old operating systems and flat network architectures that resist zero-trust segmentation without complete replacement.
Strategic Opportunities
- Visayas and Mindanao expansion:Cybersecurity penetration outside Metro Manila remains shallow; Davao and Cebu's emerging BPO clusters present untapped demand for managed detection and response services.
- DICT National Cybersecurity Plan implementation:Critical infrastructure operator mandates create procurement windows for baseline control implementations and incident reporting platform deployments.
- Converged SASE architectures:Secure access service edge platforms combining SD-WAN with cloud-delivered security are displacing standalone firewall purchases among mid-market enterprises seeking simplified vendor management.
Industry Challenges
- SOC build-versus-buy calculus:Enterprises struggle to justify 24/7 security operations center investments when local analyst salaries exceed managed security service provider subscription costs by substantial margins.
- ISO 27001 certification bottlenecks:Limited accredited auditors in the Philippines extend certification timelines, delaying contract eligibility for government procurement and enterprise vendor qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Cybersecurity Market |
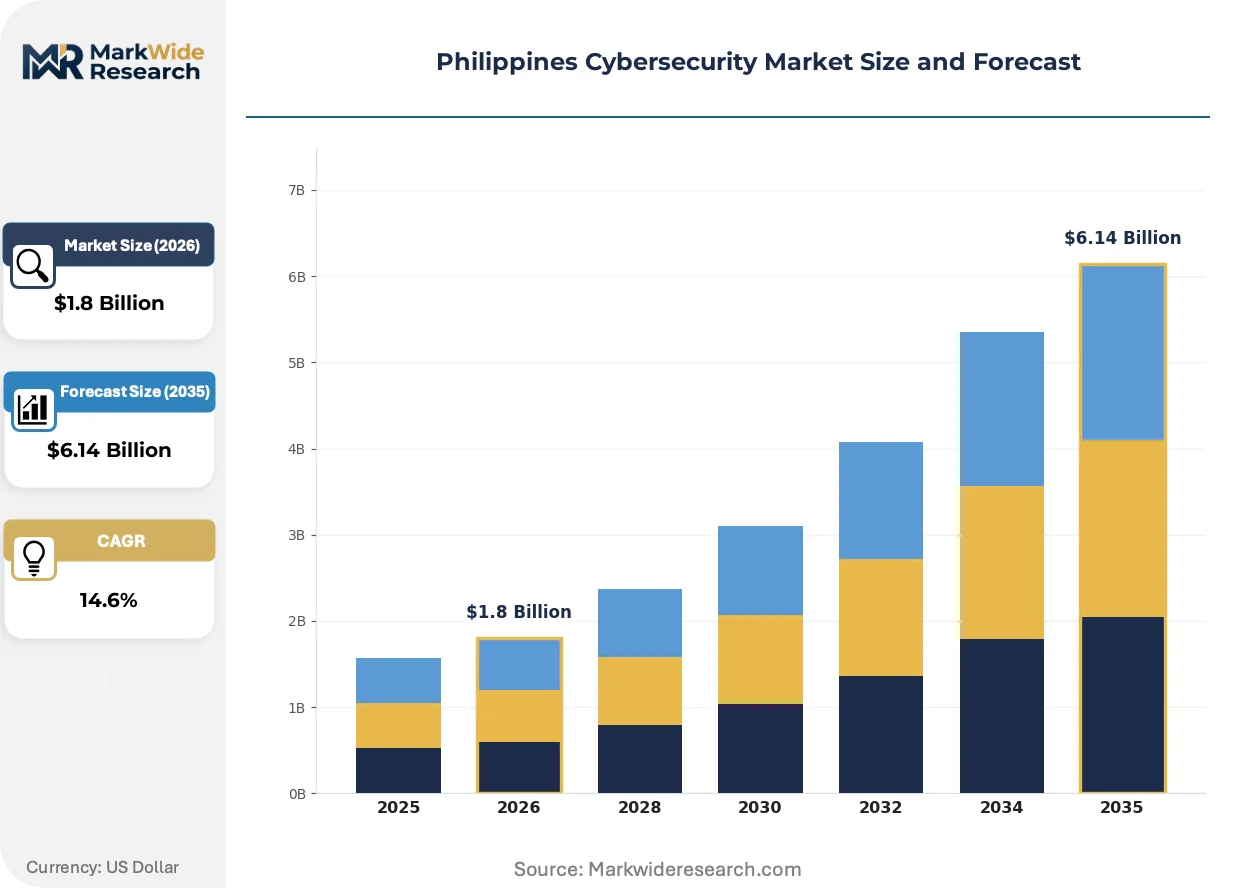
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Anti-Virus, Intrusion Detection System, Endpoint Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Government, BFSI, Healthcare, Retail Service Type: Consulting, Managed Security, Incident Response, Training |
| Companies Covered | Trend Micro Incorporated, Fortinet Inc., Cisco Systems Inc., Palo Alto Networks Inc., IBM Corporation, ePLDT, Check Point Software Technologies Ltd., Qualysec Technologies, Factosecure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Cybersecurity Market Strategic Shifts
Security consumption patterns across Philippine enterprises are fragmenting traditional product bundling, with buyers unbundling firewall, endpoint, and identity components to optimize for specific threat models and compliance requirements.
Extended detection and response platforms are modularizing security operations by aggregating telemetry across endpoints, networks, and cloud workloads into unified investigation workflows. Philippine financial institutions and large BPO operators are adopting these platforms to reduce mean-time-to-response without expanding headcount. This modularization compresses standalone SIEM and endpoint tool markets while elevating managed XDR services as the preferred consumption model.
The DICT National Cybersecurity Plan mandates baseline controls and incident reporting for critical infrastructure operators, creating procurement deadlines that accelerate security spending in energy, telecommunications, and banking sectors. Operators must implement specified technical controls and establish formal security operations capabilities by regulatory deadlines. Energy distribution utilities and water service providers in Luzon face the most compressed implementation timelines due to their classification as highest-priority critical infrastructure.
Subscription-based security consumption is displacing perpetual licensing across mid-market Philippine enterprises, with buyers preferring operational expenditure alignment to actual threat exposure and user counts. Channel partners are restructuring compensation models around recurring revenue rather than upfront product margins. This shift is most visible among Metro Manila-based professional services firms and healthcare providers seeking predictable budgeting for compliance-driven security investments.
Philippines Cybersecurity Market Segmentation
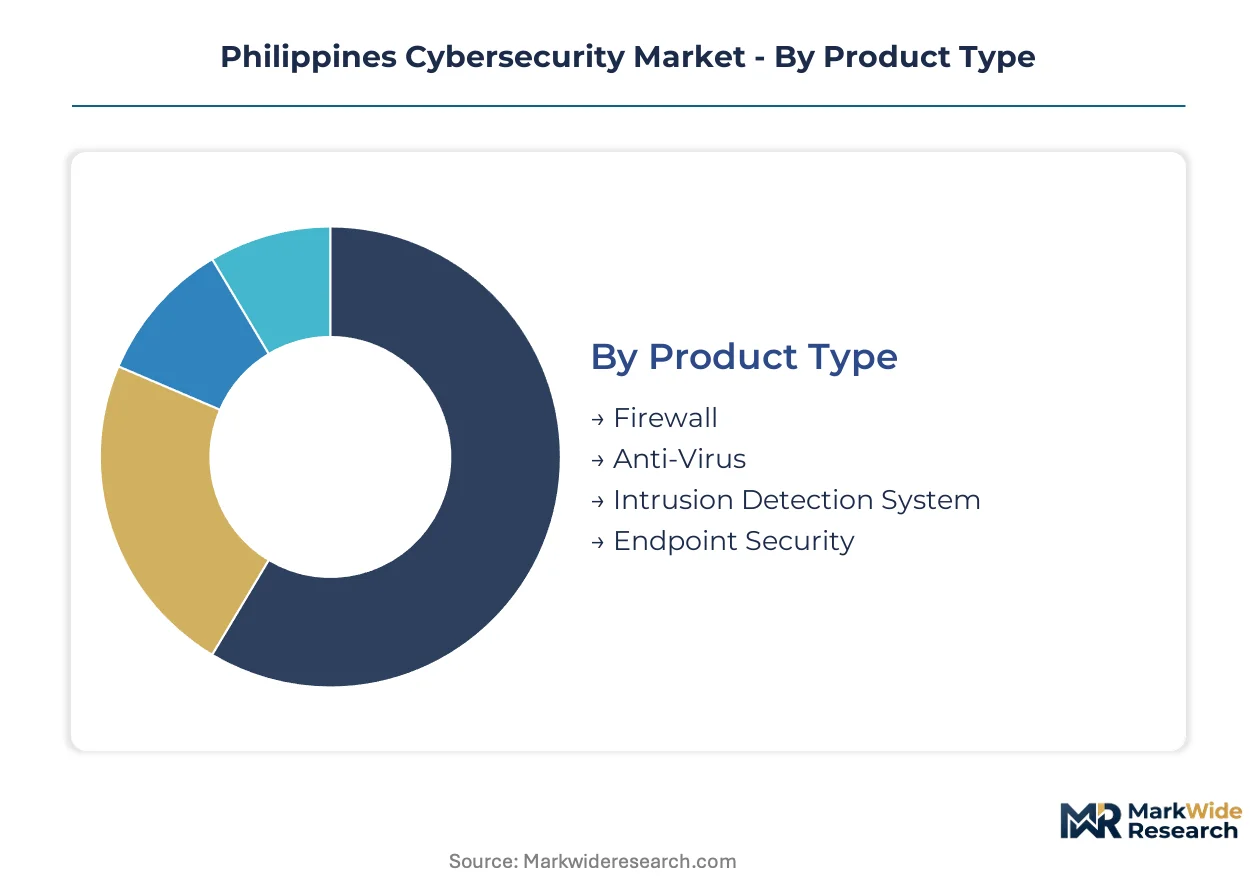
Philippine cybersecurity procurement fragments across four structural dimensions, with product type and deployment model determining capital allocation patterns while end-user verticals and service types shape recurring revenue streams. Understanding these segment boundaries clarifies where vendors capture upfront hardware margins versus long-term subscription value.
Product Type:
Capital intensity varies sharply across product categories, with hardware-dependent segments requiring substantial upfront investment in specialized appliances and licensing infrastructure.
- Firewall:Next-generation appliances with deep packet inspection and application-layer visibility command the highest per-unit capital outlays among Philippine enterprises. Demand concentrates in Metro Manila banking data centers and telecommunications facilities, driven by BSP mandates for perimeter segmentation and traffic inspection capabilities.
- Endpoint Security:Endpoint detection and response platforms aggregate telemetry from distributed workforces across Cebu and Davao BPO clusters. Remote work persistence expands device attack surfaces beyond traditional perimeter controls, accelerating subscription-based consumption models among mid-market professional services firms.
- Anti-Virus:Signature-based protection remains embedded in legacy procurement contracts at provincial government agencies and family-owned conglomerates with constrained security budgets.
- Intrusion Detection System:Network-based IDS deployments support compliance verification for critical infrastructure operators under DICT National Cybersecurity Plan timelines.
Firewall absorbs the bulk of installed capacity; Endpoint Security is expanding most quickly.
Deployment Model:
Operational expenditure alignment now governs deployment preferences, with buyers optimizing for talent scarcity and infrastructure maturity rather than ownership economics.
- Managed Service:Multi-year MSSP contracts embed 24/7 SOC capabilities without requiring CISSP-certified analyst recruitment, addressing the most acute talent constraint facing Philippine enterprises. ePLDT and other domestic providers leverage fiber infrastructure to deliver sovereign-hosted monitoring from Metro Manila facilities.
- Cloud-Based:Zero-trust network access and cloud workload protection platforms accompany enterprise migrations to hyperscaler regions in Singapore and Hong Kong. Financial institutions lead adoption, seeking elastic scaling without data center expansion.
- Hybrid:Split architectures accommodate regulated data residency requirements while offloading non-sensitive workloads to cloud environments, common among healthcare providers with patient data obligations.
- On-Premises:Appliance-heavy deployments persist at energy distribution utilities and water service providers facing compressed DICT implementation deadlines for air-gapped critical systems.
Managed Service captures the dominant share of new contract value; Cloud-Based deployment is climbing the fastest as workload migration accelerates.
End User:
Regulatory enforcement intensity creates tiered demand patterns, with mandated compliance deadlines forcing procurement acceleration in supervised sectors.
- BFSI:Bangko Sentral ng Pilipinas Technology Risk Management guidelines compel independent SOC maintenance, annual penetration testing, and incident response readiness. Philippine banks expand security budgets proportionally with digital transaction volume growth.
- Government:DICT National Cybersecurity Plan mandates baseline controls for critical infrastructure operators, with energy and telecommunications sectors facing the most compressed implementation timelines in Luzon.
- Healthcare:Patient data protection requirements and ISO 27001 certification gates drive endpoint protection investments among Metro Manila hospital networks.
- Retail:Payment card industry compliance and e-commerce expansion motivate cloud-native security architectures among Philippine consumer-facing chains.
BFSI channels the largest absolute security expenditure; Government vertical is gaining share fastest on regulatory deadline effects.
Service Type:
Margin concentration follows incident response capabilities, with retainer-based relationships embedding vendors deeper into client operational workflows than transactional engagements.
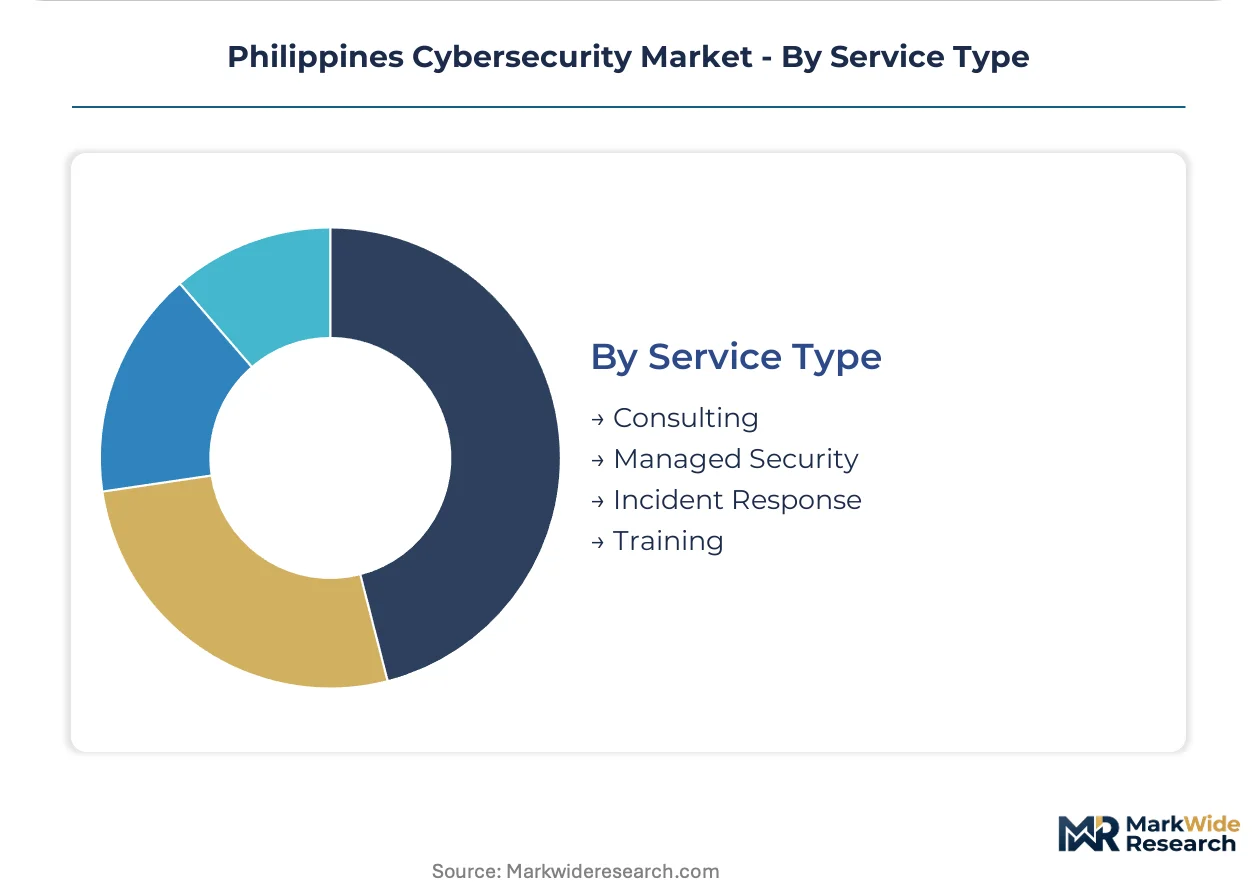
- Managed Security:Continuous monitoring and threat hunting services convert episodic consulting relationships into recurring revenue streams, with multi-year contracts now standard among Philippine enterprises seeking predictable compliance costs.
- Incident Response:Retainer-based readiness and breach containment capabilities command premium pricing, particularly among BFSI institutions requiring guaranteed response times under BSP supervisory expectations.
- Consulting:Risk assessments and architecture design engagements support initial compliance baselines but face margin pressure as buyers shift toward outcome-based managed arrangements.
- Training:Security awareness and certification preparation address analyst scarcity indirectly, though enterprises increasingly prefer embedded training within broader MSSP contracts.
Managed Security anchors the services revenue base; Incident Response is deepening its share fastest through retainer penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila concentrates Philippine cybersecurity procurement, with Makati and Ortigas business districts hosting the densest clusters of enterprise security operations centers and government compliance-driven deployments.
Metro Manila
BFSI institutions and telecommunications operators drive firewall and SOC investments across Makati, Taguig, and Quezon City. The Department of Information and Communications Technology enforces National Cybersecurity Plan baseline controls for critical infrastructure operators. Cybersecurity providers cluster in Bonifacio Global City and Ortigas Center, where ePLDT and international vendors maintain sovereign-hosted monitoring facilities.
Central Luzon
Clark Freeport Zone and Subic Bay attract data center investments requiring perimeter security and compliance architectures. The Philippine Economic Zone Authority offers fiscal incentives for technology infrastructure deployments. Manufacturing and logistics firms in Pampanga and Bulacan adopt endpoint protection as distributed workforces expand beyond traditional network boundaries.
Calabarzon
Laguna and Cavite industrial corridors house automotive and electronics manufacturers implementing ISO 27001 certification for supply chain eligibility. The Board of Investments prioritizes cybersecurity investments under the Strategic Investment Priority Plan. BPO operations in Santa Rosa and Biñan deploy zero-trust architectures to protect client data across hybrid work arrangements.
Visayas
Cebu City anchors emerging demand from offshore gaming operators and mid-market professional services firms. The DICT extends National Cybersecurity Plan implementation timelines for regional critical infrastructure operators. Mandaue and Lapu-Lapu City BPO clusters present untapped opportunities for managed detection and response services as remote work persistence expands.
Mindanao
Davao City's growing contact center and shared services sectors drive cloud-native security adoption. The Mindanao Development Authority supports digital infrastructure investments with streamlined permitting. Cagayan de Oro and General Santos City follow with compliance-driven procurement as regional enterprises face BSP Technology Risk Management guidelines.
Philippines Cybersecurity Market Competitive Environment
Capital-heavy integrated security platform vendors compete with asset-light specialized architects for Philippine enterprise contracts. Market structure tilts toward consolidated international platforms with established local channel partnerships, though domestic providers capture sovereign-hosted service revenue. Three archetypes dominate: integrated platform bundlers, cloud-native specialists, and domestic infrastructure-leveraged service operators. Competitive positioning hinges on SD-WAN convergence strategies and multi-year managed security subscription penetration.
Within the integrated platform tier, Fortinet Inc. and Palo Alto Networks Inc. exemplify contrasting architectural approaches for Philippine financial and telecommunications verticals. Cisco Systems Inc. occupies a position bridging hardware appliance dominance with cloud-delivered security transition. Domestic service provider ePLDT anchors the infrastructure-leveraged archetype, utilizing fiber network control to deliver sovereign-hosted SOC capabilities that address data residency requirements under DICT mandates.
| Leading Market Players |
|---|
| Trend Micro Incorporated |
| Fortinet Inc. |
| Cisco Systems Inc. |
| Palo Alto Networks Inc. |
| IBM Corporation |
| ePLDT |
| Check Point Software Technologies Ltd. |
| Qualysec Technologies |
| Factosecure |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification gates both qualified supply and premium-tier pricing access in the Philippines cybersecurity market, as uncertified vendors face exclusion from government procurement and BFSI vendor qualification while certified providers command retainer-based premiums for incident response capabilities.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and mean-time-to-response metrics dominates managed security services, with Bangko Sentral ng Pilipinas-mandated SOC capabilities driving subscription premiums for 24/7 monitoring. Price differentiation rests on certification density and sovereign hosting capabilities, with domestic fiber-leveraged providers capturing premium tiers over hardware-reselling channel partners. Pricing pressure intensifies in the mid-market firewall segment as converged SASE architectures displace standalone appliance purchases. Provincial government agencies exhibit highest price sensitivity due to constrained procurement budgets, while BFSI institutions show lowest sensitivity given regulatory non-compliance penalties.
Supply Chain Analysis
Freight costs and semiconductor logistics from Taiwan and South Korea inflate landed costs for next-generation firewalls and specialized network security appliances bound for Philippine data centers. Hardware supply concentrates in Taiwan, South Korea, and mainland China, with deep packet inspection chipsets and application-layer processing engines drawing from concentrated foundry capacity. Raw material dependencies span advanced semiconductors, specialized ASICs, and high-throughput memory modules. Single-source vulnerability around Taiwan Strait shipping lanes presents acute supply chain risk. Distribution runs through Manila-based systems integrators and telco-affiliated channel partners with direct enterprise relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines cybersecurity market represents a consolidation play as certified analyst scarcity forces smaller MSSPs into acquisition or exit, with talent costs exceeding operational leverage thresholds for sub-scale providers.
For Market Incumbents: Deploy multi-year managed security subscription bundling to lock in recurring revenue and raise switching costs for BFSI clients facing Bangko Sentral ng Pilipinas compliance deadlines. Fortify sovereign-hosted SOC positioning through fiber infrastructure control, addressing data residency requirements that international cloud-native competitors cannot match. Channel partner certification investments create defensive moats against emerging domestic competitors. For New Entrants and Emerging Players: Cloud-native zero-trust architectures targeting mid-market professional services firms in Cebu and Davao present the most penetrable white-space, as remote work persistence expands endpoint attack surfaces beyond incumbent perimeter-focused portfolios. Managed detection and response services for Visayas and Mindanao BPO clusters offer second entry vector. Direct sales partnerships with Philippine Economic Zone Authority-located data center operators accelerate initial traction. For Investors and Strategic Acquirers: DICT National Cybersecurity Plan implementation deadline announcements are the leading indicator that procurement acceleration will concentrate contract value among scaled providers. Long-term viability favors domestic infrastructure-leveraged MSSPs with captive fiber networks and existing BSP relationships over hardware-reselling channel partners. Acquisition targets should demonstrate certified analyst retention mechanisms and sovereign hosting certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Security Subscription Bundling | Multi-year contracts align Bangko Sentral ng Pilipinas compliance costs with predictable operational expenditure for BFSI institutions. |
| Sovereign-Hosted SOC Expansion | Domestic fiber infrastructure control addresses DICT data residency mandates while excluding international cloud competitors. |
| Zero-Trust Architecture Development | Cloud-native platforms capture Philippine enterprise migrations to Singapore and Hong Kong hyperscaler regions. |
| Visayas and Mindanao Geographic Expansion | Davao and Cebu BPO clusters present untapped demand for managed detection and response services. |
| ISO 27001 Certification Investment | Accreditation gates government procurement eligibility and enterprise vendor qualification processes. |
Study Parameters
Multi-period observation of DICT implementation timelines, BSP supervisory enforcement patterns, and hyperscaler region migration flows anchored the trend analysis, supplemented by interviews with CISOs at Philippine banks, DICT policy officers, MSSP operations directors, and data center infrastructure planners. Secondary validation drew from SEC filings of listed cybersecurity vendors, Bangko Sentral ng Pilipinas circulars, DICT National Cybersecurity Plan documentation, and hyperscaler capex disclosures for Singapore and Hong Kong regions. Bottom-up contract value aggregation across Metro Manila, Central Luzon, and Visayas-Mindanao clusters triangulated against top-down market sizing from hardware shipment data and services revenue disclosures.
Input-output matrices mapped product-type deployment volumes against end-user vertical spending patterns across the analysis window, with segmentation dimensions spanning deployment model, organization size tier, regulatory compliance intensity, and geographic infrastructure maturity. CAGRs derived from regression analysis of historical procurement cycles and forward-projected regulatory deadline effects. Industry-specific forecast inputs included Bangko Sentral ng Pilipinas Technology Risk Management enforcement trajectories and DICT critical infrastructure operator classification schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply chains, abrupt shifts in Philippine peso exchange rates affecting import-dependent hardware costs, and regulatory acceleration or delay beyond published DICT implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Egypt Cybersecurity Market
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Cloud Application Security Market
Cybersecurity
Romania Cybersecurity Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Spain Cybersecurity Market
Cybersecurity
Global Dynamic Data Masking Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Global Database Security Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Cyber Deception Market
Cybersecurity
Switzerland Cybersecurity Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
Norway Cybersecurity Market